
 5G Tester Market | 2026-2036
5G Tester Market Size, Share, and Industry Trends Forecast 2026-2036
5G Tester Market Analysis
South Korea's domestic 5G equipment manufacturing corridor is narrowing the supply gap for advanced test instrumentation. Keysight Technologies leverages its calibration laboratories in Seoul to sustain regional service density. Rohde & Schwarz anchors European R&D partnerships through its signal analysis development centers. Anritsu competes aggressively on millimeter-wave validation modules for base station rollouts.
A 5G tester is a precision electronic measurement instrument that validates radio frequency performance across sub-6 GHz and millimeter-wave bands, typically achieving phase noise specifications below -140 dBc per Hz at 1 GHz offset. Its primary purpose is certifying network equipment and user devices against 3GPP conformance standards before commercial deployment. Rack-mounted testers capture the dominant share of carrier capital expenditure as operators validate massive MIMO arrays in centralized labs. Software-based testers represent the fastest-expanding category, displacing hardware-only configurations through cloud-native architectures that reduce capital intensity for device manufacturers. Network simulation segments command premium positioning as Open RAN disaggregation multiplies interoperability testing protocols.
The FCC in the United States, ETSI through its 3GPP standards alignment in Europe, and MIIT in China collectively shape product roadmaps through spectrum certification timelines and electromagnetic compatibility mandates. Equipment vendors must synchronize firmware releases to these regulatory calendars or face market access delays. Stakeholders should monitor the divergence between national spectrum auction schedules and unified global test standards.
Market Dynamics
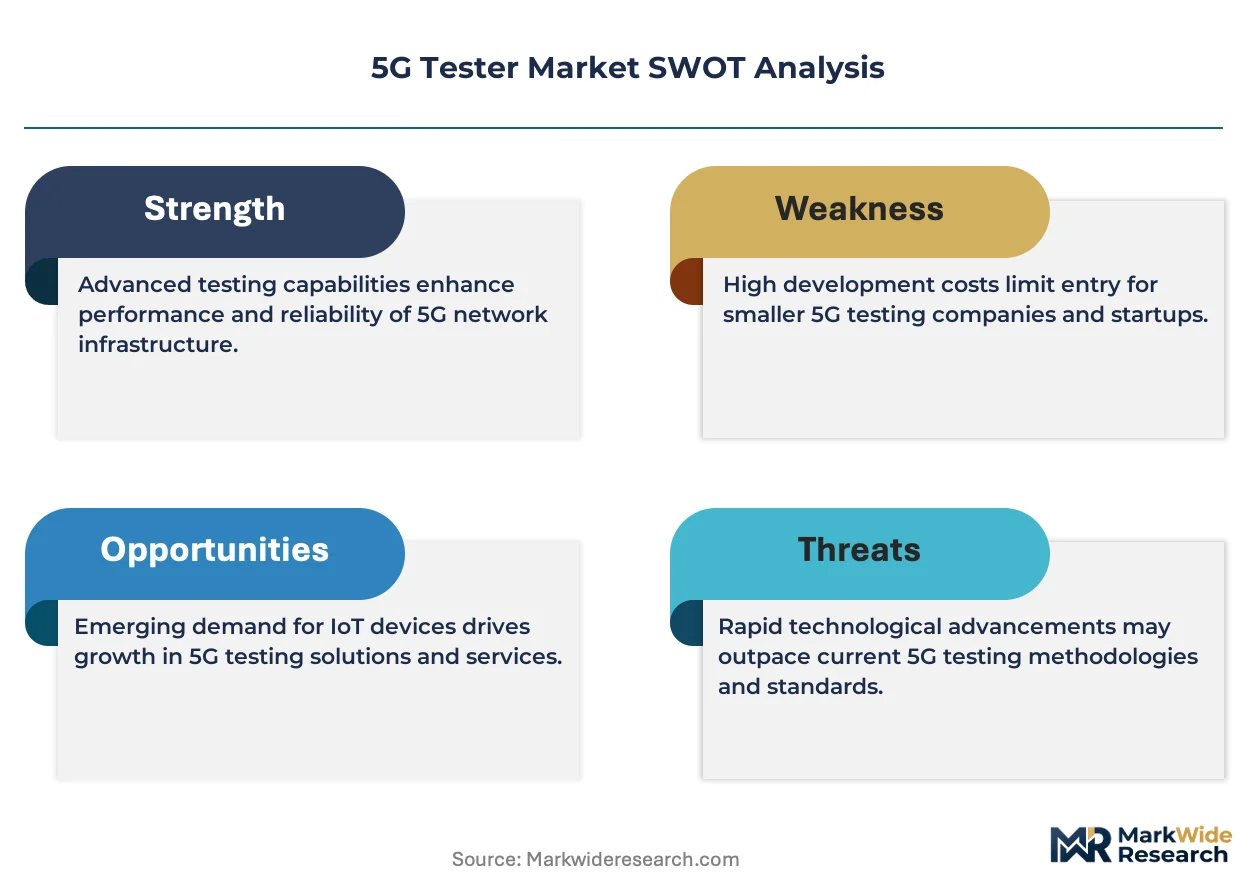
Open RAN disaggregation is fragmenting test requirements across multi-vendor radio units, creating demand for protocol-agnostic validation platforms that span sub-6 GHz through millimeter-wave bands.
Growth Catalysts
- 3GPP Release 18 conformance mandates:Advanced antenna system testing requirements in Europe force carriers to upgrade lab instrumentation ahead of 5G-Advanced commercialization.
- China's MIIT spectrum re-farming directives:Reallocation of mid-band frequencies for industrial IoT creates compliance verification bottlenecks at Shenzhen manufacturing clusters.
- Millimeter-wave base station densification:South Korean operators deploy massive MIMO arrays in Seoul's urban corridors, requiring parallel channel emulation capabilities.
Market Restraints
- Gallium nitride component shortages:RF frontend supply concentration in Taiwanese foundries creates 12-16 week lead times for high-frequency test modules.
- ETSI electromagnetic compatibility certification friction:Divergent national implementations of RED 2014/53/EU create duplicate testing burdens for equipment vendors.
- Software-defined radio substitution:Low-cost SDR platforms from academic and defense sectors erode entry-level hardware tester demand in emerging markets.
Strategic Opportunities
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives at Chennai and Pune clusters create localized test service demand from contract manufacturers.
- Private 5G network deployments:German automotive plants in Bavaria require on-site validation capabilities bypassing traditional carrier lab models.
- AI-native test automation convergence:Machine learning-driven fault prediction integrated with cloud-native architectures compresses device certification cycles.
Industry Challenges
- Millimeter-wave calibration expertise scarcity:Phase noise measurement proficiency concentrates among senior RF engineers in Seoul and Munich metropolitan areas.
- Multi-vendor interoperability integration:Open RAN fronthaul splits between O-RAN Alliance and 3GPP specifications create protocol stack validation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Tester Market |
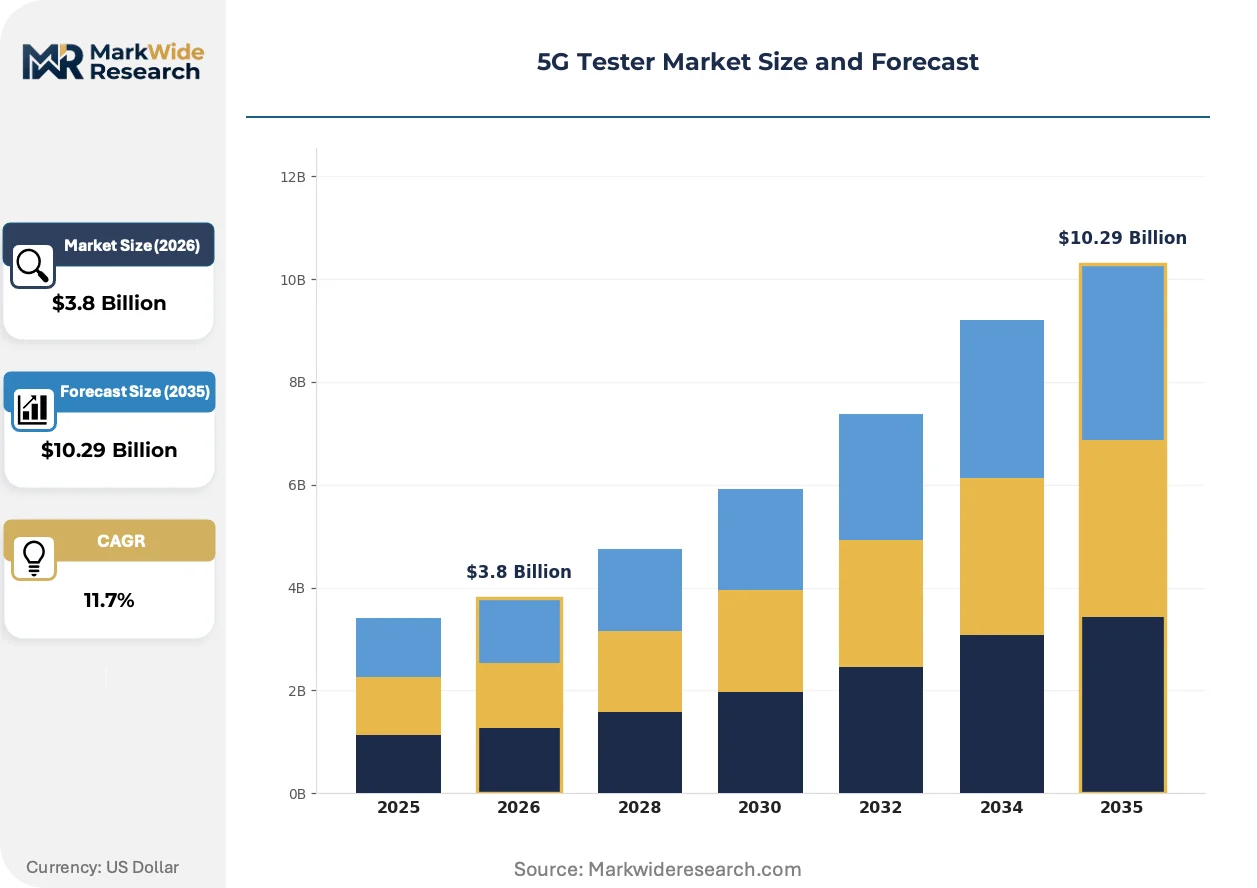
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Testers, Rack-Mounted Testers, Laboratory Testers, Software-Based Testers Technology: Wireless Testing, Network Simulation, IoT Testing, Signal Analysis Application: Network Planning, Performance Testing, Field Testing, Device Certification End User: Telecommunications, Device Manufacturers, Research Institutions, Government Agencies |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu, Teradyne Inc., VIAVI Solutions, Spirent Communications, National Instruments Corporation, EXFO Inc., Tektronix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Tester Market Emerging Trajectories
Test instrumentation architectures are pivoting from hardware-centric platforms toward virtualized measurement stacks, compressing capital deployment timelines for device manufacturers and carrier labs alike.
Cloud-native test orchestration software is migrating from supplementary automation layers to primary measurement engines. Tier-one device manufacturers in Shenzhen and San Diego now deploy containerized signal analysis workflows on hyperscaler infrastructure. This migration from rack-mounted hardware to elastic compute pools reduces per-device certification costs while enabling parallel test campaign scaling during product launch windows.
The FCC's updated equipment authorization procedures under KDB 447498 D01 are compressing unintentional radiator test timelines for 5G NR modules. Manufacturers must now submit integrated SAR and RF exposure documentation earlier in development cycles. Module suppliers serving the US market are restructuring pre-certification workflows to front-load electromagnetic compatibility validation before final firmware freeze.
Carrier procurement departments are unbundling test equipment purchases from multi-year service contracts. Verizon and AT&T now acquire instrumentation through capital leases with independent calibration providers, separating hardware ownership from metrology traceability. This model shift is most pronounced in the United States, where third-party lab accreditation through A2LA and NVLAP creates competitive pressure on OEM service pricing.
5G Tester Market Segmentation
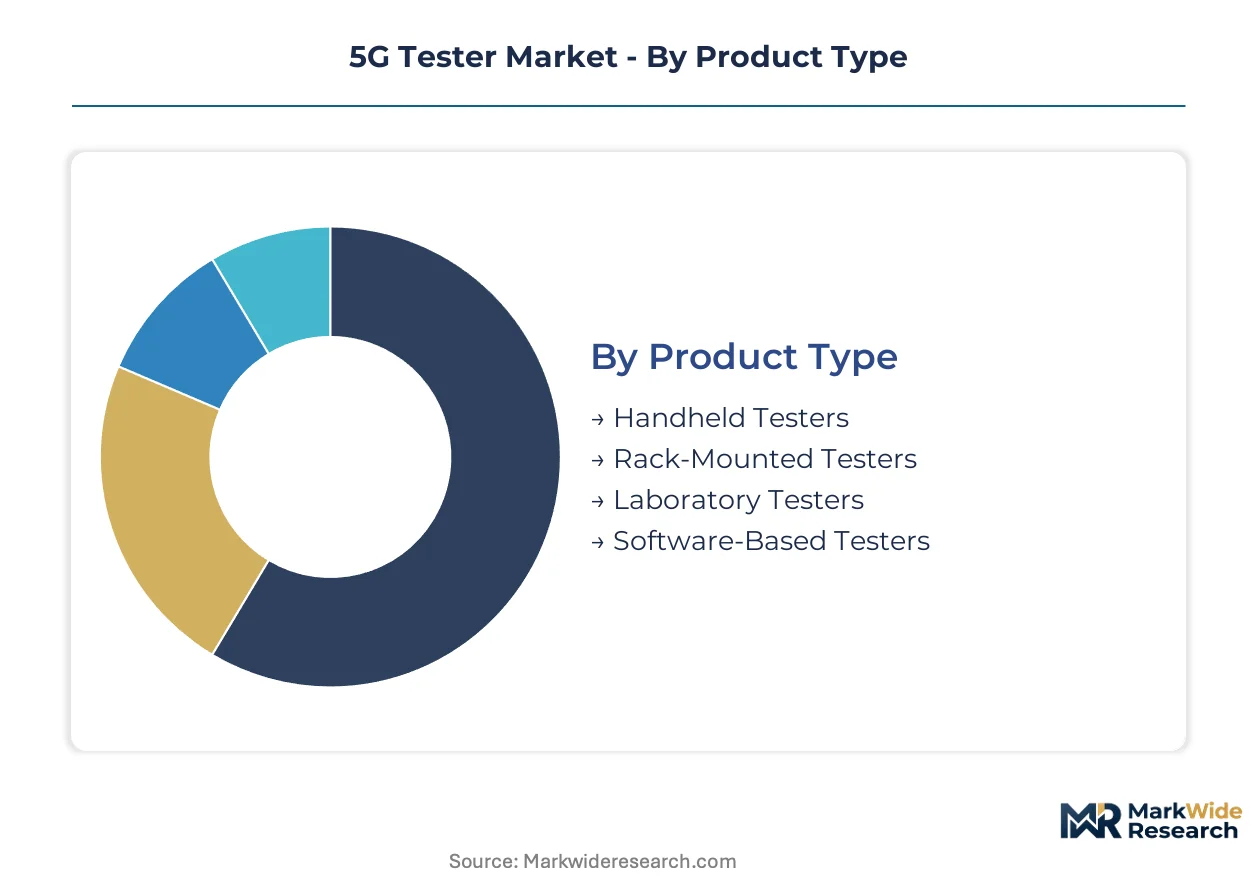
5G tester procurement patterns diverge sharply between centralized carrier labs and distributed manufacturing environments. Equipment form factor, testing protocol complexity, and end-user technical sophistication collectively determine segment boundaries and vendor positioning strategies.
Product Type:
Cost tier differentiation separates portable field units from capital-intensive laboratory installations.
- Rack-Mounted Testers:These chassis-based instruments integrate multi-channel RF analysis with programmable signal generation for massive MIMO validation. Telecommunications operators in Seoul and Munich deploy these in centralized certification labs to process high volumes of base station equipment under FCC and ETSI mandates.
- Software-Based Testers:Virtualized measurement stacks running on hyperscaler infrastructure replace dedicated hardware for device manufacturers. Shenzhen electronics clusters adopt these to compress certification timelines during smartphone launch windows.
- Handheld Testers:Battery-operated units with sub-6 GHz and millimeter-wave capability serve field engineers performing site acceptance testing.
- Laboratory Testers:Precision-grade instrumentation achieves phase noise specifications below -140 dBc per Hz for conformance verification.
Rack-mounted configurations command the established base. The steepest expansion runs through software-based architectures.
Technology:
Application complexity determines whether customers prioritize protocol depth or measurement breadth.
- Network Simulation:Emulation platforms replicate multi-cell interference scenarios and mobility patterns for pre-deployment validation. Open RAN disaggregation multiplies demand as German automotive plants and South Korean smart factories require private network testing capabilities.
- Signal Analysis:Vector signal analyzers with wideband capture process 5G NR waveforms for modulation quality verification. China's MIIT certification deadlines drive procurement at Beijing and Shenzhen manufacturing corridors.
- Wireless Testing:Over-the-air measurement systems validate radiated performance for integrated antenna modules.
- IoT Testing:Narrowband-IoT and RedCap protocol validation addresses industrial sensor certification requirements.
Network simulation captures premium positioning. Signal analysis is gaining share fastest among tier-one device manufacturers.
Application:
Customer workflow integration separates lab-centric from field-deployable testing paradigms.
- Device Certification:3GPP conformance testing against Release 18 specifications requires comprehensive protocol stack validation. US module suppliers front-load electromagnetic compatibility documentation under FCC KDB 447498 D01 procedures to compress authorization timelines.
- Performance Testing:Throughput and latency characterization under loaded network conditions. South Korean operators deploy these capabilities to validate massive MIMO arrays in Seoul's dense urban corridors.
- Network Planning:Propagation modeling and coverage prediction tools for greenfield 5G deployments.
- Field Testing:Drive-test and walk-test solutions for live network optimization and troubleshooting.
Device certification anchors carrier capital expenditure. Performance testing shows the strongest momentum from private 5G deployments.
End User:
Procurement authority and technical staffing levels create distinct buying center dynamics.
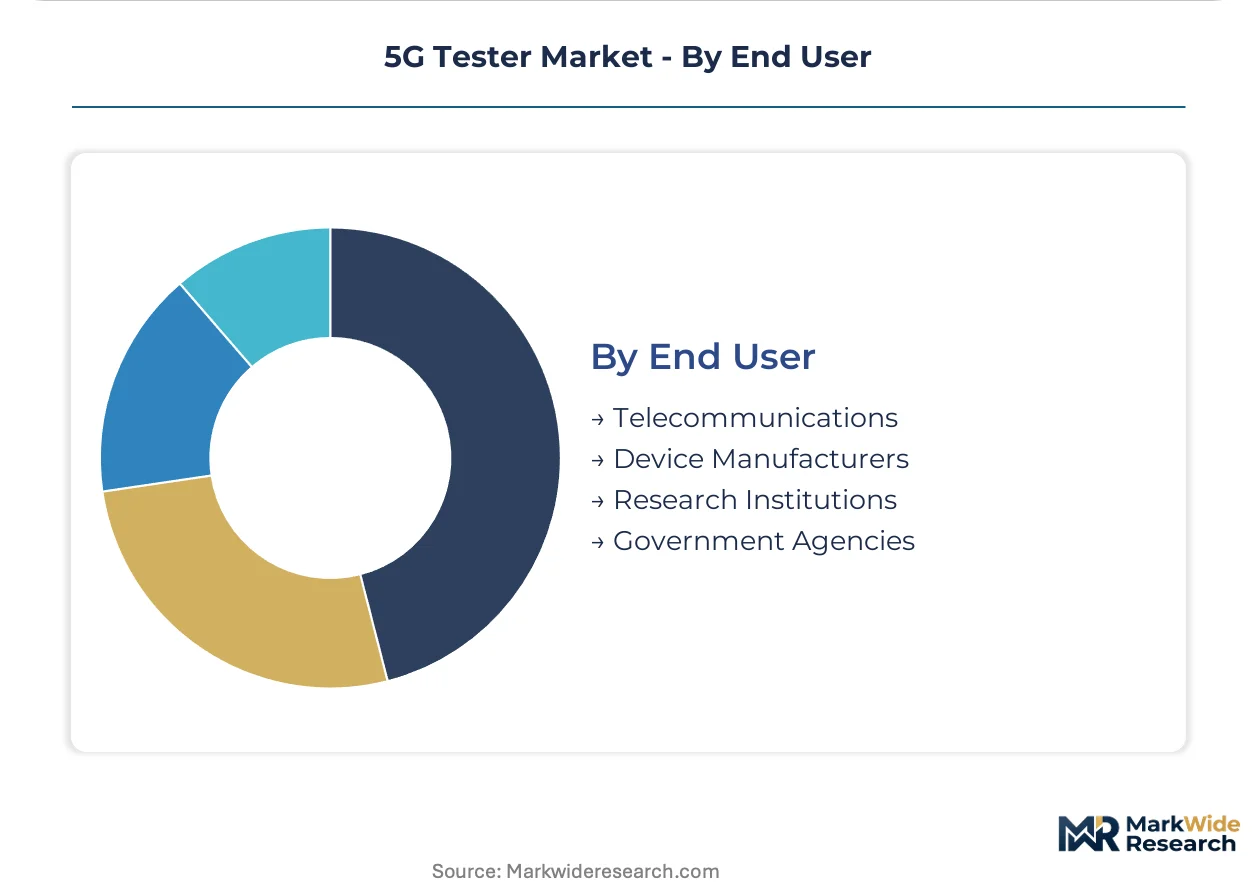
- Telecommunications:Mobile network operators maintain centralized labs with rack-mounted instrumentation for vendor acceptance testing. Verizon and AT&T now acquire equipment through capital leases with independent calibration providers.
- Device Manufacturers:Smartphone and module producers in San Diego and Shenzhen deploy cloud-native test orchestration to scale parallel campaigns during product launches.
- Research Institutions:Academic and government laboratories advance millimeter-wave and 5G-Advanced measurement methodologies.
- Government Agencies:National regulators and defense organizations specify test protocols for spectrum management and secure communications.
Telecommunications operators dominate installed base value. Device manufacturers are expanding most quickly as certification cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test equipment manufacturing clusters in South Korea, Germany, and the United States supply three-quarters of precision 5G validation systems worldwide. Regulatory mandates in each geography dictate firmware release calendars and certification protocols.
United States
FCC spectrum auctions and KDB 447498 D01 equipment authorization procedures compress test timelines for 5G NR modules. Module suppliers front-load electromagnetic compatibility documentation before firmware freeze. San Diego hosts concentrated device manufacturer procurement of cloud-native test orchestration systems.
China
MIIT spectrum re-farming directives for industrial IoT create compliance verification bottlenecks. GB standards alignment with 3GPP Release 18 forces firmware synchronization to national certification calendars. Shenzhen manufacturing corridors deploy software-based testers to compress smartphone launch certification cycles.
Germany
ETSI electromagnetic compatibility mandates under RED 2014/53/EU drive lab instrumentation upgrades. Automotive plants in Bavaria require on-site private 5G validation capabilities bypassing traditional carrier models. Munich anchors European signal analysis R&D partnerships for millimeter-wave measurement methodologies.
South Korea
Terrestrial network densification mandates accelerate massive MIMO array deployment in Seoul's urban corridors. MSIT spectrum allocation timelines synchronize with 3GPP conformance testing requirements. Domestic equipment manufacturing corridors narrow supply gaps for advanced test instrumentation through Seoul-based calibration service density.
Japan
METI industrial 5G spectrum assignments for local 5G networks multiply interoperability testing protocols. JIS standards alignment with international conformance frameworks shapes product roadmaps. Tokyo-Osaka manufacturing belts concentrate procurement of rack-mounted testers for base station vendor acceptance programs.
5G Tester Market Vendor Landscape
Full-stack instrumentation providers and specialized signal analysis developers split the market along capital intensity lines. Tier-one telecommunications operators and device manufacturers drive divergent procurement patterns, with carriers favoring rack-mounted lab systems and manufacturers adopting cloud-native alternatives. Three archetypes dominate: integrated measurement platform vendors, protocol-specific test module specialists, and software-defined virtualization providers. Competitive positioning hinges on calibration service network density and strategic partnerships with hyperscaler infrastructure providers.
Among established measurement platform developers, Keysight Technologies and Rohde & Schwarz exemplify full-stack instrumentation archetypes with extensive calibration laboratory networks. Anritsu occupies a position within millimeter-wave validation specialists competing on module performance specifications. These three entities represent divergent strategic postures toward Open RAN disaggregation and software-defined test migration.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu |
| Teradyne Inc. |
| VIAVI Solutions |
| Spirent Communications |
| National Instruments Corporation |
| EXFO Inc. |
| Tektronix Inc. |
| Others |
Supply Flow & Price Mechanics
Gallium nitride component shortages in Taiwanese foundries determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of final assembly capacity. Buyers face extended lead times that compress margins at the mid-market tier while premium instrumentation commands scarcity premiums through captive supply relationships.
Pricing Analysis
FCC KDB 447498 D01 equipment authorization procedures dictate the pricing tier structure through accelerated certification timelines that front-load validation costs. Pricing stratifies across premium, standard, and economy tiers based on phase noise specifications below -140 dBc per Hz and bundled calibration service density. Cost compression in the standard tier is intensifying because carrier procurement departments unbundle hardware purchases from multi-year service contracts. Device manufacturers in Shenzhen exhibit the highest price sensitivity due to compressed smartphone launch windows, while telecommunications operators in Seoul prioritize metrology traceability over unit cost.
Supply Chain Analysis
Gallium nitride wafers and RF frontend modules feed from concentrated Taiwanese and South Korean semiconductor foundries. The supply chain draws from specialized substrate suppliers in Japan, precision machining clusters in Germany, and final integration facilities in China and the United States. Single-source vulnerability around GaN-on-SiC epitaxy creates 12-16 week lead time exposure for high-frequency test modules. Distribution runs through direct OEM relationships with tier-one carriers and contract manufacturers, supplemented by third-party lab accreditation channels through A2LA and NVLAP in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G tester market is emerging from a cyclical trough driven by 3GPP Release 18 conformance mandates triggering replacement demand across European carrier labs. Capital expenditure normalization follows two years of deferred instrumentation upgrades.
For Market Incumbents: Entrench position through backward integration into GaN component supply and calibration laboratory density expansion in Seoul and Munich. Software-defined radio substitution from academic sectors threatens entry-tier hardware demand, requiring tiered service bundling to defend margin position. Prioritize firmware synchronization with FCC and ETSI regulatory calendars to lock in multi-year carrier contracts. For New Entrants and Emerging Players: India's PLI scheme for telecom equipment at Chennai and Pune clusters represents the most penetrable entry point, bypassing established carrier lab relationships in mature markets. Private 5G network deployments at German automotive plants in Bavaria offer protocol-agnostic validation demand outside traditional procurement channels. Lead with cloud-native test orchestration to displace capital-intensive rack-mounted configurations among device manufacturers. For Investors and Strategic Acquirers: 3GPP Release 18 commercialization timelines reshape the acquisition landscape toward millimeter-wave calibration expertise and Open RAN protocol stack capabilities. The five-to-ten year viability window favors targets with hyperscaler infrastructure partnerships and AI-native test automation roadmaps. Monitor divergence between national spectrum auction schedules and unified global test standards as the primary inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Test Orchestration Migration | Containerized signal analysis on hyperscaler infrastructure reduces per-device certification costs at Shenzhen clusters. |
| Millimeter-Wave Calibration Service Expansion | Seoul and Munich laboratory density captures premium positioning from massive MIMO deployment mandates. |
| Open RAN Protocol Stack Development | O-RAN Alliance and 3GPP specification alignment addresses multi-vendor interoperability testing complexity. |
| AI-Native Fault Prediction Integration | Machine learning-driven automation compresses device certification cycles for tier-one manufacturers. |
| Private 5G On-Site Validation Capability | Bavarian automotive plants require bypassed carrier lab models for industrial network deployment. |
Methodological Framework
Initial hypotheses were tested against primary input from RF test engineering directors, carrier procurement managers, device manufacturer quality leads, and calibration laboratory technical officers and refined through secondary validation against FCC equipment authorization databases, ETSI electromagnetic compatibility filings, 3GPP release documentation, and MIIT spectrum re-farming directives. Bottom-up instrumentation shipment data from manufacturing clusters triangulated with top-down carrier capital expenditure disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, testing protocol complexity, end-user technical sophistication, and regional regulatory cluster alignment. CAGRs derived from fitted growth curves applied to vendor-reported shipment volumes and carrier procurement pipeline visibility. Forecast inputs incorporated Open RAN disaggregation velocity and GaN component lead time normalization assumptions.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and spectrum auction timing would shift the trajectory. Forecasts reflect documented assumptions about 3GPP release synchronization and foundry capacity expansion. Cross-checking against hyperscaler infrastructure capex disclosures and carrier equipment authorization filing rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Griffin Beaker Market
Others
Reinforcement Geosynthetics Market
Others
Senior Cat Food Market
Others
Surgical Simulation Market
Others
Industrial Tablet PC Market
Others
Smart Home Solutions Market
Others
Retail Media Platform Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Profiling Floats Market
Others
Global Duty-Free Retailing Market
Others
Middle East Paper Making Machine Market
Others
Space Cables Market
Others
Global Alpha Cypermethrin Market
Others
Underwater Lighting Market
Others
Fresh Apples Market
Others
Europe Travel Retail Market