
 Roasted Wheat Market | 2026-2036
Roasted Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
Roasted Wheat Market Analysis
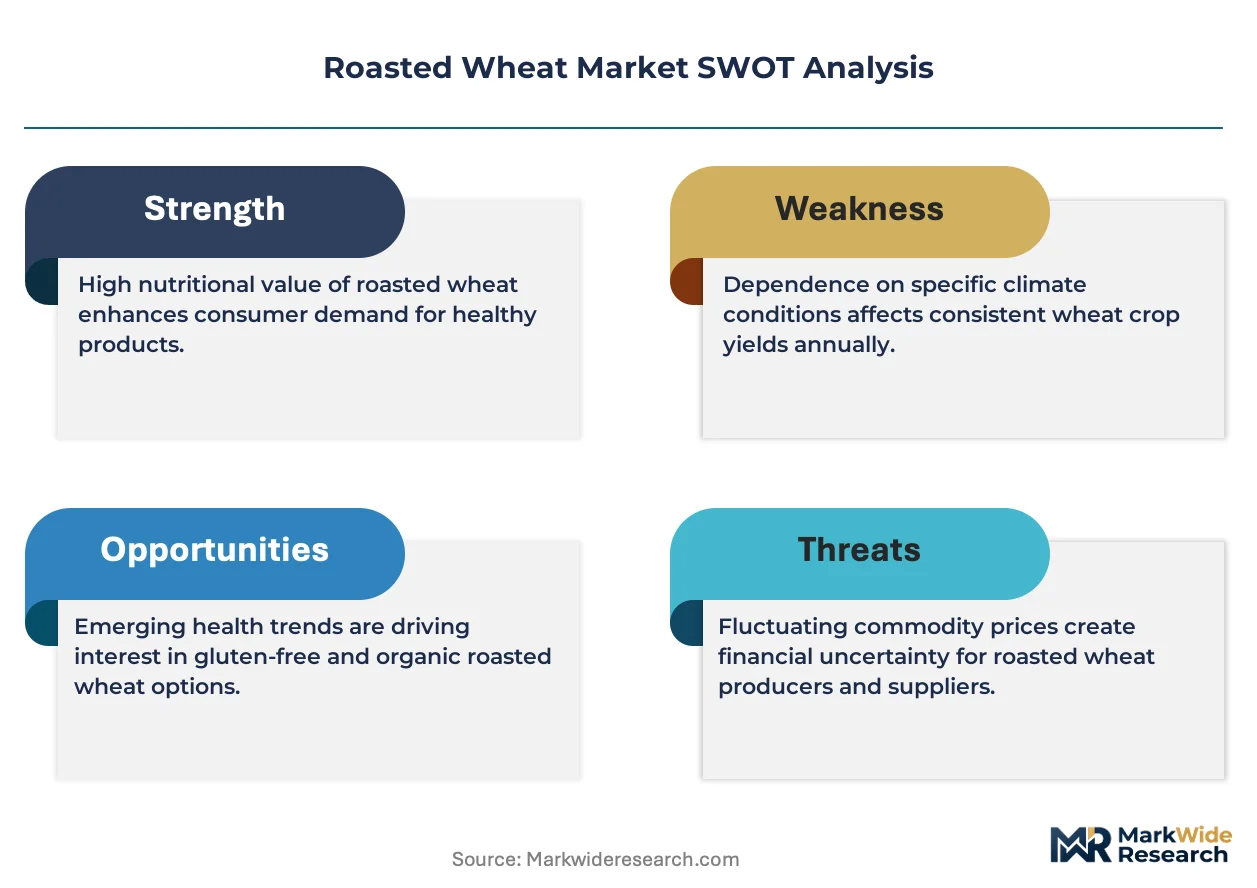
Artisanal bakeries and specialty snack producers is collapsing the traditional commodity purchasing patterns that once dominated roasted wheat procurement. Cargill leverages its vertically integrated grain handling network to secure premium roasting feedstock across multiple origins. Archer Daniels Midland Company anchors North American supply through its malting and specialty grain processing infrastructure. Bunge Limited competes on origination scale, connecting Black Sea and Argentine wheat flows to European roasting facilities.
Roasted wheat comprises heat-treated wheat kernels or milled fractions subjected to controlled temperature profiles between 140°C and 180°C to develop Maillard-derived color, flavor, and enzymatic stability for food manufacturing. The process reduces moisture to below 4% while generating characteristic nutty and caramelized notes that function as natural flavor carriers in formulated foods. Whole roasted wheat and roasted wheat flour command the deepest margin pools, as bakery sector and cereal applications prize consistent roast profiles for texture and shelf stability. Cracked roasted wheat and roasted wheat grits occupy faster-growing niches, with snack manufacturers favoring their particulate integrity for granola and savory crisp formulations.
EU Green Deal sustainability criteria and REACH chemical safety protocols govern import and processing standards for roasted wheat entering European food chains. The FDA's Food Safety Modernization Act preventive controls apply to U.S.-based roasting operations, while China's GB standards and SAMR food safety inspections shape export-oriented production in Asia. Stakeholders must monitor how divergent carbon accounting rules across these jurisdictions will alter origination premiums and roasting facility siting decisions.
Market Dynamics
Clean-label reformulation mandates from major retailers are forcing roasted wheat suppliers to certify non-GMO and pesticide residue thresholds, compressing traditional commodity sourcing windows and elevating contract premiums for verified sustainable grain.
Growth Catalysts
- EU Green Deal sustainable agriculture requirements:European snack manufacturers now specify carbon-verified wheat origins, redirecting procurement toward certified regenerative farms.
- Maillard reaction control technology:Precision roasting systems enable consistent flavor profiling that bakery sector buyers require for premium positioning.
- Germany:Malt roasting traditions anchor specialty segment development, with artisanal bakeries demanding heritage grain varieties for differentiated product lines.
Market Restraints
- Energy cost volatility:Natural gas prices directly impact roasting facility operating margins, with European processors facing input cost swings exceeding feedstock wheat price movements.
- Black Sea supply concentration:Bunge and Cargill origination dominance in Ukrainian and Russian wheat creates chokepoint risk for European roasting capacity.
- Moisture specification rigidity:Below-4% moisture targets demand continuous thermal monitoring that legacy equipment cannot achieve without capital replacement.
Strategic Opportunities
- India specialty snack sector:Underpenetrated roasted wheat ingredient demand in Indian granola and muesli manufacturing offers first-mover positioning for exporters meeting FSSAI import standards.
- Carbon labeling convergence:EU Green Deal carbon accounting rules and corporate Scope 3 reporting requirements create premium pricing tiers for verified low-emission roasted wheat.
- Direct-to-bakery digital platforms:B2B ingredient marketplaces are collapsing traditional distributor layers, enabling roasting facilities to capture margin previously lost to intermediaries.
Industry Challenges
- Roast profile calibration expertise:Shortage of thermal process engineers capable of optimizing Maillard development across variable wheat protein contents limits capacity expansion.
- REACH chemical safety documentation:ECHA substance registration timelines for roasted wheat by-products delay new product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roasted Wheat Market |
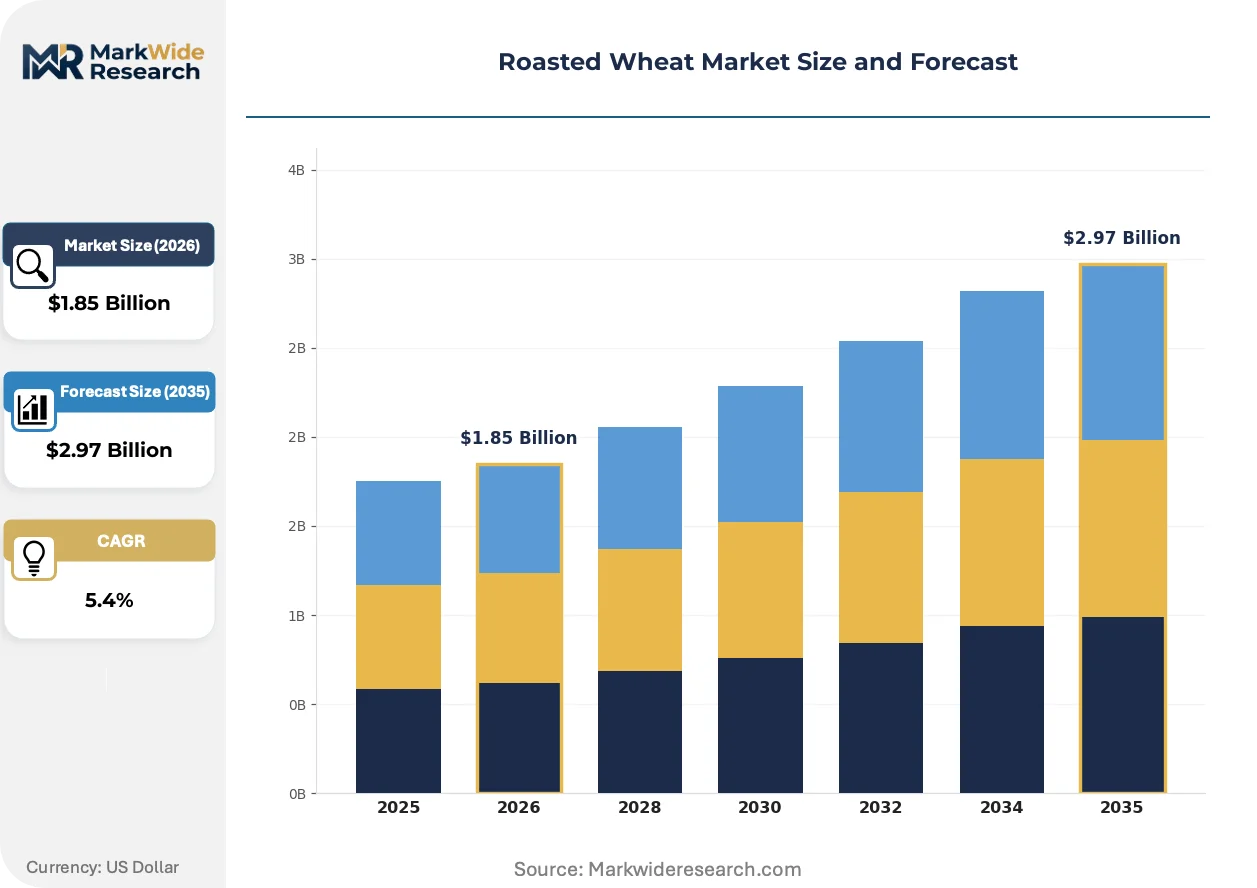
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Roasted Wheat, Cracked Roasted Wheat, Roasted Wheat Flour, Roasted Wheat Grits End User: Food Industry, Bakery Sector, Snack Manufacturers, Beverage Producers Packaging Type: Bags, Bulk Containers, Boxes, Sachets Application: Snacks, Baked Goods, Cereals, Beverages |
| Companies Covered | Cargill, Archer Daniels Midland Company, ConAgra Brands, Bunge Limited, Associated British Foods, Müller Albert Malzfabrik GmbH & Co., Thomas Fawcett & Sons Ltd., Muntons Plc, Simpsons Malt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roasted Wheat Market Emerging Trajectories
Controlled atmosphere roasting and inline spectroscopic monitoring are transforming quality assurance protocols, replacing batch sampling with real-time process control that guarantees specification compliance.
Infrared roasting technology is decomposing the traditional drum-roasting equipment installed base. Snack manufacturers in Germany and the Netherlands are retrofitting facilities with catalytic infrared systems that cut energy consumption by half while tightening roast uniformity. This shift is compressing capital equipment replacement cycles and favoring technology licensors over conventional machinery suppliers.
REACH chemical safety protocols are tightening contaminant thresholds for acrylamide and polycyclic aromatic hydrocarbons in heat-processed grains. European roasting facilities must now implement hazard analysis critical control point systems with third-party verification. Bakery sector buyers in France and Italy are demanding batch-level certificates of analysis, transferring compliance burden upstream to ingredient suppliers.
Long-term supply agreements with fixed roast specifications are displacing spot market purchasing for premium bakery applications. German artisanal bakeries and Scandinavian cereal manufacturers now contract directly with roasting facilities for twelve-month volumes with locked quality parameters. This consolidation of procurement relationships concentrates volume with certified suppliers and marginalizes commodity traders lacking technical service capabilities.
Roasted Wheat Market Segmentation
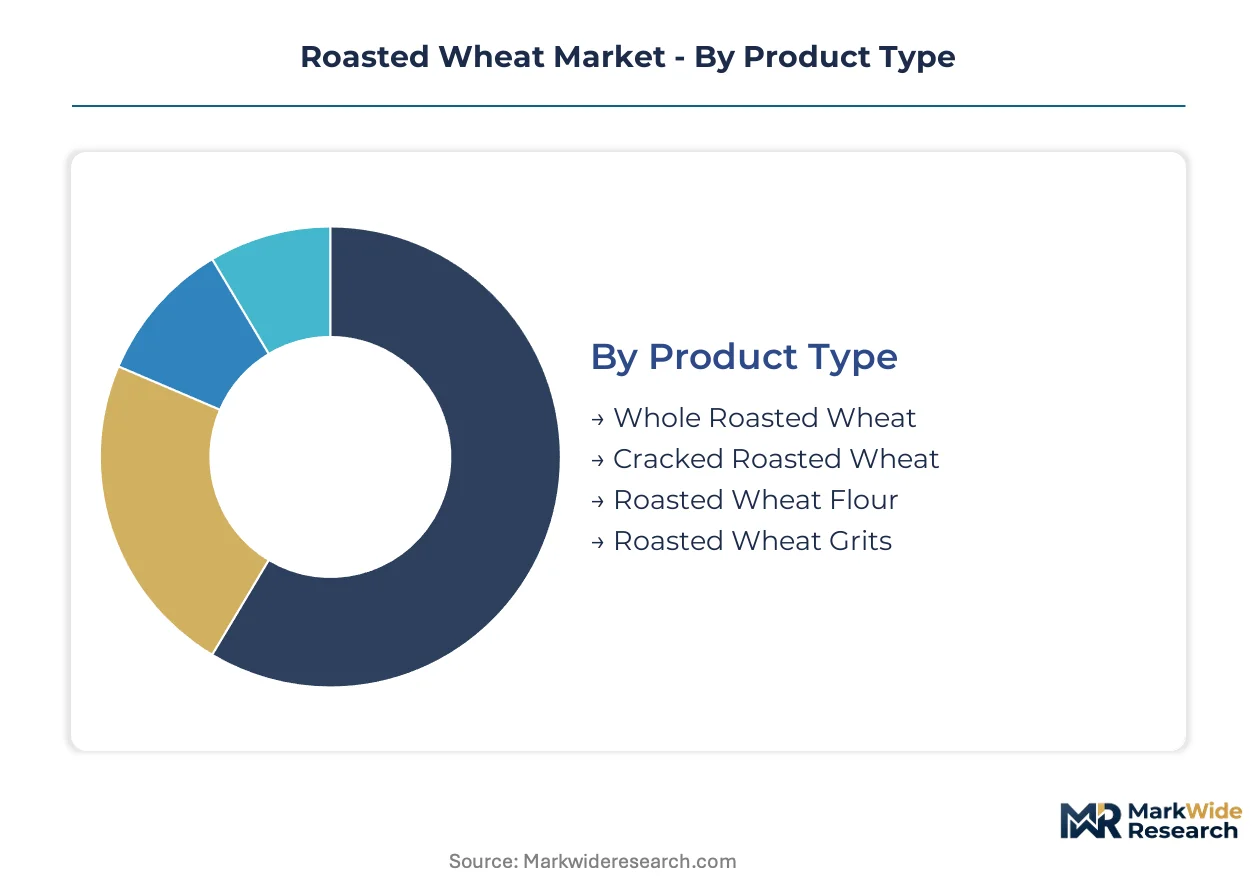
Segmentation in roasted wheat markets separates commodity-grade supply from premium-certified streams. Buyers now specify roast profiles, moisture targets, and carbon-verified origins rather than accepting standard milling grades.
Product Type:
Domestic consumption concentrates on whole kernel and flour formats, while cracked and grit varieties serve export-oriented snack manufacturing. German and Dutch processors dominate premium whole grain exports to Scandinavian markets.
- Whole Roasted Wheat:Intact kernels roasted at 160-180°C to develop uniform Maillard coloration with moisture below 4%. German artisanal bakeries and Scandinavian cereal manufacturers contract directly for heritage grain varieties with locked twelve-month specifications.
- Roasted Wheat Flour:Finely milled fractions with controlled particle size distribution for consistent hydration in bakery formulations. French and Italian bakery sector buyers now demand batch-level certificates of analysis for acrylamide compliance under REACH protocols.
- Cracked Roasted Wheat:Coarse fractured kernels retaining particulate integrity for granola and muesli applications. Indian specialty snack sector demand is climbing fastest for FSSAI-compliant imports.
- Roasted Wheat Grits:Medium-ground particles favored by savory crisp formulators for texture contrast. Dutch snack manufacturers retrofit infrared roasting systems to supply this segment with halved energy consumption.
Whole roasted wheat commands the established base. The steepest expansion runs through roasted wheat grits.
End User:
Cost tier differentiation separates commodity purchasers from premium contract buyers. Large food industry accounts negotiate volume discounts while artisanal segments pay specification premiums.
- Snack Manufacturers:Drive clean-label reformulation mandates requiring non-GMO certification and pesticide residue thresholds. EU Green Deal carbon-verified wheat origins now dominate procurement specifications for European facilities.
- Bakery Sector:Demands consistent roast profiles for texture and shelf stability in premium positioning. Long-term supply agreements with fixed specifications are displacing spot market purchasing across Germany and Scandinavia.
- Food Industry:Bulk purchasers of standard grades for ingredient blending and intermediate processing. Energy cost volatility in natural gas directly compresses operating margins for commodity roasting contracts.
- Beverage Producers:Emerging demand segment utilizing roasted wheat for malt alternatives and flavor carriers in non-alcoholic formulations. Regulatory compliance documentation delays new product launches by 18-24 months under ECHA timelines.
The bakery sector anchors volume commitment. Snack manufacturers are climbing fastest on clean-label premiumization.
Packaging Type:
Volume concentration determines format selection, with bulk dominating industrial accounts and unitized packaging serving smaller processors.
- Bulk Containers:Tote bags and flexible intermediate bulk containers for high-throughput roasting facilities supplying food industry accounts. B2B digital platforms are collapsing traditional distributor layers for this format.
- Bags:Multi-wall paper and woven polypropylene for mid-scale bakery and snack manufacturing procurement. REACH chemical safety protocols govern labeling requirements for European distribution.
- Boxes:Corrugated retail-ready packaging for specialty and organic product lines. Carbon labeling convergence creates premium pricing tiers for verified low-emission supply chains.
- Sachets:Single-serve portions for foodservice and sample distribution. Limited current penetration with expansion potential in direct-to-bakery digital channels.
Bulk containers command the established base. The steepest expansion runs through bag formats as mid-scale buyers consolidate procurement.
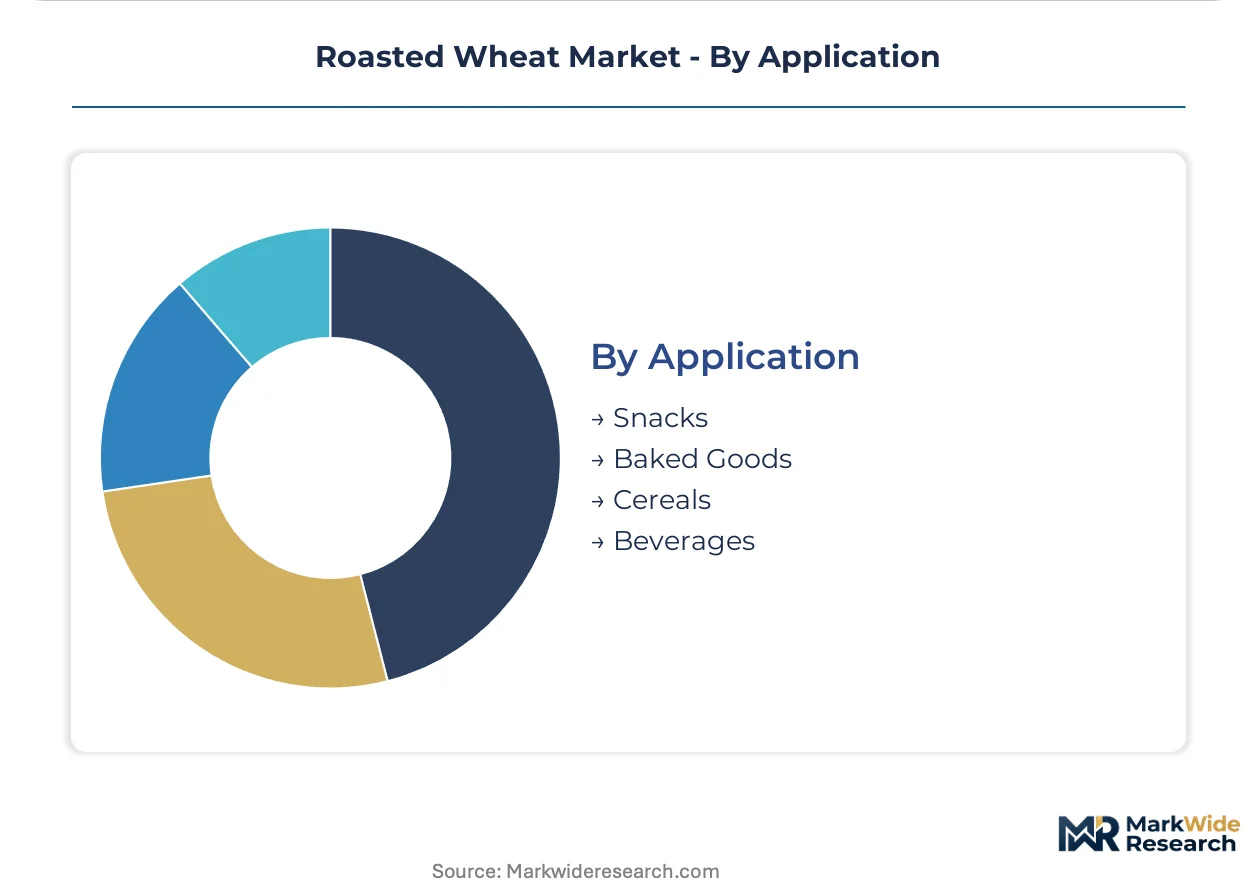
Application:
Customer type maturity separates established cereal applications from emerging beverage experimentation. Traditional baked goods maintain volume while novel formats test market acceptance.
- Baked Goods:Bread, pastry, and cracker applications requiring enzymatic stability and Maillard-derived flavor carriers. Precision roasting systems enable consistent profiling that German artisanal bakeries require for differentiated product lines.
- Snacks:Granola, muesli, and savory crisp formulations exploiting particulate integrity of cracked and grit formats. Infrared roasting technology retrofits are compressing capital replacement cycles for snack-dedicated capacity.
- Cereals:Breakfast and hot cereal applications with heritage grain demand concentration in German malt roasting traditions. Direct contracting with roasting facilities now locks twelve-month quality parameters.
- Beverages:Malt alternatives and roasted grain extracts for non-alcoholic and functional drink formulations. Acrylamide and polycyclic aromatic hydrocarbon thresholds under REACH hazard analysis systems constrain new entrants.
Baked goods command the established base. Beverages represent the fastest-growing trajectory as functional drink experimentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German roasting facilities export heritage grain formulations to Scandinavian cereal manufacturers, while Black Sea wheat flows through Ukrainian and Russian origination points toward European processing capacity.
Germany
Artisanal bakeries in Bavaria and North Rhine-Westphalia contract directly for twelve-month volumes of heritage grain varieties with locked roast specifications. The EU Green Deal's carbon-verified origin requirements redirect procurement toward certified regenerative farms in Lower Saxony. Malt roasting traditions in Bamberg and Hamburg anchor specialty segment development for premium positioning.
United States
Snack manufacturers in the Midwest and Pacific Northwest specify non-GMO certification and pesticide residue thresholds under clean-label reformulation mandates. The FDA's Food Safety Modernization Act preventive controls govern roasting operations across Illinois and Minnesota facilities. Cargill leverages vertically integrated grain handling networks to secure premium feedstock across multiple origins.
France
Bakery sector buyers in Île-de-France and Auvergne-Rhône-Alpes demand batch-level certificates of analysis for acrylamide compliance. REACH chemical safety protocols administered by ECHA tighten contaminant thresholds for heat-processed grains. Roasting facilities near Lyon implement hazard analysis critical control point systems with third-party verification.
India
Specialty snack manufacturers in Maharashtra and Gujarat drive climbing demand for FSSAI-compliant cracked roasted wheat imports in granola and muesli applications. The Food Safety and Standards Authority of India governs import standards for roasted grain ingredients. Mumbai-based processors represent first-mover positioning opportunities for exporters meeting certification requirements.
Netherlands
Snack manufacturers in Randstad retrofit facilities with catalytic infrared roasting systems that halve energy consumption while tightening roast uniformity. The EU Green Deal's sustainable agriculture requirements reshape grain sourcing protocols across Dutch supply chains. Rotterdam-area processors dominate premium whole grain exports to Scandinavian markets.
Roasted Wheat Market Vendor Landscape
Listed leaders compete with private specialists across origination scale and roasting technology differentiation. The vendor base spans multinational grain traders with captive processing assets alongside family-owned malting houses with heritage equipment. Three archetypes dominate: vertically integrated commodity traders, specialty malting cooperatives, and regional roasting specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves, with technology licensing emerging as a secondary vector.
Within the integrated commodity tier, Cargill and Bunge Limited exemplify scale-driven origination models connecting Black Sea and Argentine wheat flows to European roasting capacity. Archer Daniels Midland Company anchors North American supply through malting infrastructure. Among specialty fabricators, Müller Albert Malzfabrik GmbH & Co. and Thomas Fawcett & Sons Ltd. represent the heritage malting tradition, occupying positions where artisanal bakeries demand locked twelve-month specifications.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| ConAgra Brands |
| Bunge Limited |
| Associated British Foods |
| Müller Albert Malzfabrik GmbH & Co. |
| Thomas Fawcett & Sons Ltd. |
| Muntons Plc |
| Simpsons Malt |
| Others |
Supply Flow & Price Mechanics
Long-term supply agreements with fixed roast specifications lock in both feedstock access and price visibility for German artisanal bakeries and Scandinavian cereal manufacturers, compressing spot market liquidity while elevating contract premiums for carbon-verified heritage grain varieties under EU Green Deal sourcing protocols.
Pricing Analysis
The technology-generation pricing gap separates catalytic infrared roasting systems from legacy drum equipment, with Dutch and German facilities commanding specification premiums for energy-halving uniformity. Three-tier pricing structure across premium certified-organic, standard commercial-grade, and economy commodity tiers stratifies by carbon verification status and Maillard consistency documentation. Cost compression in economy-grade supply is intensifying because Black Sea origination volatility feeds into feedstock wheat price swings. Snack manufacturers with clean-label mandates show least price sensitivity, while bulk food industry purchasers negotiate volume discounts that squeeze roasting facility margins.
Supply Chain Analysis
Inventory cycles extending twelve to eighteen months for heritage grain contracting characterize procurement patterns, with German malt roasting traditions anchoring the longest lead-time commitments. Supply concentrates in Germany, the Netherlands, and Ukraine, with Black Sea flows feeding European processing capacity through Bunge and Cargill origination networks. Feedstock wheat, natural gas for thermal processing, and specialized roasting equipment constitute critical input dependencies. Single-source vulnerability runs through Ukrainian wheat corridors subject to geopolitical disruption. Distribution runs through B2B digital platforms collapsing traditional distributor layers for mid-scale bakery and snack manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roasted wheat market constitutes a high-growth disruption as precision Maillard control technology and EU Green Deal carbon accounting protocols simultaneously elevate technical barriers and premium pricing tiers across European supply chains.
For Market Incumbents: Fortify origination control through backward integration into certified regenerative farming partnerships in Lower Saxony and Bavaria, insulating against Black Sea supply chokepoint risk while capturing carbon-verified premium tiers that commodity traders cannot access. For New Entrants and Emerging Players: Technical service gaps in roast profile calibration and batch-level REACH documentation for French and Italian bakery sector buyers present white-space entry points, with FSSAI-compliant export positioning into Maharashtra and Gujarat offering first-mover leverage in India's underpenetrated granola and muesli ingredient demand. For Investors and Strategic Acquirers: Heritage malting cooperatives with locked twelve-month artisanal contracts and proprietary thermal process engineering expertise represent prime acquisition targets, with long-term viability hinging on carbon labeling convergence across EU Green Deal and corporate Scope 3 reporting requirements; monitor ECHA substance registration timeline acceleration as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Infrared Technology Licensing | Halves energy consumption for Dutch snack manufacturers retrofitting legacy drum equipment. |
| Carbon-Verified Origination Partnerships | Locks premium pricing tiers under EU Green Deal sustainable agriculture requirements. |
| Direct-to-Bakery Digital Platform Launch | Captures distributor margin previously lost to intermediaries in German artisanal supply chains. |
| REACH Compliance Documentation Investment | Accelerates ECHA substance registration timelines constraining new roasted wheat by-product launches. |
| FSSAI Certification Pathway Development | Enables export positioning into Maharashtra and Gujarat specialty snack manufacturing clusters. |
Methodological Framework
Cross-validation between primary interviews with thermal process engineers, procurement leads at German artisanal bakeries, snack manufacturer R&D directors, and roasting facility operations managers and secondary sources including EU customs trade data, ECHA substance registration databases, and FSSAI import compliance records anchors the qualitative findings. Bottom-up volume modeling triangulates against top-down value estimates derived from malting and specialty grain processing capacity disclosures.
Sensitivity analysis across variable natural gas price scenarios and Black Sea wheat origination disruption probabilities shapes the analytical framework. Segmentation dimensions modeled include product format, end-user industry, packaging type, and application category across the projection horizon. CAGRs derive from historical roasted wheat ingredient demand trajectories in bakery and snack manufacturing, calibrated against clean-label reformulation adoption curves and carbon verification premium capture rates.
Underlying assumptions cover sustained EU Green Deal implementation, stable FSSAI import standard enforcement, and gradual infrared roasting technology penetration, with deviation risk concentrated in energy cost volatility and geopolitical supply corridor disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Japan 3D Printing Construction Market
Others
India Smart Home Market
Others
Global Video Processing Platform Market
Others
North America Machine Vision Systems Market
Others
Nyerereite Market
Others
Cremation Furnace Market
Others
5G Enabled Healthcare Services Market
Others
Air Separation Module Kit Market
Others
Subtilisin Market
Others
Europe Medical Simulation Market
Others
Billet Market
Others
GCC Shisha Tobacco Market
Others
Canada 3D Printing Construction Market
Others
UK Real Estate Hospitality Market
Others
Global Flexible PVC Films Market
Others
Safety Critical Software Testing Market