
 Diamond Mining Market | 2026-2036
Diamond Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Mining Market Analysis
African kimberlite producers is restructuring output quotas to manage above-ground inventories and stabilize rough prices. De Beers Group leverages its Sight holder system to control distribution channels across major cutting centers. ALROSA sustains production from Siberian pipes despite logistical constraints from trade restrictions. Rio Tinto anchors its diamond portfolio through the Argyle legacy and Canadian Arctic developments.
Diamond mining encompasses the extraction of crystalline carbon formations rated at ten on the Mohs hardness scale, recovered from kimberlite pipes, lamproite deposits, and alluvial gravels for gem and industrial applications. Open-pit mining dominates volume output due to lower unit costs at shallow deposits, while marine mining represents the fastest-growing extraction method as terrestrial reserves deplete. Rough diamonds command the largest revenue pool in product type segmentation, though synthetic diamonds are displacing industrial-grade natural stones in electronics and cutting tool applications.
Kimberley Process Certification Scheme standards, EPA mining waste regulations in the United States, and REACH due diligence requirements in Europe shape traceability obligations and market access conditions for rough diamond traders. The EU Green Deal and CSRD reporting frameworks extend carbon disclosure and rehabilitation liability to extractive operations. Stakeholders must monitor evolving synthetic detection protocols and origin verification technologies to preserve premium pricing for natural stones.

Market Dynamics
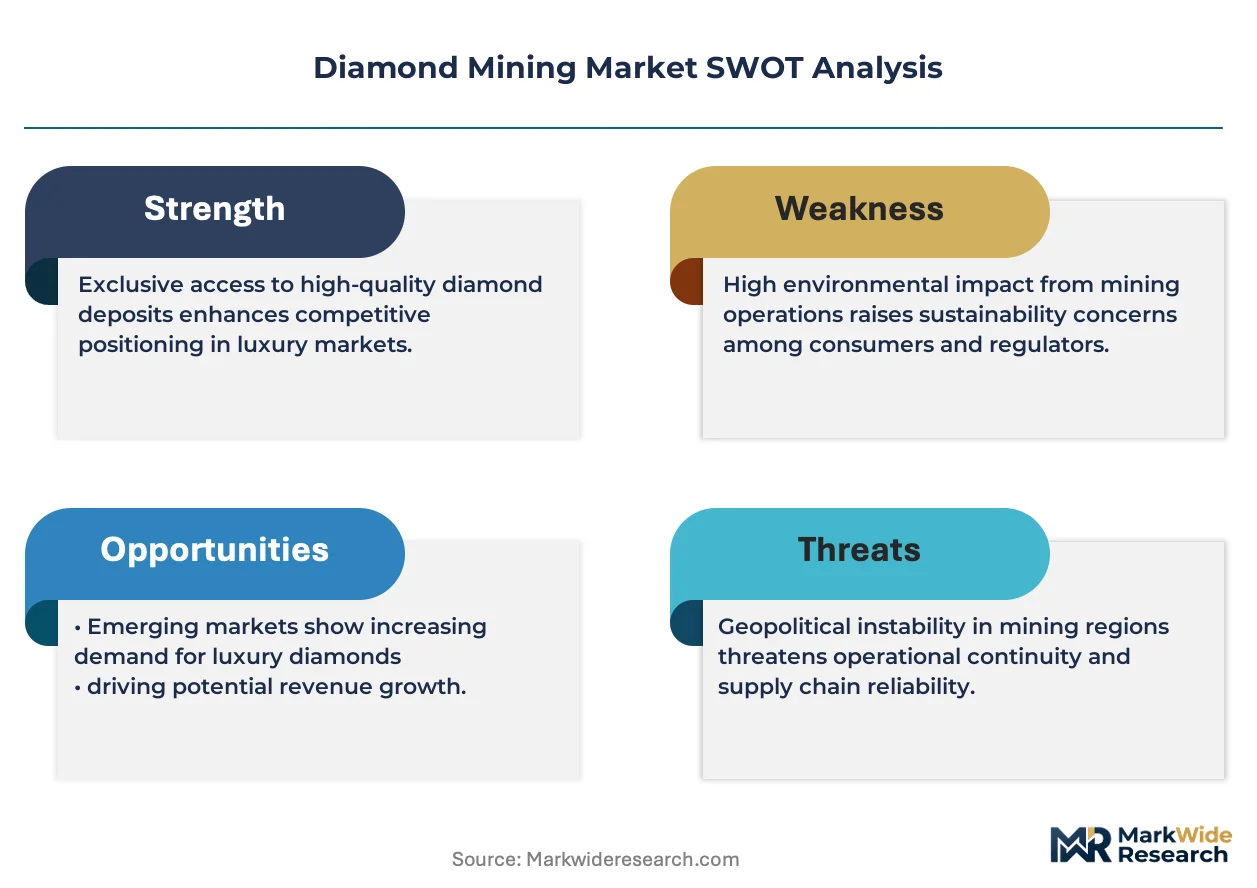
The Diamond Mining Market is experiencing structural pressure from depleting terrestrial kimberlite reserves and the rapid maturation of synthetic production technologies, forcing operators to reconfigure extraction portfolios toward marine deposits and Arctic frontiers while defending natural stone premiums through traceability investments.
Growth Catalysts
- Kimberley Process Certification Scheme:Strengthened due diligence protocols in the European Union under CSRD reporting frameworks are compelling jewelry retailers to source only ethically certified rough stones, tightening legitimate supply channels.
- Marine Mining Technology:Advanced seabed crawler systems and vertical transport methods are unlocking subsea alluvial deposits off Namibia and South Africa as terrestrial pipe grades decline.
- Botswana:The government's renegotiated revenue-sharing agreements with major producers are sustaining capital commitment to Orapa and Jwaneng operations despite price volatility.
Market Restraints
- Energy Input Volatility:Diesel and electricity costs dominate open-pit and marine extraction economics, with Arctic operations facing extreme fuel logistics premiums.
- Russian Supply Concentration:ALROSA's Siberian pipe output remains structurally constrained by trade restrictions, disrupting traditional rough allocation flows to Indian cutting centers.
- Synthetic Substitution:Chemical vapor deposition and high-pressure high-temperature synthetic diamonds are capturing industrial-grade applications in electronics and precision cutting tools.
Strategic Opportunities
- Canadian Arctic:Underdeveloped kimberlite fields in the Northwest Territories and Nunavut offer untapped resource bases with established Indigenous partnership frameworks.
- Blockchain Traceability:Distributed ledger verification systems are converging with laser-inscription technologies to create immutable origin documentation for premium gem segments.
- EU Green Deal Rehabilitation Bonds:Carbon disclosure mandates and mine closure liability instruments are creating financing mechanisms for sustainable extraction certification.
Industry Challenges
- Geotechnical Expertise Scarcity:Deep kimberlite engineering and marine operations command specialized skill sets that mining engineering programs are not producing at replacement rates.
- Synthetic Detection Certification:Laboratory-grown stone identification protocols require continuous capital investment in spectroscopic and luminescence equipment to maintain natural stone market integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Mining Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Open-Pit Mining, Underground Mining, Alluvial Mining, Marine Mining Product Type: Rough Diamonds, Polished Diamonds, Industrial Diamonds, Synthetic Diamonds Application: Jewelry, Industrial Tools, Electronics, HVAC Systems End User: Retail Jewelers, Manufacturers, Auction Houses, Online Retailers |
| Companies Covered | Dominion Diamond, Lucara Diamond, De Beers Group, Mountain Province Diamonds, Gem Diamonds, ALROSA, Petra Diamonds, Archon Minerals, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Mining Market Emerging Trajectories
Technological substitution, regulatory transparency mandates, and buyer preference fragmentation are simultaneously compressing industrial natural diamond demand while elevating traceability premiums in gem segments.
Automated marine mining platforms are overtaking conventional dredging methods in shallow-water alluvial recovery. De Beers Group and Namibian joint ventures are deploying autonomous crawler systems at Atlantic seabed concessions. This technology is overtaking land-based open-pit economics as the primary volume growth mechanism for coarse diamond recovery.
REACH due diligence requirements and the EU Corporate Sustainability Reporting Directive are mandating supply chain disclosure from mine to retail. European jewelry retailers must now document carbon footprint and rehabilitation liability across extraction operations. Gem-grade rough traders serving Antwerp and Paris cutting centers are investing in third-party audit infrastructure to maintain market access.
Certification-driven procurement is fragmenting traditional rough allocation channels. Major retailers are bypassing conventional sight holder systems to establish direct offtake relationships with Botswana and Canadian producers. This pattern is most pronounced in North American and Western European bridal jewelry segments where origin documentation commands measurable price premiums.
Diamond Mining Market Segmentation

Diamond mining segmentation reveals how extraction economics, product grade hierarchies, and end-use specifications create distinct competitive arenas. Each dimension carries unique margin profiles and regulatory exposure that shape operator strategy and investor returns.
Extraction Method:
Standalone extraction operations dominate capital deployment, while embedded recovery systems within diversified mining portfolios operate under different risk-return calculations.
- Open-Pit Mining:Surface excavation of kimberlite pipes using conventional drill-blast-load-haul cycles. De Beers Group's Orapa and Jwaneng operations in Botswana anchor global output volumes under this method, constrained by declining ore grades and stripping ratio escalation.
- Marine Mining:Seabed crawler and vertical transport systems recover alluvial deposits from Atlantic continental shelves. Namibian joint ventures deploy autonomous platforms off the Oranjemund coast as terrestrial pipe reserves deplete, representing the steepest expansion trajectory in extraction technology.
- Underground Mining:Vertical shaft and decline ramp access to deep kimberlite formations. ALROSA sustains Siberian pipe output through this method despite logistical constraints from trade restrictions.
- Alluvial Mining:Recovery of diamonds from river gravels and sedimentary deposits using rotary pans and dense media separation. Artisanal operations in Sierra Leone and Angola supply this channel.
Open-pit mining leads volumes today; marine mining is gaining share fastest.
Product Type:
Cost tier stratification separates gem-grade stones commanding certification premiums from industrial grades facing synthetic displacement.
- Rough Diamonds:Unprocessed crystalline carbon formations extracted from kimberlite and alluvial sources. Antwerp and Dubai trading centers concentrate procurement for this segment, with Kimberley Process Certification Scheme documentation now mandatory for EU market access under CSRD reporting frameworks.
- Synthetic Diamonds:Laboratory-grown stones produced via chemical vapor deposition and high-pressure high-temperature methods. Electronics manufacturers in Japan and South Korea source this grade for thermal management substrates, displacing industrial natural stones in precision cutting tool applications.
- Polished Diamonds:Cut and finished stones ready for jewelry setting. Indian cutting centers in Surat process the majority of global rough supply into this form.
- Industrial Diamonds:Lower-grade natural stones for abrasive and drilling applications. Mining equipment manufacturers represent the core demand pool.
Rough diamonds lead volumes today; synthetic diamonds are climbing the fastest.
Application:
Application maturity varies sharply, with established jewelry demand contrasting against emerging industrial substitution patterns.
- Jewelry:Gem-grade stones set into bridal and fashion pieces. North American and Western European retailers now require blockchain-verified origin documentation, fragmenting traditional rough allocation channels.
- Industrial Tools:Diamond-tipped cutting, grinding, and drilling equipment. Construction and mining machinery producers source this application.
- Electronics:Thermal substrates and semiconductor heat spreaders. Japanese electronics manufacturers drive specification requirements.
- HVAC Systems:Precision bearings and compressor components. Industrial equipment OEMs represent niche demand.
Jewelry leads volumes today; electronics is expanding most quickly.
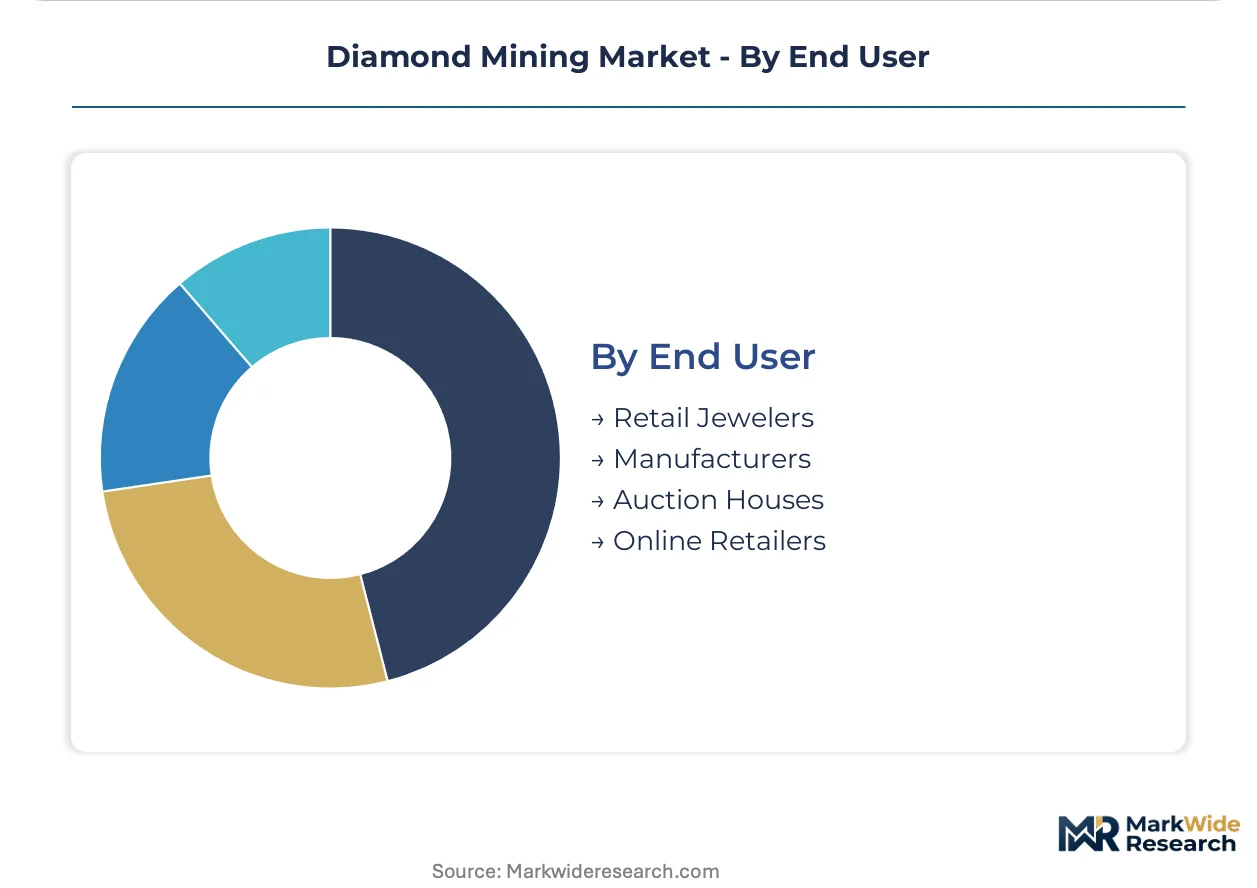
End User:
Customer type concentration determines pricing power, with direct procurement relationships displacing traditional intermediary structures.
- Retail Jewelers:Brick-and-mortar and e-commerce jewelry sellers. Signet Jewelers and Chow Tai Fook bypass conventional sight holder systems to establish direct offtake relationships with Botswana producers.
- Manufacturers:Industrial tool, electronics, and equipment producers. German automotive suppliers and Japanese electronics firms dominate procurement specifications.
- Auction Houses:Secondary market venues for exceptional stones. Christie's and Sotheby's transact rare colored diamonds.
- Online Retailers:Digital-native jewelry platforms. Blue Nile and James Allen serve bridal segments with lab-grown alternatives.
Retail jewelers lead volumes today; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing diamond mining investment toward jurisdictions with streamlined permitting and lower compliance burdens, while EU due diligence rules concentrate premium gem trading in Antwerp and Paris cutting centers.
Botswana
Jwaneng and Orapa kimberlite pipes sustain the world's highest-volume open-pit operations under renegotiated government-miner revenue agreements. The country's national mining regulator enforces local beneficiation mandates requiring rough sorting in Gaborone before export. Diamond Trading Company Botswana anchors rough aggregation activities in the capital.
Russia
Siberian kimberlite deposits in Yakutia supply substantial gem-grade output through underground shaft operations. Trade restrictions from Western sanctions have disrupted traditional rough allocation flows to Indian cutting centers. ALROSA maintains production from Mirny and Udachny pipe complexes despite logistical constraints on export routes.
Canada
Northwest Territories kimberlite fields at Ekati and Diavik represent untapped resource bases with established Indigenous partnership frameworks. Federal environmental assessment processes under the Impact Assessment Agency extend permitting timelines for new Arctic developments. Yellowknife serves as the operational logistics hub for fly-in-fly-out workforce rotations.
Namibia
Atlantic continental shelf alluvial deposits off Oranjemund drive the steepest expansion in marine extraction technology. Joint ventures deploy autonomous seabed crawler systems as terrestrial pipe reserves deplete. The Ministry of Mines and Energy regulates exclusive prospecting licenses for subsea diamond concessions.
South Africa
Venetia kimberlite mine in Limpopo Province transitions from open-pit to underground operations as stripping ratios escalate. The Department of Mineral Resources and Energy administers mining rights with Black Economic Empowerment ownership requirements. Kimberley retains historical significance as the site of the 1866 diamond discovery and early rush-era alluvial workings.
Diamond Mining Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue marine and Arctic frontiers as terrestrial reserves mature. The market structure concentrates around integrated mining houses with captive rough distribution channels and specialized explorers with single-asset development pipelines. Three archetypes dominate: diversified mining conglomerates with diamond as non-core portfolio element, pure-play diamond specialists with concentrated kimberlite exposure, and state-affiliated entities with sovereign resource mandates. Competitive positioning hinges on backward integration into cutting and polishing operations and strategic partnerships with luxury jewelry retailers for direct offtake agreements.
Among diversified mining conglomerates, Rio Tinto anchors its diamond portfolio through Canadian Arctic developments and legacy Argyle operations. De Beers Group exemplifies the integrated specialist archetype with its Sight holder distribution system controlling rough allocation to major cutting centers. ALROSA occupies a position within the state-affiliated tier, sustaining Siberian pipe output despite trade restriction headwinds. These three entities represent distinct strategic postures in an industry restructuring around traceability premiums and synthetic detection capabilities.
| Leading Market Players |
|---|
| Dominion Diamond |
| Lucara Diamond |
| De Beers Group |
| Mountain Province Diamonds |
| Gem Diamonds |
| ALROSA |
| Petra Diamonds |
| Archon Minerals |
| Rio Tinto |
| Others |
Supply Flow & Price Mechanics
EU jewelry retailers' mandatory blockchain origin documentation under CSRD reporting frameworks is forcing rough traders to absorb third-party audit costs, compressing margins at the Antwerp-Dubai intermediary layer while elevating premiums for certified Botswana and Canadian stones.
Pricing Analysis
Distributor margins at Indian cutting centers in Surat compress as direct offtake agreements between Signet Jewelers and Botswana producers bypass traditional sight holder channels. Three-tier pricing structure across premium gem-grade, standard commercial, and economy industrial levels separates stones by Kimberley Process certification status and laser-inscribed origin traceability. Pricing pressure stems from synthetic diamond substitution in thermal management substrates for Japanese electronics manufacturers. Industrial tool producers show highest price sensitivity, while North American bridal jewelry retailers accept measurable premiums for documented provenance.
Supply Chain Analysis
Secondary market flows for recycled polished stones and estate jewelry create price ceiling pressure on primary rough markets, particularly for standard commercial grades without exceptional color or clarity characteristics. Geographic concentration centers on Botswana, Russia, and Canada for kimberlite pipe output, with Namibia anchoring marine alluvial recovery. Diesel fuel and electricity inputs draw from volatile energy markets, while Arctic logistics tether Canadian operations to seasonal transport windows. Single-source vulnerability runs through ALROSA's Siberian pipe complexes under Western trade restrictions. Distribution runs through De Beers Group's controlled sight holder allocations to Surat cutting centers and direct retailer offtake relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diamond mining has entered a late-cycle quality phase where origin documentation and synthetic detection capabilities command premium multiples, with North American and Western European bridal segments now requiring blockchain-verified provenance as a baseline procurement condition.
For Market Incumbents: Deploy laser-inscription and spectroscopic detection infrastructure to defend natural stone premiums against chemical vapor deposition substitutes. Deepen backward integration into Canadian Arctic developments through Indigenous partnership frameworks to secure untapped kimberlite reserves. Channel control through direct retailer relationships insulates against synthetic displacement in gem-grade segments. For New Entrants and Emerging Players: The premium-to-economy tier gap in marine extraction technology offers entry points for autonomous seabed crawler specialists serving Namibian concessions. Target underdeveloped alluvial deposits in Sierra Leone and Angola where artisanal operations lack capital for dense media separation upgrades. Partner with European jewelry platforms seeking verified origin supply outside established sight holder systems. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play diamond specialists holding Canadian Arctic assets and marine technology IP, positioned for premium capture as terrestrial pipe grades decline. Five-to-ten year viability hinges on traceability infrastructure deployment and synthetic detection certification maintenance. Monitor EU Green Deal rehabilitation bond uptake as signal for sustainable extraction financing availability.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Immutable origin documentation preserves premium pricing for Botswana and Canadian stones under CSRD mandates. |
| Marine Mining Technology Licensing | Autonomous seabed crawler IP unlocks Namibian alluvial deposits as terrestrial kimberlite reserves deplete. |
| Synthetic Detection Certification | Spectroscopic and luminescence equipment investments maintain market integrity for natural gem-grade stones. |
| Indigenous Partnership Framework | Established agreements in Northwest Territories and Nunavut accelerate permitting for Arctic kimberlite developments. |
| Direct Retailer Offtake Agreements | Bypassing De Beers sight holder channels captures margin from North American bridal jewelry documentation premiums. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mine operations executives, rough trading desk heads at Antwerp and Dubai centers, jewelry procurement directors, and marine technology engineers with secondary validation. Secondary sources included Kimberley Process Certification Scheme documentation databases, mining ministry production statistics from Botswana and Namibia, EU regulatory filings under CSRD and REACH frameworks, and customs trade records for rough diamond flows. Bottom-up project economics modeling and top-down market sizing triangulated volume and value estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline throughput and post-sanction Russian supply disruption patterns. Segmentation dimensions spanned extraction method, product grade tier, application end-use, and customer type archetype. CAGRs derived from weighted average growth across kimberlite pipe depletion curves and marine mining technology adoption rates. Forecast inputs incorporated synthetic diamond displacement trajectories in industrial applications and EU due diligence compliance cost absorption.
Caveats apply where ALROSA export route reopening, breakthrough synthetic detection protocol failures, or abrupt Kimberley Process governance changes could materially shift the outlook. Practitioners should monitor EU Green Deal rehabilitation bond issuance volumes and marine mining equipment order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military Lighting Market
Others
Coalescing Filter Market
Others
Germany 3D Printing Construction Market
Others
Wind and Solar Hybrid Street Light Market
Others
High-Performance Films Market
Others
Global Cryogenic Tanks Market
Others
Europe Meditation Market
Others
Wearable Brain Devices Market
Others
China Automotive LED Lighting Market
Others
Level Measuring Instrument Market
Others
APAC Machine Vision Systems Market
Others
Japan Smart Home Market
Others
Aircraft Switches Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Italy Feed Additives Market
Others
High Frequency Vibrator Market