
 Profilometer Market | 2026-2036
Profilometer Market Size, Share, and Industry Trends Forecast 2026-2036
Profilometer Market Outlook
The profilometer supply base is consolidating around two distinct performance tiers: sub-nanometer optical systems for EUV mask and wafer qualification versus shop-floor stylus units for general machining. KLA Corporation leverages its installed base in semiconductor process control to dominate the premium optical segment. Bruker Corporation sustains differentiation through white light interferometry depth and breadth across research and industrial accounts. Mitutoyo Corporation anchors the volume stylus tier with dense distribution in metalworking and automotive quality labs.
A profilometer measures surface topography through contact stylus displacement or non-contact optical interference, typically resolving roughness from angstroms to hundreds of micrometers depending on technique. The instrument serves critical functions in semiconductor manufacturing, precision machining, and optical fabrication where surface finish directly determines component performance. Optical profilometers using white light interferometry command the highest margins as foundries push below 3nm node requirements. Stylus profilometers retain durable demand in automotive powertrain and aerospace landing gear where Ra and Rz specifications remain standard. Laser scanning variants are gaining share in electronics assembly for solder paste and conformal coating inspection.
ISO 25178 surface texture standards and SEMI equipment guidelines shape product development cycles and customer qualification protocols in this market. The US FDA and NHTSA impose traceable metrology requirements on medical device and automotive suppliers, reinforcing demand for certified profilometer platforms. Japan's METI and JIS standards bodies coordinate domestic precision equipment roadmaps that influence export specifications. Stakeholders must monitor how CHIPS Act domestic content rules and EU CSRD supply chain disclosure mandates redirect procurement toward auditable, standards-traceable measurement infrastructure.
Market Dynamics
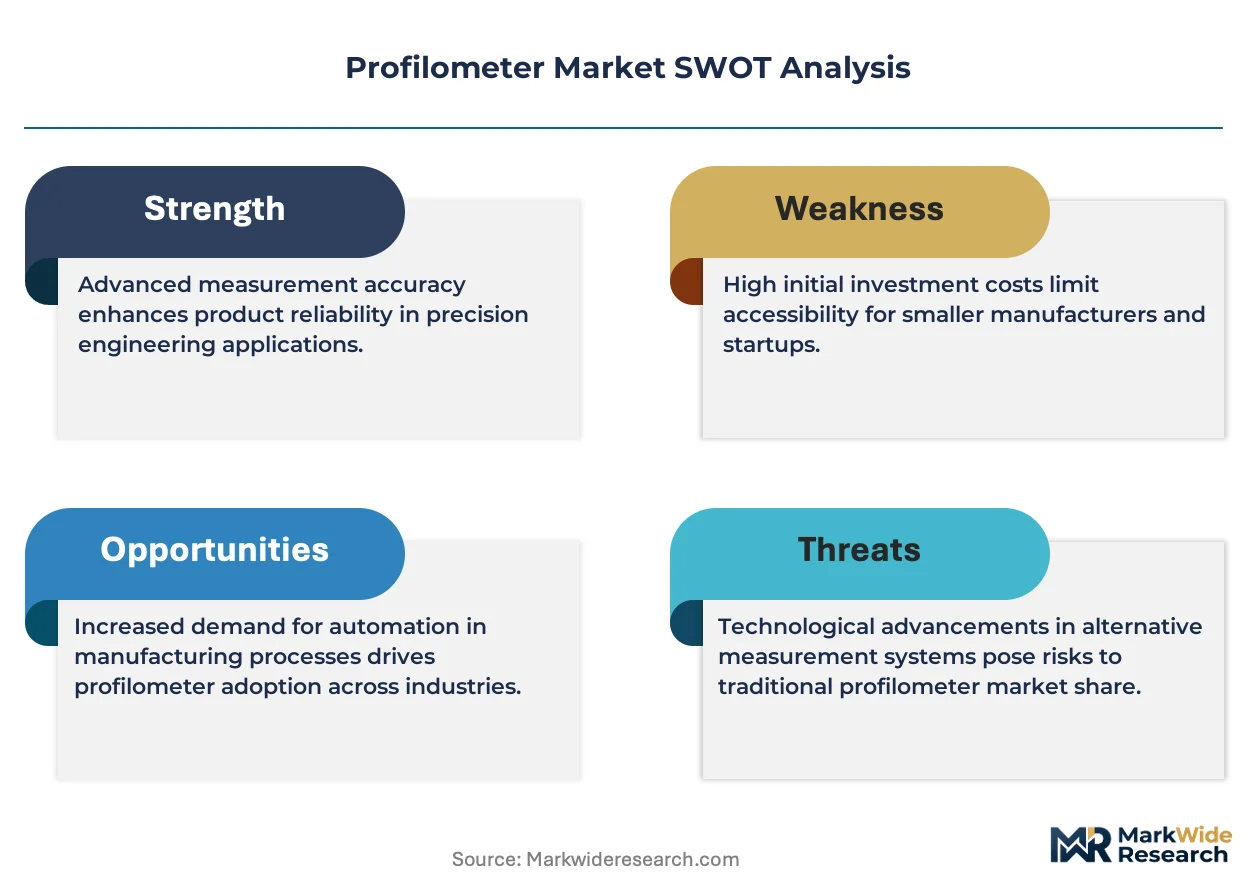
Semiconductor process nodes below 3nm are compressing surface roughness tolerances to sub-angstrom levels, forcing foundries to replace legacy stylus systems with optical interferometry platforms that resolve atomic-layer thickness variations.
Growth Catalysts
- EUV Lithography Nodes:Taiwan and South Korean fabs now require sub-nanometer mask blank qualification, pulling white light interferometry systems into high-volume production lines.
- US CHIPS Act:Domestic content mandates for semiconductor capital equipment are redirecting procurement toward traceable, NIST-calibrated metrology infrastructure.
- ISO 25178:Surface texture standardization across automotive and medical device supply chains is mandating certified profilometer platforms for supplier qualification.
Market Restraints
- Optical Component Concentration:Precision interferometer objectives and piezo stages concentrate in German and Japanese specialty optics suppliers, creating single-source vulnerabilities.
- Technical Ceiling:Stylus profilometers face fundamental physics limits below 0.1nm resolution, blocking their entry into EUV mask qualification workflows.
- Capital Intensity:White light interferometry platforms require cleanroom-grade vibration isolation and temperature control, adding facility costs that exclude smaller machine shops.
Strategic Opportunities
- India Semiconductor Mission:Domestic fab construction under PLI incentives creates first-mover advantage for profilometer vendors establishing local calibration centers.
- Battery Electrode Inspection:Lithium-ion cell manufacturing is adopting laser scanning profilometry for electrode coating uniformity verification.
- AI-Assisted Surface Analysis:Machine learning defect classification is converging with optical profilometry to automate pass-fail decisions in high-mix production environments.
Industry Challenges
- Interferometry Specialist Shortage:Optical system alignment and wavefront calibration require physics-trained technicians that fabs and OEMs struggle to recruit.
- Legacy Integration Friction:New optical profilometers must interface with existing MES and SPC databases through SEMI GEM standards that vary across foundry generations.
- Multi-Site Calibration Drift:Maintaining measurement correlation across Taiwan, South Korea, and Arizona fabs demands continuous round-robin artifact exchanges that strain logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Profilometer Market |
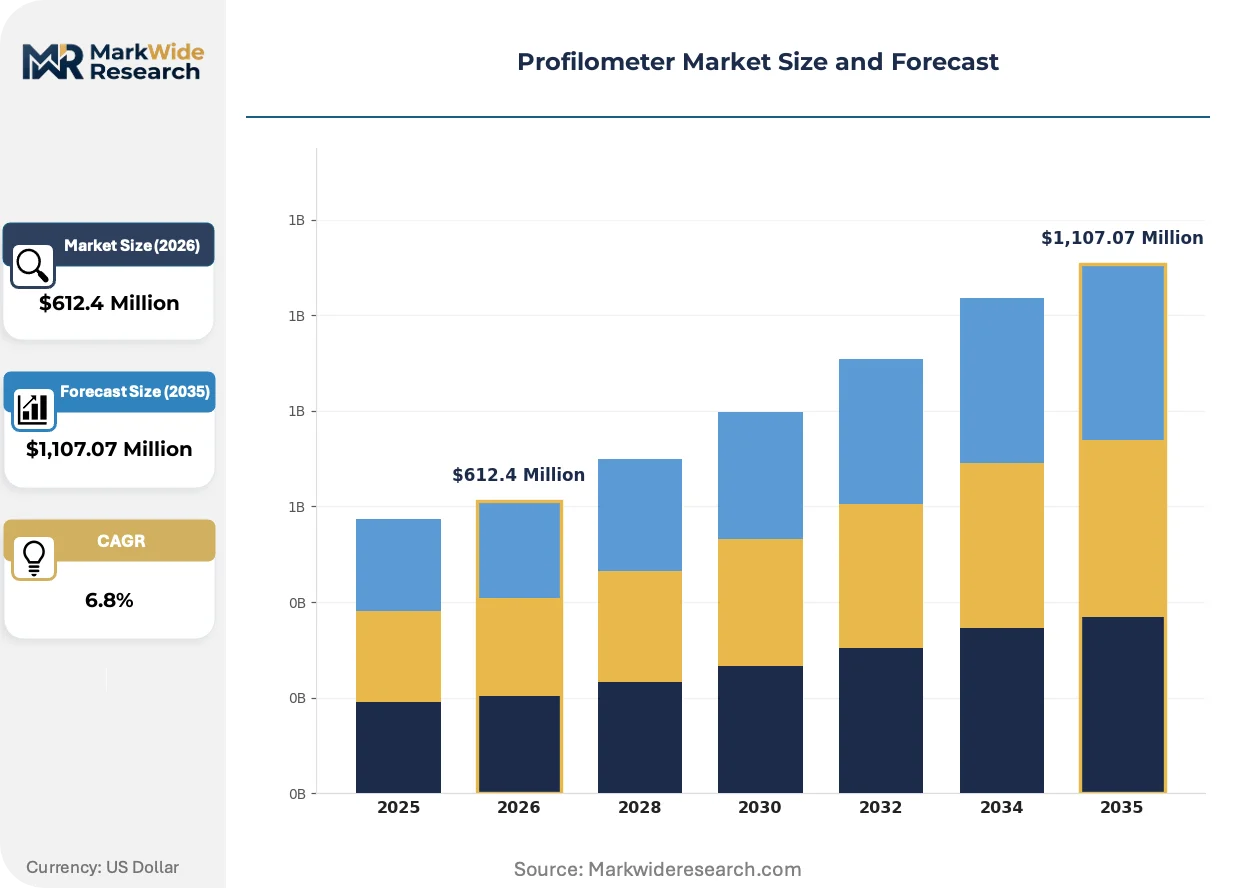
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, Stylus, Non-contact, 3D Technology: Laser, White Light Interferometry, Confocal, Scanning End User: Semiconductor, Automotive, Aerospace, Electronics Application: Surface Roughness, Thickness Measurement, Height Profiling, Quality Control |
| Companies Covered | KLA Corporation, Bruker Corporation, Mitutoyo Corporation, Zygo Corporation, Mahr Federal Inc., Jenoptik AG, Keyence Corporation, AMETEK Inc., Renishaw plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Profilometer Market Strategic Shifts
Optical profilometry is absorbing capabilities from adjacent metrology domains while regulatory pressure and procurement rationalization reshape how surface measurement systems are specified, financed, and deployed across precision manufacturing.
White light interferometry is absorbing atomic force microscopy functions for step height and critical dimension measurement in EUV mask production. Taiwan Semiconductor Manufacturing and Samsung Foundry are accelerating adoption for incoming wafer qualification. This convergence is absorbing budget allocations that previously supported separate AFM installations.
EU CSRD supply chain disclosure mandates are forcing automotive and medical device OEMs to document surface finish traceability for regulatory audits. Tier-1 suppliers must now maintain calibrated profilometer records with ISO 17025-accredited certificates. German automotive suppliers are responding fastest, embedding metrology data directly into digital product passports.
Foundry procurement teams are consolidating vendor relationships from point-tool purchases to multi-year fleet management agreements covering calibration, training, and upgrade pathways. Equipment financing through captive lessors is displacing outright purchase in capital-constrained fabs. This pattern is most visible in South Korea, where memory manufacturers are standardizing on single-vendor optical platforms to reduce qualification overhead.
Profilometer Market Segmentation
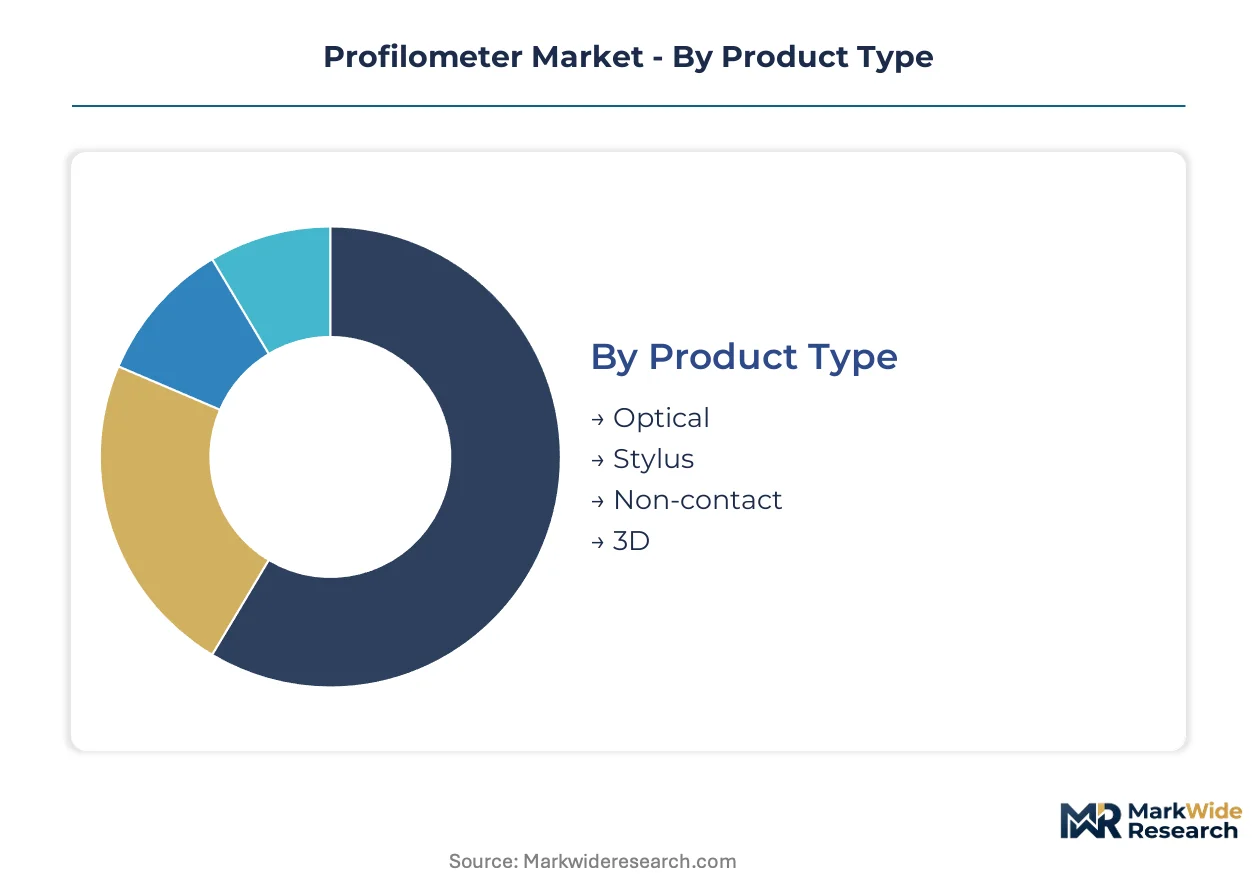
Profilometer procurement divides sharply between fabs requiring sub-nanometer optical resolution and machine shops measuring standard roughness parameters. Segmentation reveals where capital concentrates and which technologies are displacing legacy platforms.
Product Type:
Capital intensity escalates dramatically from shop-floor stylus units to cleanroom-grade optical systems requiring vibration isolation and temperature control.
- Optical:White light interferometry and confocal systems resolve atomic-layer thickness variations for EUV mask blank qualification. Taiwan and South Korean foundries now mandate these platforms for sub-3nm node production, pulling budget from legacy metrology.
- Stylus:Contact profilometers using diamond-tipped probes measure Ra and Rz parameters in automotive powertrain and aerospace landing gear manufacturing. Physics limits below 0.1nm resolution exclude this segment from semiconductor mask workflows.
- Non-contact:Laser triangulation and chromatic confocal variants inspect electronics assembly solder paste and conformal coatings without surface damage.
- 3D:Area-scanning profilometers capture full surface maps for additive manufacturing qualification and medical implant texture verification.
Optical systems absorb the bulk of installed capacity in semiconductor fabs; 3D profilometry is expanding most quickly through additive manufacturing adoption.
Technology:
Resolution specifications and speed requirements determine which technology platforms fabs and OEMs deploy across their measurement workflows.
- Laser:Triangulation and confocal laser systems balance throughput with micron-level precision for electronics assembly and battery electrode inspection. Lithium-ion cell manufacturers in South Korea are adopting these platforms for coating uniformity verification.
- White Light Interferometry:Broadband interference microscopy achieves sub-angstrom vertical resolution for EUV lithography mask qualification. TSMC and Samsung Foundry have standardized on these systems for incoming wafer inspection, consolidating previously separate AFM budgets.
- Confocal:Chromatic confocal sensors measure steep slopes and transparent films that interferometry cannot capture, serving optical component and display manufacturing.
- Scanning:Stage-based raster scanning platforms combine large fields of view with high resolution for aerospace component and precision mold qualification.
White light interferometry commands the highest unit economics; laser profilometry is climbing the fastest through electronics and battery manufacturing expansion.
End User:
Process control intensity and regulatory traceability requirements vary substantially across end-user verticals, shaping procurement specifications and service attach rates.
- Semiconductor:Foundries and mask shops drive demand for sub-nanometer resolution platforms with SEMI-compliant data interfaces. The US CHIPS Act domestic content mandates are redirecting procurement toward NIST-traceable metrology infrastructure.
- Automotive:Powertrain, transmission, and EV battery manufacturers require ISO 25178-certified roughness measurement for supplier qualification. German Tier-1 suppliers are embedding profilometry data directly into digital product passports for EU CSRD compliance.
- Aerospace:Landing gear, turbine blade, and structural component manufacturers demand traceable measurement records for FAA and EASA certification.
- Electronics:PCB, connector, and consumer device manufacturers use mid-range optical and stylus systems for assembly process control.
Semiconductor fabs concentrate the highest-value installed base; automotive quality labs are gaining share fastest through electrification and regulatory disclosure mandates.
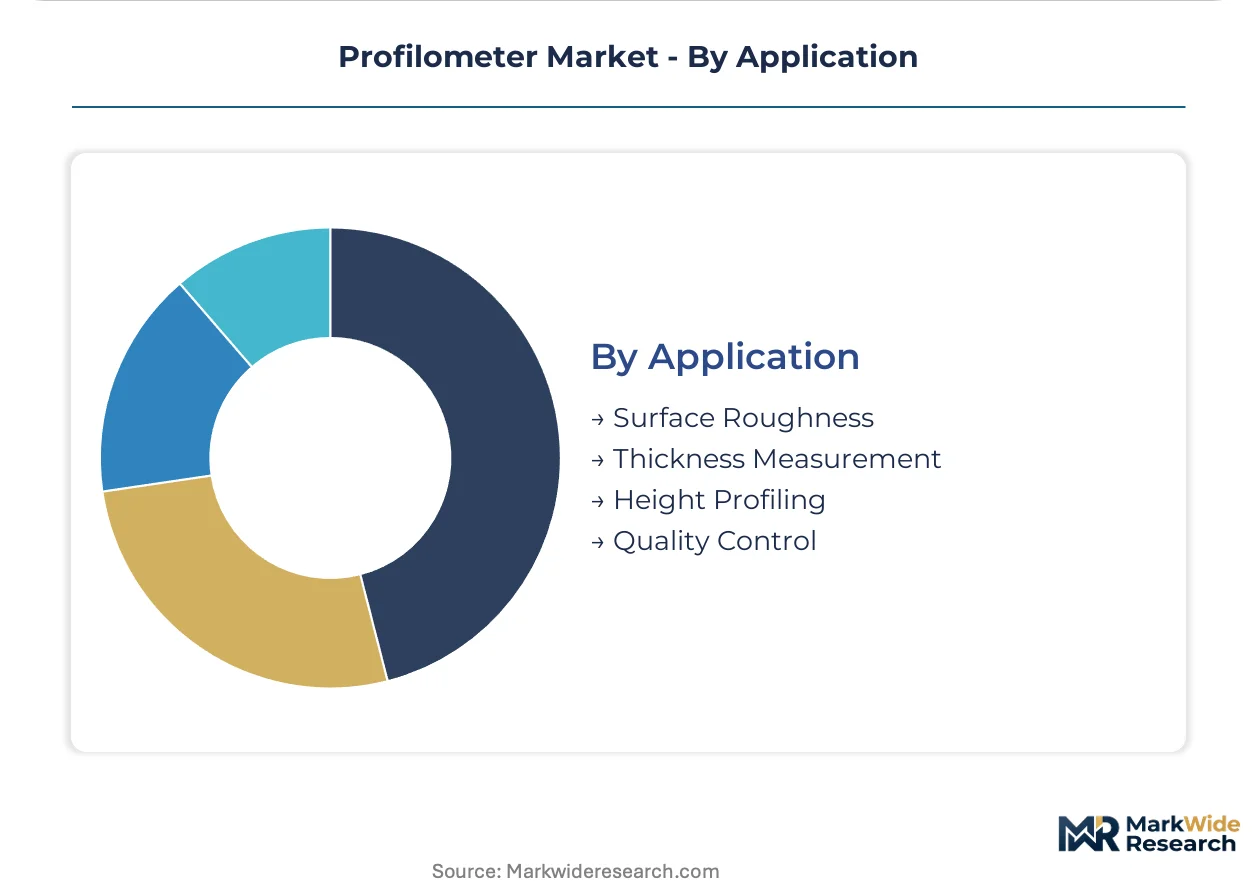
Application:
Measurement function determines instrument specification, with surface roughness requiring different capabilities than dimensional metrology or defect detection.
- Surface Roughness:Ra, Rz, and Sa parameter measurement dominates automotive and general machining quality labs. ISO 25178 standardization is mandating certified platforms with accredited calibration certificates.
- Thickness Measurement:Film and coating thickness verification serves semiconductor, display, and battery electrode manufacturing where layer uniformity determines performance.
- Height Profiling:Step height and critical dimension measurement for MEMS, microfluidics, and precision optics requires interferometric or confocal techniques.
- Quality Control:In-line pass-fail inspection with automated defect classification is converging with AI-assisted analysis in high-mix production environments.
Surface roughness measurement retains the largest installed instrument population; quality control applications are expanding most quickly through automation and AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's densest concentration of profilometer demand, with Taiwan Semiconductor Manufacturing and United Microelectronics Corporation driving sub-nanometer optical platform procurement for EUV lithography nodes.
United States
CHIPS Act subsidies are accelerating fab construction in Arizona and Texas, pulling NIST-traceable metrology infrastructure into domestic semiconductor supply chains. The Department of Commerce domestic content mandates redirect procurement toward certified optical profilometer platforms. Intel's expansion in Chandler and TSMC's fabrication complex in Phoenix concentrate capital equipment deployment in the Southwest.
South Korea
Samsung Foundry and SK Hynix are standardizing on single-vendor optical profilometer fleets to reduce qualification overhead across memory and logic production lines. The Ministry of Trade, Industry and Energy semiconductor cluster investments support metrology infrastructure in the Gyeonggi-Seoul corridor. Yongin and Pyeongtaek host the densest concentration of white light interferometry installations for EUV mask blank qualification.
Japan
Tokyo Electron and Shin-Etsu Chemical are expanding EUV resist and mask blank production, requiring atomic-layer resolution surface characterization. METI precision equipment roadmaps coordinate domestic vendor specifications that influence export requirements. The Kyoto-Osaka-Kobe manufacturing belt concentrates stylus and optical profilometer demand from automotive and precision optics suppliers.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg and Bavaria are embedding profilometry data into digital product passports for EU CSRD supply chain disclosure compliance. The KBA vehicle certification framework mandates traceable surface finish measurement for powertrain components. Stuttgart and Munich industrial clusters drive ISO 25178-certified platform procurement for supplier qualification programs.
China
Domestic fab construction under the 14th Five-Year Plan is creating demand for optical profilometry in Shanghai and Beijing semiconductor clusters. MIIT localization targets are redirecting procurement toward domestic metrology vendors for non-critical applications. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate battery electrode and display manufacturing inspection demand.
Profilometer Market Competitive Environment
Premium-margin players sit above commodity-margin players across resolution capability and cleanroom integration requirements. The market structure bifurcates between sub-nanometer optical systems for semiconductor fabs and shop-floor stylus units for general machining. Three strategic archetypes dominate: integrated process control conglomerates leveraging installed base advantages, precision optics specialists with interferometry depth, and volume metrology houses with dense distribution networks. Competitive moves center on multi-year fleet management agreements displacing point-tool purchases, and captive financing structures reducing customer capital burden.
Within the integrated process control tier, KLA Corporation and AMETEK Inc. exemplify archetypes that bundle profilometry with broader semiconductor metrology portfolios. Bruker Corporation and Zygo Corporation occupy positions among precision optics specialists with white light interferometry heritage. Mitutoyo Corporation and Keyence Corporation anchor the volume-distributed tier with dense service networks in metalworking and automotive quality labs. Mahr Federal Inc. and Jenoptik AG sit within European precision engineering traditions serving automotive and optical fabrication verticals. Renishaw plc represents the metrology-to-manufacturing integration archetype with encoder and motion control adjacencies.
| Leading Market Players |
|---|
| KLA Corporation |
| Bruker Corporation |
| Mitutoyo Corporation |
| Zygo Corporation |
| Mahr Federal Inc. |
| Jenoptik AG |
| Keyence Corporation |
| AMETEK Inc. |
| Renishaw plc |
| Others |
Value Chain & Pricing Dynamics
Piezoelectric ceramic price indices and precision optical glass feedstock benchmarks cascade through profilometer manufacturing tiers, compressing margins on stylus units while amplifying pricing power for cleanroom-grade interferometry systems bound by SEMI qualification protocols.
Pricing Analysis
Yield-guarantee contracts tied to wafer throughput anchor value-based pricing for EUV-qualified optical profilometers. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable semiconductor platforms from ISO 25178-certified automotive systems and uncertified shop-floor units. Cost compression in the stylus tier is intensifying because Chinese domestic vendors are undercutting legacy Japanese suppliers on diamond probe assemblies. Automotive quality labs exhibit highest price sensitivity; foundry process control teams prioritize resolution specifications over unit cost.
Supply Chain Analysis
SEMI S2/S8 safety certification and ISO 17025 calibration accreditation gate access to semiconductor foundry procurement lists, forcing component traceability through every supply tier. Precision interferometer objectives concentrate in Germany and Japan; piezoelectric nanopositioning stages source predominantly from Japanese specialty motion control houses. Single-source vulnerability runs through germanium-doped optical substrates used in broadband interferometry sources. Distribution runs through direct field service organizations for premium optical platforms and industrial distributors for volume stylus units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The profilometer market sits in a technology-transition phase where white light interferometry is systematically displacing legacy stylus systems and atomic force microscopy for sub-3nm node characterization.
For Market Incumbents: Hedge against optical component supply concentration by securing long-term offtake agreements with German and Japanese precision optics suppliers or cultivating qualified secondary sources for piezoelectric stages. Accelerate fleet management contract penetration to lock in recurring calibration revenue and raise switching costs for foundry customers evaluating multi-vendor standardization. For New Entrants and Emerging Players: The US CHIPS Act domestic content mandates open a window for NIST-traceable optical profilometer assembly in Arizona and Texas fabs hungry for qualified local suppliers. Target India Semiconductor Mission incentives for first-mover calibration center establishment ahead of domestic fab commissioning. Pursue battery electrode inspection as the most penetrable adjacent vertical, positioning laser scanning variants for lithium-ion coating uniformity verification. For Investors and Strategic Acquirers: The window for entry favors precision optics specialists with white light interferometry IP and established SEMI compliance pathways. Long-term viability hinges on consolidation plays that bundle surface metrology with broader process control portfolios. Watch for inflection when TSMC or Samsung Foundry announces next-generation mask qualification specifications that obsolete current interferometry resolution thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Center Localization | India Semiconductor Mission PLI incentives reward domestic metrology infrastructure with preferential vendor status. |
| AI-Assisted Defect Classification Integration | Machine learning pass-fail automation addresses interferometry specialist shortages plaguing Taiwan and South Korea fabs. |
| Fleet Management Contract Standardization | South Korean memory manufacturers consolidate vendor relationships to reduce multi-site qualification overhead. |
| Battery Electrode Inspection Platform Launch | Lithium-ion cell manufacturing in South Korea adopts laser profilometry for coating uniformity verification. |
| Digital Product Passport Data Integration | German automotive Tier-1 suppliers embed ISO 25178 traceability for EU CSRD supply chain disclosure compliance. |
Study Parameters
SEMI equipment market databases, foundry capital expenditure disclosures, and ISO 25178 standardization committee records formed the secondary backbone, cross-referenced with primary interviews across semiconductor process control engineers, automotive quality lab directors, and precision optics procurement leads. Bottom-up unit economics modeling triangulated against top-down capital equipment spending patterns validated market sizing across the analysis window.
Historical trendline analysis of fab equipment procurement cycles informed projection frameworks, with segmentation across product type, technology platform, end-user vertical, and application function. CAGRs derived from equipment intensity ratios per wafer start and node migration timelines incorporated EUV lithography adoption curves and CHIPS Act subsidy disbursement schedules as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for EUV mask blank qualification would alter the outlook if directed self-assembly or other patterning technologies displace optical lithography. A model refresh is warranted upon material change in foundry node transition schedules or CHIPS Act domestic content rule enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Hardware Acceleration Market
Others
Aircraft Lighting Market
Others
Hypersensitivity Market
Others
Smart TV Platforms Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Africa Lime Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Drum Motor Market
Others
Video Conferencing Hardware Market
Others
Durian Market
Others
Thermoformed Plastics Market
Others
Global Smart Devices Market
Others
Foldable Smartphone Market
Others
Europe Astrology Market
Others
Flexographic Printing Plate Market
Others
Europe Video Encoder Market