
 Digital Signage Media Player Market | 2026-2036
Digital Signage Media Player Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signage Media Player Market Analysis
4K-native output capability is unwinding the baseline specification floor across procurement contracts. BrightSign LLC leverages its purpose-built OS ecosystem to dominate premium fixed-installation deployments. Samsung Electronics sustains manufacturing scale across integrated display-and-player bundles for corporate campus networks. Advantech Co. Ltd. anchors industrial-grade embedded variants with extended temperature tolerances for transportation hub deployments.
A digital signage media player is a dedicated computing device that decodes and renders multimedia content to attached displays, typically featuring ARM or x86 processors with hardware-accelerated H.265 decoding and HDMI outputs for synchronized multi-screen arrays. These units serve commercial environments requiring scheduled, remote-managed visual communication without general-purpose PC overhead. Embedded players now lead volume shipments due to their fanless thermal designs and solid-state reliability in continuous-operation settings, while cloud-based players capture the fastest expansion as SaaS content management platforms displace on-premise server infrastructure. Wall-mounted installations retain the largest installed base across retail and corporate segments, though mobile units are gaining traction in experiential marketing pop-ups and temporary event deployments.
The FCC's equipment authorization requirements govern radio-enabled smart players in the United States, while the EU's CE marking and RoHS substance restrictions shape product compliance for European distribution. China's MIIT enforces network access licensing for cellular-connected players deployed in public infrastructure projects. Stakeholders must monitor how fragmented energy-efficiency certifications across jurisdictions reshape hardware design priorities and sourcing strategies.
Market Dynamics
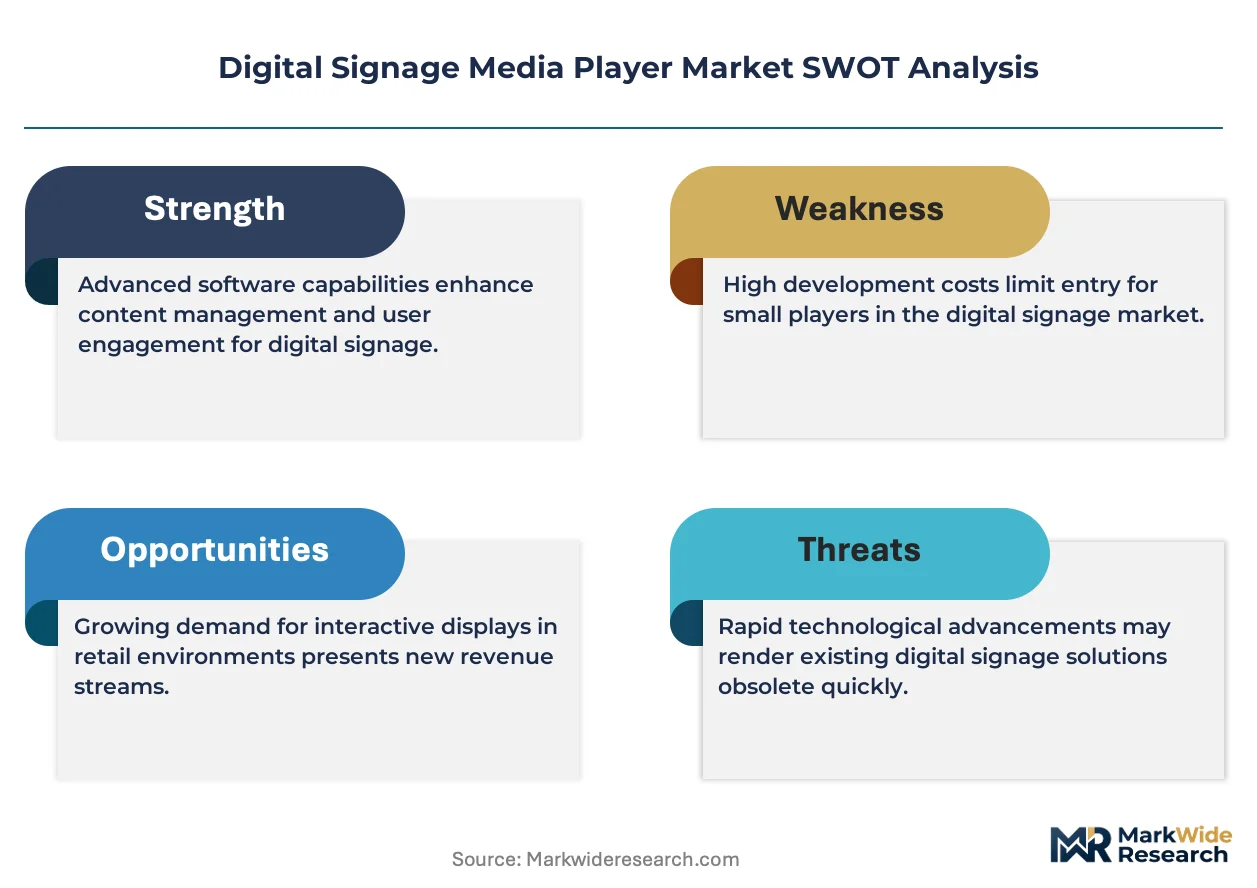
Resolution escalation from 4K toward 8K output is compressing hardware refresh cycles across retail and transit infrastructure deployments. The EU's Ecodesign Directive standby power limits are forcing thermal architecture redesigns in networked player hardware.
Growth Catalysts
- Smart city infrastructure mandates:China's tier-one cities require large-format digital transit installations, driving procurement of outdoor-rated media players with cellular backhaul capability.
- REACH substance restrictions:European RoHS compliance deadlines accelerate replacement of legacy players containing restricted heavy metals in solder and PCB substrates.
- Dynamic shelf-edge advertising:United States retail chains deploy synchronized player arrays for real-time pricing and inventory-linked promotional content at point-of-sale.
Market Restraints
- Semiconductor supply concentration:ARM and x86 SoC fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to foundry allocation volatility.
- Cellular module certification friction:China's MIIT network access licensing adds 4-6 months to deployment timelines for public infrastructure projects.
- General-purpose PC substitution:Mini-PCs with HDMI outputs threaten dedicated player volumes in low-complexity single-screen corporate deployments.
Strategic Opportunities
- India smart city expansion:Tier-two municipal corporations under the Ministry of Housing and Urban Affairs mandate seek cost-optimized players for transit and civic information displays.
- FCC equipment authorization streamlining:Simplified radio certification pathways for Wi-Fi 6E-enabled players reduce time-to-market for North American distribution.
- AI-driven content adaptation:Edge inference chips converging with media decoders enable real-time audience analytics and contextual ad insertion without cloud latency.
Industry Challenges
- Embedded Linux firmware specialization:Shortage of engineers with hardware-accelerated codec optimization skills constrains OEM development timelines.
- Legacy CMS integration:Proprietary on-premise content management protocols resist migration to cloud-native SaaS platforms, complicating fleet upgrades.
- Extended temperature certification:IEC 60068 environmental testing for transportation hub deployments adds cost and validation duration to industrial-grade product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signage Media Player Market |
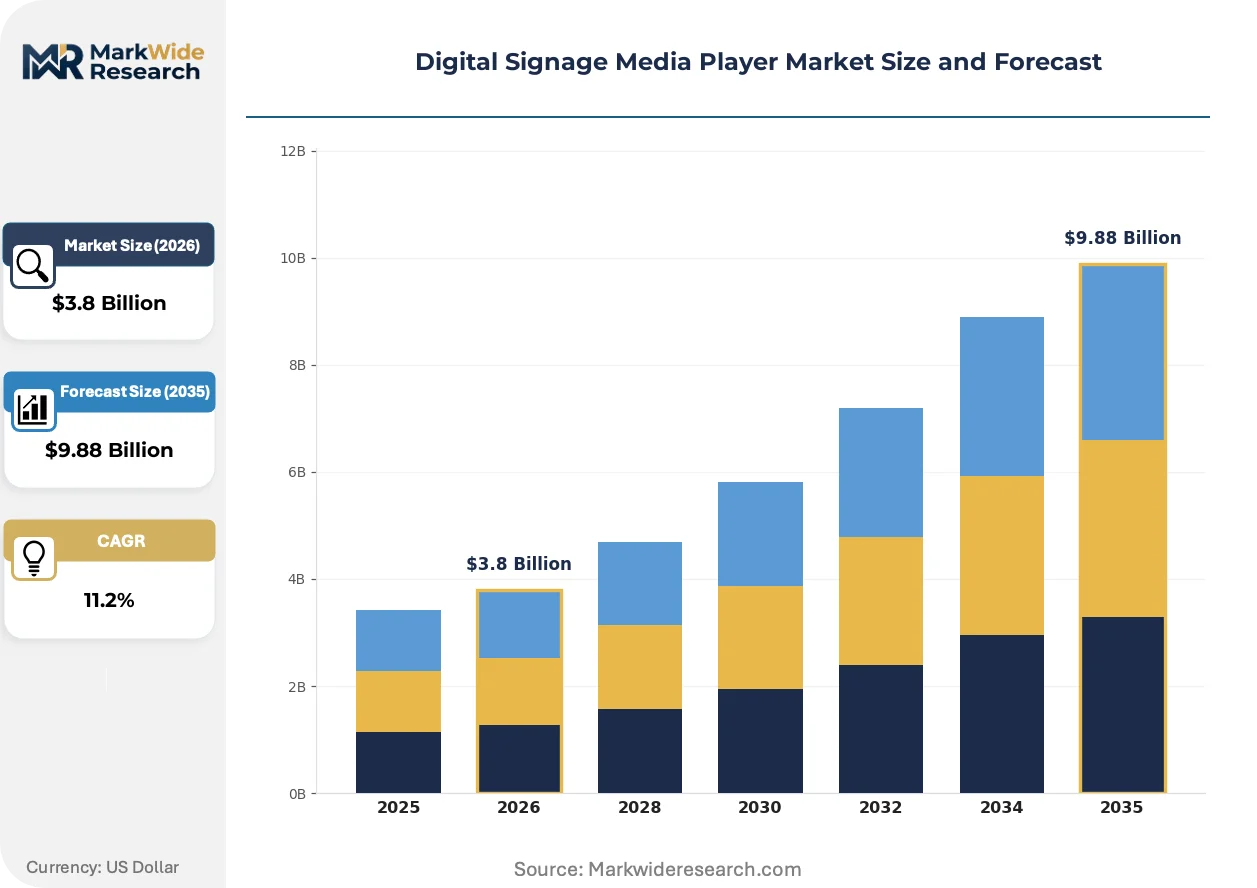
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Players, Embedded Players, Cloud-Based Players, Media Software Technology: LCD, LED, OLED, Projection End User: Retail Stores, Corporate Offices, Educational Institutions, Transportation Hubs Installation: Wall-Mounted, Freestanding, Ceiling-Mounted, Mobile Units |
| Companies Covered | BrightSign LLC, Advantech Co. Ltd., AOPEN Inc., Barco, 3M Company, Samsung Electronics Co., Ltd., LG Electronics, Panasonic, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signage Media Player Market Emerging Trajectories
Hardware acceleration architectures and cloud-native management platforms are restructuring how commercial displays receive and render content. Three distinct vectors are reshaping product development and procurement patterns.
Edge AI inference silicon is bifurcating the media player category into pure decoding units and intelligent nodes capable of real-time audience measurement. Retail and QSR operators in the United States and United Kingdom are piloting computer vision-enabled players for demographic-responsive content scheduling. This capability compression is collapsing the separate server tier previously required for analytics processing.
The EU's Ecodesign for Energy-Related Products Directive is tightening standby power limits below one watt for networked display hardware. Manufacturers must redesign power supply subsystems and implement aggressive sleep-state logic to maintain CE marking eligibility. European distribution channels now prioritize hardware with certified low-power modes, disadvantaging legacy inventory.
Content management platform unbundling from hardware procurement is altering buyer-seller relationships. Large retail chains negotiate SaaS subscriptions separately from player purchases, pressuring bundled-margin business models. This decoupling is most pronounced in North American and Western European enterprise accounts with dedicated AV procurement teams.
Digital Signage Media Player Market Segmentation
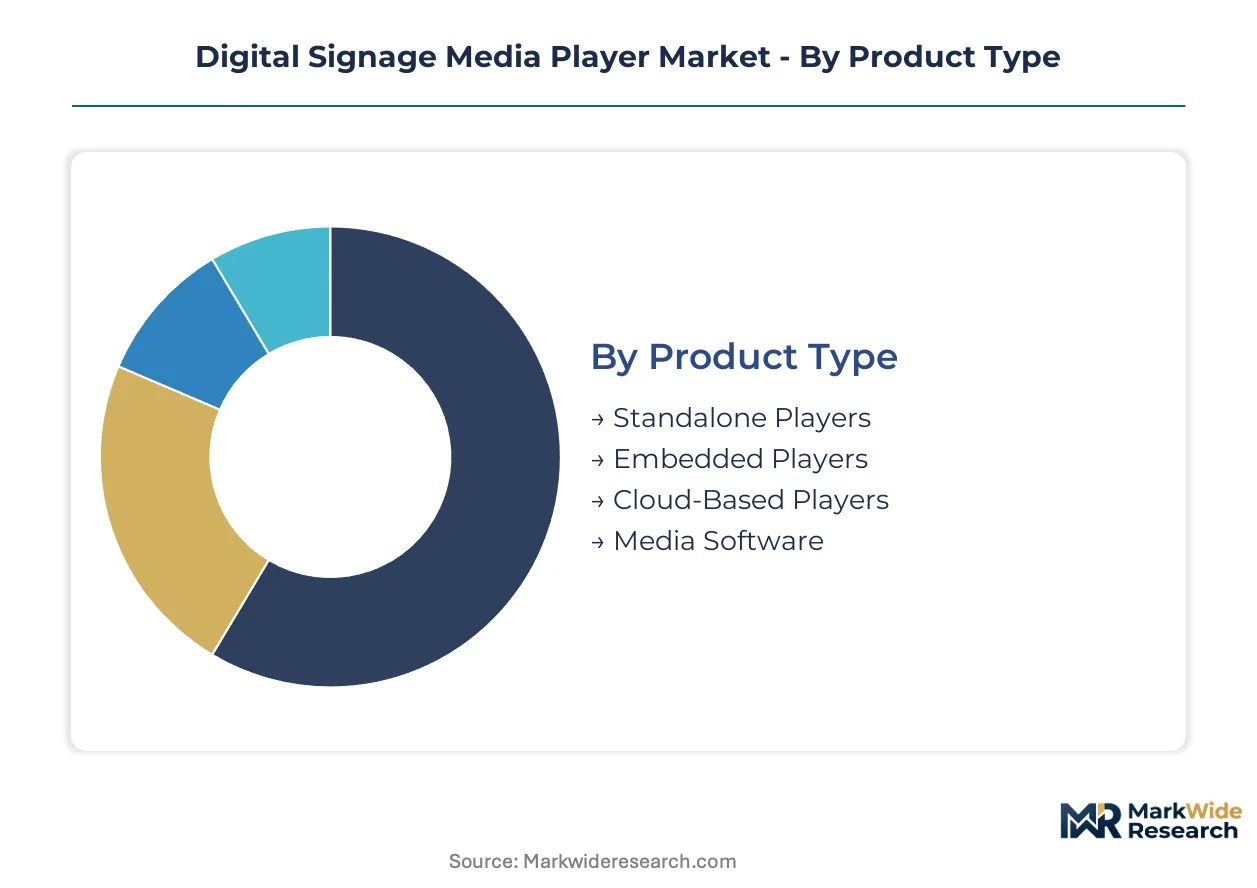
Segmentation in the digital signage media player market reveals how procurement priorities diverge across deployment environments. Technical specifications, thermal constraints, and content management architectures create distinct margin pools that reshape vendor positioning.
Product Type:
Margin concentration sits with integrated hardware-software bundles that reduce customer integration burden.
- Embedded Players:Fanless ARM-based units with solid-state storage and extended temperature tolerances dominate transportation and industrial deployments. China's tier-one transit authorities specify these for 24/7 outdoor reliability, with MIIT network licensing requirements adding procurement friction but locking in premium pricing.
- Cloud-Based Players:Thin-client architectures with persistent connectivity to SaaS content management platforms. United States retail chains favor these for centralized fleet control across thousands of endpoints, with FCC equipment authorization for Wi-Fi 6E modules becoming a competitive differentiator.
- Standalone Players:Self-contained x86 or ARM units with local storage and scheduling capability.
- Media Software:Decoding and rendering applications deployed on third-party hardware or virtualized environments.
The dominant share belongs to Embedded Players, while Cloud-Based Players are expanding most quickly as SaaS platforms displace on-premise infrastructure.
Technology:
Application requirements drive technology selection more than hardware compatibility, with brightness and form factor determining player specification.
- LED:Direct-view LED walls demand specialized players with synchronized multi-output cards and high refresh rates. United States sports venues and corporate lobbies deploy these for seamless large-format imagery, with thermal management becoming critical as pixel pitches tighten.
- LCD:Standard commercial panels requiring HDMI or DisplayPort connectivity with basic 4K decoding. Retail shelf-edge and point-of-sale networks across Germany and France concentrate volume here, with EU Ecodesign standby power limits below one watt reshaping power supply designs.
- OLED:Premium transparent and curved displays requiring precise timing controllers.
- Projection:Laser and lamp-based systems needing edge-blending and geometric correction support.
LED commands the highest average selling prices per unit, though LCD maintains volume leadership across installed base.
End User:
Procurement sophistication varies sharply, with enterprise accounts negotiating SaaS separately from hardware.
- Retail Stores:Dynamic pricing and inventory-linked content at shelf-edge and checkout. United States grocery and convenience chains deploy synchronized player arrays with real-time data feeds, with FCC authorization for cellular backhaul enabling rapid rollout without IT infrastructure.
- Transportation Hubs:IEC 60068-certified units for extended temperature and vibration tolerance. China's smart city mandates in Beijing, Shanghai, and Shenzhen specify outdoor-rated players with redundant connectivity, creating concentrated demand for industrial-grade embedded variants.
- Corporate Offices:Internal communication and visitor experience networks with centralized management.
- Educational Institutions:Campus-wide digital bulletin boards and emergency alert systems with budget constraints.
Retail Stores generate the largest absolute revenue, while Transportation Hubs show the steepest expansion trajectory driven by infrastructure mandates.
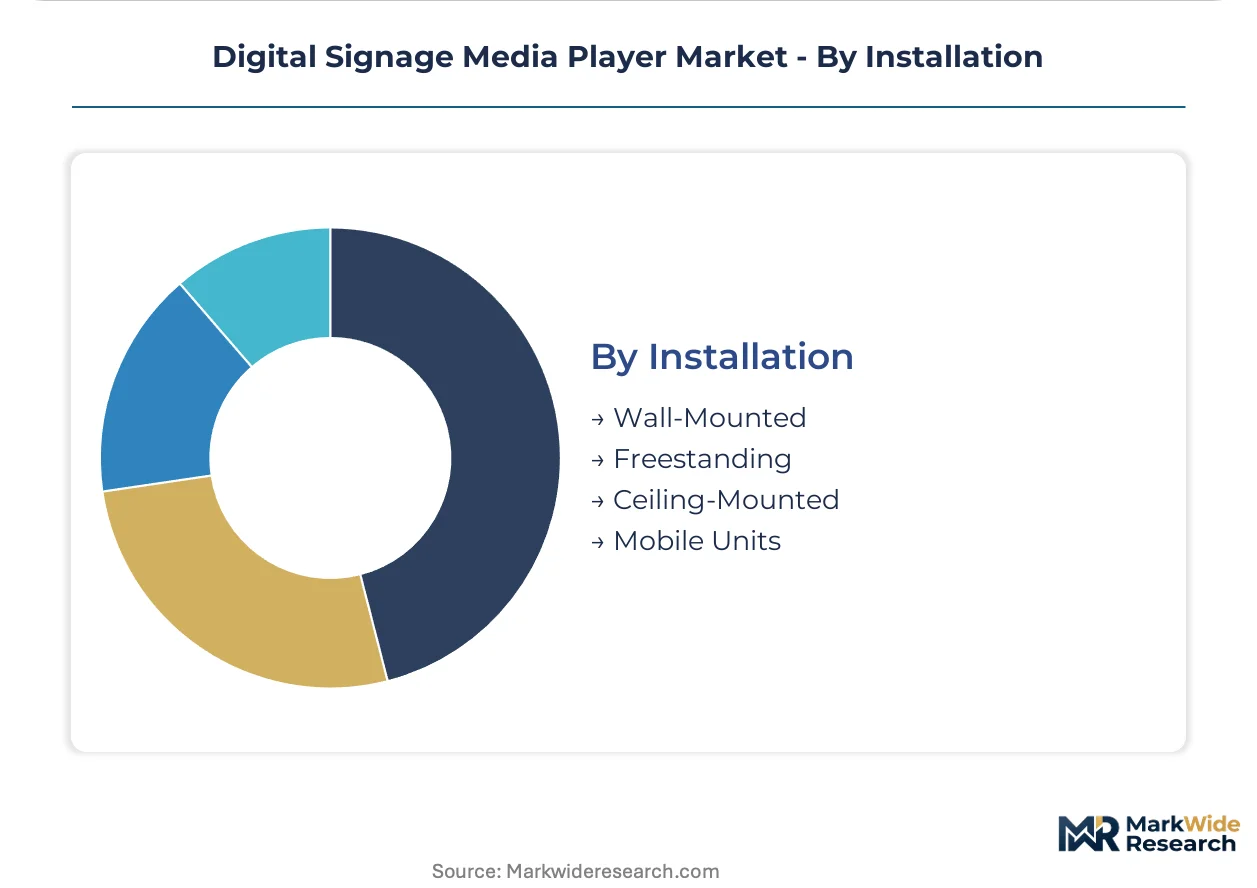
Installation:
Physical mounting constraints determine thermal design and connectivity architecture more than display technology.
- Wall-Mounted:Flush or articulating installations behind or adjacent to displays in retail and corporate environments. The largest installed base persists here, with EU CE marking and RoHS compliance requirements shaping hardware sourcing for European rollouts.
- Mobile Units:Battery-powered or PoE+ cart-based systems for experiential marketing and temporary events. Pop-up retail and trade show deployments in the United States and United Kingdom favor these for rapid reconfiguration without infrastructure investment.
- Freestanding:Kiosk and totem enclosures with integrated players in weatherized housing.
- Ceiling-Mounted:Projector and display suspensions requiring long cable runs and signal amplification.
Wall-Mounted retains structural dominance in unit terms, though Mobile Units are gaining share fastest in experiential and event-driven segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for ARM and x86 SoCs concentrates in Taiwan and South Korea, exposing hardware vendors to allocation volatility while procurement decisions in end markets diverge sharply by regulatory environment and infrastructure maturity.
United States
Retail chains deploy synchronized 4K and 8K player arrays for dynamic shelf-edge advertising with real-time inventory linkage. FCC equipment authorization requirements govern radio-enabled smart players, with streamlined Wi-Fi 6E certification pathways reducing time-to-market for new entrants. Procurement concentrates among grocery and convenience operators in the Southeast and Midwest, where cellular backhaul enables rapid rollout without dedicated IT infrastructure.
Germany
Corporate campus networks and retail environments drive demand for integrated display-and-player bundles with centralized management. EU Ecodesign Directive standby power limits below one watt force thermal architecture redesigns, with CE marking and RoHS substance restrictions shaping hardware sourcing strategies. Industrial clusters in Bavaria and North Rhine-Westphalia anchor premium fixed-installation deployments for automotive and manufacturing facility networks.
China
Smart city infrastructure mandates in tier-one cities require large-format digital transit installations with outdoor-rated embedded players. MIIT network access licensing for cellular-connected players adds four to six months to deployment timelines, locking in premium pricing for compliant vendors. Beijing, Shanghai, and Shenzhen specify IEC 60068-certified units with redundant connectivity for 24/7 public infrastructure reliability.
India
Tier-two municipal corporations under the Ministry of Housing and Urban Affairs mandate seek cost-optimized players for transit and civic information displays. BIS certification requirements for electronic products create compliance barriers for unvetted imports. Deployment activity concentrates in Maharashtra and Karnataka, where smart city mission funding supports digital signage networks for urban mobility hubs.
United Kingdom
Experiential marketing pop-ups and temporary event deployments favor mobile battery-powered units for rapid reconfiguration. GDPR compliance requirements influence data handling architectures for audience analytics-enabled players. London and Manchester anchor demand for computer vision-enabled pilots in retail and QSR segments, with edge inference capabilities collapsing separate server tiers for real-time content scheduling.
Digital Signage Media Player Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where purpose-built OS ecosystems compete against integrated bundle providers and industrial-grade specialists. The vendor base spans semiconductor-integrated conglomerates, embedded computing specialists, and AV-focused hardware pure-plays. Three archetypes dominate: premium fixed-installation providers with proprietary software stacks, scale manufacturers of display-integrated bundles, and ruggedized embedded specialists for transportation deployments. Competitive moves center on SaaS platform unbundling from hardware procurement and edge AI capability integration into decoding silicon.
Within the premium fixed-installation tier, BrightSign LLC exemplifies purpose-built ecosystem dominance through its dedicated operating system architecture. Samsung Electronics Co., Ltd. anchors the scale-driven integrated bundle segment, leveraging manufacturing breadth across corporate campus networks. Advantech Co., Ltd. occupies the industrial-grade embedded position, representing extended temperature tolerance specialization for transportation hub certifications. These three players collectively illustrate how technical specification depth, manufacturing scale, and environmental ruggedness define distinct competitive positions without overlapping core segments.
| Leading Market Players |
|---|
| BrightSign LLC |
| Advantech Co. Ltd. |
| AOPEN Inc. |
| Barco |
| 3M Company |
| Samsung Electronics Co., Ltd. |
| LG Electronics |
| Panasonic |
| Cisco Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
CE marking and RoHS substance restrictions gate both vendor qualification and price differentiation in European distribution, compressing margins for non-compliant inventory while rewarding certified suppliers with premium positioning. The interaction between regulatory compliance costs and procurement specifications creates tiered access where certification investment directly translates to pricing power across retail and corporate accounts.
Pricing Analysis
The EU's Ecodesign Directive dictates the pricing tier structure by mandating standby power limits below one watt, forcing redesign costs that stratify hardware across premium certified, standard transitional, and economy non-compliant tiers. Price differentiation hinges on IEC 60068 environmental certification grade and volume procurement scale, with transportation hub buyers least sensitive and tier-two municipal purchasers in India most price-constrained. Pricing pressure stems from general-purpose mini-PC substitution in single-screen corporate deployments, eroding dedicated player margins in low-complexity applications.
Supply Chain Analysis
Container availability fluctuations on the Asia-North America trade lane expose inventory carrying costs for vendors sourcing ARM and x86 SoCs from Taiwan and South Korea. Fabrication concentrates in these two jurisdictions, with memory modules and power management ICs drawing from the same foundry base, creating single-source vulnerability to allocation volatility. Distribution runs through AV integrators and direct enterprise procurement channels, with cloud-based player vendors increasingly bypassing traditional hardware distributors for SaaS-attached subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware procurement is decoupling from content management subscriptions, expanding recurring SaaS revenue pools faster than unit sales in North American and Western European enterprise accounts. This service-attach dynamic redefines margin capture away from one-time device transactions.
For Market Incumbents: Secure cloud-native platform integration to defend against SaaS-native entrants unbundling hardware from software procurement. Incumbents must accelerate IEC 60068 certification pipelines for transportation hub specifications while consolidating channel control through direct enterprise relationships, as mini-PC substitution threatens low-end corporate volumes. For New Entrants and Emerging Players: Differentiate on edge AI inference integration for real-time audience analytics, targeting United Kingdom retail and QSR pilots where computer vision capabilities collapse separate server tiers. White-space concentrates in India's tier-two smart city mandates, where cost-optimized embedded players with BIS certification meet municipal budget constraints through cellular-backhaul architectures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed embedded computing specialists possessing MIIT licensing moats in China but limited SaaS platform depth. Long-term viability favors vendors bridging hardware ruggedness with recurring software revenue; watch for inflection when cloud-native player penetration in retail accounts exceeds fixed-installation replacement rates.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Integration | Converges inference chips with media decoders for real-time demographic-responsive content scheduling. |
| SaaS Platform Unbundling | Separates hardware procurement from content management subscriptions, pressuring bundled-margin models. |
| IEC 60068 Certification Expansion | Unlocks transportation hub deployments in Beijing, Shanghai, and Shenzhen smart city mandates. |
| Wi-Fi 6E Module Authorization | FCC streamlined pathways reduce North American time-to-market for radio-enabled player rollouts. |
| Low-Power Architecture Redesign | Ecodesign Directive compliance below one watt standby maintains CE marking eligibility for EU distribution. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, EU Ecodesign compliance registries, and MIIT network access licensing records. Interviews with AV procurement officers, embedded systems engineers, content management platform executives, and transportation authority technology directors combined with customs trade data and SEC supplier filings. Bottom-up unit shipment estimates triangulate against top-down infrastructure spending projections across smart city mandates.
Segmentation dimensions modeled include product architecture type, display technology interface, end-user vertical, and installation configuration across the projection horizon. CAGRs derive from regression analysis of historical procurement cycles against regulatory compliance deadlines and infrastructure investment trajectories. Forecast inputs incorporate foundry capacity allocation patterns for ARM SoCs and cellular module certification timeline distributions.
The analysis sits within stated boundaries; outcomes outside sustained smart city funding continuity or foundry allocation stability would require recalibration. Forecasts assume Ecodesign Directive enforcement timelines and MIIT licensing durations persist without structural interruption. Recalibration cycles align with material shifts in semiconductor supply geography or regulatory compliance threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Egg Market
Others
Sound Reinforcement Market
Others
Gem Faceting Machine Market
Others
Solar Panel Testers Market
Others
Digital Supply Chain Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Global Automotive LED Lighting Market
Others
Residential Electrical Conduit Market
Others
Global Application Testing Services Market
Others
Smart Doorbell Market
Others
Internet Protocol Television (IPTV) Market
Others
Trusted Platform Module (TPM) Market
Others
Reef Aquarium Market
Others
Global Electronic Filters Market
Others
North America Forklift Truck Market
Others
Global Pregnancy Tracker Apps Market