
 Normal Saline for Parenteral Use Market | 2026-2036
Normal Saline for Parenteral Use Market Size, Share, and Industry Trends Forecast 2026-2036
Normal Saline for Parenteral Use Market Analysis
China is narrowing the supply-demand gap for normal saline through aggressive domestic capacity additions in Jiangsu and Sichuan provinces. Baxter leverages its integrated plasma-derived and pharmaceutical manufacturing footprint to sustain bulk supply contracts across North American hospital networks. Fresenius Kabi AG anchors European demand through specialized parenteral nutrition and fluid therapy portfolios. Kelun Group dominates volume production in Asia through scaled intravenous solution manufacturing.
Normal saline for parenteral use is a sterile, pyrogen-free sodium chloride solution typically formulated at 0.9% w/v concentration in water for injection, manufactured via aseptic processing in closed-system filling lines and used primarily for intravascular volume expansion, medication dilution, and electrolyte restoration. Isotonic saline occupies the largest share of hospital procurement budgets due to its universal compatibility with blood products and broad clinical indication base. Drug dilution applications within intravenous therapy are expanding fastest as biologic and oncology injectables require compatible diluents with demonstrated stability profiles.
The FDA enforces current Good Manufacturing Practice standards for large-volume parenterals through facility inspections and sterility assurance requirements, while the EMA's Annex 1 revision mandates enhanced contamination control strategies for aseptically processed saline products. China's NMPA aligns domestic saline registration with international ICH Q7 guidelines, raising barrier costs for smaller regional manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs to anticipate specification drift that could trigger reformulation or relabeling investments.
Market Dynamics
Hospital procurement consolidation across North American acute-care networks is compressing supplier margins while amplifying volume concentration among integrated delivery networks that negotiate multi-year saline supply agreements.
Growth Catalysts
- Surgical volume normalization:Operating room utilization rates in United States tertiary centers are rebounding toward pre-pandemic baselines, pulling demand for intraoperative fluid resuscitation and irrigation.
- EMA Annex 1 revision:Enhanced contamination control mandates for aseptically processed sterile pharmaceuticals are accelerating facility upgrades among European saline manufacturers seeking continued market access.
- Dialysis center expansion:Hemodialysis fluid requirements are scaling proportionally with clinic network growth in Germany and Japan, where aging demographics expand patient censuses.
Market Restraints
- Polymer resin cost volatility:Large-volume parenteral bag production depends on medical-grade PVC and polypropylene feedstocks subject to petrochemical price swings.
- Supply concentration in Jiangsu province:China's normal saline manufacturing clusters in eastern coastal regions create geographic vulnerability to regional logistics disruptions or environmental enforcement actions.
- Water-for-injection scarcity:Purified water infrastructure constraints at manufacturing sites limit production ramp rates during demand surges.
Strategic Opportunities
- Home infusion therapy penetration:United States reimbursement pathways for ambulatory parenteral administration are expanding addressable volume beyond traditional hospital settings.
- Biologic diluent compatibility testing:Oncology and immunology injectables require validated saline formulations with demonstrated stability profiles for monoclonal antibody reconstitution.
- India's PLI scheme for pharmaceuticals:Production-linked incentives for critical care medicines include intravenous fluids, attracting capacity investment toward export-oriented manufacturing.
Industry Challenges
- Aseptic processing technician shortage:Qualified personnel for cleanroom operations and environmental monitoring remain scarce relative to facility expansion timelines.
- Steam sterilization validation cycles:Terminal sterilization protocol updates require extended qualification periods that delay product release and compress working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Normal Saline for Parenteral Use Market |
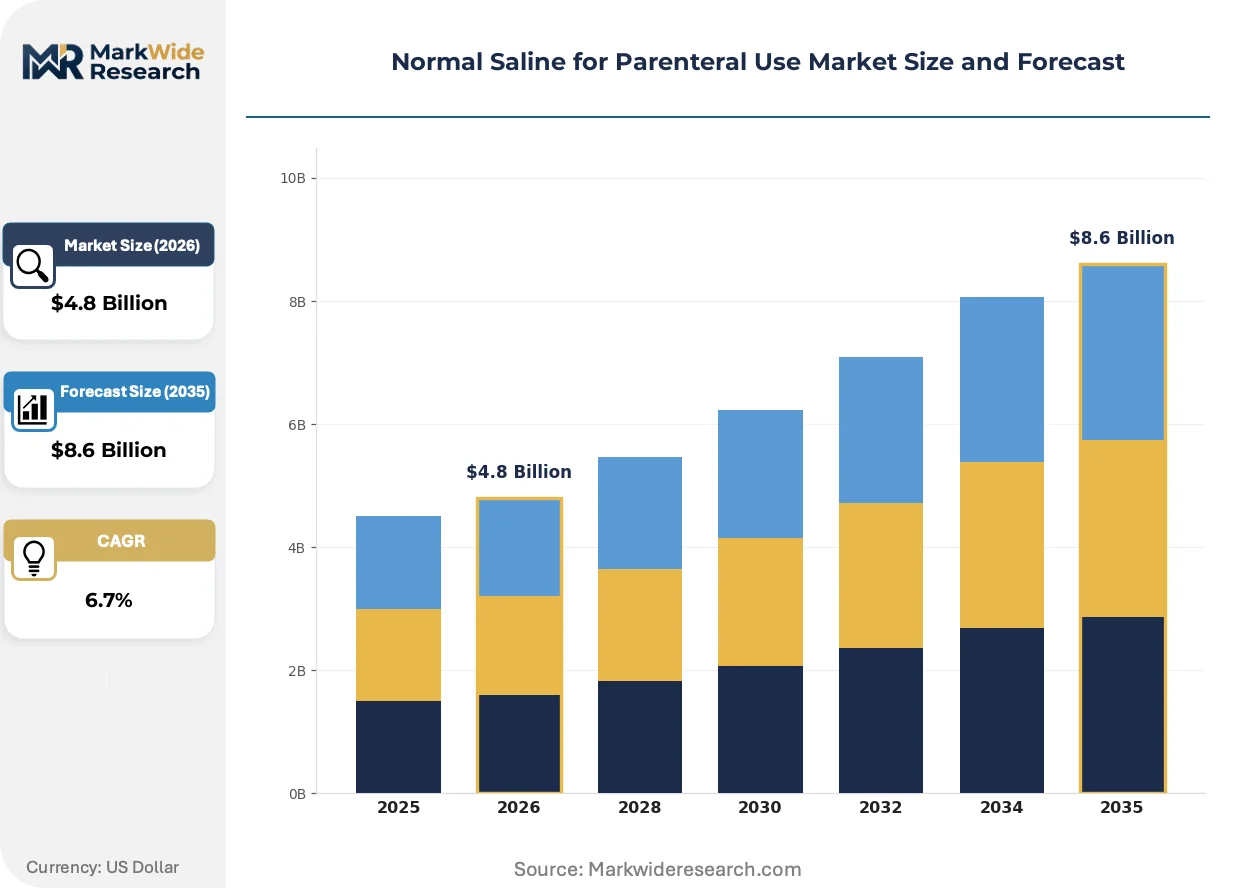
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic Saline, Hypertonic Saline, Hypotonic Saline, Buffered Saline, Preserved Saline Application: Intravenous Therapy, Wound Irrigation, Fluid Replacement, Electrolyte Balance, Drug Dilution End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Nursing Homes, Dialysis Centers Packaging Type: Glass Bottles, Plastic Bottles, PVC Bags, Polyethylene Bags, Ampoules |
| Companies Covered | B. Braun Melsungen AG, Double Crane Pharmaceutical, Baxter, Cisen Pharmaceutical Co. Ltd, Otsuka Pharmaceutical Co. Ltd, Kelun Group, SSY Group Limited, ICU Medical, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Normal Saline for Parenteral Use Market Emerging Trajectories
Manufacturing technology and regulatory architecture are converging to reshape how sterile saline is produced, tested, and distributed across healthcare supply chains.
Closed-system filling technology is migrating from legacy open-vessel aseptic processing to isolator-based containment systems that reduce human intervention and environmental contamination risk. European and North American manufacturers are retrofitting existing lines or constructing greenfield facilities around this architecture. The shift is compressing batch failure rates while raising capital intensity thresholds for new market entrants.
FDA's updated guidance on sterile pharmaceutical manufacturing tightens sterility assurance requirements for large-volume parenterals through enhanced environmental monitoring and media fill protocols. Facilities must demonstrate continuous viable particle control across filling operations. United States-based producers are responding with accelerated automation investments and real-time microbiological detection systems.
Consolidated procurement through group purchasing organizations is displacing hospital-level contracting for saline and other commodity parenterals. Integrated delivery networks in the United States are centralizing purchasing decisions and demanding guaranteed supply security with penalty clauses for stockouts. This behavioral shift favors manufacturers with multi-site production footprints and dedicated logistics contracts.
Normal Saline for Parenteral Use Market Segmentation
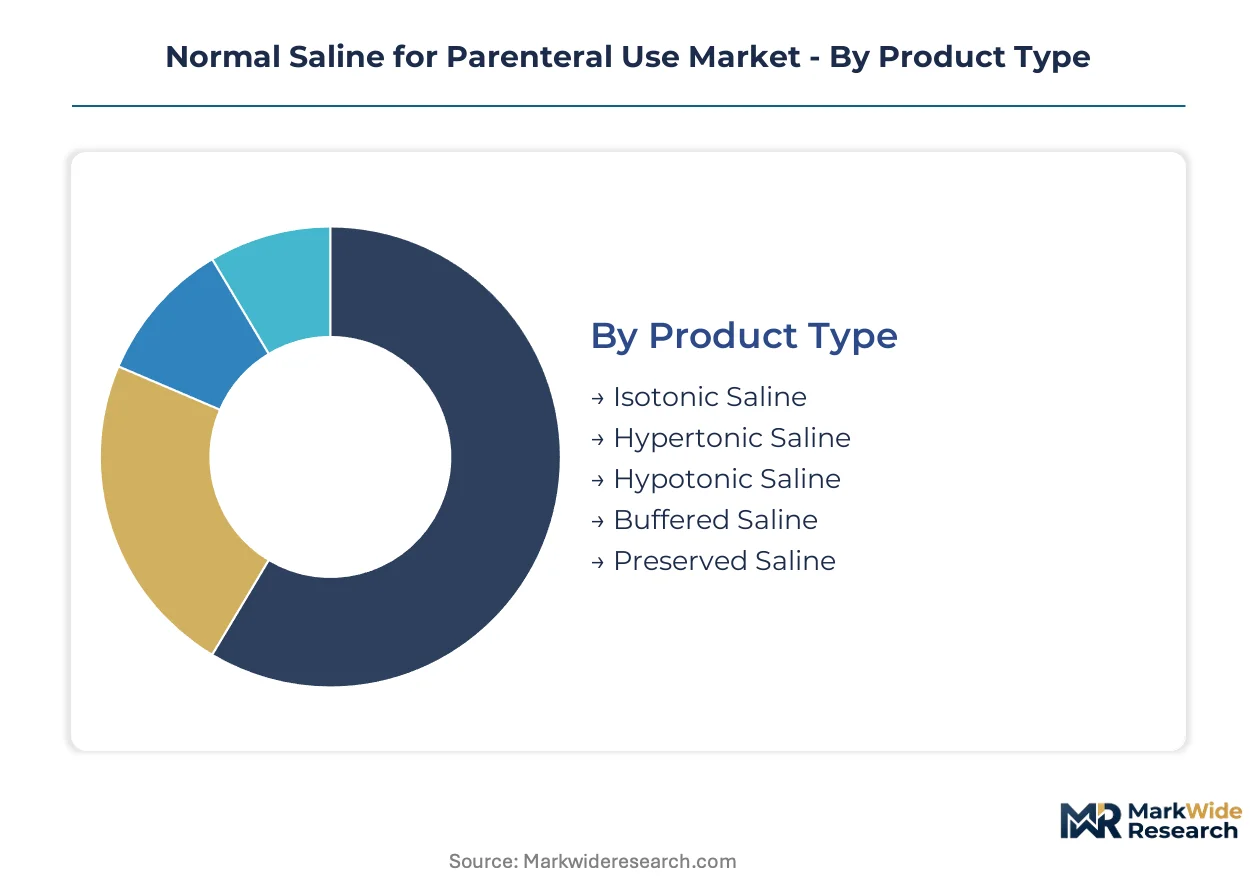
Saline segmentation reflects divergent technical specifications, sterility requirements, and supply chain economics that shape procurement patterns across acute-care networks. Product chemistry, clinical application, and packaging format each impose distinct manufacturing constraints and margin structures on producers.
Product Type:
After-sales service intensity varies sharply across saline formulations, with buffered and preserved variants requiring stability monitoring and lot-tracking support that commodity isotonic solutions do not demand.
- Isotonic Saline:The 0.9% sodium chloride standard dominates hospital formularies due to universal compatibility with blood products and minimal electrolyte disturbance risk. United States surgical networks pull the majority of volume for intraoperative fluid resuscitation and irrigation protocols.
- Buffered Saline:pH-stabilized formulations reduce vein irritation during prolonged infusions, attracting oncology and parenteral nutrition applications where patient comfort metrics influence contracting decisions. Demand concentrates in European tertiary centers adopting enhanced recovery after surgery pathways.
- Hypertonic Saline:Elevated sodium concentration (3-7.5%) serves hyponatremia correction and intracranial pressure management in neurocritical care units.
- Hypotonic Saline:Lower osmolarity solutions address pediatric fluid maintenance and specific electrolyte replacement protocols.
- Preserved Saline:Benzalkonium chloride or similar agents enable multi-dose vial applications in ophthalmic and respiratory device rinsing.
Isotonic saline holds the largest share; momentum sits with buffered formulations as patient-centered protocols gain adoption.
Application:
Cost tier stratification separates high-volume commodity uses from specialized applications commanding formulation premiums and technical support.
- Intravenous Therapy:Direct vascular administration for volume expansion and medication delivery represents the foundational use case, with demand scaling proportionally to surgical census and emergency department throughput. United States integrated delivery networks negotiate multi-year supply agreements covering this category.
- Drug Dilution:Biologic and oncology injectables require validated saline compatibilities with demonstrated stability profiles for monoclonal antibody reconstitution. This application commands the steepest expansion trajectory as injectable biologics proliferate in cancer and immunology protocols.
- Wound Irrigation:Sterile saline cleans traumatic and surgical wounds without cytotoxic effects, supporting emergency medicine and orthopedic procedure volumes.
- Fluid Replacement:Dehydration and hypovolemia correction in medical and surgical settings drives predictable baseline demand.
- Electrolyte Balance:Sodium restoration protocols in critical care and nephrology units require precise concentration control.
Intravenous therapy anchors procurement budgets; drug dilution applications are gaining share fastest.
End User:
Customer type determines order frequency, volume scale, and regulatory documentation requirements that differentiate service models.
- Hospitals:Acute-care facilities consume the majority of large-volume parenterals through centralized pharmacy operations, with procurement consolidating through group purchasing organizations that demand supply security guarantees. United States hospital networks are centralizing purchasing decisions and imposing penalty clauses for stockouts.
- Dialysis Centers:Hemodialysis fluid requirements scale with clinic network expansion in Germany and Japan, where aging demographics expand patient censuses and treatment frequency creates predictable recurring demand.
- Outpatient Clinics:Ambulatory settings require smaller package sizes and flexible delivery schedules.
- Ambulatory Surgical Centers:Same-day procedure volumes drive demand for pre-packaged irrigation and infusion kits.
- Nursing Homes:Long-term care hydration protocols generate steady but lower-margin volume.
Hospitals command the dominant share; dialysis centers show the strongest volume growth momentum.
Packaging Type:
Material selection trades off sterility assurance, environmental impact, and logistics efficiency in ways that reshape supplier competitive position.
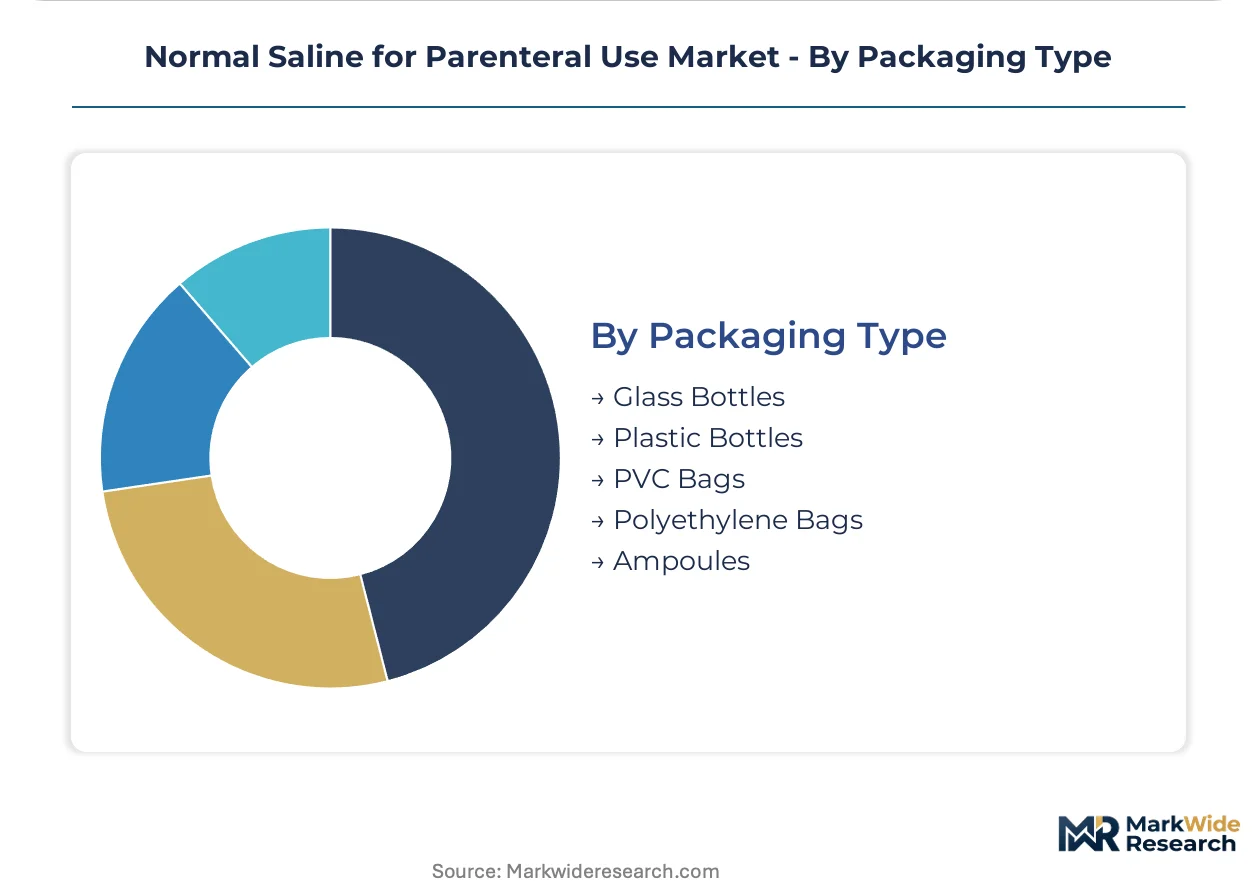
- PVC Bags:Flexible large-volume parenteral containers dominate fluid replacement applications due to collapsible design eliminating air embolism risk and established filling line infrastructure. Jiangsu and Sichuan province manufacturers in China have scaled production capacity for this format.
- Polyethylene Bags:PVC-free alternatives address environmental and patient safety concerns around plasticizer leaching, attracting European procurement specifications aligned with EMA contamination control mandates. German and French hospital networks are transitioning purchasing criteria toward these materials.
- Glass Bottles:Rigid containers persist in specific applications requiring terminal heat sterilization and extended shelf stability.
- Plastic Bottles:Semi-rigid formats serve irrigation and topical applications where puncture resistance matters.
- Ampoules:Single-dose glass units protect small-volume applications from contamination and overfill waste.
PVC bags retain the largest installed base; polyethylene alternatives are climbing the fastest as regulatory pressure mounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-volume parenteral manufacturing clusters in Jiangsu and Sichuan provinces anchor Asian supply capacity, while FDA and EMA compliance investments reshape facility economics in North America and Europe.
United States
Surgical volume recovery at tertiary centers and dialysis center network expansion drive bulk saline procurement through integrated delivery networks. FDA sterility assurance requirements for large-volume parenterals mandate enhanced environmental monitoring protocols that compress production timelines. Manufacturing concentration in Illinois and North Carolina supports multi-site supply security for hospital group purchasing organizations.
Germany
Aging demographics expand hemodialysis patient censuses, scaling fluid requirements proportionally with clinic network growth across Bavaria and North Rhine-Westphalia. EMA Annex 1 revision mandates contamination control upgrades that accelerate facility retrofits among domestic aseptic processors. The Frankfurt-Rhine-Main corridor hosts specialized parenteral nutrition manufacturing aligned with enhanced recovery after surgery pathways.
China
Domestic capacity additions in Jiangsu and Sichuan provinces narrow the supply-demand gap for normal saline through scaled intravenous solution manufacturing. NMPA alignment with ICH Q7 guidelines raises registration barriers for smaller regional manufacturers. Yangtze River Delta production clusters leverage integrated chemical-pharmaceutical infrastructure to serve hospital procurement consolidation across eastern coastal networks.
Japan
Hemodialysis fluid requirements scale with clinic expansion in Kansai and Chubu regions where treatment frequency creates predictable recurring demand. PMDA sterility standards for aseptically processed products enforce batch release protocols that extend qualification periods. Tokyo-Osaka manufacturing corridors concentrate parenteral fluid production capacity serving domestic acute-care networks.
India
Production-linked incentives for critical care medicines under the PLI scheme attract capacity investment toward export-oriented intravenous fluid manufacturing. CDSCO registration harmonization with international guidelines streamlines market access for qualified domestic producers. Gujarat and Maharashtra pharmaceutical corridors expand sterile formulation capacity targeting Middle East and African export markets.
Normal Saline for Parenteral Use Market Vendor Landscape
Integrated plasma-pharmaceutical conglomerates and specialized parenteral manufacturers split the market between bulk supply security and formulation specialization. Baxter and Fresenius Kabi anchor European and North American procurement networks through dedicated hospital contracts, while Kelun Group and SSY Group concentrate volume production in Asian manufacturing clusters. Three strategic archetypes dominate: diversified healthcare conglomerates with captive raw material sourcing, standalone parenteral specialists with aseptic processing expertise, and scaled generic injectable producers competing on volume throughput. Competitive positioning hinges on multi-site production footprints for supply security and isolator-based filling technology for sterility assurance.
Among diversified healthcare conglomerates, Baxter and Fresenius Kabi AG exemplify the integrated model combining plasma-derived and pharmaceutical manufacturing capabilities. Kelun Group occupies a position within the scaled generic tier, representing Chinese domestic capacity expansion through provincial manufacturing clusters. Fresenius Kabi anchors European demand through specialized fluid therapy portfolios, while Baxter sustains bulk supply contracts across North American hospital networks. ICU Medical and B. Braun Melsungen AG sit within the parenteral specialist archetype, emphasizing aseptic processing infrastructure and contamination control technologies. These groupings reflect divergent capital intensity thresholds and regulatory compliance burdens that stratify competitive position across regional markets.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Double Crane Pharmaceutical |
| Baxter |
| Cisen Pharmaceutical Co. Ltd |
| Otsuka Pharmaceutical Co. Ltd |
| Kelun Group |
| SSY Group Limited |
| ICU Medical |
| Fresenius Kabi AG |
| Others |
Supply Flow & Price Mechanics
Water-for-injection scarcity at manufacturing sites compresses production ramp rates during demand surges, widening the spread between premium isolator-based saline and commodity open-vessel products while forcing supply chain redesigns toward multi-site sourcing architectures.
Pricing Analysis
FDA sterility assurance requirements dictate the pricing tier structure across normal saline procurement, with isolator-based aseptic processing commanding premium positioning against legacy open-system manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates GPO-negotiated hospital contracts from dialysis center volume agreements and export-oriented bulk shipments. Cost compression in the standard tier is intensifying because Jiangsu province capacity additions are flooding Asian spot markets. Dialysis centers exhibit the highest price sensitivity due to predictable recurring volumes, while biologic diluent applications show inelastic demand for validated stability profiles.
Supply Chain Analysis
Export-control restrictions on isolator technology and real-time microbiological detection systems limit technology transfer to emerging manufacturers, concentrating advanced production capability among established North American and European facilities. Supply draws from China, Germany, and the United States, with Jiangsu and Sichuan provinces anchoring Asian volume, Bavaria and North Rhine-Westphalia serving European demand, and Illinois and North Carolina supporting North American networks. Raw material dependencies center on medical-grade PVC resin, polypropylene feedstocks, and pharmaceutical-grade sodium chloride. Single-source vulnerability runs through Jiangsu province clustering where environmental enforcement actions could disrupt regional output. Distribution runs through hospital group purchasing organizations and integrated delivery networks with penalty-clause contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-system filling technology migration represents a high-growth disruption as FDA and EMA contamination control mandates force facility retrofits across the manufacturing base, compressing batch failure rates while raising capital intensity thresholds for market participation.
For Market Incumbents: Harden isolator-based production footprints through multi-site redundancy investments in Illinois, North Carolina, and Bavaria to defend against Jiangsu province supply concentration risks. Deepen backward integration into pharmaceutical-grade sodium chloride sourcing to insulate margins from commodity volatility. Prioritize FDA pre-approval inspection readiness for sterility assurance protocol upgrades.
For New Entrants and Emerging Players: Establish a beachhead in India's export-oriented manufacturing corridor under the PLI scheme for critical care medicines, targeting Middle East and African markets with lower regulatory barriers. Exploit the aseptic processing technician shortage by developing automated cleanroom training programs as a service differentiator. Pursue biologic diluent compatibility testing partnerships with oncology injectable manufacturers.
For Investors and Strategic Acquirers: EMA Annex 1 revision reshapes the acquisition landscape toward isolator-equipped facilities with demonstrated environmental monitoring capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than volume scale alone. Target mid-cap parenteral specialists with FDA establishment inspection histories and multi-product aseptic lines. Monitor FDA warning letter issuance rates as the inflection indicator for competitive shakeout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | FDA sterility mandates force legacy facility upgrades to reduce human intervention contamination risk. |
| Multi-Site Production Footprint | Hospital GPO penalty clauses demand supply security through geographically distributed manufacturing. |
| Biologic Diluent Validation | Oncology monoclonal antibody compatibility testing commands formulation premiums in drug dilution. |
| PLI Scheme Capacity Buildout | India's production-linked incentives attract export-oriented intravenous fluid manufacturing investment. |
| Real-Time Microbiological Detection | Automated environmental monitoring systems compress batch release timelines for large-volume parenterals. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital pharmacy directors, GPO contracts managers, aseptic processing engineers, and dialysis center operations leads; and secondary validation against FDA 483 observations, EMA inspection reports, USP monograph revisions, and hospital procurement databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, end user, and packaging format dimensions.
Forecast inputs considered surgical volume recovery trajectories, dialysis center network expansion rates, and regulatory compliance investment cycles across the projection horizon. Segmentation modeling captured product chemistry variations, sterility requirement tiers, and regional manufacturing cluster economics. CAGRs derived from demand elasticity analysis and capacity utilization assumptions specific to aseptic processing constraints.
Sensitivities concentrate around FDA sterility guidance enforcement intensity, Jiangsu province environmental regulatory actions, and polymer resin price volatility. Forecasts reflect documented assumptions regarding surgical normalization timelines and biologic injectable proliferation rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market