
 Specimen Retrieval Market | 2026-2036
Specimen Retrieval Market Size, Share, and Industry Trends Forecast 2026-2036
Specimen Retrieval Market Intelligence
The European Union's Medical Device Regulation (MDR) is restructuring the cost-of-entry calculus for device manufacturers. This shift favors large-scale entities like Johnson & Johnson Services, Inc., which leverages its extensive regulatory infrastructure to navigate compliance. Medtronic sustains its market position through a diversified portfolio, while Applied Medical Resources Corporation differentiates with specialized, single-use retrieval systems.
Specimen retrieval systems are medical devices designed to safely contain and extract tissue samples during minimally invasive procedures. These systems, often made from tear-resistant, impermeable polymers, prevent the spillage of potentially cancerous cells within the body cavity, ensuring accurate pathological analysis. While hospitals are the dominant end-user, demand is accelerating in specialized clinics. The market for biopsy devices and specialized forceps shows higher growth than the more mature container segment.
Market access is governed by stringent regulatory frameworks, including the US FDA's 510(k) clearance pathway and China's NMPA approval process. The EU's Medical Device Regulation (MDR) imposes rigorous post-market surveillance requirements, influencing product lifecycle management. Consequently, manufacturers must balance investments in novel, tear-resistant materials against intense cost pressures from hospital procurement departments.
Market Dynamics
The specimen retrieval market is shaped by the fundamental tension between escalating regulatory demands for device safety and intense cost-containment pressures from hospital procurement systems. This dynamic forces manufacturers to innovate with advanced, tear-resistant materials while simultaneously optimizing production costs to remain competitive.
Growth Catalysts
- Minimally Invasive Surgery Volume:The expanding application of laparoscopic and robotic-assisted surgeries, particularly in oncology for precise tissue removal, directly fuels demand for reliable specimen retrieval systems to prevent intraoperative contamination.
- Healthcare Modernization in China:Rapid improvements in healthcare access and diagnostic capabilities across China are creating a concentrated demand hub, prompting both domestic and international manufacturers to focus on this geography.
- Advanced Polymer Science:Innovations in tear-resistant and impermeable polymer films enable the development of more secure and user-friendly retrieval bags, enhancing procedural safety and encouraging adoption in complex surgeries.
Market Restraints
- Hospital Procurement Pressure:Centralized purchasing departments in hospitals exert significant downward pressure on device pricing, limiting manufacturer margins and slowing investment in next-generation materials or features.
- Stringent Regulatory Pathways:The EU's Medical Device Regulation (MDR) and the US FDA's 510(k) clearance process create high-cost, lengthy barriers to entry, favoring established players with extensive regulatory affairs teams.
- Material Cost Volatility:The specialized, medical-grade polymers required for manufacturing high-performance retrieval bags are subject to supply chain disruptions and price fluctuations, impacting production costs and final pricing.
Strategic Opportunities
- Specialized Clinic Penetration:Developing single-use, procedure-specific kits tailored for the workflow of ambulatory surgical centers and specialized outpatient clinics opens a new channel beyond the mature hospital market.
- Robotic Surgery Integration:Designing retrieval systems specifically for compatibility with leading robotic surgery platforms presents an opportunity to capture value in a high-growth segment of minimally invasive procedures.
- Emerging Market Entry:Beyond China, healthcare infrastructure development in markets like Brazil and India presents long-term growth potential for manufacturers able to navigate local regulatory frameworks like ANVISA and CDSCO.
Industry Challenges
- Multi-Jurisdictional Compliance:Simultaneously managing compliance with disparate regulatory requirements from the FDA, EU MDR, and China's NMPA creates significant operational overhead and extends product development timelines.
- Material Sourcing and Qualification:Securing a consistent supply of qualified, biocompatible polymers that meet performance specifications without compromising on cost is a persistent supply chain challenge for manufacturers.
- Clinician Training and Adoption:Ensuring proper technique and usage of new retrieval systems to prevent bag rupture or spillage requires significant investment in clinician training and education, slowing adoption of novel designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specimen Retrieval Market |
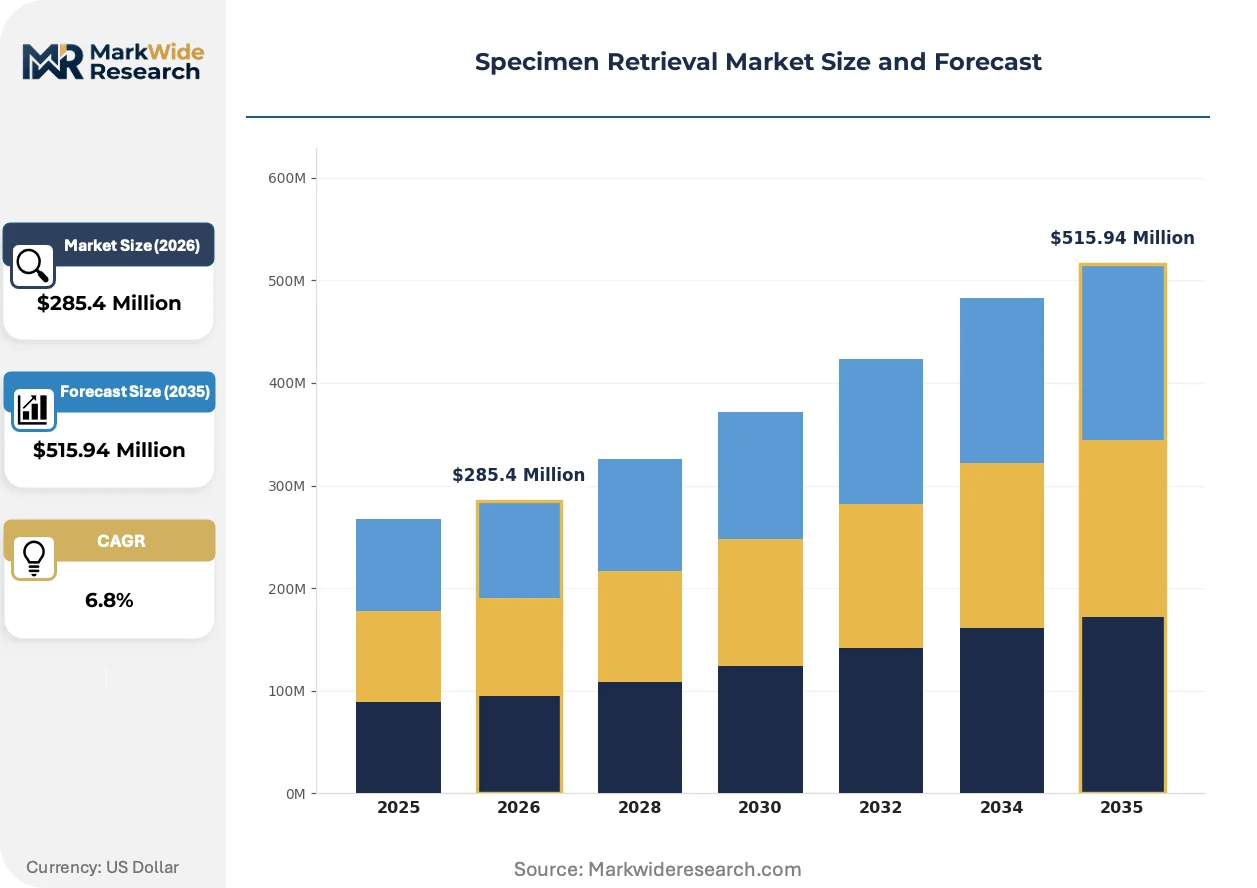
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Devices, Forceps, Syringes, Containers End User: Clinics, Laboratories, Hospitals, Research Institutions Technology: Endoscopic, Surgical, Imaging-Directed, Manual Application: Pathology, Oncology, Hematology, Microbiology |
| Companies Covered | Johnson & Johnson Services, Inc., Teleflex Incorporated, Applied Medical Resources Corporation, Medtronic, CONMED Corporation, B. Braun SE, Cooper Surgical, Inc., Genicon, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specimen Retrieval Market Strategic Shifts & Innovations
The market's evolution is driven by a concurrent push for enhanced procedural safety and greater material performance. This movement is influenced by stricter regulatory oversight and a clinical demand for devices that guarantee specimen integrity for accurate pathological analysis, especially in cancer-related surgeries.
Advanced polymer composites featuring enhanced tear resistance and impermeability are a key product evolution. Surgical teams in oncology and gynecology are rapidly adopting these next-generation materials to minimize the risk of cell spillage during tissue extraction. This focus on material science is overtaking older polyurethane films, establishing a new performance standard for devices used in critical oncological procedures.
The European Union's Medical Device Regulation (MDR) is a defining regulatory shift with global impact. It mandates more rigorous clinical evidence and continuous post-market surveillance for all medical devices, including specimen retrieval systems. This regulation most affects manufacturers exporting to the EU, forcing a complete overhaul of technical documentation and quality management systems to maintain market access.
A notable behavioral shift is occurring as purchasing decisions decentralize away from large hospitals toward specialized ambulatory surgical centers. These outpatient facilities prioritize procedure-specific, single-use kits over the bulk, non-sterile components favored by large hospital systems, disrupting established distribution channels. This trend is most prominent in the United States, where the volume of outpatient oncologic and gynecologic procedures continues to climb.
Specimen Retrieval Market Segmentation
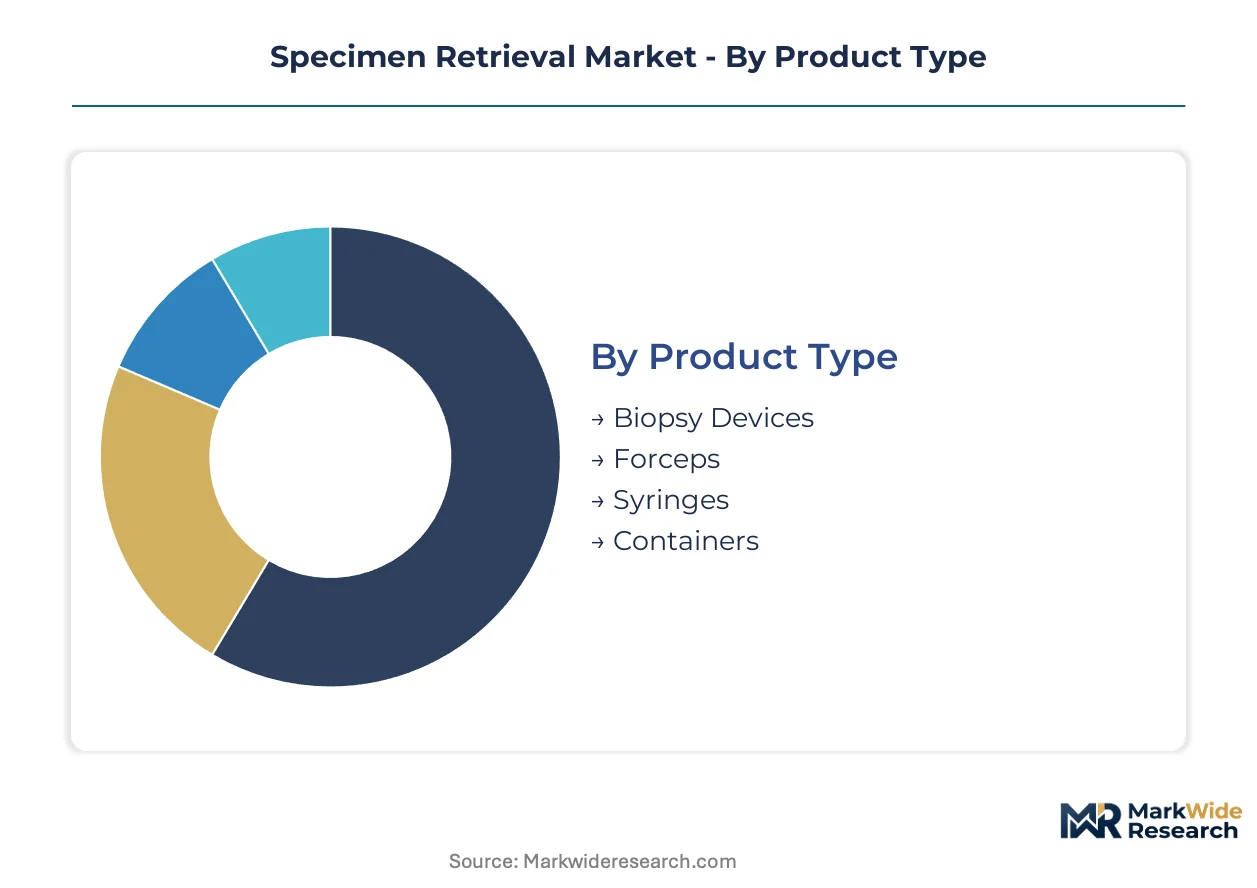
The specimen retrieval market's diverse segmentation reflects the varied clinical needs and procedural contexts for tissue extraction. Understanding these distinct segments is crucial for manufacturers to align product development with specific end-user requirements and regulatory pathways. This granular view helps identify areas of concentrated demand and technological innovation.
Product Type:
Segments within product type vary significantly in their capital intensity, with complex devices demanding substantial upfront investment in design and manufacturing.
- Biopsy Devices:These instruments are specifically engineered to extract tissue samples for diagnostic analysis, often incorporating advanced cutting mechanisms for precise collection. Demand concentrates in oncology, where accurate tissue analysis is paramount for treatment planning.
- Forceps:Specialized forceps facilitate the grasping and removal of tissue during minimally invasive procedures, requiring high-grade materials for strength and sterility. The expanding volume of laparoscopic surgeries in China fuels demand for these versatile tools.
- Syringes:Syringes are utilized for aspiration biopsies, drawing fluid or small tissue fragments from target areas with minimal invasiveness.
- Containers:These impermeable bags or receptacles safely enclose retrieved specimens to prevent spillage and contamination during removal from the body cavity.
Most installed capacity flows through Containers. Expansion is steepest in Biopsy Devices.
End User:
The end-user segmentation highlights where the highest volume of specimen retrieval procedures are performed, influencing procurement scale and product customization.
- Hospitals:Hospitals represent the primary end-users, integrating specimen retrieval systems into a wide array of surgical and diagnostic departments. Their centralized procurement systems drive demand for cost-effective, high-volume solutions.
- Clinics:Specialized clinics, including ambulatory surgical centers, are rapidly increasing their utilization of specimen retrieval devices for outpatient procedures. This shift prioritizes single-use, procedure-specific kits that streamline workflow.
- Laboratories:Clinical laboratories use retrieval systems for post-procedural handling and preparation of specimens for pathological examination.
- Research Institutions:Academic and private research institutions employ these systems for tissue collection in studies related to disease progression and therapeutic development.
Hospitals continue to dominate market share. Clinics are gaining traction rapidly.
Technology:
Technology segments are differentiated by their primary application method, indicating the specific procedural environments where devices are deployed.
- Endoscopic:Endoscopic retrieval systems are designed for use within the confines of endoscopes, requiring flexible yet robust materials for navigating complex anatomical pathways. Adoption is accelerating in gastrointestinal and pulmonary diagnostics.
- Surgical:Surgical retrieval technology encompasses devices used directly during open or minimally invasive surgical interventions for tissue extraction. The increasing sophistication of robotic-assisted surgery drives demand for compatible systems.
- Imaging-Directed:These technologies utilize real-time imaging modalities like ultrasound or CT scans to guide precise specimen collection from target lesions.
- Manual:Manual retrieval involves direct physical manipulation and extraction of tissue samples, often employed in simpler or less invasive procedures.
Surgical technologies drive significant revenue. Endoscopic applications are experiencing robust expansion.
Application:
The application segments reflect varying levels of maturity in their adoption of advanced specimen retrieval techniques, from established diagnostic pathways to emerging specialized fields.
- Oncology:Oncology represents a critical application, where precise and contamination-free tissue retrieval is essential for cancer diagnosis and staging. The rising global incidence of cancer fuels consistent demand for high-integrity systems.
- Pathology:Pathology serves as the foundational application, encompassing all diagnostic analyses performed on retrieved tissue samples to identify diseases. This segment benefits from continuous innovation in specimen integrity and transport.
- Hematology:Hematology applications involve the collection of blood and bone marrow samples for diagnosing blood disorders and related conditions.
- Microbiology:Microbiology utilizes specimen retrieval for collecting samples from infections, enabling identification of pathogens and guiding antimicrobial therapy.
Pathology remains a foundational application. Oncology-related procedures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled medical workforce across developed nations drives the global demand for advanced specimen retrieval systems. These professionals require precision instruments for complex diagnostic and surgical procedures. Regulatory harmonization efforts also influence market dynamics, particularly for manufacturers operating across multiple jurisdictions.
United States
The high volume of minimally invasive surgeries, especially in oncology, fuels consistent demand for advanced specimen retrieval devices. The US FDA's 510(k) clearance pathway governs market entry for most devices, requiring substantial clinical evidence. Medical device manufacturing clusters in Massachusetts and California continually innovate product design and material science.
Germany
Germany's strong emphasis on medical device quality and patient safety supports the adoption of high-performance retrieval systems. Compliance with the EU's Medical Device Regulation (MDR) is paramount for market access and product registration. Medical technology hubs in Bavaria and Baden-Württemberg lead research into new polymer composites and surgical integration.
China
Rapid improvements in healthcare access and diagnostic capabilities across China are creating a concentrated demand hub for specimen retrieval systems. The NMPA approval process is a critical gateway for both domestic and international manufacturers. Expanding diagnostic capabilities in the Yangtze River Delta and Pearl River Delta drive significant market growth.
Japan
Japan's aging population and advanced healthcare infrastructure necessitate precise diagnostic tools, increasing the need for sophisticated specimen retrieval. The PMDA approval process ensures stringent quality and safety standards for medical devices. Precision manufacturing facilities in the Tokyo metropolitan area and Kansai region develop highly specialized instruments.
Brazil
Healthcare infrastructure development and a growing patient population contribute to rising demand for medical devices, including specimen retrieval systems. ANVISA approval is a mandatory regulatory requirement for all medical products entering the Brazilian market. Growing medical device manufacturing capabilities in São Paulo and Minas Gerais address local market needs.
Specimen Retrieval Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the specimen retrieval market. The market structure exhibits a tiered approach, with large entities dominating established segments and smaller innovators carving out niche areas. Strategic archetypes include broad-portfolio surgical suppliers and specialized single-use device manufacturers. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach.
Among the diversified medical technology conglomerates, Johnson & Johnson Services, Inc. and Medtronic exemplify established market leadership through extensive product portfolios and global distribution networks. These companies leverage their significant regulatory infrastructure to navigate complex compliance frameworks, particularly the EU's Medical Device Regulation. Applied Medical Resources Corporation, conversely, represents a specialist archetype, focusing on innovative single-use retrieval systems. This company differentiates through its specialized offerings, which cater to specific procedural requirements. These entities anchor different segments of the market, catering to varied clinical needs and procurement preferences across global geographies.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Teleflex Incorporated |
| Applied Medical Resources Corporation |
| Medtronic |
| CONMED Corporation |
| B. Braun SE |
| Cooper Surgical, Inc. |
| Genicon |
| KARL STORZ SE & Co. KG |
| Others |
Cost & Logistics Intelligence
Premium-grade, highly certified specimen retrieval systems diverge significantly from standard, cost-effective options, shaping both pricing and supply chain configurations. Manufacturers of advanced devices invest in specialized materials and rigorous testing, allowing for higher price points and necessitating complex, secure supply networks for critical components.
Pricing Analysis
Bundled procedural kits, combining retrieval devices with complementary instruments, often command higher prices than unbundled components. Per-unit transactional pricing dominates the market, with some larger hospital systems securing contract-based long-term agreements. EU MDR compliance level and material tear resistance are primary price differentiation drivers. Downward pricing pressure stems from hospital procurement departments' cost-containment mandates. Specialized clinics prioritize workflow efficiency and device reliability, making them less price-sensitive than centralized hospital purchasing units.
Supply Chain Analysis
China's NMPA approval process and "Made in China" initiatives increasingly influence sourcing decisions for manufacturers targeting the Asian market. Geographic supply concentration for medical-grade polymers and specialized device components draws from China, Germany, and the United States. Raw material dependencies include high-strength polymer films and sterile packaging. Material cost volatility for specialized polymers presents a structural supply chain risk. Direct sales forces and third-party distributors manage downstream channels to hospitals, clinics, and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specimen retrieval market acts as a stable compounder, driven by the expanding volumes of minimally invasive surgeries globally. This consistent demand underpins long-term growth for well-positioned participants.
For Market Incumbents:To counter new entrant innovation in specialized segments and intense cost pressure from procurement, incumbents must continuously invest in advanced polymer R&D for superior tear resistance. Expanding global regulatory affairs teams is crucial for navigating multi-jurisdictional compliance, particularly for EU MDR and NMPA requirements. Leveraging established distribution networks can reinforce market presence against emerging competitors.
For New Entrants and Emerging Players:Capture white-space opportunities by focusing on niche segments like robotic surgery integration and specialized clinic penetration. Ambulatory surgical centers in the United States represent a highly penetrable end-user segment. A strong go-to-market angle involves developing procedure-specific, single-use kits with integrated training modules to streamline clinical workflow and enhance adoption.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory complexity and the need for scale to absorb compliance costs are high. The market offers consistent, albeit moderate, growth driven by essential diagnostic needs over the next decade. Acquisition targets should include innovators in advanced material science or companies with strong market access in emerging economies like China. Increased M&A activity among mid-sized players seeking regulatory expertise or specialized product lines is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Expansion | Navigating EU MDR and NMPA approvals ensures market access and compliance. |
| Advanced Polymer R&D | Developing superior tear-resistant materials enhances product safety and clinical adoption. |
| Robotic Surgery Compatibility | Designing systems for robotic platforms captures value in a high-growth surgical segment. |
| Emerging Market Entry | Establishing local manufacturing or distribution in China addresses concentrated demand. |
| Specialized Kit Development | Tailoring single-use kits for clinics streamlines workflow and expands end-user reach. |
Research Approach
Bottom-up hospital and clinic procurement modeling reconciled against top-down polymer and device manufacturing output tracking forms the analytical core of this study. Primary interviews with surgical oncologists, hospital procurement managers, medical device engineers, and regulatory affairs specialists provided critical insights. Secondary validation drew from FDA 510(k) clearances, EU MDR notified body reports, NMPA device approvals, and medical journal publications.
Historical trendline analysis, regression modeling, and scenario planning underpin the forecast framework. Product type, end-user, technology, application, and geographic regulatory frameworks are key segmentation dimensions modeled. Compound annual growth rates are calculated using historical trends and projected market drivers across the analysis window. Minimally invasive surgery procedure volumes and cancer incidence rates are critical industry-specific forecast inputs.
Regulatory policy shifts, material supply chain disruptions, and changes in surgical practice are the dominant revision risks for market projections. Forecasts reflect current market dynamics and expected technological advancements within these boundaries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Handpiece Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Water Flosser Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
IOL Delivery Systems Market