
 Global Biomedical Sensor Market | 2026-2036
Global Biomedical Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomedical Sensor Market Foresight
Sensor foundry capacity in Taiwan and South Korea is realigning toward medical-grade MEMS wafer output. Texas Instruments leverages its analog front-end portfolio to anchor glucose monitoring subsystem design. STMicroelectronics sustains European hospital procurement relationships through ISO 13485-certified fabrication.
Biomedical sensors are transducers that convert physiological signals—electrical, optical, thermal, or mechanical—into quantifiable data, typically operating at microampere-level power budgets and millivolt signal resolutions for real-time patient monitoring. Electrochemical sensors dominate glucose monitoring applications due to enzymatic specificity and decades of manufacturing refinement, while wearable technology is displacing clinic-bound devices as skin-interfaced flexible electronics mature. Optical sensors occupy premium positions in pulse oximetry and photoplethysmography where LED-photodiode arrays achieve clinical-grade accuracy at consumer price points.
FDA 510(k) pathways and EU MDR technical documentation requirements are extending validation timelines for new entrants, compressing effective patent windows. China's NMPA has harmonized priority review channels with international standards, accelerating market access for multinationals with existing FDA or EMA approvals. Stakeholders must monitor reimbursement code expansions for remote patient monitoring in the United States and Germany, as these determine viable addressable markets for wireless sensor platforms.
Market Dynamics
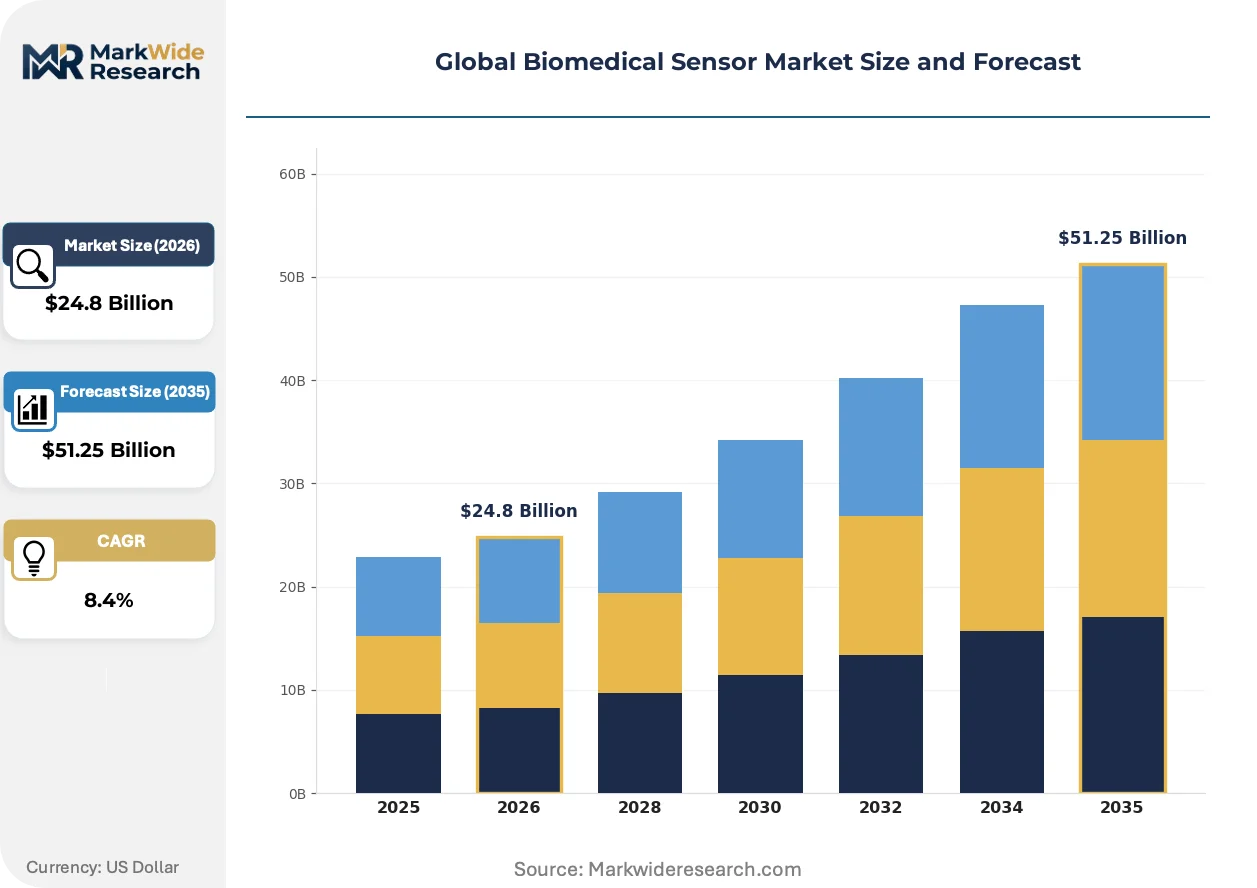
Continuous glucose monitoring systems are compressing hospital procurement cycles as Germany and Japan accelerate ward-level deployment, while FDA 510(k) pathway modifications and EU MDR recertification timelines force sensor manufacturers to front-load validation spending before revenue recognition.
Growth Catalysts
- Hospital digitization mandates:China's tier-one cities are expanding public hospital budgets for real-time patient monitoring infrastructure, pulling demand for wireless sensor platforms into centralized procurement frameworks.
- EU MDR harmonization:The Medical Device Regulation's technical documentation requirements have created a single certification pathway that accelerates cross-border hospital procurement across European member states.
- MEMS foundry realignment:Taiwan and South Korean fabrication facilities are converting automotive sensor capacity toward medical-grade wafer output, expanding supply availability for electrochemical and optical sensor architectures.
Market Restraints
- Validation cost concentration:ISO 13485-certified fabrication requires multi-year capital commitments that lock smaller sensor developers out of hospital-grade supply chains.
- Regulatory friction:EU MDR technical documentation timelines extend 18-24 months beyond legacy CE marking windows, compressing effective patent protection for novel transducer designs.
- Enzyme supply vulnerability:Electrochemical glucose sensors depend on glucose oxidase production concentrated in specific bioreactor facilities, creating input cost volatility.
Strategic Opportunities
- Skin-interfaced flexible electronics:Wearable form factors that displace clinic-bound devices are opening outpatient and home-monitoring revenue pools previously inaccessible to wired sensor systems.
- Remote patient monitoring codes:Reimbursement expansion for wireless platforms in the United States and Germany is creating addressable market segments outside traditional hospital capital budgets.
- Optical-thermal convergence:LED-photodiode arrays combined with micro-thermopiles are enabling multi-parameter monitoring from single wearable units, differentiating premium product tiers.
Industry Challenges
- Systems integration complexity:Analog front-end subsystems from legacy semiconductor suppliers require custom calibration protocols that extend hospital IT deployment timelines.
- Biocompatibility certification bottlenecks:ISO 10993 testing for skin-contact materials creates 12-18 month delays between prototype completion and commercial sampling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomedical Sensor Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical Sensors, Optical Sensors, Piezoelectric Sensors, Thermal Sensors, Magnetic Sensors Application: Glucose Monitoring, Blood Pressure Measurement, Heart Rate Tracking, Respiratory Analysis, Neurological Assessment End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Healthcare, Fitness Centers Technology: Microelectromechanical Systems, Nanotechnology Sensors, Wearable Technology, Wireless Sensors, Implantable Devices |
| Companies Covered | Analog Devices, Honeywell International, STMicroelectronics, GE Healthcare, NXP Semiconductors, Medtronic, Abbott Laboratories, F. Hoffmann-La Roche, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomedical Sensor Market Shifts & Advancements
Sensor architecture is fragmenting into modular subsystems that separate signal acquisition, processing, and transmission functions, enabling faster regulatory recertification and supply chain risk distribution.
Flexible printed circuit assemblies paired with micro-needle electrode arrays are modularizing glucose monitoring hardware into skin-patch formats that bypass traditional finger-prick workflows. Hospital systems in Japan are piloting these platforms for perioperative glycemic control. The decomposition of sensor systems into interchangeable analog front-end, power management, and wireless communication blocks is compressing OEM development cycles from 36 months to 18 months.
FDA 510(k) pathway modifications now require predicate device comparisons for software-as-medical-device components, extending documentation burdens for AI-enabled signal processing algorithms. This regulatory friction is concentrating development resources among firms with existing 510(k) clearances. Wearable sensor manufacturers are responding by segregating hardware and software regulatory submissions to parallelize approval timelines.
Hospital procurement departments are unbundling sensor hardware from data analytics subscriptions, forcing vendors to price transducers as capital equipment while monetizing longitudinal patient data separately. German hospital networks pioneered this split-contracting model. Tier-one Chinese public hospitals are now adopting similar structures, compressing upfront equipment margins while expanding recurring revenue pools for cloud-connected monitoring platforms.
Global Biomedical Sensor Market Segmentation
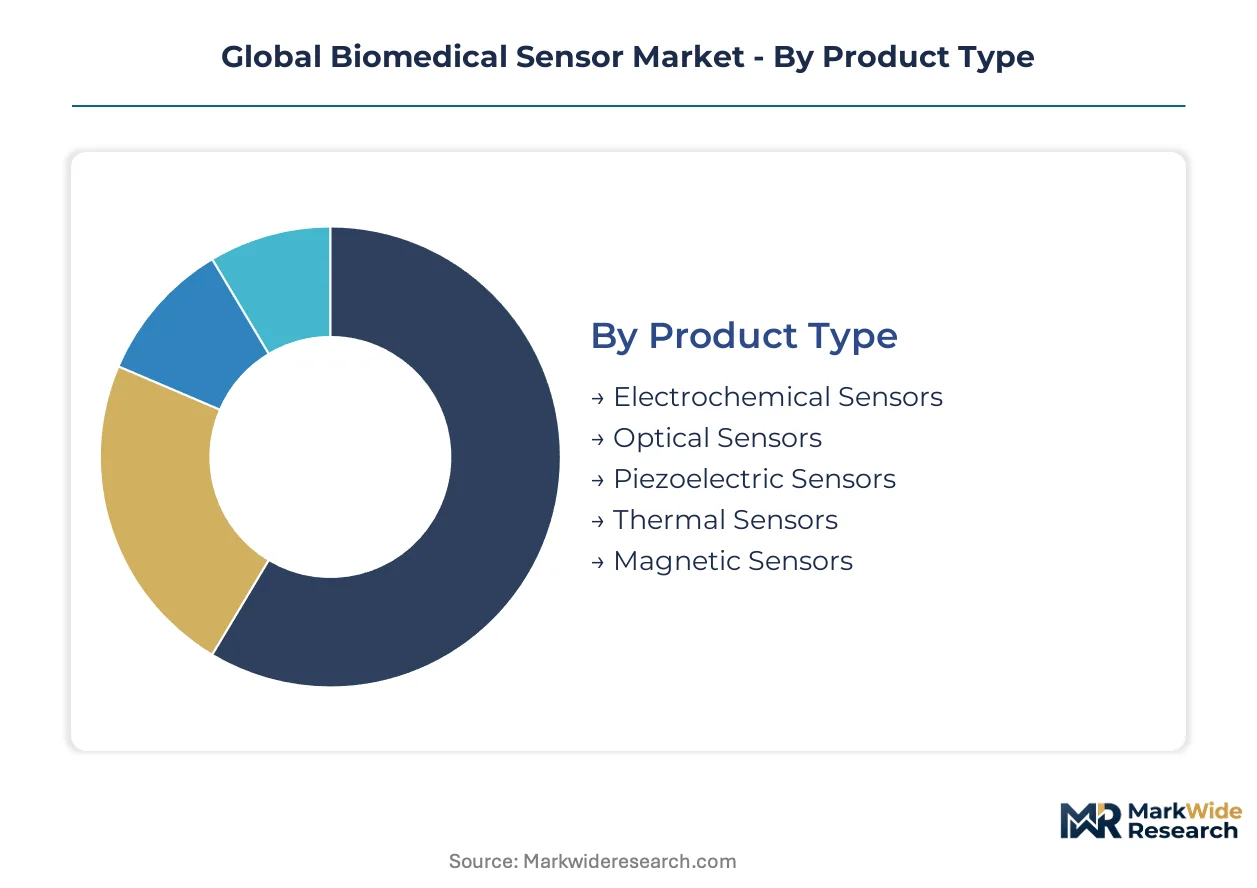
Biomedical sensor architectures fragment across transduction principles, clinical use cases, and deployment settings. Each segmentation axis carries distinct regulatory burdens, margin profiles, and supply chain requirements that determine viable competitive positioning.
Product Type:
Customization intensity varies from enzymatic specificity in electrochemical designs to standardized photodiode arrays in optical platforms.
- Electrochemical Sensors:Enzyme-based transducers exploit glucose oxidase catalytic reactions to generate microampere-level current signals proportional to analyte concentration. Demand concentrates in Germany and Japan where hospital procurement of continuous glucose monitoring systems is accelerating ward-level deployment.
- Optical Sensors:LED-photodiode architectures achieve clinical-grade pulse oximetry and photoplethysmography through near-infrared tissue penetration algorithms. China's tier-one cities are pulling premium optical modules into public hospital digitization frameworks as bedside monitoring infrastructure expands.
- Piezoelectric Sensors:Quartz crystal microbalances detect mass changes from biomolecular binding events in diagnostic assays.
- Thermal Sensors:Micro-thermopile arrays measure metabolic heat flux for non-invasive glucose correlation studies.
- Magnetic Sensors:Giant magnetoresistance elements track magnetic nanoparticle labels in immunoassay workflows.
Most installed capacity flows through electrochemical platforms. Expansion is steepest in optical sensors.
Application:
Reimbursement code availability determines addressable market depth across clinical indications.
- Glucose Monitoring:Enzymatic electrochemical strips and factory-calibrated continuous monitors dominate outpatient glycemic management. FDA 510(k) pathway modifications and EU MDR recertification timelines are compressing product development cycles for next-generation interstitial fluid sensors.
- Blood Pressure Measurement:Oscillometric cuff sensors and arterial tonometry arrays serve hypertension management protocols. Home healthcare channels in the United States are expanding reimbursement for remote patient monitoring codes that cover wireless blood pressure platforms.
- Heart Rate Tracking:Photoplethysmography dominates consumer wearables while ECG patches serve clinical arrhythmia detection.
- Respiratory Analysis:Capnography and spirometry sensors support perioperative ventilation management.
- Neurological Assessment:Electrode arrays and accelerometer fusion enable seizure detection and sleep staging.
Glucose monitoring commands the deepest installed base. Neurological assessment is gaining share fastest.
End User:
Procurement sophistication separates centralized hospital tenders from direct-to-consumer retail channels.
- Hospitals:ISO 13485-certified fabrication and biocompatibility documentation requirements dominate capital equipment purchasing. German hospital networks pioneered unbundled contracting that separates sensor hardware from data analytics subscriptions.
- Diagnostic Laboratories:High-throughput analyzers demand precision-calibrated sensor modules with traceable quality control. Taiwan and South Korean MEMS foundries are realigning capacity toward medical-grade wafer output to serve laboratory instrument OEMs.
- Research Institutes:Custom sensor development for preclinical studies tolerates longer validation timelines.
- Home Healthcare:Consumer price sensitivity drives cost-optimized designs with simplified regulatory pathways.
- Fitness Centers:Wellness-oriented metrics prioritize engagement over clinical accuracy.
Hospital procurement channels process the highest sensor volumes. Home healthcare is climbing the fastest.
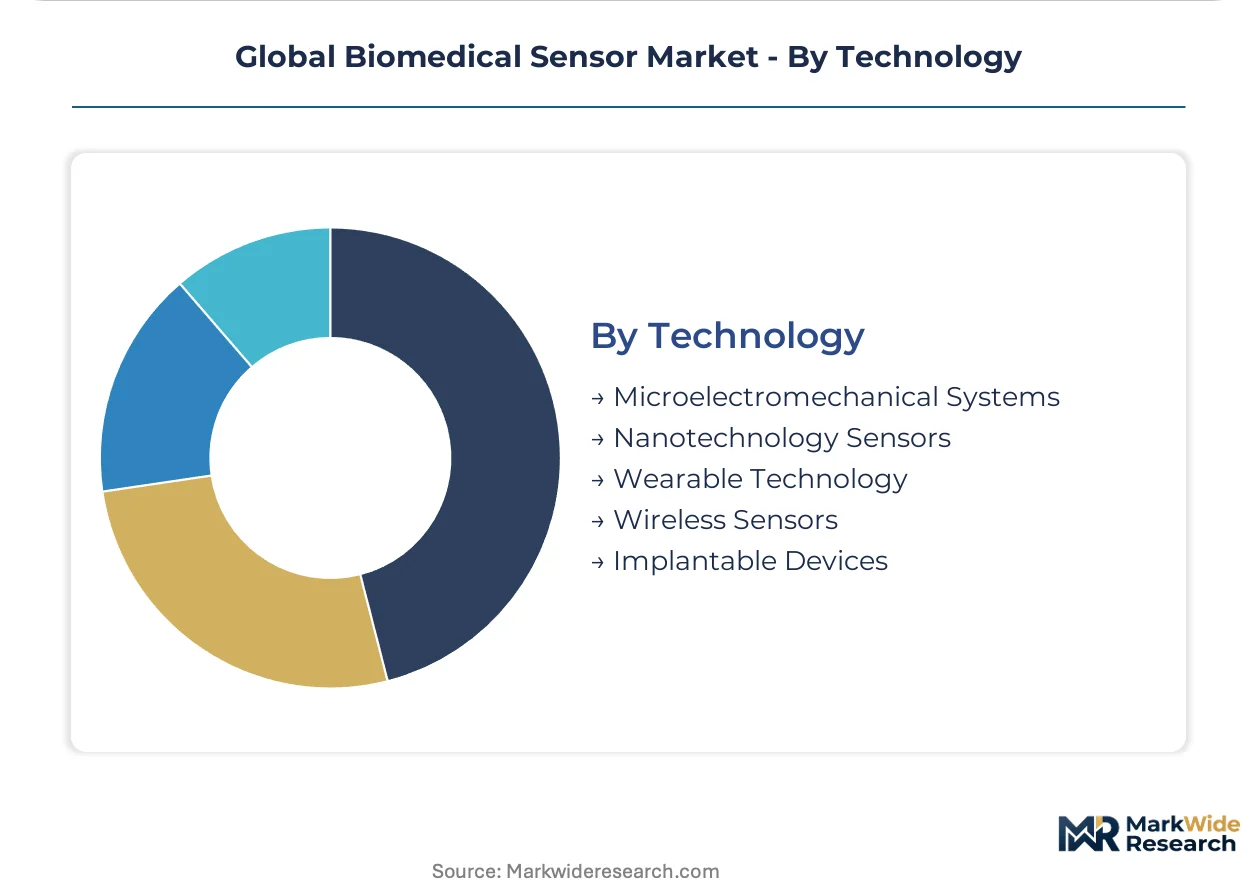
Technology:
Integration complexity escalates from discrete MEMS elements to fully implantable biocompatible systems.
- Microelectromechanical Systems:Silicon-based pressure, inertial, and acoustic sensors leverage semiconductor fabrication economies. STMicroelectronics sustains European hospital relationships through ISO 13485-certified MEMS foundry output.
- Wearable Technology:Skin-interfaced flexible electronics with micro-needle electrode arrays bypass traditional finger-prick workflows. Japan's hospital systems are piloting these platforms for perioperative glycemic control.
- Nanotechnology Sensors:Carbon nanotube and graphene transducers exploit extreme surface-area-to-volume ratios for biomolecular detection.
- Wireless Sensors:Bluetooth Low Energy and proprietary protocols enable continuous data streaming without bedside tethering.
- Implantable Devices:Hermetic packaging and biostable materials extend functional lifetime inside physiological environments.
Wearable technology platforms are absorbing the steepest capacity expansion. MEMS retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating sensor fabrication toward jurisdictions with streamlined medical-device quality-system certification, exploiting cost-of-compliance gaps between legacy European notified bodies and accelerated Asian conformity assessment pathways.
United States
FDA 510(k) pathway modifications are compressing predicate-device comparison timelines for glucose monitoring submissions, pulling venture funding toward digital health clusters in Greater Boston and the San Francisco Bay Area where software-as-medical-device expertise concentrates.
Germany
EU MDR technical documentation harmonization has consolidated hospital procurement frameworks across member states, with Baden-Württemberg and Bavaria hosting ISO 13485-certified MEMS foundries that supply electrochemical sensor substrates to diagnostic instrument OEMs.
China
NMPA priority review channels harmonized with FDA and EMA standards are accelerating market access for multinationals, while tier-one cities including Shanghai and Beijing expand public hospital digitization budgets for wireless patient monitoring infrastructure.
Japan
PMDA streamlined approval pathways for continuous glucose monitoring systems are driving ward-level deployment in Tokyo and Osaka hospital networks, with Kanto-region electronics manufacturers converting consumer sensor capacity toward medical-grade output.
South Korea
MFDS fast-track designation for wearable biosensors is attracting foundry investment in Gyeonggi Province, where semiconductor fabrication facilities are reorienting automotive MEMS lines toward medical-grade wafer production for pulse oximetry modules.
Global Biomedical Sensor Market Competitive Landscape
United States-based semiconductor conglomerates anchor the premium-tier subsystem supply; European component specialists hold hospital-certification relationships through ISO 13485-accredited fabrication. The vendor structure concentrates around analog front-end integration, MEMS foundry capacity, and enzymatic sensor chemistry. Three archetypes dominate: diversified semiconductor suppliers with medical-grade analog portfolios, pure-play MEMS fabricators with healthcare quality-system certification, and integrated device manufacturers with vertical control over glucose oxidase supply. Competitive positioning hardens through strategic partnerships between sensor developers and hospital procurement networks, plus foundry capacity reservations that lock in multi-year wafer supply.
Within the diversified semiconductor tier, Texas Instruments and Analog Devices exemplify subsystem suppliers that anchor glucose monitoring reference designs through precision analog front-end portfolios. STMicroelectronics occupies a distinct position among European ISO 13485-certified fabricators sustaining hospital procurement relationships across German and Swiss diagnostic instrument supply chains. These three entities represent the competitive anchors around which smaller sensor developers cluster for signal-processing IP and quality-system compliance.
| Leading Market Players |
|---|
| Analog Devices |
| Honeywell International |
| STMicroelectronics |
| GE Healthcare |
| NXP Semiconductors |
| Medtronic |
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
MEMS foundry conversion from automotive to medical-grade wafer output is simultaneously compressing unit economics for electrochemical sensor substrates and concentrating fabrication capacity among Taiwan and South Korean suppliers with ISO 13485-certified cleanroom infrastructure. This dual shift reshapes pricing power dynamics between sensor developers and contract manufacturers.
Pricing Analysis
Distributor margins on glucose monitoring hardware compress when hospital procurement departments unbundle sensor equipment from data analytics subscriptions. Pricing stratifies across FDA-cleared premium tiers, ISO 13485-certified standard tiers, and economy tiers for direct-to-consumer retail channels. Cost compression in the standard tier intensifies as Taiwan foundries expand medical-grade MEMS capacity. Home healthcare channels exhibit the highest price sensitivity; hospital procurement committees demonstrate the lowest.
Supply Chain Analysis
Single-source vulnerability sits with glucose oxidase enzyme production concentrated in specific bioreactor facilities. Taiwan, South Korea, and Germany anchor medical-grade MEMS wafer supply. Raw material dependencies include silicon wafers, platinum electrode coatings, and biocompatible polymers. Tariff exposure on Chinese-sourced flexible printed circuit assemblies creates supply chain risk. Distribution runs through hospital GPO contracts, diagnostic instrument OEMs, and direct-to-consumer retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
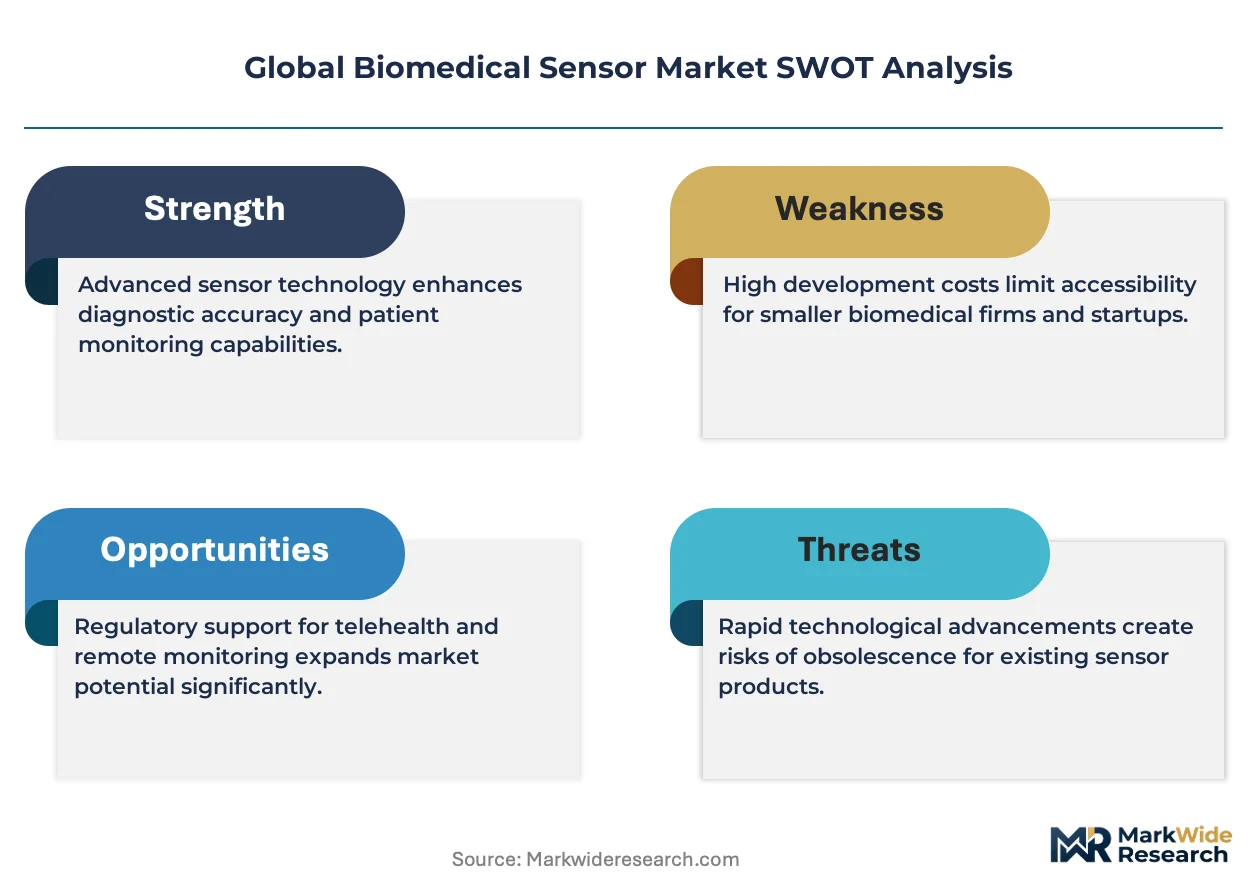
This market functions as a regulatory compounder where EU MDR harmonization and FDA 510(k) pathway modifications accelerate demand for pre-certified sensor platforms.
For Market Incumbents: Anticipate margin pressure from modular subsystem vendors by securing multi-year foundry capacity reservations in Taiwan and South Korea. Deepen backward integration into glucose oxidase supply through captive bioreactor partnerships. ISO 13485 recertification investment ahead of EU MDR timelines protects hospital procurement relationships from emerging MEMS competitors. For New Entrants and Emerging Players: Launch via remote patient monitoring reimbursement codes in the United States and Germany where regulatory pathways for wireless platforms are expanding fastest. Target skin-interfaced flexible electronics for perioperative glycemic control in Japanese hospital pilots. Partner with analog front-end subsystem suppliers to bypass multi-year validation timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play MEMS fabricators with pending ISO 13485 certification and established automotive sensor revenue. Long-term viability over the next decade hinges on regulatory moat depth rather than technology differentiation. Watch NMPA priority review channel harmonization with FDA standards as the signal for accelerated multinational market access in China.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device comparisons for AI-enabled signal processing algorithms concentrate development resources among cleared firms. |
| CE Marking Pathway | EU MDR technical documentation harmonization accelerates cross-border hospital procurement across German and Swiss networks. |
| Hospital System Partnership | Unbundled contracting models pioneered in Germany separate hardware from data analytics subscriptions. |
| Software Companion Development | Segregated hardware and software regulatory submissions parallelize approval timelines for wearable platforms. |
| Reimbursement Strategy | Remote patient monitoring code expansion in the United States and Germany creates addressable markets outside hospital capital budgets. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and South Korea, with primary inputs from each market combining interviews with hospital procurement managers, biomedical engineers, MEMS foundry operations directors, and regulatory affairs specialists. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, NMPA priority review announcements, and hospital GPO contract databases. Bottom-up sensor unit demand estimates triangulate against top-down healthcare IT expenditure forecasts.
Granularity-level modeling operates at the transduction principle, clinical application, end-user procurement channel, and regional regulatory cluster dimensions across the analysis window. CAGRs derive from fitted growth curves calibrated to historical hospital digitization spending patterns and MEMS foundry capacity expansion announcements. Forecast inputs incorporate reimbursement code expansion timelines and ISO 13485 certification pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR recertification delays or glucose oxidase supply disruptions. Forecasts reflect assumptions regarding hospital procurement cycle normalization and foundry yield ramp schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market