
 Remote Electrocardiogram Monitoring Market | 2026-2036
Remote Electrocardiogram Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Electrocardiogram Monitoring Market Analytics
Aftermarket service revenue is rewriting profit dynamics across the remote electrocardiogram monitoring landscape. Medtronic leverages its integrated device-cloud ecosystem to capture recurring subscription income from health systems. Philips Healthcare anchors its position through hospital-centric telemetry platforms that sustain long-term service contracts.
Remote electrocardiogram monitoring encompasses wearable electrodes, handheld acquisition devices, and cloud-connected interpretation platforms that capture cardiac electrical activity at 12-lead or single-lead resolution for asynchronous clinician review. The primary purpose is to detect arrhythmias, ischemia, and conduction abnormalities outside traditional clinical settings while enabling timely intervention. Wearable devices command the largest installed base among product types, yet cloud-based solutions are expanding fastest as health systems consolidate data infrastructure. Telemetry systems retain margin strength in acute-care transitions, while mobile apps face pricing pressure from platform commoditization.
The FDA's 510(k) and De Novo pathways govern device clearance in the United States, while the EU MDR and CE marking framework reshape conformity requirements across European markets. Japan's PMDA enforces rigorous electrical safety and clinical validation standards that filter market entrants. Stakeholders must weigh regulatory capital requirements against the pull of reimbursement expansion in remote patient monitoring categories.
Market Dynamics
Cloud-native telemetry architectures are compressing hardware margins while expanding recurring revenue pools for platform operators. The shift from device-centric to data-centric business models is redistributing value capture toward interpretation software and clinical workflow integration layers.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for AI-enabled arrhythmia detection algorithms are shortening commercialization cycles for algorithm developers seeking 510(k) clearance.
- Wearable electrode miniaturization:Advances in dry-electrode materials and flexible printed circuit manufacturing are extending continuous monitoring duration from days to weeks without skin irritation.
- Germany's DiGA fast-track pathway:Digital health applications for cardiac rehabilitation now qualify for statutory health insurance reimbursement, creating immediate addressable demand for prescribed remote monitoring solutions.
Market Restraints
- Cloud infrastructure concentration:Reliance on hyperscale providers in the United States for HIPAA-compliant data hosting creates geopolitical exposure and vendor lock-in risks for European operators.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations and notified body capacity constraints are extending CE marking timelines by 12-18 months for novel sensor platforms.
- Substitute diagnostic modalities:Implantable loop recorders with decade-long battery life are capturing high-risk arrhythmia cases that might otherwise deploy external patch monitors.
Strategic Opportunities
- Japan's super-aging prefectures:Rural regions with physician shortages present concentrated demand for asynchronous ECG interpretation services delivered via regional health cooperatives.
- AI-ECG integration with electronic health records:Native embedding of automated rhythm classification within Epic and Cerner workflows eliminates standalone platform fragmentation.
- Direct-to-employer contracting:Self-insured corporations in the United States are bypassing traditional payers to purchase cardiac screening programs for high-risk employee cohorts.
Industry Challenges
- Electrophysiologist interpretation bottleneck:Trained clinician scarcity limits scalable review of high-volume ambulatory ECG streams, forcing reliance on unproven autonomous diagnostic algorithms.
- Legacy hospital telemetry integration:Proprietary data formats from incumbent bedside monitor manufacturers obstruct seamless flow of wearable-acquired signals into existing alarm management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Electrocardiogram Monitoring Market |
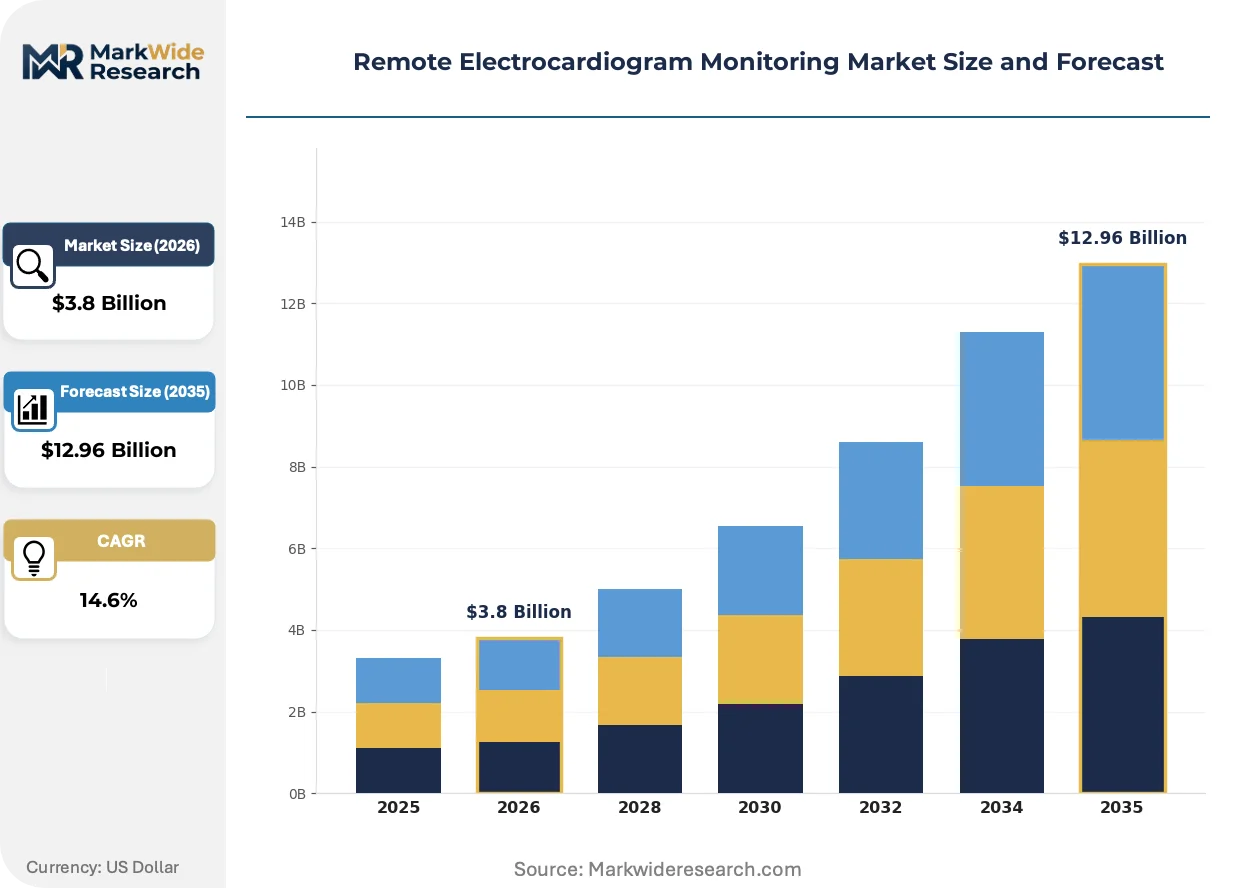
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Handheld Monitors, Mobile Apps, Telemetry Systems End User: Cardiologists, Primary Care Physicians, Hospitals, Homecare Providers Technology: Bluetooth, Wi-Fi, Cellular, Cloud-Based Solutions Application: Continuous Monitoring, Remote Diagnosis, Patient Management, Emergency Response |
| Companies Covered | Medtronic, Philips Healthcare, GE Healthcare, iRhythm Technologies, AliveCor, Biotronik, Abbott, Boston Scientific, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Electrocardiogram Monitoring Market Evolving Landscape
Machine learning inference at the network edge is transforming how cardiac signals are processed before reaching clinical review queues. This architectural shift is compressing alert latency while raising new questions about algorithmic liability and diagnostic accountability.
Deep learning architectures trained on million-scale ECG corpora are digitizing rhythm classification tasks previously requiring specialist overreading. Cardiology departments at integrated delivery networks in the United States are deploying these tools to triage normal sinus rhythm strips away from human queues. The technology is digitizing the economics of interpretation by collapsing per-study review costs toward marginal compute pricing.
Japan's PMDA has issued guidance distinguishing software-as-a-medical-device from traditional hardware-centric regulatory frameworks, clarifying approval pathways for algorithm-only products. This policy clarification is enabling domestic health technology ventures to commercialize without manufacturing physical sensors. Cardiovascular AI developers are responding by unbundling software from hardware partnerships to preserve margin capture.
Health systems are consolidating vendor relationships around platform-agnostic data lakes that ingest signals from multiple wearable OEMs. Procurement committees now prioritize interoperability over single-source device loyalty, fragmenting incumbent positions. This pattern is most pronounced in Germany's university hospital networks, where standardized FHIR-based data exchange is mandated for digital health procurement eligibility.
Remote Electrocardiogram Monitoring Market Segmentation
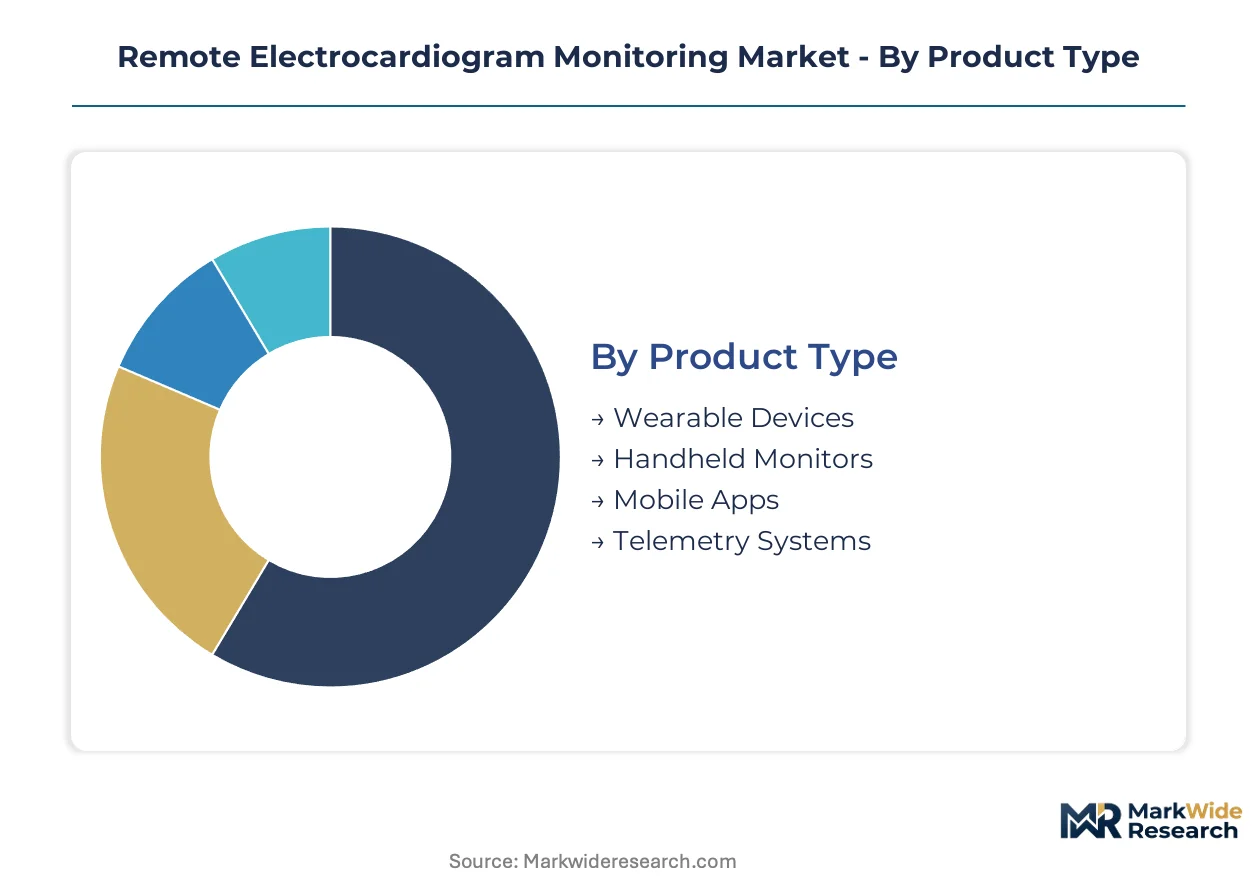
Segmentation in remote electrocardiogram monitoring reveals divergent replacement cycles and margin profiles across hardware, software, and service layers. Understanding these velocity differences guides capital allocation between device manufacturing and recurring revenue platforms.
Product Type:
Wearable electrodes turn over every 7-14 days per patient, while telemetry infrastructure persists for 5-7 years, creating stark working capital contrasts across this category.
- Wearable Devices:Single-use or limited-duration patches with dry-electrode interfaces capture cardiac signals at single-lead resolution. Homecare providers in the United States and Germany are expanding post-discharge programs for heart failure patients, driving volume concentration where reimbursement codes support remote patient monitoring.
- Telemetry Systems:Bedside and ambulatory transmitters with dedicated radio frequency links feed centralized monitoring stations in hospital settings. Acute-care transitions in Japan's super-aging prefectures sustain demand for these capital-intensive installations where physician shortages limit continuous bedside coverage.
- Handheld Monitors:Pocket-sized acquisition devices with integrated electrodes for symptomatic event recording.
- Mobile Apps:Smartphone-integrated software platforms leveraging device cameras or external sensors for rhythm analysis.
Wearable Devices anchors the volume base while Cloud-Based Solutions gains share at the steepest rate — though here Telemetry Systems retain the strongest margin profile due to long-term service contract lock-in.
End User:
Procurement authority and reimbursement access split unevenly across clinical settings, with hospitals commanding capital budgets and homecare providers capturing expanding fee-for-service streams.
- Hospitals:Integrated delivery networks consolidate purchasing for telemetry infrastructure and enterprise software licenses. Germany's university hospital networks mandate FHIR-based interoperability, fragmenting single-vendor relationships as procurement committees prioritize data lake compatibility over device loyalty.
- Homecare Providers:Post-acute and chronic disease management services deploy wearable patches for extended ambulatory monitoring. Japan's regional health cooperatives in rural prefectures are scaling asynchronous ECG interpretation services to address electrophysiologist shortages.
- Cardiologists:Specialist practices with interpretation expertise and patient referral networks.
- Primary Care Physicians:Gatekeeper clinicians screening for arrhythmia in asymptomatic populations.
Hospitals dominate capital expenditure while Homecare Providers expand most quickly as reimbursement shifts toward value-based chronic disease management.
Technology:
Connectivity architecture determines latency, coverage, and regulatory burden, with cellular and cloud layers commanding premium pricing against commoditized short-range protocols.
- Cloud-Based Solutions:Centralized data lakes with AI-enabled triage and automated rhythm classification integrate directly with Epic and Cerner electronic health records. Health systems in the United States are consolidating vendor relationships around platform-agnostic ingestion from multiple wearable OEMs.
- Cellular:Direct-to-cloud transmission bypassing local hub devices, enabling coverage in rural geographies with limited broadband infrastructure. Germany's DiGA fast-track pathway for prescribed digital health applications is accelerating statutory health insurance reimbursement for cellular-connected cardiac rehabilitation solutions.
- Bluetooth:Short-range pairing with smartphones or dedicated hubs for intermittent data offload.
- Wi-Fi:Higher-bandwidth local connectivity for multi-lead telemetry in residential or clinical settings.
Bluetooth and Wi-Fi retain the largest installed base while Cloud-Based Solutions capture the steepest expansion trajectory as interpretation economics shift toward marginal compute pricing.
Application:
Clinical utility and reimbursement intensity vary sharply between scheduled chronic management and unscheduled emergency intervention, reshaping vendor R&D priorities.
- Continuous Monitoring:Extended-duration surveillance for post-myocardial infarction, post-ablation, or heart failure management. The FDA's Breakthrough Device Designation pathway is accelerating 510(k) clearance for AI-enabled arrhythmia detection algorithms embedded in these workflows.
- Remote Diagnosis:Asynchronous specialist interpretation of symptomatic event recordings or screening captures. Japan's PMDA guidance distinguishing software-as-a-medical-device from hardware frameworks is enabling algorithm-only commercialization without sensor manufacturing partnerships.
- Patient Management:Longitudinal care coordination integrating ECG data with medication adherence and lifestyle interventions.
- Emergency Response:Real-time alert systems triggering emergency services for detected ventricular arrhythmias or ischemic events.
Continuous Monitoring anchors current revenue while Remote Diagnosis climbs fastest as AI triage collapses per-study interpretation costs toward automated margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in the United States, Germany, and Japan, while cloud infrastructure and AI development distributes across software hubs in Israel and Singapore. Regulatory divergence across FDA, EU MDR, and PMDA frameworks fragments certification pathways and shapes regional competitive positioning.
United States
Integrated delivery networks in Texas and California drive hospital telemetry procurement, while Medicare's remote patient monitoring reimbursement codes expand homecare provider adoption. FDA breakthrough device designations for AI-enabled arrhythmia detection compress 510(k) review timelines for algorithm developers. The Boston-Cambridge corridor anchors cardiovascular AI venture formation, with startups clustering near Massachusetts General Hospital's electrophysiology research programs.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia mandate FHIR-based interoperability, fragmenting single-vendor relationships as procurement prioritizes data lake compatibility. The DiGA fast-track pathway enables statutory health insurance reimbursement for prescribed cardiac rehabilitation applications. Berlin's digital health ecosystem hosts software-as-a-medical-device ventures commercializing algorithm-only products without sensor manufacturing partnerships.
Japan
Super-aging prefectures in rural Tohoku and Hokkaido sustain demand for telemetry systems where physician shortages limit continuous bedside coverage. PMDA guidance distinguishing software-as-a-medical-device from hardware frameworks clarifies approval pathways for algorithm-only commercialization. The Kansai region's Osaka-Kobe medical device cluster hosts established cardiac monitor manufacturers expanding into cloud-connected interpretation services.
Israel
Tel Aviv's digital health ecosystem specializes in AI-ECG algorithm development for integration with Epic and Cerner electronic health records. The absence of domestic medical device manufacturing shifts focus toward software licensing and technology partnerships with United States health systems. Venture capital concentration in Herzliya Pituach supports cardiovascular AI ventures seeking FDA clearance through the De Novo pathway.
Singapore
The Biopolis research cluster attracts multinational telemetry manufacturers establishing Asia-Pacific regulatory compliance centers. Government-funded smart nation initiatives pilot remote cardiac monitoring for elderly populations in public housing estates. Proximity to Malaysia's electronics manufacturing corridor enables supply chain integration for wearable sensor component sourcing.
Remote Electrocardiogram Monitoring Market Competitive Landscape
Integrated device-cloud ecosystems and specialized algorithm developers split the market between recurring subscription platforms and modular software licensing. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with hospital telemetry infrastructure, pure-play wearable sensor manufacturers, and cardiovascular AI ventures unbundling software from hardware partnerships. Dominant competitive moves include M&A activity targeting cloud-native telemetry architectures and strategic partnerships embedding rhythm classification directly into electronic health record workflows.
Within the diversified conglomerate tier, Medtronic and Philips Healthcare exemplify integrated device-cloud positioning that captures long-term service contract lock-in. Philips Healthcare anchors hospital-centric telemetry platforms sustaining enterprise software relationships, while Medtronic leverages its cardiac rhythm management heritage to bridge implantable and external monitoring ecosystems. Among pure-play specialists, iRhythm Technologies occupies a position exemplifying wearable patch-focused commercialization models that turn over hardware every 7-14 days per patient while building recurring interpretation revenue.
| Leading Market Players |
|---|
| Medtronic |
| Philips Healthcare |
| GE Healthcare |
| iRhythm Technologies |
| AliveCor |
| Biotronik |
| Abbott |
| Boston Scientific |
| Nihon Kohden Corporation |
| Others |
Value Network & Pricing Analysis
Malaysia's electronics manufacturing corridor anchors wearable sensor component sourcing, with Penang-based flexible printed circuit foundries feeding dry-electrode production lines that determine downstream margin capture for patch manufacturers competing on continuous monitoring duration claims.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across wearable ECG segments, with breakthrough device designations commanding premium positioning against standard pathway equivalents. Price differentiation separates cloud-native interpretation platforms with Epic integration from standalone mobile applications facing commoditization pressure. Cost compression in single-lead patch hardware is intensifying as dry-electrode material suppliers consolidate. Homecare providers exhibit highest price sensitivity, while integrated delivery networks prioritize interoperability over per-unit costs.
Supply Chain Analysis
Silver-silver chloride electrode materials, flexible substrate polymers, and Bluetooth Low Energy chipsets feed from concentrated upstream bases in China, Taiwan, and South Korea. Malaysia's assembly clusters and Mexico's nearshore electronics corridors provide geographic diversification for final device integration. Single-source vulnerability in dry-electrode conductive ink formulations creates exposure to specialty chemical supplier disruptions. Distribution runs through GPO contracts with integrated delivery networks and direct-to-provider channels for homecare patch programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: FDA and PMDA clearance timelines create switching costs that lock health systems into validated interpretation platforms despite emerging algorithm alternatives.
For Market Incumbents: Build data-network moats through native Epic and Cerner workflow embedding that raises replacement costs for hospital customers. Deepen backward integration into dry-electrode material production to defend margin position against conductive ink price volatility. Target telemetry infrastructure refresh cycles in Japan's super-aging prefectures where physician shortages sustain capital equipment demand. Secure long-term GPO contracts before AI-only entrants achieve FDA breakthrough status. For New Entrants and Emerging Players: Rural Germany's statutory health insurance reimbursement gaps present white-space for DiGA-fast-tracked cardiac rehabilitation applications bypassing incumbent hospital relationships. Japan's regional health cooperatives in Tohoku and Hokkaido offer entry points for asynchronous ECG interpretation services unbundled from hardware manufacturing. Partner with established sensor OEMs to accelerate commercialization without PMDA hardware validation burdens. Focus direct-to-employer cardiac screening contracts with self-insured US corporations outside traditional payer networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cardiovascular AI ventures with FDA De Novo pathway experience over hardware-dependent patch manufacturers facing margin compression. Long-term viability hinges on algorithmic liability frameworks clarifying diagnostic accountability for autonomous rhythm classification. Acquisition targets should demonstrate FHIR-based interoperability and existing health system pilot deployments. Watch FDA guidance on software-as-a-medical-device autonomy thresholds as inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates 510(k) review timelines for AI-enabled arrhythmia detection algorithms. |
| Hospital System Partnership | Locks recurring revenue through enterprise telemetry platform integration with Epic workflows. |
| CE Marking Pathway | Navigates EU MDR post-market surveillance obligations for novel sensor platform commercialization. |
| Software Companion Development | Unbundles algorithm licensing from hardware manufacturing partnerships per Japan PMDA guidance. |
| Reimbursement Strategy | Secures DiGA fast-track eligibility for statutory health insurance coverage in Germany. |
Research Methodology
Desk research of FDA 510(k) clearance databases, PMDA approval registries, and hospital procurement contract filings preceded structured interviews with electrophysiologists, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from CMS remote patient monitoring reimbursement data, EU MDR notified body capacity reports, and DiGA directory listings. Bottom-up patch volume estimates from homecare provider deployments triangulated against top-down health system telemetry infrastructure spending.
Fixed assumptions across the modeling period include sustained Medicare RPM reimbursement codes and stable EU MDR clinical evidence requirements. Segmentation dimensions modeled encompass product type, connectivity architecture, end-user setting, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and interpretation service pricing trajectories. Forecast inputs incorporated wearable electrode miniaturization curves and AI triage adoption thresholds in integrated delivery networks.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investments by diversified medtech conglomerates would shift outcomes beyond projected ranges. Cross-checking against hospital capital expenditure surveys and health system AI procurement benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
Global Consumer Healthcare Sensor Market