
 North America Hemodynamic Monitoring Market | 2026-2036
North America Hemodynamic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hemodynamic Monitoring Market Analytics
Project finance for connected critical-care infrastructure is narrowing the competitive field to operators with balance-sheet depth. Edwards Lifesciences Corporation leverages its catheter manufacturing scale to dominate North American supply of pulmonary artery systems. GE HealthCare Technologies, Inc. sustains installed-base loyalty through integrated monitoring architectures across hospital networks. Masimo Corporation differentiates via proprietary signal-processing algorithms that extend parameter detection beyond conventional platforms.
Hemodynamic monitoring encompasses the continuous measurement of blood flow dynamics, cardiac output, vascular resistance, and oxygen delivery through invasive and non-invasive sensor technologies, typically employing pressure transducers, thermodilution methods, or pulse contour analysis to guide therapeutic decisions in acute care settings. Minimally invasive monitoring leads technology adoption as clinicians seek reduced complication profiles without sacrificing parameter richness. Disposable sensors capture recurring revenue pools, while integrated systems anchor capital budgets through enterprise-wide standardization contracts. Wireless monitors represent the fastest-growing product type, driven by telemetry expansion into step-down units and emergency departments.
The FDA governs device safety and efficacy through 510(k) and PMA pathways, while Health Canada mandates Medical Device License compliance for market entry. The Joint Commission and CMS quality metrics shape hospital procurement criteria, favoring platforms with proven outcomes documentation. Stakeholders must monitor reimbursement alignment between remote monitoring codes and wireless hemodynamic modalities to anticipate capital allocation shifts.
Market Dynamics
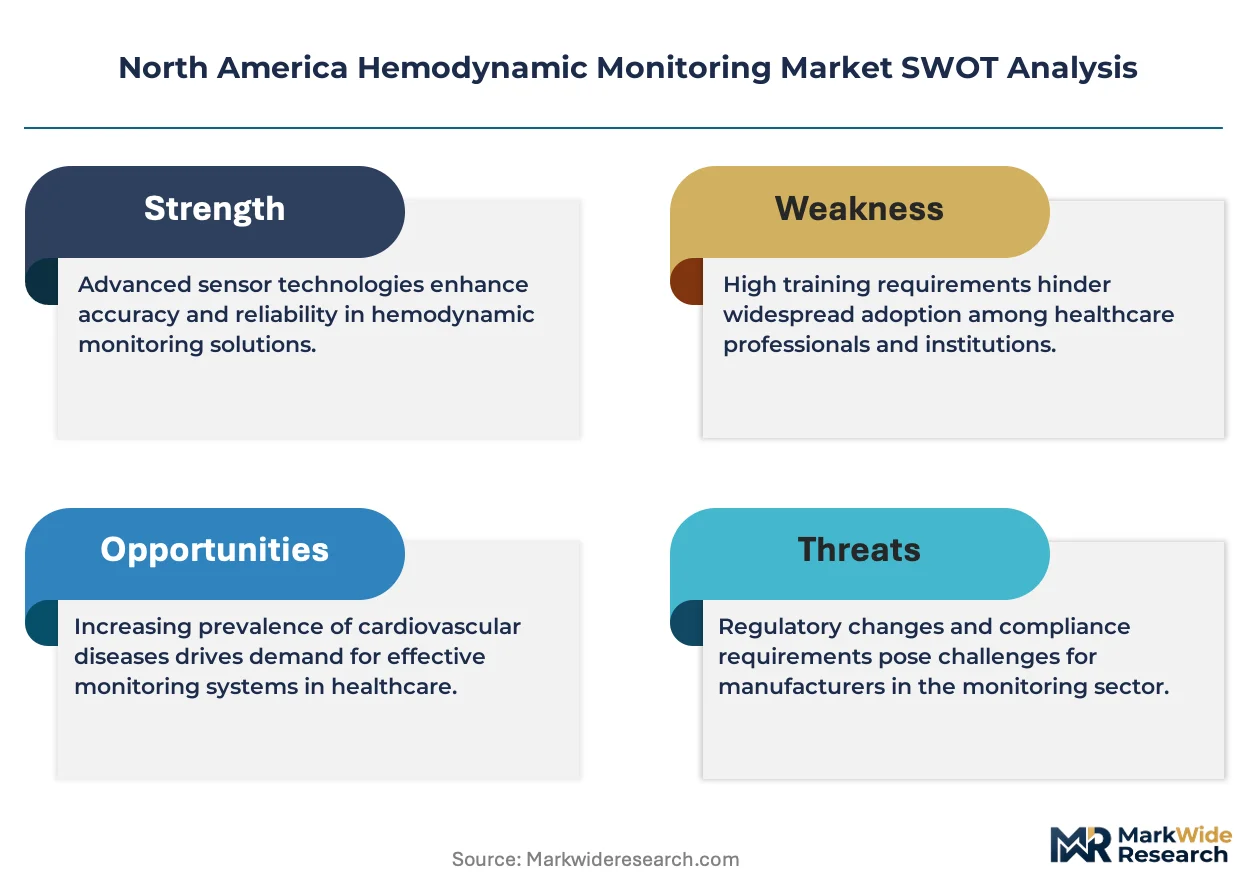
Wireless telemetry architectures are compressing capital deployment cycles across US and Canadian hospital systems, forcing incumbents to retrofit installed bases or cede step-down unit expansion to modular competitors.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket notification reviews for Class II cardiovascular devices are shortening product launch timelines for catheter-based monitoring systems.
- CMS quality metric alignment:Hospital reimbursement tied to perioperative outcome reporting drives procurement of platforms with integrated data capture for cardiac surgery suites.
- Minimally invasive catheter adoption:Tertiary care centers in Texas and California are standardizing arterial pressure waveform analysis to reduce pulmonary artery catheter complication rates.
Market Restraints
- Disposable sensor cost concentration:Single-use pressure transducers and thermodilution injectates create recurring expenditure burdens that strain non-profit hospital operating budgets.
- Supply chain geographic concentration:Domestic manufacturing of piezoelectric pressure sensors clusters in specific Midwest industrial corridors, creating vulnerability to regional logistics disruptions.
- Interoperability technical limitations:Proprietary data protocols from established monitoring vendors fragment electronic health record integration, complicating enterprise standardization.
Strategic Opportunities
- Underpenetrated Canadian market expansion:Health Canada Medical Device License compliance, once achieved, opens procurement pathways in Ontario and Quebec cardiac centers with less saturated competitive intensity.
- Artificial intelligence convergence:Machine learning algorithms applied to arterial waveform databases enable predictive hypotension alerts before clinical deterioration manifests.
- Remote monitoring regulatory tailwind:Alignment between CMS remote patient monitoring reimbursement codes and wireless hemodynamic modalities creates sustainable revenue models for telemetry expansion.
Industry Challenges
- Perfusionist and critical-care nurse skill gaps:Specialized training requirements for advanced hemodynamic parameter interpretation outpace academic program output in several US states.
- Legacy system integration complexity:Bedside monitor replacement in established cardiac surgery units requires phased rollout to maintain continuous patient surveillance during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hemodynamic Monitoring Market |
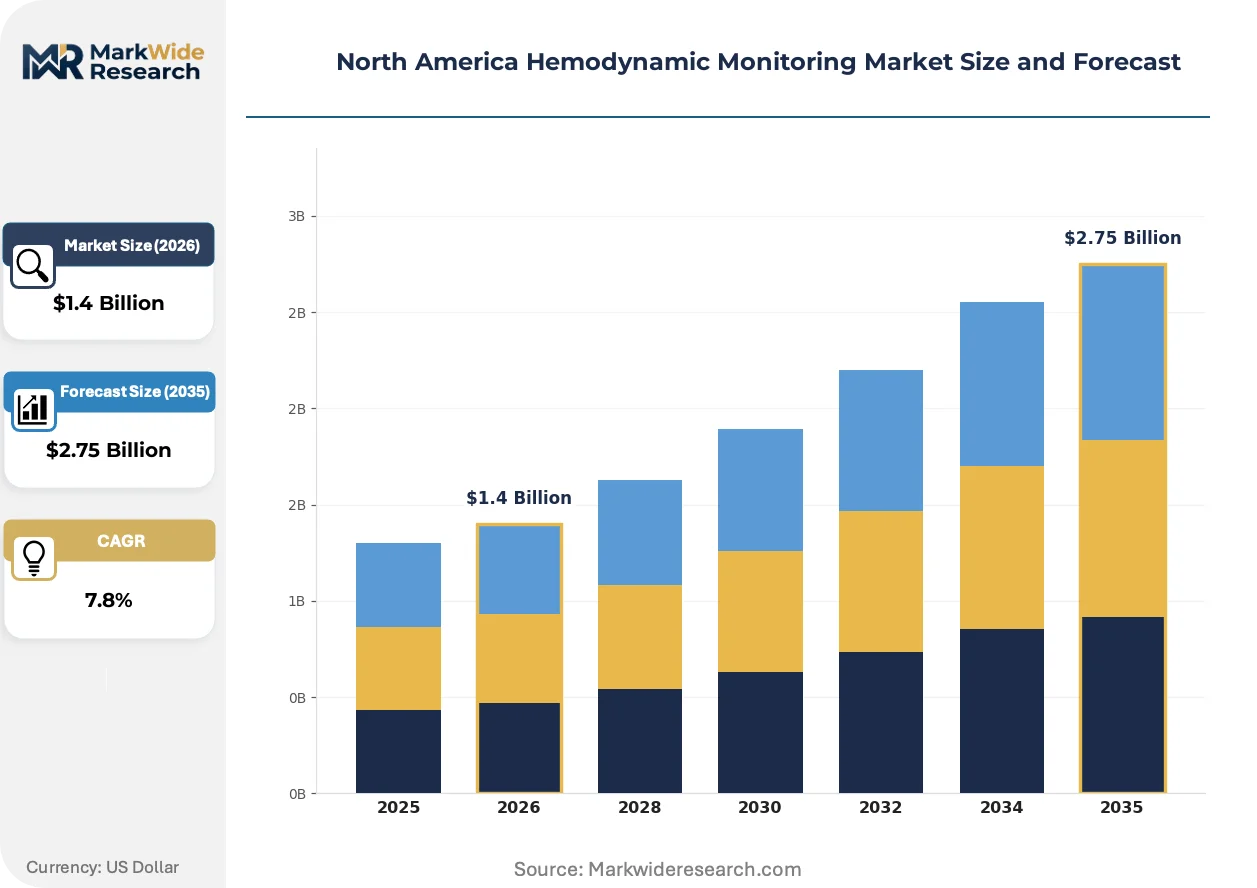
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Arterial Pressure Monitoring, Cardiovascular Monitoring, Pulmonary Artery Catheters, Minimally Invasive Monitoring Product Type: Standalone Devices, Integrated Systems, Disposable Sensors, Wireless Monitors End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Emergency Departments Application: Cardiac Surgery, Critical Care, Pediatric Monitoring, Postoperative Care |
| Companies Covered | Edwards Lifesciences Corporation, GE HealthCare Technologies, Inc., Baxter International, Inc., ICU Medical, Inc., Masimo Corporation, Medtronic PLC, Koninklijke Philips N.V., Getinge AB, BD, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hemodynamic Monitoring Market Evolving Landscape
Digital twin architectures and edge computing are redefining how physiologic data flows from sensor to decision support, collapsing the latency between signal acquisition and therapeutic intervention.
Photoplethysmography-based cardiac output estimation is virtualizing traditional invasive monitoring workflows. Community hospitals and ambulatory surgical centers lacking interventional cardiology support are adopting these platforms for moderate-risk procedures. The technology is virtualizing the capital barrier that previously restricted advanced hemodynamic surveillance to tertiary facilities.
FDA's evolving cybersecurity guidance for networked medical devices is mandating encryption standards and vulnerability disclosure protocols for wireless monitoring systems. Manufacturers must now embed security-by-design into hardware architecture rather than layering software patches post-market. Cardiac surgery application segments face the steepest compliance burden given their institutional exposure to ransomware targeting.
Hospital procurement committees are consolidating vendor relationships through enterprise standardization contracts that bundle monitoring hardware, disposable sensors, and data analytics subscriptions. Integrated delivery networks in California and Texas are replacing fragmented point solutions with sole-source agreements covering multiple care settings. This concentration is most visible among IDNs operating more than fifteen acute care facilities.
North America Hemodynamic Monitoring Market Segmentation
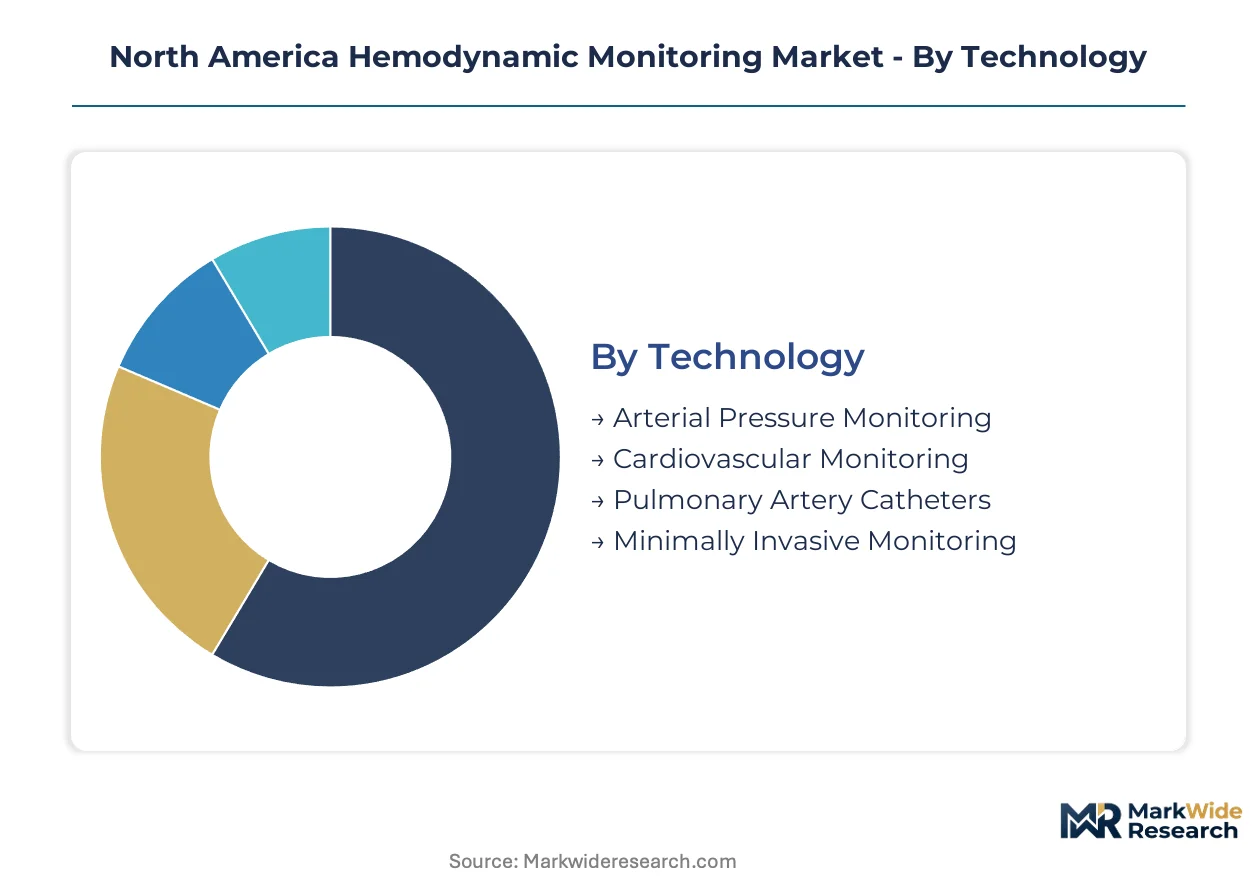
Hemodynamic monitoring segmentation reveals divergent capital intensity and replacement cycles across technology platforms. Product type and end-user configurations determine whether revenue flows from disposable recurring purchases or multi-year capital deployments.
Technology:
Cycle times vary dramatically, with catheter-based systems requiring quarterly sensor replacement while integrated monitoring platforms operate on seven-to-ten-year depreciation schedules.
- Arterial Pressure Monitoring:Pressure transducer systems measure systolic, diastolic, and mean arterial pressure through radial or femoral cannulation. Texas and California tertiary centers are standardizing these platforms to reduce pulmonary artery catheter complication rates while maintaining parameter richness.
- Minimally Invasive Monitoring:Arterial waveform analysis and pulse contour methods estimate cardiac output without right heart catheterization. Community hospitals across Ontario and Quebec are adopting these systems where interventional cardiology support is limited.
- Cardiovascular Monitoring:Multi-parameter platforms track ECG, blood pressure, and oxygen saturation simultaneously.
- Pulmonary Artery Catheters:Thermodilution-based systems remain the gold standard for mixed venous oxygen saturation measurement.
Arterial Pressure Monitoring anchors the volume base while Minimally Invasive Monitoring gains share at the steepest rate.
Product Type:
Margin structures separate capital equipment from consumable revenue streams, with disposable sensors commanding recurring margins that offset hardware price compression.
- Disposable Sensors:Single-use pressure transducers, thermodilution injectates, and catheter components generate recurring revenue pools. Non-profit hospital operating budgets in the US Midwest face particular strain from these expenditure burdens.
- Wireless Monitors:Telemetry-enabled devices transmit hemodynamic data to central nursing stations without bedside tethering. Step-down units and emergency departments in California IDNs are expanding these platforms fastest.
- Standalone Devices:Modular monitors serve specific parameters without enterprise integration.
- Integrated Systems:Enterprise-wide architectures bundle hardware, software, and analytics across hospital networks.
Disposable Sensors capture the highest purchase frequency while Wireless Monitors are climbing the fastest as telemetry expands beyond intensive care.
End User:
Procurement authority concentrates differently across settings, with hospital value analysis committees controlling capital budgets while ambulatory centers prioritize lease flexibility.
- Hospitals:Acute care facilities with cardiac surgery suites drive demand for comprehensive parameter detection. Tertiary centers in Texas, California, and Ontario represent the primary adoption corridor for advanced monitoring platforms.
- Emergency Departments:Rapid assessment protocols require portable hemodynamic verification for shock classification. These settings favor wireless modalities that integrate with triage workflows.
- Ambulatory Surgical Centers:Moderate-risk procedure volumes are rising in settings lacking 24-hour critical care coverage.
- Home Care Settings:Remote patient monitoring reimbursement codes are creating viable economics for post-discharge surveillance.
Hospitals dominate absolute revenue contribution while Emergency Departments are expanding most quickly as telemetry compresses deployment cycles.
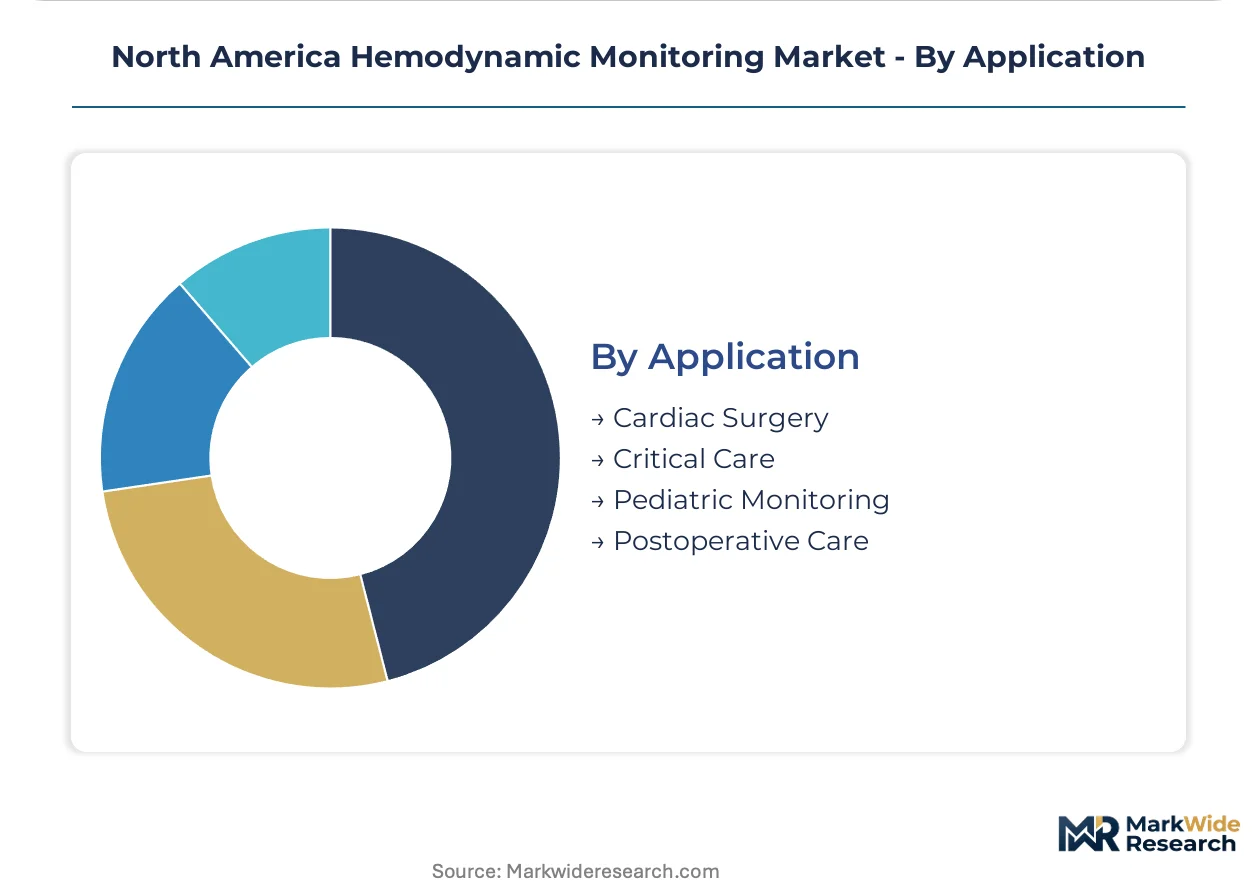
Application:
Clinical acuity determines parameter complexity requirements, with high-stakes surgical applications demanding redundant measurement modalities.
- Cardiac Surgery:Cardiopulmonary bypass and valve replacement procedures require continuous cardiac output, mixed venous oxygen saturation, and systemic vascular resistance tracking. CMS quality metrics tied to perioperative outcome reporting shape procurement criteria in this segment.
- Critical Care:Septic shock and acute respiratory distress syndrome management depends on dynamic preload assessment and fluid responsiveness testing.
- Postoperative Care:Early detection of hemorrhage or cardiac tamponade drives monitoring duration into recovery phases.
- Pediatric Monitoring:Neonatal and pediatric catheter sizing constraints limit technology transfer from adult platforms.
Cardiac Surgery commands the highest per-procedure monitoring intensity while Critical Care is gaining share fastest as sepsis protocols broaden parameter surveillance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States and Canada concentrate buying power for hemodynamic monitoring systems, with integrated delivery networks in Texas and California commanding multi-facility standardization contracts that reshape vendor competitive dynamics.
United States
Tertiary cardiac centers in Texas and California drive demand for minimally invasive monitoring platforms as clinicians seek reduced pulmonary artery catheter complication rates. FDA 510(k) pathway streamlining accelerates premarket clearance timelines for Class II cardiovascular devices. The Cleveland Clinic and Mayo Clinic networks anchor adoption corridors in the Midwest, standardizing arterial pressure waveform analysis across surgical suites.
Canada
Ontario and Quebec cardiac surgery units expand procurement of wireless telemetry systems as Health Canada Medical Device License compliance opens less saturated competitive pathways. Provincial health authorities in Ontario consolidate purchasing through group service organizations that favor integrated monitoring architectures. Toronto's University Health Network and Montreal's McGill University Health Centre anchor the primary adoption corridor for advanced hemodynamic platforms.
Mexico
Private hospital chains in Mexico City and Monterrey import monitoring systems through distributor networks serving the high-acuity surgical segment. COFEPRIS regulatory compliance requirements shape product registration timelines for cardiovascular device manufacturers. The ABC Medical Center in Mexico City and Hospital San José Tec de Monterrey anchor demand concentration for catheter-based monitoring in cardiac surgery applications.
North America Hemodynamic Monitoring Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated delivery network procurement power. Edwards Lifesciences Corporation leverages catheter manufacturing scale to dominate pulmonary artery system supply, while GE HealthCare Technologies, Inc. sustains installed-base loyalty through enterprise-wide monitoring architectures. Masimo Corporation differentiates via proprietary signal-processing algorithms. Strategic moves concentrate on M&A for telemetry capabilities and backward integration into sensor manufacturing.
Among North American-based device manufacturers, Edwards Lifesciences Corporation, GE HealthCare Technologies, Inc., and Masimo Corporation occupy positions across the competitive spectrum. Edwards Lifesciences exemplifies the catheter-scale archetype through its Irvine, California headquarters and cardiovascular device heritage. GE HealthCare Technologies represents the integrated-systems tier with its Chicago-based healthcare technology platform. Masimo Corporation anchors the algorithm-specialist position from its Irvine, California base, with signal-processing capabilities extending parameter detection beyond conventional platforms.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| GE HealthCare Technologies, Inc. |
| Baxter International, Inc. |
| ICU Medical, Inc. |
| Masimo Corporation |
| Medtronic PLC |
| Koninklijke Philips N.V. |
| Getinge AB |
| BD |
| Others |
Value Network & Pricing Analysis
Overcapacity in Midwest piezoelectric sensor manufacturing is compressing component pricing while concentrating bargaining power among catheter assemblers in California and Texas. FDA 510(k) clearance timelines shape inventory positioning, as Health Canada compliance costs create tiered entry barriers that segment pricing power across the border.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-cleared Class II devices commanding substantial premiums over Health Canada-only platforms. Three-tier pricing structure across premium, standard, and economy levels reflects disposable sensor bundling and software analytics subscriptions. Cost compression in the economy tier is intensifying because community hospitals in Ontario and Quebec prioritize lease flexibility over capital ownership. Ambulatory surgical centers exhibit the highest price sensitivity, while tertiary cardiac centers in Texas and California prioritize parameter richness over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for pressure transducer manufacturers. Domestic manufacturing of piezoelectric sensors clusters in Midwest industrial corridors, while semiconductor components for wireless telemetry draw from Taiwan and South Korea. Single-source vulnerability in thermodilution injectate chemistry creates procurement concentration risk. Distribution runs through integrated delivery network value analysis committees that consolidate multi-facility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized training pipelines for perfusionists and critical-care nurses lag deployment timelines, constraining technology absorption regardless of hardware availability. This capability gap favors vendors with embedded education services over pure equipment suppliers.
For Market Incumbents: Entrench installed-base loyalty through backward integration into disposable sensor manufacturing, capturing recurring revenue pools that offset hardware price erosion. Expand telemetry retrofit programs for existing monitoring architectures before modular competitors capture step-down unit expansion. Prioritize FDA cybersecurity guidance compliance as ransomware targeting of cardiac surgery networks intensifies. For New Entrants and Emerging Players: Build out artificial intelligence-enabled predictive analytics platforms that layer atop existing arterial waveform infrastructure, avoiding direct catheter manufacturing scale disadvantages. Target Ontario and Quebec cardiac centers where Health Canada Medical Device License compliance opens less saturated procurement pathways. Lead with machine learning hypotension alert capabilities that require minimal hardware displacement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among disposable sensor manufacturers with hospital system sole-source agreements. Long-term viability across the projection horizon rests on reimbursement alignment between CMS remote monitoring codes and wireless hemodynamic modalities. Signal telemetry capability acquisitions as the inflection indicator for enterprise standardization contract capture.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shorter premarket clearance timelines compress competitive response windows for catheter-based systems. |
| Hospital System Partnership | Integrated delivery networks in California and Texas consolidate procurement through enterprise standardization contracts. |
| Software Companion Development | Predictive analytics platforms differentiate arterial pressure monitoring beyond hardware parameter detection. |
| Reimbursement Strategy Alignment | CMS remote patient monitoring code capture creates sustainable economics for telemetry expansion. |
| CE Marking Pathway | Health Canada Medical Device License compliance opens procurement pathways in Ontario and Quebec cardiac centers. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and critical-care clinicians converged on the working assumptions underlying this analysis. Primary fieldwork with cardiac surgery suite directors and perfusionist training program administrators combined with secondary validation against FDA 510(k) filings, Health Canada Medical Device License databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up demand modeling across technology platforms, product types, and end-user settings triangulated with top-down market sizing from integrated delivery network capital expenditure disclosures.
Demand-supply balance dynamics across the analysis window anchored the forecast framework, with segmentation modeling spanning technology platform, product configuration, end-user setting, and application acuity. CAGRs were derived from installed base replacement cycles, telemetry expansion trajectories, and disposable sensor purchase frequency patterns. Input assumptions incorporated FDA premarket notification pathway evolution, Health Canada compliance timeline standardization, and provincial health authority procurement consolidation in Ontario and Quebec.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algorithm-specialist entrants or integrated systems vendors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
North America Wearable Ambulatory Monitoring Devices Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Wrist Blood Pressure Monitors Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Global Consumer Healthcare Sensor Market