
 Global Ambient Food Packaging Market | 2026-2036
Global Ambient Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambient Food Packaging Market Analysis
Biodegradable materials is restructuring cost structures across ambient food packaging as converters absorb higher input costs and reformulate barrier properties. Amcor Plc leverages its global manufacturing footprint to sustain multi-material platform supply. Huhtamaki Oyj anchors European fiber-based production with advanced molded-fiber technology for shelf-stable applications. Tetra Pak dominates aseptic carton systems for ambient beverages and liquid foods.
Ambient food packaging encompasses barrier-engineered containers, films, and cartons designed to preserve shelf-stable products without refrigeration, typically achieving oxygen transmission rates below 1 cc/m²/day and moisture vapor transmission rates under 0.5 g/m²/day to inhibit microbial growth and oxidative degradation. Its primary commercial purpose is extending product safety and sensory stability across ambient temperature supply chains from manufacture through retail display. Flexible packaging leads volume deployment for snack and condiment applications where lightweight logistics and material efficiency concentrate margin pools. Rigid packaging retains structural priority for ready-to-eat meals requiring stack strength and microwave compatibility. Smart packaging represents the fastest-growing technology segment as time-temperature indicators and freshness sensors attract premium positioning.
FDA food contact substance notifications govern material migration limits in the United States, while EFSA and REACH compliance frameworks in Europe restrict certain phthalates and perfluorinated compounds in food-contact layers. China's SAMR enforces GB standards for composite packaging structures, creating divergent testing protocols that fragment formulation strategies. ISO 22000 and BRCGS certification requirements shape supplier qualification thresholds for multinational food brands. Stakeholders must monitor evolving extended producer responsibility mandates and bio-based content thresholds as these frameworks increasingly determine market access and procurement specifications.
Market Dynamics
Barrier performance requirements are tightening as shelf-stable formulations migrate toward clean-label preservatives, forcing converters to engineer oxygen and moisture protection without conventional synthetic additives. This technical pivot is restructuring supplier capabilities and qualification timelines across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants in aerosol food packaging is accelerating investment in compressed gas and mechanical dispensing alternatives across European condiment and cooking spray segments.
- India PLI scheme:Production-linked incentives for food processing infrastructure are driving packaging line upgrades in Maharashtra and Gujarat, expanding domestic demand for retort pouch and carton systems.
- Smart packaging sensors:Time-temperature indicators are penetrating premium ready-to-eat meal segments as retailers deploy freshness verification to reduce shrink and extend distribution radius.
Market Restraints
- Resin supply concentration:Ethylene vinyl alcohol and polyamide barrier film feedstocks concentrate among Northeast Asian petrochemical complexes, exposing converters to freight cost volatility and allocation risk.
- Compostable film performance gap:Polylactic acid and polyhydroxyalkanoate structures fail to match polyethylene terephthalate moisture barriers in tropical supply chains, limiting geographic deployment.
- Extended producer responsibility mandates:Germany's Verpackungsgesetz and France's AGEC law impose fee structures that disproportionately burden small-format flexible packaging relative to rigid alternatives.
Strategic Opportunities
- Indonesia cold chain gaps:Archipelago logistics constraints create ambient-stable packaging demand for shelf-stable dairy and beverage products in outer island retail networks.
- Retortable mono-material pouches:Polypropylene barrier innovations enable high-temperature sterilization compatibility with existing polyethylene recycling streams, unlocking circular economy positioning.
- SAMR GB standards alignment:China's convergence of composite packaging safety testing with Codex Alimentarius frameworks reduces dual-certification burden for exporters targeting domestic and international markets simultaneously.
Industry Challenges
- Migration testing capacity:Laboratory bottlenecks for FDA food contact substance notifications and EFSA compliance verification extend new product qualification cycles by six to twelve months.
- Legacy line retrofit complexity:Aseptic carton and retort pouch formats require incompatible filling equipment, constraining co-manufacturers from serving divergent customer specifications without dedicated asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambient Food Packaging Market |
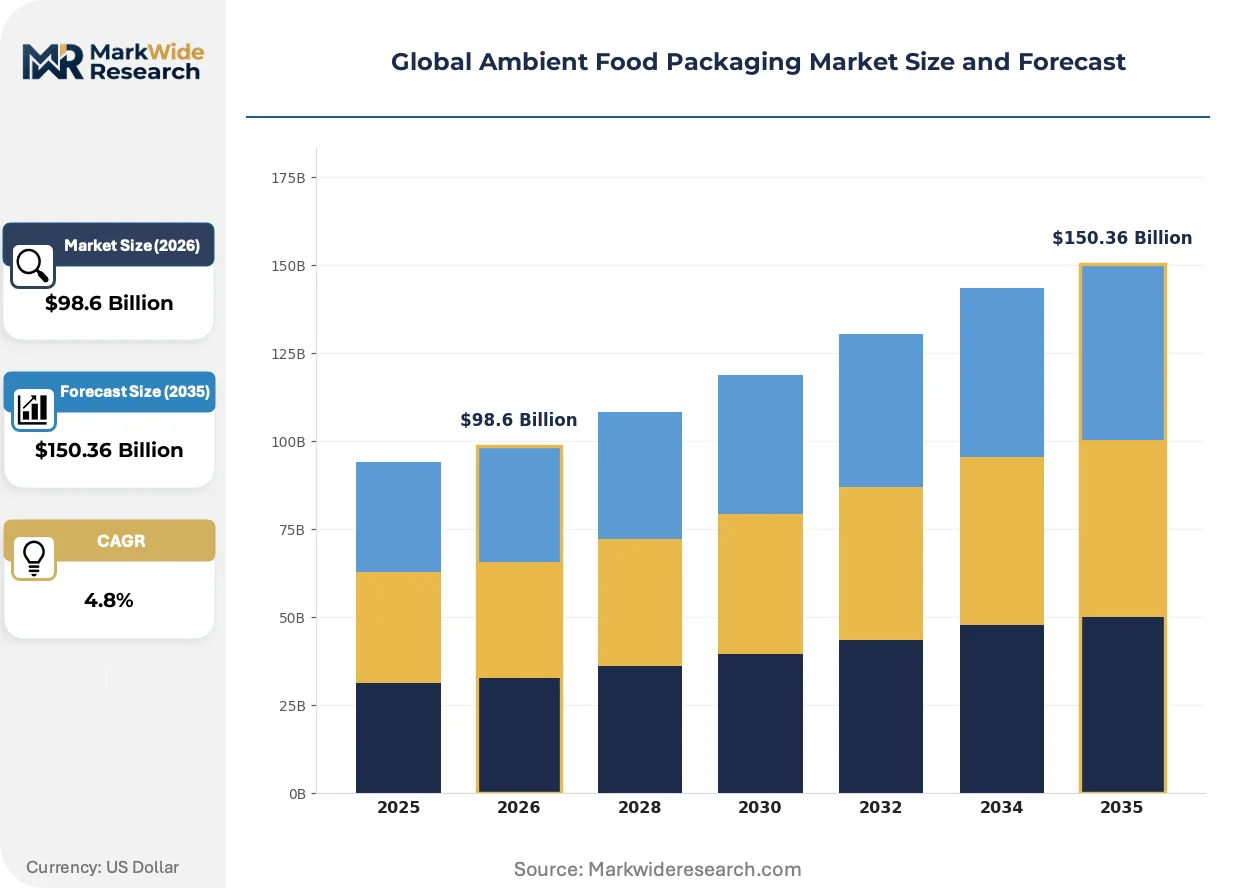
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $150.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Vacuum Packaging, Resealable Packaging Material: Plastic, Paper, Metal, Biodegradable Materials End Use: Snacks, Ready-to-Eat Meals, Beverages, Condiments Technology: Modified Atmosphere Packaging, Active Packaging, Smart Packaging, Barrier Packaging |
| Companies Covered | Smurfit Kappa Group, WestRock Company, Amcor Plc, DS Smith Plc, Huhtamaki Oyj, Tetra Pak, Berry Global Inc., Sonoco Products Company, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambient Food Packaging Market Emerging Trajectories
Active and intelligent packaging functionalities are migrating from pharmaceutical applications into food-contact systems, creating new technical specifications for sensor integration, data capture, and regulatory compliance that reshape converter R&D priorities.
High-barrier mono-material polypropylene structures are consolidating flexible packaging specifications across snack and condiment segments. Brand owners in Western European markets are specifying these structures to preempt EPR fee differentials and simplify consumer sorting instructions. The consolidation is compressing multi-material laminate demand and forcing adhesive and coating suppliers to reformulate for single-substrate compatibility.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are accelerating fluorine-free barrier coating development. Paperboard converters serving frozen and refrigerated ambient categories are qualifying silicone and clay-based alternatives to maintain grease resistance. German retail chains are enforcing compliance ahead of regulatory deadlines, shifting procurement specifications across Central European supply bases.
Direct-to-retailer procurement of private-label ambient packaging is shortening specification cycles and compressing converter margin structures. Large-format grocery operators in the United Kingdom are consolidating supplier panels and demanding volume-commitment pricing in exchange for multi-year category exclusivity. The shift is visible in ready-to-eat meal and ambient soup segments where retailer own-brand penetration exceeds sixty percent.
Global Ambient Food Packaging Market Segmentation
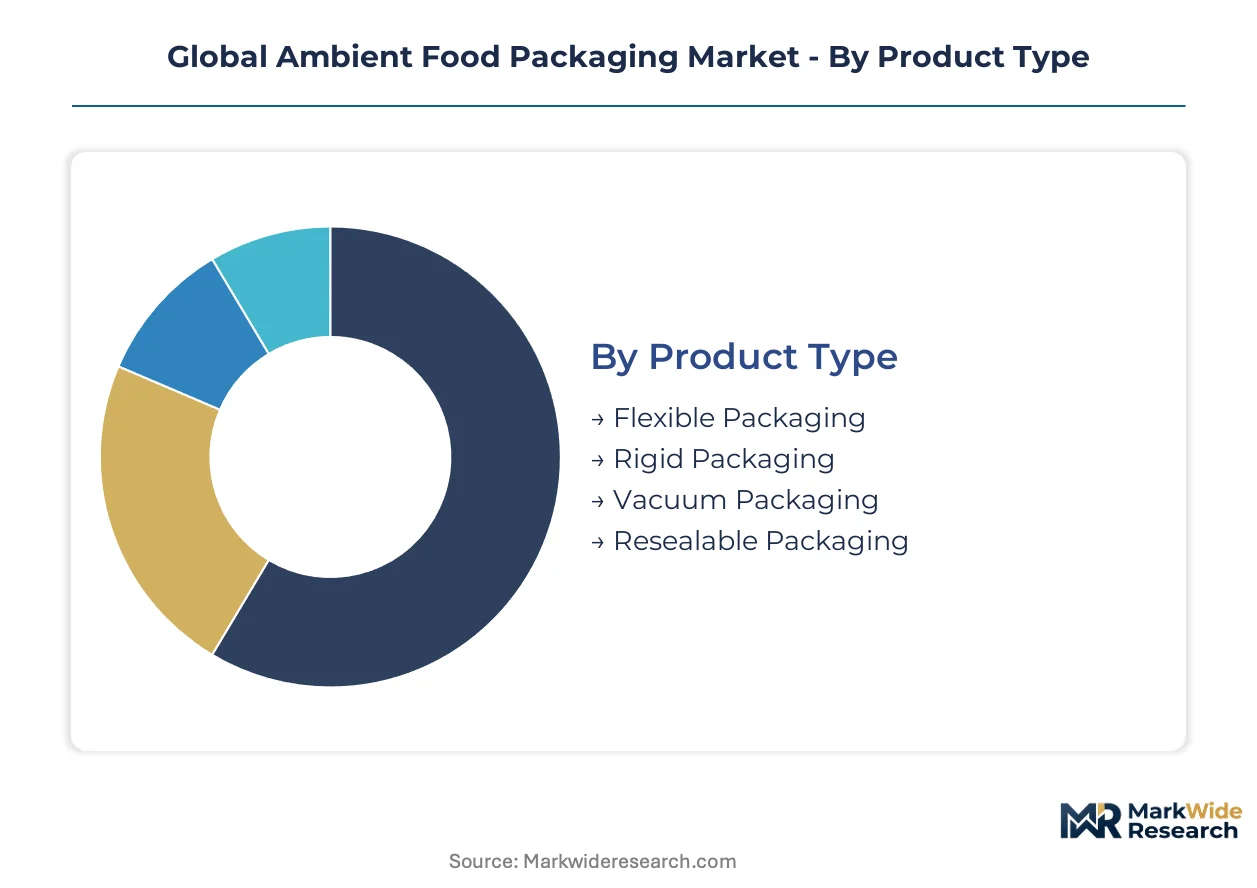
Segmentation in ambient food packaging reveals how technical specifications map to supply chain economics. Material choices and barrier technologies determine qualification timelines, while end-use applications dictate volume concentration and margin structures.
Product Type:
Standalone formats operate independently of filling equipment, while embedded systems require tight integration with processing lines.
- Flexible Packaging:Multi-layer films and pouches achieve oxygen transmission below 1 cc/m²/day through ethylene vinyl alcohol and polyamide barriers. Demand clusters in snack and condiment segments across India and Southeast Asia where lightweight logistics reduce freight costs.
- Rigid Packaging:Injection-molded polypropylene and thermoformed PET containers provide stack strength for retail display. Ready-to-eat meal applications in Germany and France drive specification tightening around microwave compatibility and EPR compliance.
- Vacuum Packaging:Thermoformed trays with peelable lidding films remove headspace oxygen to extend shelf stability.
- Resealable Packaging:Zipper-equipped pouches and lidded trays support multi-serve consumption patterns.
Volume placements concentrate in Flexible Packaging; the faster expansion belongs to Resealable Packaging.
Material:
Cost tiers separate commodity feedstocks from engineered alternatives with compliance premiums.
- Plastic:Polyethylene, polypropylene, and polyester dominate through proven barrier performance and established recycling infrastructure. India's PLI scheme drives domestic resin compounding capacity for retort pouch applications.
- Biodegradable Materials:Polylactic acid and polyhydroxyalkanoate structures target EPR fee reductions in France and Germany. Tropical supply chain deployment remains constrained by moisture barrier gaps versus conventional plastics.
- Paper:Fiber-based cartons and molded pulp serve aseptic beverage systems with renewable positioning.
- Metal:Tinplate and aluminum cans preserve shelf-stable proteins and prepared meals.
Plastic retains the dominant volume position; biodegradable alternatives are climbing the fastest.
End Use:
Application requirements determine barrier specifications and regulatory exposure.
- Ready-to-Eat Meals:Retort pouch and tray formats require high-temperature sterilization compatibility. Urban retail modernization in Mumbai and Delhi expands demand for ambient curry and rice products with extended shelf life.
- Beverages:Aseptic carton and bottle systems preserve UHT milk and juice without refrigeration. Indonesia's outer island distribution networks favor ambient-stable dairy packaging over cold chain-dependent alternatives.
- Snacks:Nitrogen-flushed flexible bags maintain crispness for fried and baked products.
- Condiments:Squeeze tubes and portion packs address foodservice and retail channels.
Snacks command the largest volume placements; ready-to-eat meals are gaining share fastest.
Technology:
Maturity levels separate established barrier methods from emerging sensor integration.
- Barrier Packaging:Oxygen and moisture control through material engineering and coating systems. REACH restrictions on perfluorinated compounds in Europe accelerate fluorine-free coating qualification at German paperboard converters.
- Smart Packaging:Time-temperature indicators and freshness sensors reduce retail shrink. UK grocery chains deploy these in premium ready-to-eat meals to extend distribution radius and verify cold chain integrity.
- Modified Atmosphere Packaging:Gas flushing replaces headspace oxygen with nitrogen or carbon dioxide.
- Active Packaging:Oxygen scavengers and ethylene absorbers extend shelf life without synthetic preservatives.
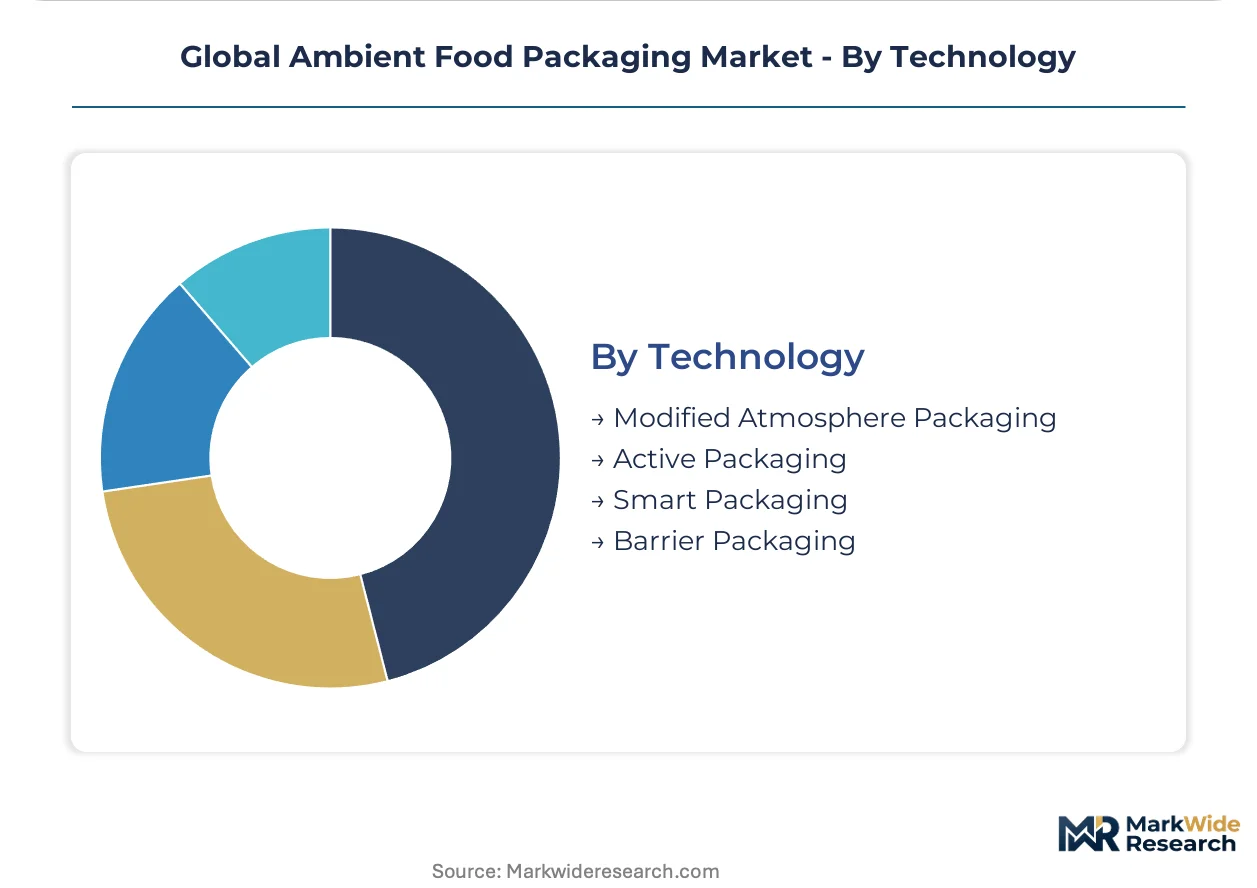
Barrier Packaging holds the volume concentration; smart packaging represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's production-linked incentive zones in Maharashtra and Gujarat are concentrating packaging line investments. Germany's extended producer responsibility frameworks reshape procurement specifications. Indonesia's archipelago logistics gaps sustain ambient-stable demand.
India
Urban retail modernization in Mumbai and Delhi accelerates retort pouch adoption for ambient curry and rice products. FSSAI and the PLI scheme for food processing infrastructure drive domestic compounding capacity expansion. Maharashtra and Gujarat host the fastest packaging line upgrades.
Germany
Ready-to-eat meal specifications tighten around microwave compatibility and EPR compliance under Verpackungsgesetz. EFSA and REACH frameworks restrict perfluorinated compounds in food-contact layers. Paperboard converters in Baden-Württemberg qualify fluorine-free barrier coatings ahead of regulatory deadlines.
United States
Smart packaging sensors penetrate premium ready-to-eat segments as retailers deploy freshness verification. FDA food contact substance notifications govern material migration limits. Flexible packaging demand clusters in snack and condiment applications across Midwest food manufacturing corridors.
Indonesia
Cold chain gaps across outer island retail networks sustain ambient-stable dairy and beverage packaging demand. The country's national food safety regulator enforces composite packaging standards. Java-based converters supply carton systems for UHT milk distribution to Sumatra and Sulawesi.
China
SAMR's GB standards for composite packaging structures create divergent testing protocols that fragment formulation strategies. Yangtze River Delta converters align safety testing with Codex Alimentarius frameworks to reduce dual-certification burdens. Shanghai and Jiangsu provinces lead barrier film production scale.
Global Ambient Food Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multi-material platform suppliers holding structural advantages in qualification-heavy categories. The vendor base organizes around three archetypes: integrated material-science conglomerates, fiber-based packaging specialists, and regional flexible film converters. Consolidation pressure intensifies as retailers consolidate supplier panels and demand volume-commitment pricing. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Within the integrated material-science tier, Amcor Plc and Berry Global Inc. exemplify global manufacturing footprint strategies that sustain multi-material platform supply across divergent regulatory environments. Huhtamaki Oyj occupies a position among fiber-based specialists, anchoring European molded-fiber technology development for shelf-stable applications. Tetra Pak represents the aseptic carton systems archetype, serving ambient beverage and liquid food segments through filling equipment integration. These three companies illustrate how scale, material specialization, and equipment integration create distinct competitive positions.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| WestRock Company |
| Amcor Plc |
| DS Smith Plc |
| Huhtamaki Oyj |
| Tetra Pak |
| Berry Global Inc. |
| Sonoco Products Company |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up flexible film specialists have consolidated regional converter networks across Germany and Poland, tightening working capital discipline and enforcing contract-based volume commitments that anchor pricing stability for multinational food brands.
Pricing Analysis
Short lead-time premiums dominate spot procurement for EVOH and polyamide barrier films, while annual contract structures secure resin allocation at stabilized rates for Tier 1 converters. Pricing stratifies across premium certified grades meeting EFSA migration limits, standard BRCGS-compliant tiers, and economy specifications for non-contact layers. Cost compression in biodegradable alternatives is intensifying because tropical moisture-barrier failures trigger reformulation cycles and scrap losses. Private-label retailers at British grocery chains exhibit acute price sensitivity, whereas aseptic beverage brands prioritize barrier performance over unit economics.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg and Gujarat have delayed commissioning of new barrier film extrusion lines, extending equipment lead times and concentrating output among incumbent asset bases. Northeast Asian petrochemical complexes in South Korea and Japan supply concentrated EVOH and polyamide feedstocks, while Indian domestic compounding capacity expands under PLI incentives. Single-source vulnerability in specialty resin grades exposes converters to allocation risk during maintenance turnarounds. Distribution runs through co-manufacturer networks serving retail private-label programs, with direct-to-retailer procurement shortening specification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility fee structures in Germany and France are compressing margins for small-format flexible specialists, forcing consolidation among regional converters unable to absorb compliance costs.
For Market Incumbents: Deepen backward integration into EVOH compounding to secure resin allocation and hedge Northeast Asian supply concentration. Anchor European fiber-based production in molded-fiber technology to preempt REACH restrictions on fluorinated barriers. Threat: Retailer panel consolidation demands volume-commitment pricing that squeezes mid-tier converter margins. For New Entrants and Emerging Players: Fluorine-free barrier coating platforms offer a technology-first wedge into German paperboard segments ahead of regulatory deadlines. Target Indonesia's outer island dairy distribution networks where cold chain gaps sustain ambient-stable carton demand. White-space opportunity: Retortable mono-material pouches compatible with existing polyethylene recycling infrastructure. Go-to-market angle: SAMR GB standards alignment for dual domestic-export certification. For Investors and Strategic Acquirers: India's PLI scheme announcement for food processing infrastructure is the leading indicator that domestic packaging line upgrades will concentrate demand among qualified suppliers. Long-term viability favors integrated material-science conglomerates with multi-material platforms spanning flexible, rigid, and fiber-based formats. Acquisition target archetype: Regional flexible film converters with established retailer relationships and available extrusion capacity. Signal to watch: FSSAI enforcement tightening on composite packaging migration limits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Resin Compounding | Captive EVOH supply secures allocation priority during Northeast Asian maintenance cycles. |
| Fluorine-Free Coating Platform Development | Silicone and clay-based alternatives qualify ahead of REACH perfluorinated substance restrictions. |
| Retortable Mono-Material Pouch Scale-Up | Polypropylene barrier innovations unlock circular economy positioning with existing recycling streams. |
| Smart Packaging Sensor Integration | Time-temperature indicators reduce retail shrink and extend distribution radius for premium ready-to-eat meals. |
| Direct-to-Retailer Procurement Consolidation | Volume-commitment pricing secures multi-year category exclusivity in high-penetration private-label segments. |
Methodological Framework
Multi-period observation of EVOH resin pricing spreads, EFSA compliance qualification timelines, and retailer panel consolidation patterns anchored the trend analysis, supplemented by interviews with plant managers at European flexible film converters, procurement leads at German food brands, technical R&D directors at barrier coating suppliers, and category buyers at British grocery chains. Secondary validation drew from customs trade data on ethylene vinyl alcohol imports, SEC 10-K filings of listed packaging conglomerates, Cefic plastics industry reports, and EFSA scientific opinions on food contact materials. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices mapped resin feedstock costs, barrier performance specifications, and regulatory compliance tiers across product type, material, end-use, and technology segments. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends across the analysis window. Industry-specific forecast inputs included PLI scheme disbursement schedules in Maharashtra and Gujarat, and REACH restriction implementation timelines for perfluorinated compounds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EVOH supply disruption or accelerated EPR fee escalation. Projections reflect documented assumptions on regulatory enforcement intensity and resin capacity commissioning schedules. Material deviation in FSSAI migration limit tightening or Indonesia cold chain investment trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Ice Cream Packaging Market