
 Ice Cream Packaging Market | 2026-2036
Ice Cream Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Packaging Market Outlook
Subscription-based packaging redesign services is rebalancing how converters engage frozen dessert brands. Sonoco Products Company leverages its fiber-based engineering network to anchor North American supply for premium ice cream tubs. Huhtamaki Oyj sustains competitive positioning through specialized molded-fiber capabilities in European dairy corridors. Amcor Plc dominates flexible lidding films for multi-pack novelty formats across Australasian markets.
Ice cream packaging encompasses barrier-coated containers, closure systems, and secondary wrapping engineered to maintain thermal stability and prevent flavor migration at temperatures below -18°C. Paperboard tubs with polyethylene or bio-based moisture barriers constitute the primary structural format for premium retail pints, while plastic tubs and lidding films retain volume leadership in single-serve and gallon formats. Closure type segmentation reveals screw-cap systems capturing margin pools in resealable premium lines, whereas snap-on lids occupy cost-optimized wholesale gallon segments. Size segmentation shows single-serve formats expanding fastest through convenience retail and food service channels, while quart containers face maturity in traditional grocery.
FDA food-contact regulations govern barrier coatings and substrate migration limits in US ice cream packaging, while the EU's F-Gas Regulation and REACH framework restrict certain plasticizers and propellants used in insulated shipping materials. BIS standards in India mandate specific labeling and material safety thresholds for frozen dairy packaging entering retail distribution. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling infrastructure investments before committing to material platform transitions.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing material transition timelines across frozen dessert supply chains, forcing converters to requalify barrier coatings and substrate platforms ahead of enforcement deadlines.
Growth Catalysts
- REACH framework compliance:Dairy processors in Germany and France are accelerating adoption of bio-based moisture barriers to preempt registration requirements for conventional polyethylene coatings.
- Premium artisanal segment expansion:Small-batch ice cream producers are specifying molded-fiber tubs with specialized closure systems to differentiate shelf presence in specialty retail.
- India FSSAI frozen dairy standards:Packaged ice cream penetration is rising in tier-two cities as labeling mandates create quality signaling mechanisms for organized retail entry.
Market Restraints
- Recycled pulp supply concentration:European paperboard converters face input cost volatility as Nordic mills control the majority of food-grade recycled fiber capacity.
- Barrier performance trade-offs:Bio-based coatings from polylactic acid and starch blends exhibit inferior moisture vapor transmission rates versus polyethylene at sub-zero temperatures.
- Extended producer responsibility schemes:Germany's VerpackG and France's Citeo eco-modulation fees are adding compliance overhead without mature recycling infrastructure for coated paperboard streams.
Strategic Opportunities
- Indonesia dairy corridor development:Cold chain investments by domestic processors are creating first-mover openings for aseptic filling and barrier packaging suppliers.
- Digital printing convergence:Variable-data decoration on paperboard tubs enables hyper-localized flavor launches and promotional versioning without plate changeover costs.
- EU Green Deal carbon border adjustments:Importing producers face incentive alignment to source European-manufactured packaging with verified lower embodied carbon.
Industry Challenges
- Thermal engineering talent scarcity:Few packaging engineers possess combined expertise in polymer science and cryogenic logistics required for insulated shipping format development.
- Legacy filling line retrofit costs:Dairy plants operating mechanical sealing equipment face capital-intensive upgrades to handle fiber-based tub rigidity and dimensional tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Packaging Market |
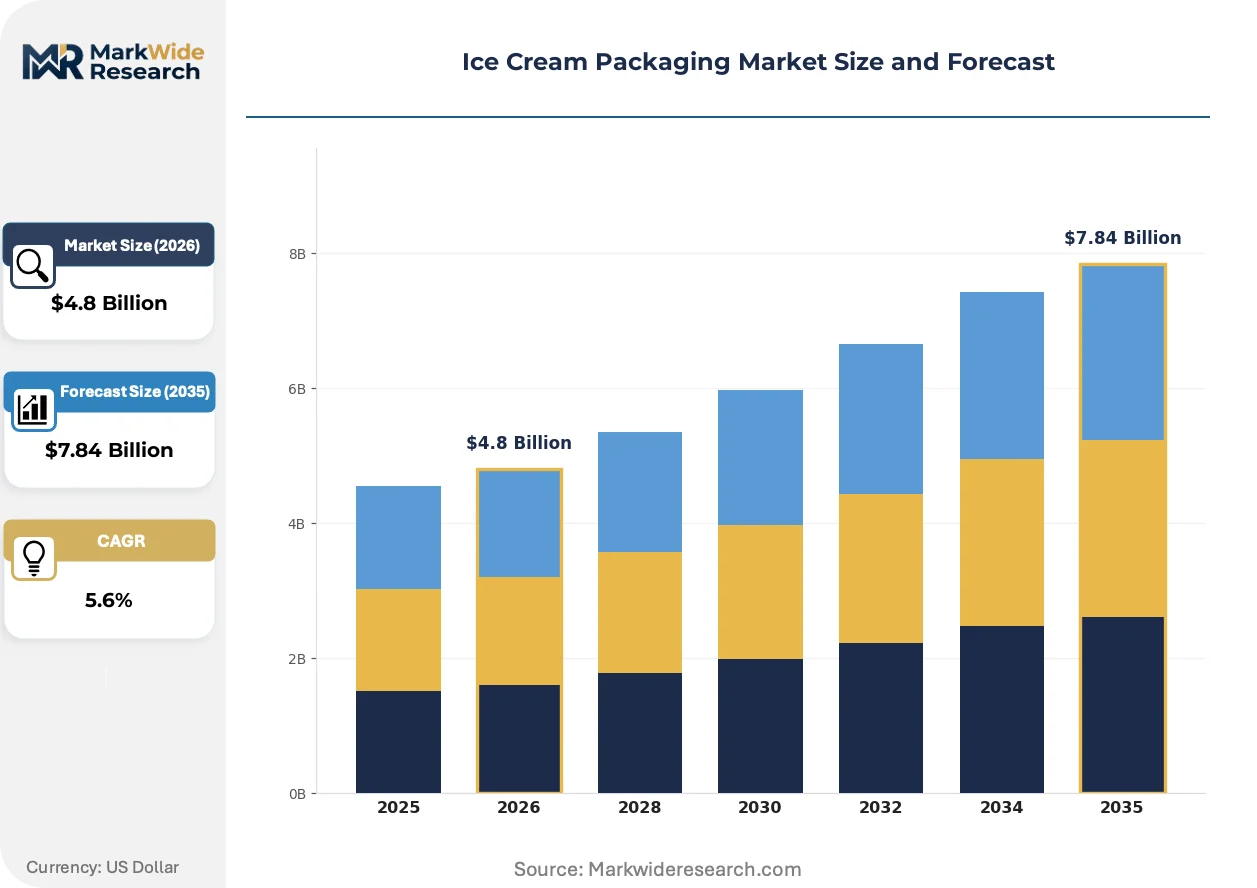
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paperboard, Glass, Metal Closure Type: Screw Cap, Snap On, Twist Off, Pull Tab Size: Single Serve, Pint, Quart, Gallon End User: Retail, Wholesale, Food Service, Online |
| Companies Covered | Sonoco Products Company, Tetra Laval, Amcor Plc, Sealed Air, INDEVCO, ITC Packaging, Berry Global Group, International Paper, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Packaging Market Strategic Shifts
Barrier coating chemistry and closure system engineering are converging to solve the central technical tension in frozen dessert packaging: maintaining thermal stability while eliminating fossil-derived substrates.
Molded-fiber tubs with spray-applied bio-barriers are consolidating technical validation pathways across European dairy processors. Sonoco and Huhtamaki have scaled pilot lines with German cooperatives to demonstrate runnability at commercial speeds. This consolidation is compressing the qualification window for conventional plastic tub suppliers who lack fiber-forming assets.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant coatings previously standard in premium ice cream packaging. The ECHA sunset dates are triggering supply contract renegotiations across the 2024-2027 window. Scandinavian brands are responding earliest, with Orkla and Arla accelerating migration to silicone-based barrier alternatives.
Direct-to-consumer subscription channels are fragmenting order patterns and compressing production runs. Small-batch brands in the United States are unbundling from traditional co-packer minimums by specifying digitally printed short-run tubs. This behavioral shift is most visible in California and New York metro corridors where micro-creameries bypass grocery distribution entirely.
Ice Cream Packaging Market Segmentation
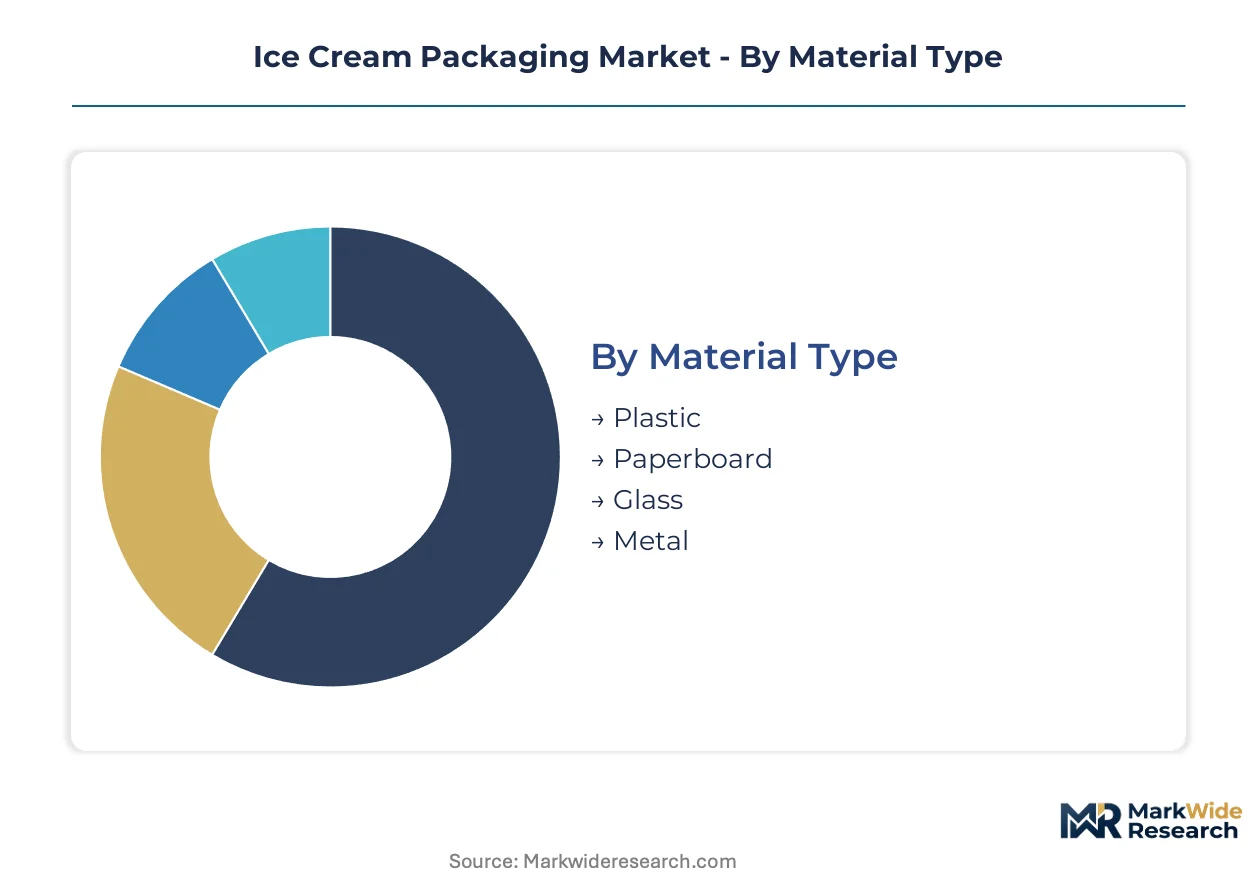
Segmentation in ice cream packaging reveals how thermal performance requirements and regulatory pressures fragment converter capabilities across substrate platforms. Material selection and closure engineering determine margin capture, while size and channel configurations shape capital deployment strategies for filling line investments.
Material Type:
Cost tier differentiation drives procurement decisions, with barrier performance requirements escalating from economy bulk formats to premium single-serve lines.
- Plastic:Polypropylene and polyethylene terephthalate tubs dominate gallon and multi-pack novelty formats through superior moisture vapor transmission resistance at -18°C. Dairy processors in the United States specify injection-molded polypropylene for mechanical filling line compatibility and dimensional stability during cryogenic distribution.
- Paperboard:Barrier-coated fiber tubs command premium pint positioning through sustainability signaling and printability for artisanal brand differentiation. German cooperatives are accelerating molded-fiber adoption ahead of EU Single-Use Plastics Directive enforcement deadlines.
- Glass:Limited to ultra-premium gift and specialty formats where inert substrate properties justify weight and fragility trade-offs.
- Metal:Tinplate and aluminum retain niche positions in frozen novelties with stick formats and seasonal promotional packs.
Plastic leads on scale; paperboard leads on momentum.
Closure Type:
Application-specific sealing requirements separate resealable premium retail formats from single-use food service and wholesale configurations.
- Screw Cap:Threaded polypropylene closures enable repeated opening cycles for premium pint lines targeting home consumption. French dairy brands specify torque-controlled screw systems to prevent freezer burn across multi-week storage intervals.
- Snap On:Press-fit polyethylene lids dominate cost-optimized gallon formats through minimal material usage and high-speed filling line compatibility. US wholesale private label programs favor snap-on economics for club store volume commitments.
- Twist Off:Metal lug closures appear in glass jar formats for specialty dessert and gelato positioning.
- Pull Tab:Aluminum tear-away systems serve single-serve novelty bars and frozen confection sticks.
Snap-on closures dominate volume throughput; screw-cap systems command margin premiums.
Size:
Customer type and consumption occasion stratify format demand, with convenience retail and food service channels fragmenting traditional grocery volume concentration.
- Single Serve:Individually wrapped bars and cups target impulse purchase and on-premise consumption through minimal unit economics. Convenience retail chains in Japan and South Korea are expanding grab-and-go freezer sets for commuter and office park locations.
- Pint:Four-hundred-fifty-milliliter fiber tubs anchor premium artisanal positioning with direct-to-consumer subscription compatibility. California micro-creameries leverage pint formats to bypass traditional grocery distribution minimums.
- Quart:Traditional family-size containers face demand maturity as household size reduction shifts volume toward smaller formats.
- Gallon:Bulk polyethylene tubs retain institutional and club store concentration despite retail downsizing trends.
Gallon formats retain institutional scale; single-serve lines are expanding most quickly through convenience channel penetration.
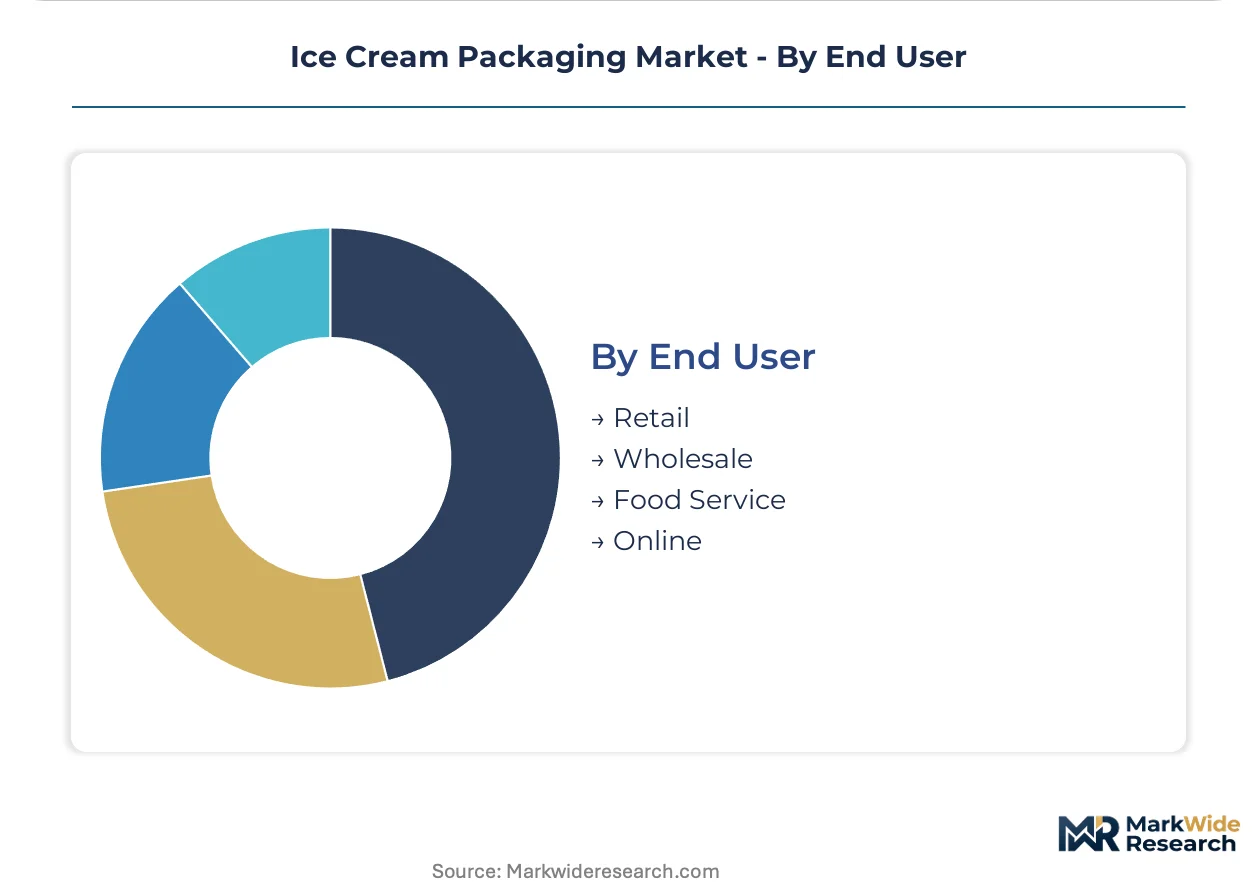
End User:
Volume and margin concentration diverge across channel types, with retail premiumization running counter to wholesale cost optimization.
- Retail:Branded and private label grocery placement demands shelf-ready secondary packaging and seasonal promotional versioning. German supermarket chains are mandating recyclable paperboard primary packaging for own-label ice cream entries.
- Wholesale:Club store and distributor formats prioritize palletization efficiency and extended frozen storage compatibility over primary decoration. Costco and Sam's Club specifications drive gallon-format standardization.
- Food Service:Scoop shop and restaurant bulk supply requires bag-in-box or cylindrical tubs optimized for high-turnover dipping cabinets.
- Online:Direct-to-consumer shipment demands insulated secondary packaging with dry ice compatibility and unboxing experience design.
Retail channels concentrate value capture; online fulfillment represents the steepest expansion trajectory for specialized thermal protection formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dairy cooperatives invest more aggressively in molded-fiber packaging conversion than their United States counterparts, where mechanical filling line inertia slows substrate transitions. This divergence shapes converter capital allocation across both markets.
United States
FDA food-contact regulations govern barrier coating migration limits for frozen dairy distribution. California micro-creameries bypass traditional grocery minimums through direct-to-consumer pint subscriptions. The Pacific Northwest hosts emerging digitally printed short-run tub specialists serving fragmented artisanal order patterns.
Germany
VerpackG extended producer responsibility fees pressure converters to requalify recyclable paperboard streams ahead of enforcement deadlines. The EU's Single-Use Plastics Directive accelerates molded-fiber adoption in Bavarian dairy processing corridors. North Rhine-Westphalia concentrates mechanical engineering talent for legacy filling line retrofit programs.
India
FSSAI frozen dairy labeling mandates create quality signaling mechanisms for organized retail entry in tier-two cities. BIS material safety thresholds govern substrate specifications for domestic distribution. Maharashtra's dairy processing clusters near Mumbai and Pune attract barrier packaging suppliers for aseptic filling expansion.
Indonesia
Cold chain investments by domestic processors generate first-mover openings for thermal protection packaging suppliers. The national food and drug regulator enforces labeling and material safety standards for frozen dairy retail entry. Java's dairy corridor development concentrates near Jakarta and Surabaya metropolitan zones.
France
Citeo eco-modulation fees add compliance overhead for coated paperboard recycling streams without mature infrastructure. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force barrier coating reformulation across premium ice cream lines. The Auvergne-Rhône-Alpes region anchors dairy cooperative packaging specification leadership.
Ice Cream Packaging Market Competitive Environment
Top-tier vendors anchor substrate platform transitions, while mid-tier specialists occupy regional filling line retrofit niches. The vendor base stratifies across fiber-forming asset owners, flexible film specialists, and integrated paperboard converters. Three archetypes dominate: multinational packaging conglomerates with cryogenic logistics expertise, regional molded-fiber engineering houses, and flexible lidding film specialists. Capacity expansion and strategic technology licensing represent the dominant competitive moves as converters race to requalify barrier coatings ahead of regulatory deadlines.
Within the multinational conglomerate tier, Sonoco Products Company and Huhtamaki Oyj exemplify divergent geographic anchoring strategies for premium frozen dessert packaging supply. Sonoco's fiber-based engineering network occupies a position in North American premium tub markets, while Huhtamaki's molded-fiber capabilities concentrate in European dairy corridors. Amcor Plc represents the flexible film specialist archetype across Australasian multi-pack novelty segments. These three entities illustrate how substrate-specific asset bases determine competitive positioning as regulatory pressure forces material platform transitions.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Tetra Laval |
| Amcor Plc |
| Sealed Air |
| INDEVCO |
| ITC Packaging |
| Berry Global Group |
| International Paper |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
EU Single-Use Plastics Directive compliance mandates are forcing dairy processors to requalify barrier-coated substrates ahead of enforcement deadlines, compelling converters to absorb qualification costs while passing through material premiums for bio-based alternatives. This demand-side specification shift concentrates pricing power among fiber-forming asset owners with validated molded-fiber capabilities.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for barrier-coated paperboard as Nordic mills expand food-grade recycled fiber output. Three-tier pricing structure across premium artisanal, standard retail, and economy bulk levels reflects substrate performance and sustainability certification tiers. Pricing pressure stems from bio-barrier coating scale-up costs as PLA and starch blends underperform polyethylene at cryogenic temperatures. Wholesale gallon buyers exhibit highest price sensitivity, while premium pint subscription channels accept material premiums for molded-fiber differentiation.
Supply Chain Analysis
Dual-sourcing requirements from German dairy cooperatives mandate qualified backup suppliers for both fiber-based tubs and flexible lidding films, compressing single-source dependencies. Supply concentrates in Finland, Sweden, and Germany for food-grade recycled pulp, while flexible film extrusion anchors in China and South Korea. Raw material dependencies span Nordic recycled fiber, bio-based PLA resins, and aluminum lidding foil. Tariff exposure on coated paperboard imports from non-EU origins presents structural risk. Distribution runs through dairy processor co-packer networks with direct-to-consumer channels fragmenting traditional wholesale consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ice cream packaging market functions as a stable compounder, with regulatory-driven substrate transitions providing sustained demand visibility for qualified converters across the forecast horizon.
For Market Incumbents: Anchor fiber-forming capacity in Bavarian and North Rhine-Westphalia dairy corridors ahead of VerpackG enforcement deadlines. Backward integration into barrier coating chemistry secures margin capture as REACH Annex XVII restrictions eliminate PFAS-based alternatives. Defend against flexible film specialists by locking multi-year co-packer agreements with tier-one German cooperatives. For New Entrants and Emerging Players: Launch via digitally printed short-run tub services targeting California and New York metro micro-creameries bypassing grocery minimums. Indonesia's Java dairy corridor offers first-mover whitespace as cold chain investments outpace local barrier packaging supply. Position around aseptic filling compatibility for emerging market processor expansion. For Investors and Strategic Acquirers: Asymmetric upside sits with regional molded-fiber engineering houses possessing validated European dairy qualifications and scalable bio-barrier coating partnerships. Five-to-ten year viability hinges on extended producer responsibility scheme maturation and recycling infrastructure buildout. Monitor Citeo eco-modulation fee revisions as inflection signal for coated paperboard stream economics.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Barrier Coating Scale-Up | REACH Annex XVII compliance secures German and French dairy processor qualification windows. |
| Molded-Fiber Asset Acquisition | VerpackG enforcement concentrates value capture among EU-qualified fiber-forming converters. |
| Digital Printing Platform Deployment | Variable-data decoration enables California micro-creamery hyper-localized flavor launches. |
| Indonesia Dairy Corridor Partnership | Cold chain investments by domestic processors create thermal protection packaging demand. |
| Legacy Filling Line Retrofit Services | Mechanical sealing equipment upgrades address fiber-based tub rigidity tolerance requirements. |
Study Parameters
Multiple input streams — primary interviews with dairy procurement directors, barrier coating R&D leads, and co-packer operations managers; secondary validation through EU ECHA regulatory filings, BIS material safety standards, and FSSAI frozen dairy labeling mandates; plus trade data from Nordic pulp mill associations and dairy processor association reports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across material type, closure system, format size, and end-user channel segmentation throughout the forecast period. CAGRs were derived from substrate transition timelines tied to regulatory enforcement windows and processor capital expenditure cycles. Modeled inputs incorporated EU Single-Use Plastics Directive compliance costs and bio-based barrier coating performance validation timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, breakthrough barrier coating chemistry displacing incumbent platforms, and macroeconomic shocks to dairy commodity pricing. Deviation in extended producer responsibility fee structures or recycling infrastructure deployment pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Asia Pacific Food Packaging Market