
 Europe Chocolate Packaging Market | 2026-2036
Europe Chocolate Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chocolate Packaging Market Insights
Asset-light leasing arrangements for converting equipment is tilting competitive dynamics toward mid-tier converters who previously lacked capital for rotary die-cutting and foil stamping lines. Mondi Group leverages its integrated paperboard mills to sustain margin control across kraft liner supply. Smurfit Kappa Group Plc anchors its position through corrugated box specialization for seasonal gift formats. Huhtamaki Oyj differentiates via molded fiber capabilities that serve premium chocolate trays.
Europe chocolate packaging encompasses primary and secondary enclosures designed to protect cocoa-based confectionery from moisture, oxygen, and thermal degradation while enabling brand differentiation at point of sale; specifications include barrier coatings ranging from 12-micron aluminum laminates to water-based varnishes applied through flexographic or rotogravure processes. Paperboard dominates structural applications for rigid gift boxes and folding cartons where print fidelity and structural rigidity determine shelf impact. Plastic retains share in flow-wrap and twist-wrap formats for countline bars despite regulatory pressure. Aluminum occupies a specialized niche in foil-wrapped premium assortments where hermetic sealing extends shelf life.
The EU Green Deal and Packaging and Packaging Waste Regulation mandate recyclability targets and extended producer responsibility schemes that reshape material selection across the value chain. REACH and F-Gas Regulation govern chemical inputs and solvent-based printing processes, compelling converters to validate water-based ink systems. ECHA substance restrictions on per- and polyfluoroalkyl substances threaten existing grease-resistant coatings, forcing reformulation timelines. Stakeholders must monitor delegated acts under the PPWR that will define harmonized recyclability performance grades before committing to multi-million-euro coating line investments.
Market Dynamics
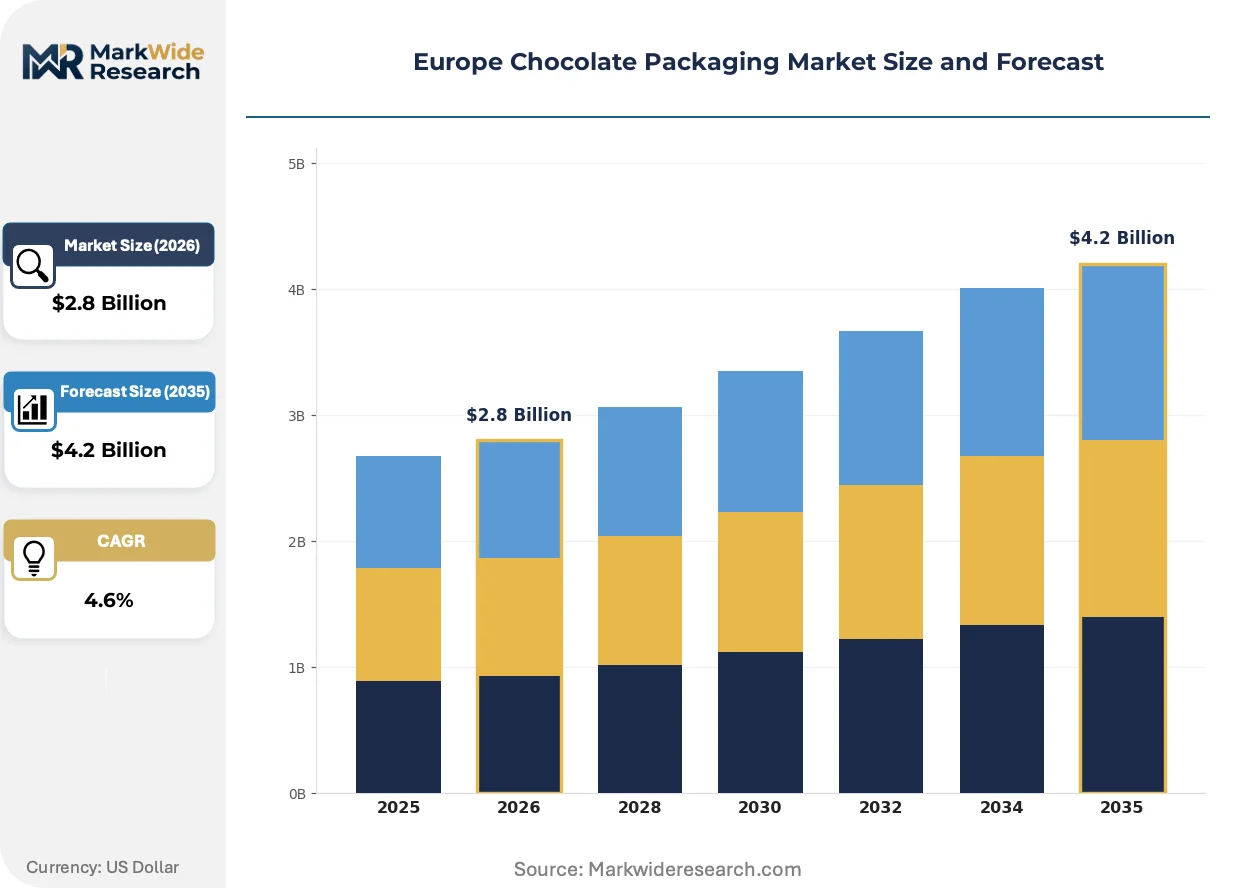
The EU Green Deal and Packaging and Packaging Waste Regulation are compressing material transition timelines across European chocolate packaging, forcing converters to validate water-based coating systems and recyclable substrates before delegated acts define harmonized performance grades.
Growth Catalysts
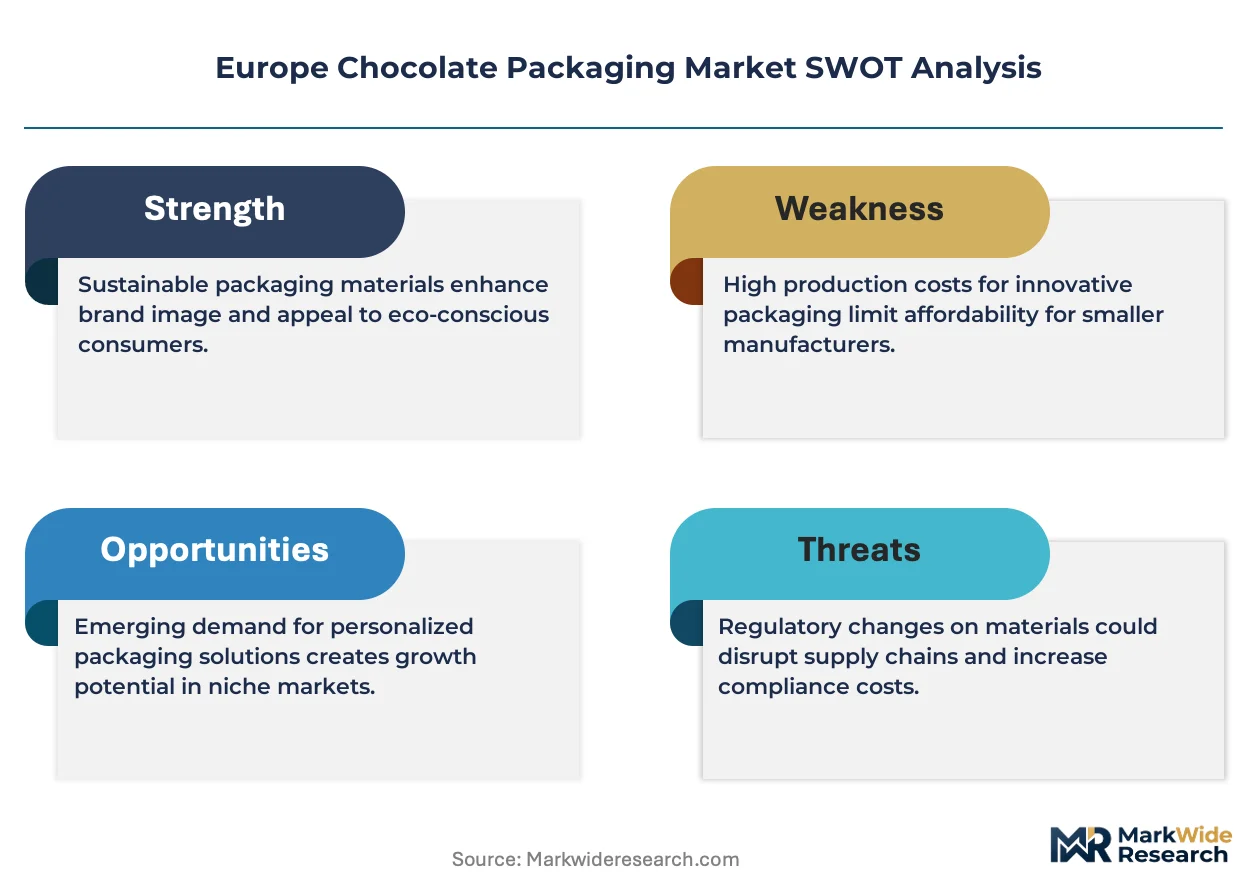
- Belgium Premium Segment Expansion:Heritage chocolate houses are mandating molded fiber trays and aluminum-laminated foil wraps for assortments, pulling specialized converting capacity toward Antwerp and Brussels industrial zones.
- REACH Chemical Reformulation:ECHA substance restrictions on per- and polyfluoroalkyl substances are accelerating grease-resistant coating innovation, creating first-mover advantage for converters with validated water-based barrier systems.
- Rotary Die-Cutting Equipment Leasing:Asset-light financing models are democratizing access to foil stamping and embossing lines, enabling mid-tier converters to bid on seasonal gift formats previously locked by capital barriers.
Market Restraints
- Kraft Liner Supply Concentration:Integrated paperboard mills in Nordic regions control virgin fiber supply for chocolate box substrates, exposing independent converters to input cost volatility and allocation priority schemes.
- Aluminum Foil Technical Limitation:Hermetic sealing requirements for premium assortments prevent full substrate substitution, locking certain formats into specialized converting capacity with limited geographic distribution.
- Extended Producer Responsibility Friction:Divergent national implementations of EU Packaging and Packaging Waste Regulation fee structures are creating compliance cost uncertainty for multi-country brand owners.
Strategic Opportunities
- Poland Regional Manufacturing Hub:Central European location and lower converting cost base position Warsaw and Krakow corridors to capture overflow demand from German packaging procurement functions.
- E-Commerce Direct-to-Consumer Channel:Unboxing experience requirements are creating specification divergence from retail formats, opening niche for protective yet decorative corrugated solutions with print personalization.
- Digital Print-Converting Convergence:Integration of inkjet decoration with inline cutting and creasing is enabling short-run seasonal customization without plate changeover downtime.
Industry Challenges
- Rotogravure-to-Flexographic Skill Migration:Solvent-based printing expertise pools are aging while water-based ink system technicians remain scarce, compressing workforce transition timelines.
- Multi-Million-Euro Coating Line Capex:Barrier validation requirements for PPWR recyclability grades demand speculative investment before delegated acts clarify performance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chocolate Packaging Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Box, Wrapper, Pouch, Sleeve Material: Paperboard, Plastic, Aluminum, Glass Closure Type: Seal, Snap, Zip, Lid End User: Retailers, Manufacturers, Wholesalers, E-commerce |
| Companies Covered | Amcor Plc, Smurfit Kappa Group Plc, Mondi Group, WestRock Co., Huhtamaki Oyj, AS Food Packaging, ATP - Engineering & Packaging SL, John C. Brow Ltd., Wihuri International Oy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chocolate Packaging Market Trends and Innovations
Material science advances and regulatory compression are converging to reshape European chocolate packaging specifications, with digitization of production workflows and substrate traceability emerging as decisive capability differentiators.
Digital print engines equipped with inline spectrophotometric color control are digitizing quality assurance across short-run seasonal campaigns. Swiss and Belgian premium manufacturers are adopting these systems for limited-edition assortments. The technology is digitizing proof-to-production cycles from weeks to hours, compressing time-to-market for holiday-specific formats.
EU F-Gas Regulation phase-down schedules are accelerating solvent recovery system investments across rotogravure operations. Converters in Germany and Austria face capital allocation decisions between aqueous ink migration and carbon-intensive solvent containment. Chocolate countline segments with high volume and lower print fidelity requirements are pivoting fastest to water-based flexographic systems.
Brand-owner sustainability scorecards are reshaping supplier qualification protocols across European procurement functions. Tier-one chocolate manufacturers are unbundling packaging awards by environmental performance tier rather than unit cost alone. This behavioral shift is most pronounced in Netherlands and UK operations where retailer-facing brands face downstream pressure for packaging recyclability claims.
Europe Chocolate Packaging Market Segmentation
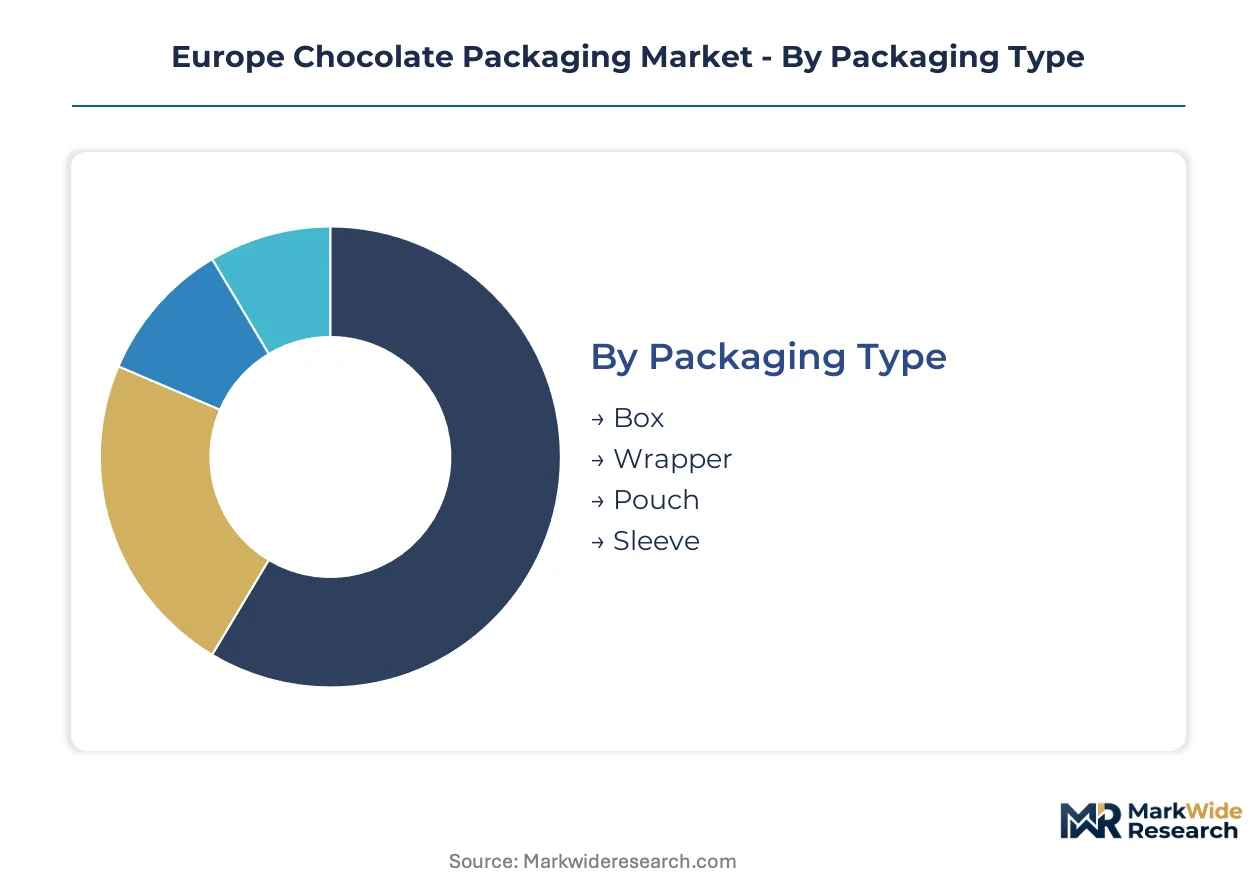
Segmentation reveals how EU Green Deal compliance costs and premium brand requirements fragment converting capacity across material types and closure specifications. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape supplier selection criteria.
Packaging Type:
Structural format determines barrier performance requirements and print decoration complexity across chocolate confectionery applications.
- Box:Rigid paperboard constructions with foil stamping and embossing dominate seasonal gift assortments. Belgian and Swiss heritage manufacturers concentrate procurement for premium assortments in Antwerp and Brussels industrial corridors, pulling specialized die-cutting capacity toward Benelux.
- Wrapper:Flow-wrap and twist-wrap formats serve countline bars with high-speed converting requirements. Germany's centralized packaging procurement functions drive volume specifications for this segment, favoring converters with rotogravure or flexographic lines.
- Pouch:Stand-up and flat pouch configurations accommodate sharing formats and resealable premium lines.
- Sleeve:Shrink and cardboard sleeve formats provide 360-degree print real estate for brand storytelling on multi-packs.
Box formats command the established base. The steepest expansion runs through Pouch configurations as resealable premium lines multiply.
Material:
Substrate selection tracks directly against EU Packaging and Packaging Waste Regulation recyclability mandates and ECHA substance restrictions.
- Paperboard:Virgin and recycled fiber grades with water-based barrier coatings now dominate rigid applications. Nordic integrated mills control kraft liner supply, exposing independent converters to allocation priority schemes during peak seasonal demand.
- Plastic:Polypropylene and polyethylene laminates retain flow-wrap share despite regulatory pressure, with converters validating mono-material structures for upcoming PPWR recyclability grades.
- Aluminum:12-micron foil laminates provide hermetic sealing for premium assortments where shelf life extension justifies specialized converting costs.
- Glass:Limited to ultra-premium gifting formats with high breakage risk and transport weight penalties.
Paperboard holds the volume base. Plastic is climbing the fastest as mono-material innovation unlocks compliance pathways ahead of delegated acts.
Closure Type:
Sealing mechanism determines barrier integrity duration and consumer convenience positioning across consumption occasions.
- Seal:Heat-sealed and adhesive closures dominate single-serve formats with hermetic requirements.
- Snap:Rigid box closures with magnetic or friction-fit mechanisms elevate unboxing experience for gift segments.
- Zip:Press-to-close resealable systems capture sharing-format demand in UK and Netherlands retail channels.
- Lid:Hinged or separate lid constructions for rigid boxes and trays enable repeated access without structural degradation.
Seal configurations anchor the installed base. Zip mechanisms gain share fastest as resealability becomes a procurement scoring criterion.
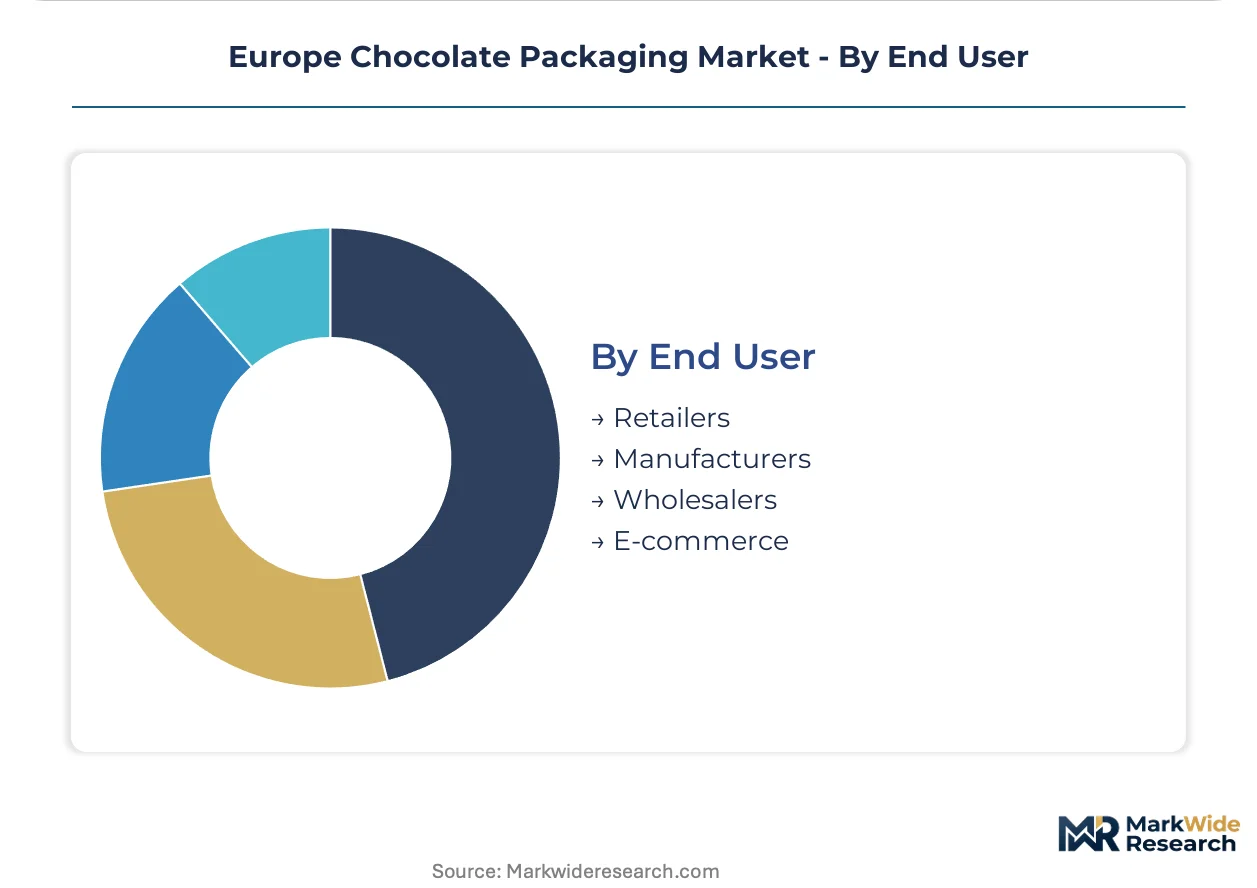
End User:
Channel-specific requirements create specification divergence between retail-facing and direct-to-consumer formats.
- Retailers:Supermarket and specialty store channels demand shelf-ready packaging with standardized case counts and pallet optimization. German retail consolidation drives centralized procurement with sustainability scorecard requirements.
- Manufacturers:Contract packaging and co-manufacturing relationships require flexible converting capacity for short-run seasonal campaigns.
- Wholesalers:Bulk distribution channels prioritize case efficiency and transport durability over point-of-sale decoration.
- E-commerce:Direct-to-consumer shipments require protective corrugated outer packs with print personalization capabilities for unboxing experience differentiation.
Retailers dominate the established demand base. E-commerce represents the steepest expansion trajectory as chocolate brands build direct channel infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented chocolate packaging capacity clusters in northwestern Europe, with Benelux and German converters supplying heritage brands across the continent. Import dependency for specialized aluminum laminates and molded fiber equipment creates cross-border supply chain interlocks that shape regional procurement patterns.
Germany
Centralized packaging procurement functions at major chocolate manufacturers drive volume specifications for countline and seasonal formats. REACH chemical reformulation mandates from ECHA accelerate water-based coating validation programs across converting operations. The Cologne-Düsseldorf industrial corridor concentrates rotogravure and flexographic capacity serving retail-facing brands with sustainability scorecard requirements.
Belgium
Heritage chocolate houses in Antwerp and Brussels mandate molded fiber trays and aluminum-laminated foil wraps for premium assortments. EU Green Deal packaging waste targets pull specialized die-cutting capacity toward Benelux industrial zones. The Port of Antwerp cluster handles inbound kraft liner supply from Nordic integrated mills for rigid gift box substrates.
Switzerland
Premium confectionery brands prioritize hermetic sealing specifications that sustain aluminum foil demand despite substrate substitution pressure elsewhere. Swissmedic-adjacent quality protocols influence barrier coating validation standards across neighboring supply chains. The Zurich-Basel corridor hosts specialized converting capacity for ultra-premium gifting formats with magnetic closure systems.
Poland
Central European location and lower converting cost base position Warsaw and Krakow corridors to capture overflow demand from German procurement functions. EU Packaging and Packaging Waste Regulation implementation creates compliance cost arbitrage for multi-country brand owners. Silesian industrial zones develop corrugated specialization for e-commerce direct-to-consumer protective outer packs.
Netherlands
Retailer-facing brands face downstream pressure for packaging recyclability claims that reshape supplier qualification protocols. Rotterdam port infrastructure facilitates Nordic paperboard import for folding carton applications. The Randstad cluster concentrates digital print-converting integration for short-run seasonal customization without plate changeover downtime.
Europe Chocolate Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated paperboard producers and specialized converting groups with barrier coating capabilities. Tier-one packaging groups anchor volume positions through captive mill supply, while mid-tier converters exploit equipment leasing to penetrate seasonal gift segments. Two strategic archetypes dominate: Nordic-integrated paperboard suppliers controlling virgin fiber allocation, and Benelux-based specialists in premium foil-laminated formats. Competitive moves concentrate on backward integration into kraft liner production and geographic expansion into Polish manufacturing corridors.
Among Nordic-integrated suppliers, Mondi Group and Huhtamaki Oyj exemplify the paperboard-to-converting control archetype that sustains margin positions across volatile fiber input cycles. Smurfit Kappa Group Plc occupies a position within the corrugated specialization tier, anchoring capacity for protective e-commerce formats. These three entities represent distinct strategic postures: captive fiber supply, molded fiber premium positioning, and corrugated scale economies respectively.
| Leading Market Players |
|---|
| Amcor Plc |
| Smurfit Kappa Group Plc |
| Mondi Group |
| WestRock Co. |
| Huhtamaki Oyj |
| AS Food Packaging |
| ATP - Engineering & Packaging SL |
| John C. Brow Ltd. |
| Wihuri International Oy |
| Others |
Pricing and Supply Chain Analysis
The Cologne-Düsseldorf industrial corridor concentrates rotogravure and flexographic converting capacity for German chocolate manufacturers, translating supply scarcity into pricing leverage for operators with validated water-based barrier systems. Nordic integrated mills control virgin kraft liner allocation, exposing independent converters to input cost volatility that compresses margins during peak seasonal demand.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on FSC certification status and hermetic sealing performance, while standard tiers compete on volume scale and geographic delivery optimization. Cost compression in economy tiers intensifies because mono-material plastic innovation unlocks compliance pathways ahead of PPWR delegated acts. Private-label retail buyers exhibit highest price sensitivity; heritage Belgian and Swiss houses show lowest sensitivity due to sustainability scorecard prioritization.
Supply Chain Analysis
EU REACH substance restrictions on per- and polyfluoroalkyl substances limit grease-resistant coating technology flows, constraining converter qualification timelines. Raw material supply draws from Nordic integrated paperboard mills, German specialty chemical formulators, and Benelux aluminum foil laminators. Single-source vulnerability concentrates in virgin kraft liner allocation controlled by Mondi Group and Smurfit Kappa captive production. Distribution runs through centralized procurement functions at major chocolate manufacturers, with Antwerp and Rotterdam port clusters handling inbound fiber supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated water-based barrier coating expertise represents the critical scarcity asset in this market, with workforce transition timelines compressing faster than technical validation cycles can replenish capability pools.
For Market Incumbents: Insulate margin positions through backward integration into kraft liner production and captive coating line capacity in Polish manufacturing corridors. ECHA substance restriction timelines threaten existing PFAS-based grease-resistant formulations, making water-based system validation the priority capability investment. Geographic expansion into Silesian industrial zones captures e-commerce protective pack demand while hedging Benelux cost inflation. For New Entrants and Emerging Players: Mid-tier seasonal gift converters in Poland and Czechia represent the most penetrable entry point, where equipment leasing models democratize access to rotary die-cutting and foil stamping lines. Resealable zip-closure pouch formats for UK and Netherlands retail channels offer specification divergence from incumbent rigid box specialization. Go-to-market through digital print-converting integration for short-run holiday customization bypasses plate changeover capital barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance arbitrage play because EU Green Deal implementation timelines create multi-year capability scarcity windows. Acquisition targets should screen for validated water-based barrier coating programs and established relationships with German centralized procurement functions. The signal to watch is ECHA delegated act publication defining harmonized PPWR recyclability performance grades, which will trigger coating line investment decisions across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Validation | ECHA PFAS restrictions force reformulation timelines that reward first-mover converters with certified systems. |
| Polish Manufacturing Corridor Expansion | Central European location and lower converting cost base capture overflow from German procurement centralization. |
| Digital Print-Converting Integration | Inline inkjet decoration with spectrophotometric color control compresses proof-to-production cycles for seasonal campaigns. |
| Molded Fiber Premium Tray Capacity | Belgian and Swiss heritage manufacturers mandate sustainable tray formats that pull specialized capacity toward Benelux. |
| Mono-Material Plastic Structure Development | PPWR recyclability targets drive innovation in flow-wrap formats previously locked into multi-layer laminates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with packaging procurement directors at tier-one chocolate manufacturers, converting plant managers in Benelux and German industrial corridors, sustainability compliance officers at Nordic integrated paperboard mills, and barrier coating R&D leads at specialty chemical formulators. Secondary validation incorporated EU Packaging and Packaging Waste Regulation delegated act tracking, ECHA substance restriction timelines, FSC and PEFC chain-of-custody certification databases, and customs trade data for kraft liner and aluminum foil flows. Bottom-up capacity assessments at converting facilities were triangulated against top-down demand modeling from chocolate production volumes.
Calibration against historical material transition patterns in adjacent food packaging segments informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, closure mechanism, and end-user channel, with additional granularity on sustainability certification tier and seasonal versus year-round format mix. CAGRs were derived from volume-weighted growth rates across these segments, incorporating regulatory compliance cost trajectories and brand-owner sustainability scorecard adoption curves as industry-specific forecast inputs.
Practitioners should monitor ECHA delegated act publication schedules and Nordic mill allocation priority schemes for early signals of supply constraint or compliance cost acceleration. Forecasts reflect assumptions on PPWR implementation timelines, water-based coating validation success rates, and equipment leasing penetration among mid-tier converters. Material shifts in EU Green Deal enforcement intensity or unexpected PFAS restriction acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
North America Food Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Pie Packaging Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Burger Boxes Market