
 Peelable Pouches Market | 2026-2036
Peelable Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Peelable Pouches Market Analytics
ISO 11607 certification for sterile barrier systems is unwinding competitive access in medical-grade peelable pouches, forcing smaller converters toward subcontracting or exit. Amcor plc leverages its multi-site sterilization validation network across North America and Europe to sustain hospital supply contracts. Constantia Flexibles anchors European pharmaceutical pouch demand through its Salzburg facility's dedicated cleanroom laminating lines. Sealed Air competes on vacuum-sealed medical tray compatibility, extending its reach into ambulatory surgical centers.
Peelable pouches are multi-layer flexible packages engineered with controlled seal-strength interfaces, typically combining polyethylene, polyester, or medical-grade Tyvek with heat-seal coatings calibrated to 1.5–3.0 N/15mm peel force for aseptic presentation. Their primary purpose is to maintain sterility until point of use while permitting glove-handed opening in surgical and clinical settings. Plastic material type dominates volume due to cost scalability in food and consumer applications, though biodegradable alternatives are gaining fastest traction as EU Single-Use Plastics Directive enforcement tightens. Medical Applications as an end-user segment commands the strongest margin pool because lot traceability and biocompatibility testing requirements create qualification barriers that protect pricing.
FDA's 21 CFR Part 820 quality system regulation governs U.S. medical pouch validation protocols, while EMA's Medical Device Regulation in Europe mandates clinical evidence linkage to packaging sterility assurance. REACH restricts phthalate plasticizers in seal layers, redirecting formulation R&D toward polyester-urethane alternatives. Stakeholders must monitor evolving ISO 13485 audit expectations for supplier qualification, as notified bodies tighten subcontractor oversight across the sterile barrier supply base.
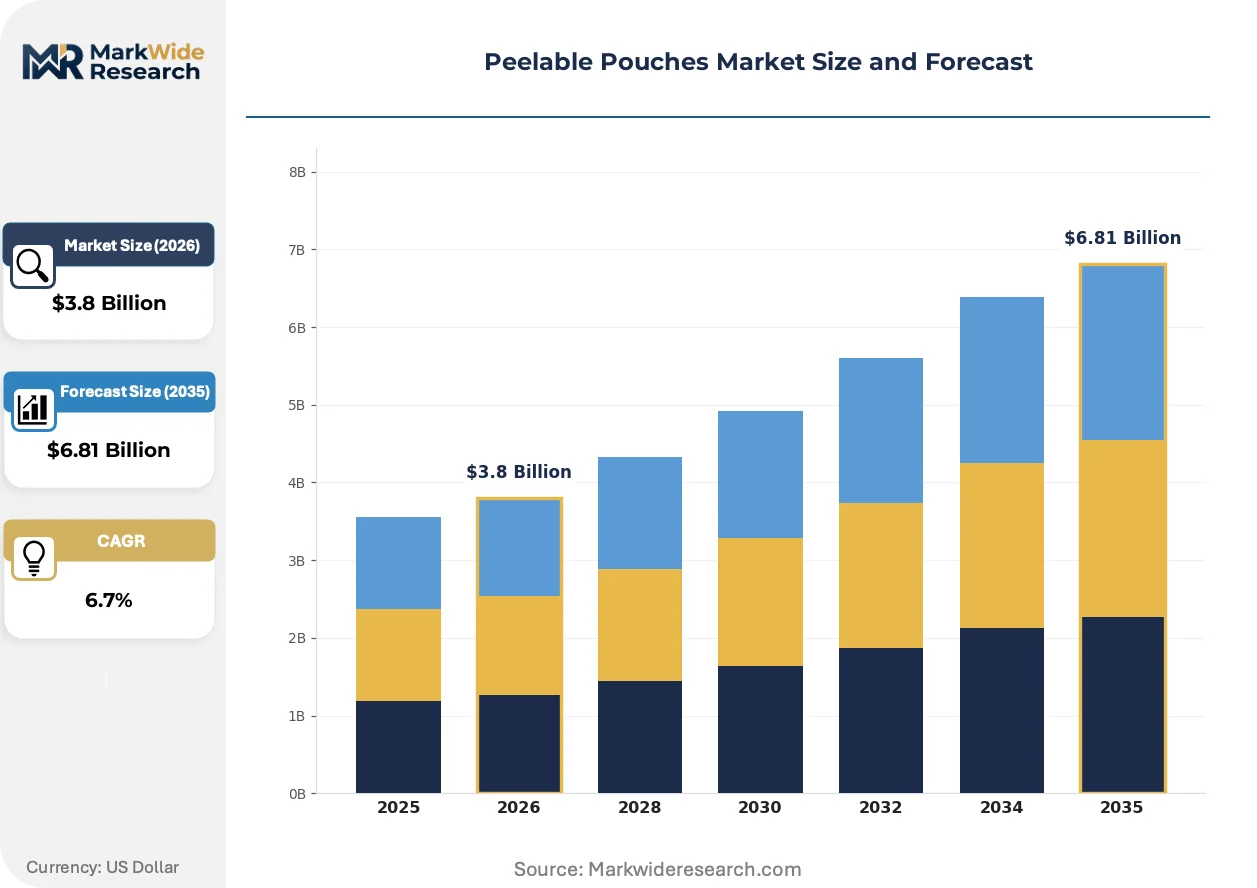
Market Dynamics
ISO 11607 certification requirements for sterile barrier systems are compressing supplier participation in medical-grade peelable pouches, concentrating contract awards among multi-site validated converters while forcing smaller regional players toward subcontracting relationships or market exit.
Growth Catalysts
- Single-use sterile barriers:Hospitals across Germany, France, and the United States are eliminating reusable sterilization containers to reduce cross-contamination risk, directly expanding pouch volume demand.
- REACH compliance evolution:ECHA's tightened phthalate restrictions in seal-layer formulations are redirecting R&D investment toward polyester-urethane alternatives, creating first-mover advantage for compliant material suppliers.
- Tyvek adoption:Medical device manufacturers are specifying DuPont's spunbonded olefin for breathable sterile barriers due to its established FDA master file status and consistent fiber structure.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs fluctuate with crude oil benchmarks, compressing margin predictability for high-volume food and consumer pouch converters.
- Cleanroom infrastructure concentration:Validated laminating capacity clusters around Frankfurt's pharmaceutical corridor and North Carolina's Research Triangle, creating geographic supply risk for distant device manufacturers.
- Biodegradable performance gap:PLA and PHA alternatives exhibit inferior moisture barrier properties versus conventional multi-layer structures, limiting substitution in moisture-sensitive medical applications.
Strategic Opportunities
- Ambulatory surgical centers:Outpatient procedure volume expansion in the United States and Germany is creating dedicated pouch specifications for smaller instrument kits with simplified opening protocols.
- EU Single-Use Plastics Directive:Enforcement timelines are mandating recyclable or compostable packaging transitions, opening formulation partnerships between film suppliers and certified industrial composting operators.
- Digital printing integration:Variable data printing for lot traceability and UDI compliance is converging with pouch converting lines, enabling late-stage customization without plate changeover delays.
Industry Challenges
- ISO 13485 auditor scarcity:Notified bodies are extending supplier qualification timelines due to insufficient trained auditors, delaying new converter entry into sterile barrier supply chains.
- Legacy equipment retrofit costs:Converting lines require substantial capital expenditure for seal-strength calibration systems capable of meeting 1.5–3.0 N/15mm peel force specifications consistently.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, elongating new material qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peelable Pouches Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Aluminum, Biodegradable Closure Type: Peel Seal, Zip Lock, Resealable, Adhesive End User: Food Packaging, Medical Applications, Consumer Goods, Electronics Size: Small, Medium, Large, Custom Size |
| Companies Covered | Huhtamaki, Constantia Flexibles, Amcor plc, Rotek Laminates, TOPPAN Inc., Sealed Air, UFlex Limited, Glenroy, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peelable Pouches Market Evolving Landscape
Peelable pouch engineering is pivoting toward intelligent material systems that integrate sterilization indicators, antimicrobial surfaces, and digitally traceable identities without compromising aseptic presentation integrity.
Tyvek-to-film lamination technology is fragmenting traditional converter specializations as medical device manufacturers demand in-house seal-strength validation capabilities. Tier-one hospitals in Germany and the United States are specifying peel force ranges narrower than ISO 11607 minimums, forcing material suppliers to tighten coating weight tolerances. This precision requirement is fragmenting the supplier base into certified sterile barrier specialists versus commodity food-grade converters unable to meet medical audit standards.
EMA's Medical Device Regulation is mandating clinical evidence linkages between packaging sterility assurance and device performance, elevating packaging from commodity procurement to quality system oversight. Pouch converters must now maintain technical files demonstrating seal integrity across distribution simulation testing. European pharmaceutical corridors around Salzburg and Basel are responding by consolidating supplier relationships toward vertically integrated film-laminating-cleanroom operations.
Buyer concentration among group purchasing organizations is compressing contract negotiation cycles and unbundling after-sales technical support from unit pricing. Hospital networks in the United States are consolidating sterile barrier procurement through centralized supply chain functions, displacing individual facility autonomy. This concentration is most visible in multi-hospital systems across Texas and California, where standardization committees now dictate pouch specifications system-wide.
Peelable Pouches Market Segmentation
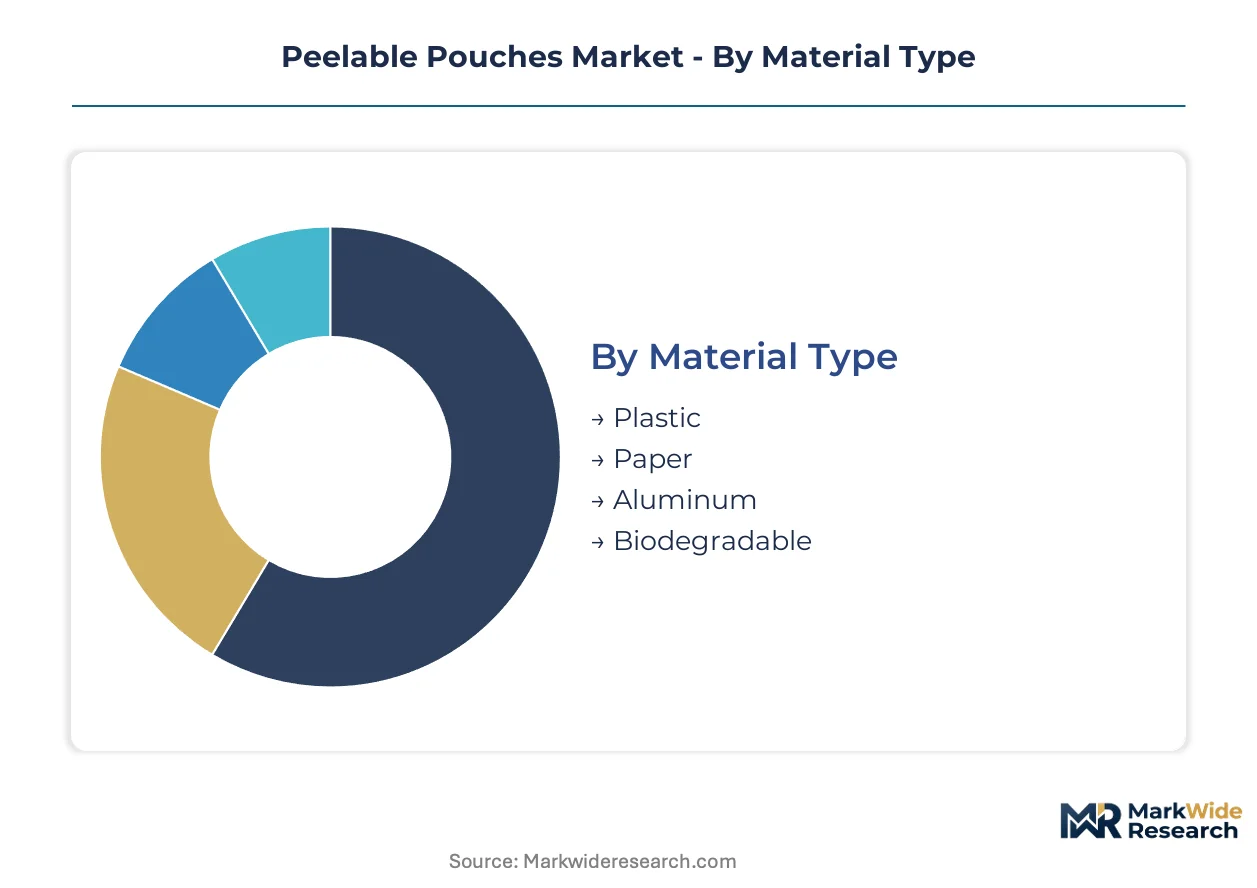
Peelable pouch specifications diverge sharply across sterilization requirements, barrier performance, and opening protocols. Material selection and closure engineering determine qualification pathways for medical versus consumer applications, creating distinct supply ecosystems with incompatible certification standards.
Material Type:
Plastic films dominate domestic production volumes in Germany and the United States, while aluminum laminates and biodegradable alternatives rely heavily on export-oriented manufacturing clusters.
- Plastic:Multi-layer polyethylene and polyester structures calibrated to 1.5–3.0 N/15mm peel force specifications anchor sterile barrier applications. German hospitals around Frankfurt's pharmaceutical corridor specify these for single-use surgical instrument kits, driven by cross-contamination elimination mandates.
- Biodegradable:PLA and PHA alternatives are gaining formulation investment as EU Single-Use Plastics Directive enforcement tightens, though moisture barrier limitations restrict penetration in moisture-sensitive medical segments. Salzburg-based cleanroom laminators are piloting certified industrial composting partnerships.
- Paper:Medical-grade kraft and glassine papers serve breathable sterilization applications with gamma irradiation compatibility.
- Aluminum:Foil laminates provide absolute moisture and oxygen barriers for pharmaceutical stability requirements.
Plastic holds the largest share; momentum sits with Biodegradable alternatives.
Closure Type:
Peel seal configurations command premium pricing tiers due to ISO 11607 validation requirements, while zip lock and resealable variants serve cost-sensitive consumer segments with simpler qualification pathways.
- Peel Seal:Heat-seal interfaces with controlled delamination paths engineered for glove-handed aseptic presentation in surgical settings. DuPont's Tyvek-to-film laminations with FDA master file status concentrate demand in Texas and California hospital networks.
- Resealable:Multi-cycle opening systems serve ambulatory surgical centers in Germany and the United States where instrument kit access protocols differ from operating room standards.
- Zip Lock:Interlocking channel closures dominate food and consumer goods where reclosure functionality outweighs sterile barrier requirements.
- Adhesive:Pressure-sensitive seal layers enable room-temperature sealing for temperature-sensitive contents.
Peel Seal captures the dominant revenue pool; ambulatory center specifications are expanding Resealable uptake fastest.
End User:
Medical Applications concentrate in validated cleanroom corridors, while Food Packaging distributes across broader geographic manufacturing bases with less stringent infrastructure requirements.
- Medical Applications:Sterile barrier systems for device sterilization packaging with lot traceability and biocompatibility testing requirements. North Carolina's Research Triangle hosts concentrated converting capacity serving FDA-regulated device manufacturers.
- Food Packaging:High-volume polyethylene pouches for retail and foodservice applications where ethylene feedstock volatility directly compresses margin predictability.
- Consumer Goods:Cosmetic and personal care pouches with emphasis on shelf appeal and convenience features.
- Electronics:Static-dissipative and moisture-barrier pouches for semiconductor and component protection.
Medical Applications command the strongest margin pool; Food Packaging sustains the highest absolute volume.
Size:
Custom Size specifications fragment production runs across medical device OEMs, while standardized Small, Medium, and Large formats enable economies of scale in consumer-facing segments.
- Custom Size:Dimension-specific pouches engineered for proprietary instrument geometries and kit configurations. Group purchasing organization consolidation in U.S. multi-hospital systems is standardizing previously fragmented specifications.
- Small:Compact formats for single-instrument or limited-component presentation in catheter and implantable device packaging.
- Medium:General-purpose surgical trays and procedure kits representing the volume baseline across hospital procurement.
- Large:Extended-dimension pouches for orthopedic and laparoscopic instrument sets requiring expanded sterile fields.
Custom Size dominates medical contract value; Medium formats anchor standardized procurement volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement and FDA quality system regulations are redirecting sterile barrier capacity toward validated cleanroom corridors in Germany and the United States. Hospital procurement consolidation and single-use sterilization mandates concentrate demand in pharmaceutical manufacturing clusters.
Germany
Frankfurt's pharmaceutical corridor anchors European medical pouch demand through precision laminating infrastructure serving device manufacturers. EMA's Medical Device Regulation mandates clinical evidence linkages between packaging sterility and device performance, elevating supplier qualification requirements. Cleanroom operations around Salzburg and Basel consolidate toward vertically integrated film-laminating facilities.
United States
North Carolina's Research Triangle hosts concentrated converting capacity serving FDA-regulated device manufacturers with ISO 11607-validated sterile barriers. FDA's 21 CFR Part 820 governs validation protocols for hospital supply contracts. Texas and California multi-hospital systems standardize pouch specifications through group purchasing organization consolidation.
China
Domestic medical device packaging demand expands as NMPA tightens sterile barrier requirements for imported and locally manufactured products. GB standards for medical packaging materials redirect formulation investment toward compliant multi-layer structures. Yangtze River Delta manufacturing clusters develop export-oriented laminating capacity for Asia-Pacific pharmaceutical markets.
India
CDSCO medical device regulations and PLI scheme incentives attract sterile barrier investment toward domestic production. Karnataka and Maharashtra pharmaceutical corridors expand converting capacity to reduce import dependence for device packaging. Hyderabad and Mumbai clusters develop cleanroom infrastructure serving contract manufacturing organizations.
Japan
PMDA quality system requirements and aging demographics drive precision medical pouch specifications for surgical instrument sterilization. METI industrial policy supports advanced material development for moisture-barrier applications. Osaka-Kobe manufacturing belt concentrates laminating expertise serving domestic device manufacturers and Southeast Asian export markets.
Peelable Pouches Market Competitive Landscape
Listed leaders compete with private specialists across multi-site sterilization validation networks and cleanroom laminating capacity. The supplier base compresses toward certified sterile barrier specialists as ISO 11607 and ISO 13485 audit requirements eliminate commodity converters. Three archetypes dominate: multi-national converters with hospital supply contracts, regional laminators with pharmaceutical corridor proximity, and material-integrated players controlling upstream film supply. Competitive moves center on cleanroom capacity expansion and strategic partnerships with device manufacturers for co-development of kit-specific pouch geometries.
Among the validated converter tier, Amcor plc exemplifies multi-site sterilization validation networks across North America and Europe. Constantia Flexibles anchors European pharmaceutical demand through Salzburg-based cleanroom laminating operations. Sealed Air occupies a position bridging vacuum-sealed medical tray compatibility with ambulatory surgical center specifications. These three represent distinct strategic postures: geographic diversification, regional corridor concentration, and end-use segment specialization.
| Leading Market Players |
|---|
| Huhtamaki |
| Constantia Flexibles |
| Amcor plc |
| Rotek Laminates |
| TOPPAN Inc. |
| Sealed Air |
| UFlex Limited |
| Glenroy |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day raw material lead times for medical-grade Tyvek and polyester films concentrate pricing power with validated cleanroom converters in Germany and the United States, while commodity pouch producers absorb ethylene resin volatility without contract pass-through mechanisms.
Pricing Analysis
Certification level creates the primary spread across pouch tiers, with ISO 11607-validated sterile barriers commanding substantial premiums over food-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth, lot traceability capability, and after-sales technical support bundling. Cost compression in commodity polyethylene pouches is intensifying because hospital group purchasing organizations consolidate procurement volumes and unbundle technical services from unit pricing. Ambulatory surgical centers exhibit highest price sensitivity due to reimbursement pressure, while tier-one hospital networks in Texas and California prioritize seal-strength consistency over per-unit cost.
Supply Chain Analysis
Germany and the United States anchor sterile barrier laminating capacity through Frankfurt's pharmaceutical corridor and North Carolina's Research Triangle, while China and India develop export-oriented converting clusters for Asia-Pacific device markets. Medical-grade peelable pouches draw from DuPont Tyvek supply, multi-layer polyester films, and heat-seal coating formulations subject to REACH phthalate restrictions. Single-source vulnerability concentrates in FDA master file holders for breathable sterile barriers, creating qualification bottlenecks when capacity constraints emerge. Distribution runs through medical device OEM direct contracts, group purchasing organization tiered supply agreements, and regional distributor networks serving ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peelable pouch demand tracks hospital capital expenditure cycles and single-use sterilization adoption curves, positioning the current window as mid-cycle expansion with ambulatory center buildouts extending runway.
For Market Incumbents: Fortify sterile barrier validation networks by expanding multi-site ISO 11607 certification across European and North American cleanroom corridors, insulating against emerging regional converters in India and China that threaten contract erosion through cost-based positioning. Deepen backward integration into medical-grade film extrusion to capture margin pools currently residing with specialty resin compounders and coating suppliers. For New Entrants and Emerging Players: Differentiate on biodegradable material systems certified for industrial composting, targeting EU Single-Use Plastics Directive compliance gaps that incumbent converters address slowly due to legacy equipment retrofit burdens. Penetrate ambulatory surgical center specifications in Germany and the United States where simplified opening protocols and smaller kit geometries reduce validation complexity and accelerate qualification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because ISO 13485 auditor scarcity and biocompatibility testing backlogs create durable moats around certified sterile barrier specialists that commodity converters cannot replicate. Acquisition targets cluster around regional laminators with pharmaceutical corridor proximity and existing cleanroom infrastructure rather than greenfield capacity builds. Watch EMA Medical Device Regulation enforcement intensity as the inflection signal determining whether packaging technical file requirements accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | Validates additional ISO 11607-certified production lines serving FDA-regulated device manufacturers in North Carolina and Texas. |
| Biodegradable Material Partnership | Secures certified industrial composting offtake agreements with Salzburg-based laminators ahead of EU directive enforcement. |
| Digital Printing Integration | Enables late-stage UDI compliance and lot traceability customization without plate changeover delays on converting lines. |
| Hospital System Partnership | Locks multi-year sterile barrier supply contracts with group purchasing organizations standardizing specifications across California networks. |
| Tyvek Lamination Technology | Develops in-house seal-strength validation capabilities that medical device OEMs increasingly specify for kit-specific pouch geometries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA Medical Device Regulation guidance documents, hospital procurement database extracts, and ISO certification registry data. Conversations with sterile barrier converters, biomedical engineers at tier-one hospital networks, group purchasing organization contracts managers, and medical device packaging R&D directors informed qualification pathway mapping. Customs trade data for polyethylene resin and Tyvek imports, SEC filings from listed packaging converters, and ECHA REACH restriction notifications provided external validation anchors. Bottom-up demand modeling from device sterilization procedure volumes converged with top-down market sizing from converter revenue disclosures.
Segmentation dimensions modeled include material type, closure configuration, end-use application, and geographic regulatory cluster across the projection horizon. CAGRs derive from sterilization procedure growth trajectories, single-use adoption penetration curves, and hospital infrastructure investment patterns. The analytical framework incorporates ethylene feedstock cost sensitivity, cleanroom capacity utilization rates, and notified body audit queue lengths as industry-specific forecast inputs.
Material uncertainties — ethylene price volatility, ISO 13485 auditor availability, and biodegradable barrier performance gaps — sit outside the modeled envelope and could compress or extend forecast ranges. Recalibration cycles align with material shifts in EMA enforcement timelines, FDA quality system inspection priorities, and hospital procurement consolidation waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Slider Zipper Pouch Market
Pouch
France Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
China Pouch Packaging Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Retort Pouch Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
PCR Pouches Market