
 North America Frozen Food Packaging Market | 2026-2036
North America Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen Food Packaging Market Analytics
Multi-source sourcing among frozen food brands is recalibrating how converters allocate film extrusion capacity across the region. Amcor PLC leverages its integrated resin-to-reel platform to secure long-term supply agreements with protein processors. Pactiv Evergreen Inc. anchors the foodservice channel through its proprietary hinged-lid container lines for institutional buyers. Sealed Air differentiates via Cryovac vacuum skin technologies that extend frozen seafood shelf life.
North America frozen food packaging encompasses engineered barrier structures—typically multilayer coextruded films with oxygen transmission rates below 1 cc/m²/day—designed to prevent freezer burn, moisture loss, and flavor degradation across temperature fluctuations from -18°C to ambient thaw cycles. Flexible pouches dominate retail-ready vegetable and prepared meal applications due to cube efficiency in e-commerce fulfillment, while rigid containers sustain premium positioning in single-serve dessert and entree segments where microwave-venting features command shelf price premiums. Biodegradable films represent the fastest-growing material category as California and New York state-level extended producer responsibility laws accelerate compostable substrate trials.
The U.S. FDA regulates food contact substances under 21 CFR, while Health Canada/PMRA enforces parallel safety standards for cross-border packaged goods, and OSHA mandates cryogenic handling protocols at converting facilities operating below -20°F ambient. These overlapping frameworks compel packaging suppliers to maintain dual-compliant substrate inventories and documented chain-of-custody records. Stakeholders must monitor pending state-level recycled content mandates that could force rapid substrate reformulation before federal harmonization emerges.
Market Dynamics
Quick-service restaurants and ready-to-eat meal brands are expanding frozen product lines, recalibrating how converters allocate film extrusion capacity across the region. This demand pull is compressing lead times for multilayer barrier structures while forcing substrate suppliers to maintain dual-compliant inventories under overlapping FDA and Health Canada frameworks.
Growth Catalysts
- Extended Producer Responsibility Laws:California and New York state-level mandates are accelerating compostable substrate trials among converters seeking first-mover positioning in biodegradable films.
- Vacuum Skin Technology:Cryovac systems for frozen seafood are extending shelf life metrics, creating pull from protein processors facing distribution radius constraints.
- E-commerce Cube Efficiency:Flexible pouch formats dominate retail-ready vegetable and prepared meal applications as fulfillment centers prioritize dimensional weight optimization.
Market Restraints
- Resin Supply Concentration:Ethylene-vinyl alcohol copolymer supply clusters among Asian petrochemical producers, exposing converters to freight volatility and tariff exposure.
- Dual-Compliance Inventory Burden:21 CFR food contact substance notifications and parallel Health Canada standards force substrate suppliers to maintain parallel certification documentation.
- Technical Limitation in Microwave Venting:Rigid container microwave-venting features require specialized tooling that smaller converters cannot amortize across limited production runs.
Strategic Opportunities
- Midwest Production Cluster Proximity:Chicago and Minneapolis processing hub concentration enables just-in-time film delivery models that reduce working capital requirements for regional converters.
- Recycled Content Mandates:Pending state-level post-consumer resin requirements create formulation partnerships between resin suppliers and multilayer film producers before federal harmonization emerges.
- Quick-Service Restaurant Channel Expansion:Institutional buyers are specifying proprietary hinged-lid container formats that lock in multi-year supply agreements with early-qualifying converters.
Industry Challenges
- Cryogenic Handling Certification:OSHA mandates for converting facilities operating below -20°F ambient require specialized safety protocols that constrain labor pool availability in rural extrusion locations.
- Multilayer Structure Redesign Cycles:Rapid substrate reformulation timelines to meet evolving FDA food contact substance notifications compress product development windows without guaranteed regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen Food Packaging Market |
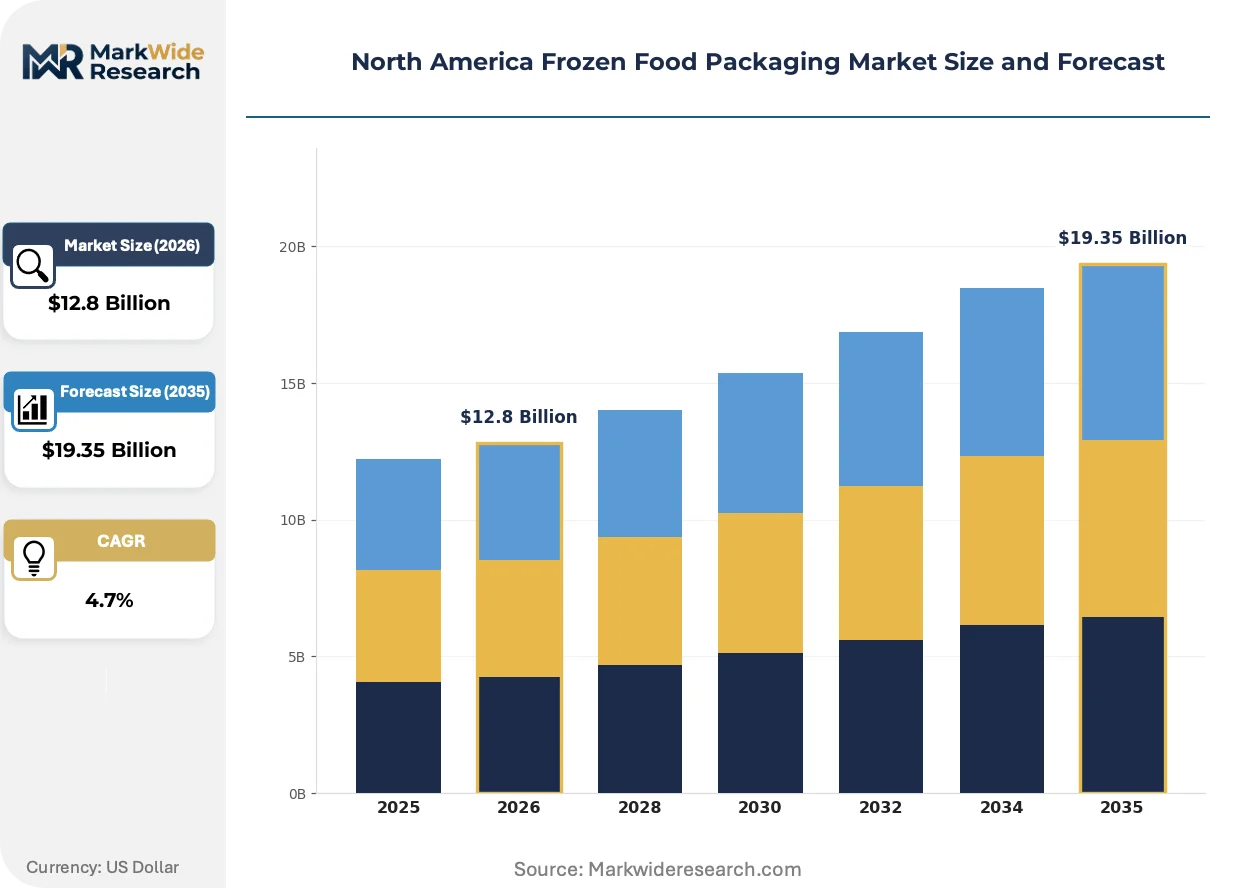
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Rigid Containers, Flexible Pouches, Shrink Wraps, Blister Packs Material: Plastic, Cardboard, Aluminum, Biodegradable Films End User: Retail Chains, Food Service Providers, Online Grocery, Hypermarkets Size: Small Packaging, Medium Packaging, Bulk Packaging, Multi-pack Options |
| Companies Covered | Amcor PLC, Pactiv Evergreen Inc., ProAmpac LLC, Ball Corporation Inc., Aptar-Food Protection Inc., Sonoco Products Company, Sealed Air, Berry Global Inc., WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen Food Packaging Market Evolving Landscape
Barrier engineering and material science advances are compressing traditional packaging performance tiers while regulatory pressure on end-of-life outcomes forces substrate experimentation. These forces are converging to redefine converter competitive positioning across the frozen food supply chain.
High-barrier coextruded films with oxygen transmission rates below 1 cc/m²/day are overtaking legacy metallized structures in premium frozen seafood and prepared meal applications. Protein processors facing distribution cold-chain constraints are adopting these substrates to extend shelf life without aluminum delamination risks. The shift is compressing price premiums between metallized and clear barrier categories while enabling microwaveable packaging formats previously blocked by metal detection systems.
Health Canada's evolving parallel safety standards for cross-border packaged goods are forcing substrate suppliers to maintain documented chain-of-custody records that exceed 21 CFR documentation depth. The industrial consequence is a bifurcation between large converters with dedicated regulatory affairs functions and mid-tier competitors dependent on third-party certification. Frozen vegetable packagers operating near the U.S.-Canada border are most affected, responding by consolidating supplier relationships to reduce audit complexity.
Institutional procurement teams at quick-service restaurant chains are compressing qualification cycles for new packaging formats from 18-month windows to 9-month thresholds. Direct converter relationships are displacing distributor-mediated sourcing for high-volume frozen protein and prepared meal categories. The pattern is most visible in the U.S. Midwest, where Chicago and Minneapolis processing hub proximity enables same-week sample turnaround that distant competitors cannot match.
North America Frozen Food Packaging Market Segmentation
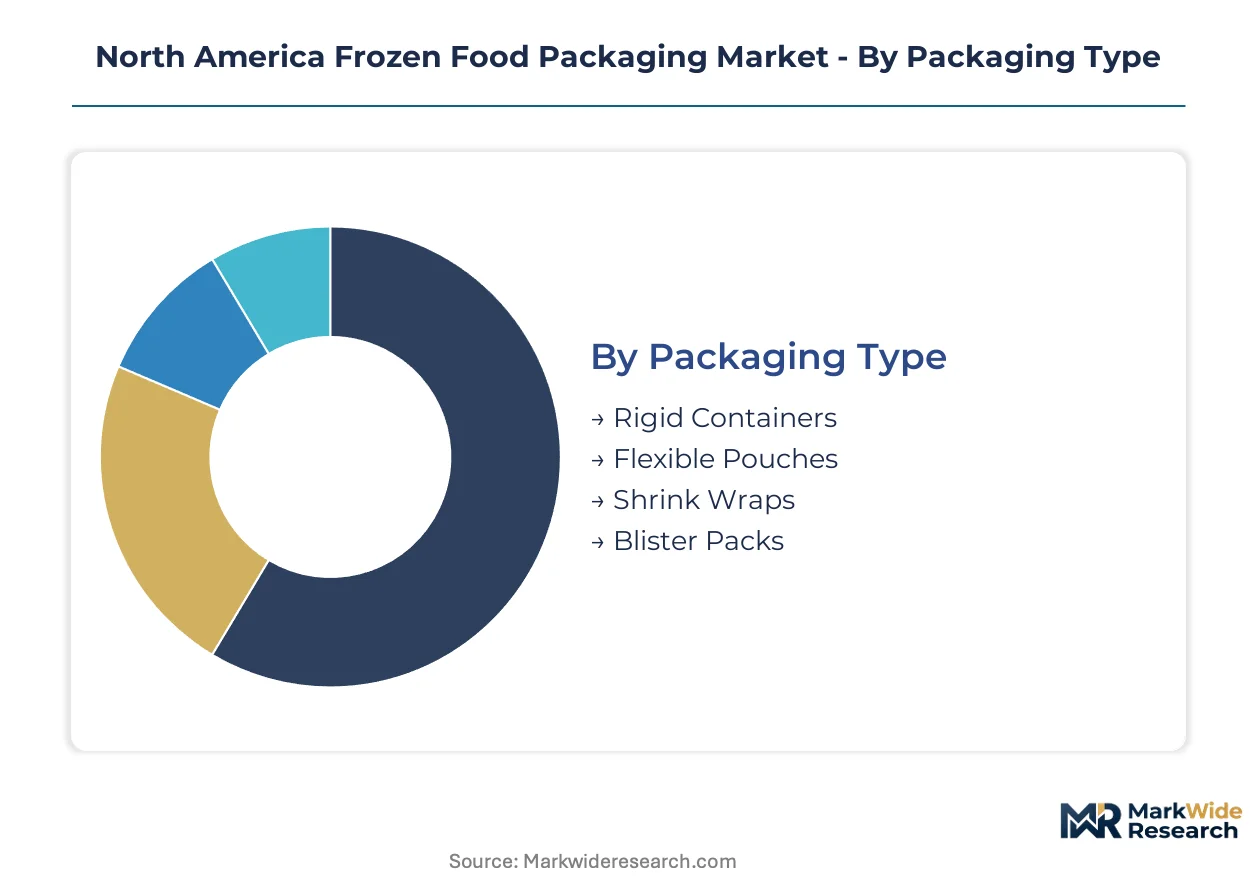
Segmentation in frozen food packaging reveals how substrate choices and format specifications map directly to cold-chain logistics requirements and retail channel economics. Each dimension carries distinct regulatory, performance, and cost imperatives that shape converter investment priorities.
Packaging Type:
Standalone formats dominate retail shelf presence while embedded barrier systems integrate into processing-line automation.
- Rigid Containers:Polypropylene and crystallized PET structures with microwave-venting features command premium positioning in single-serve entree and dessert categories. Illinois and Wisconsin converters cluster near Chicago processing hubs to supply quick-service restaurant chains specifying proprietary hinged-lid designs.
- Flexible Pouches:Multilayer coextruded films with oxygen transmission rates below 1 cc/m²/day enable cube-efficient e-commerce fulfillment for retail-ready vegetables and prepared meals. Minnesota-based protein processors are compressing qualification cycles for these formats to nine-month windows.
- Shrink Wraps:Polyolefin-based collation films secure multi-unit frozen pizza and breaded protein bundles for club store displays.
- Blister Packs:Thermoformed PVC-PVDC combinations protect premium frozen seafood portions with individual cavity barriers.
Rigid containers lead volumes today; flexible pouches are gaining share fastest.
Material:
Cost tiers separate commodity substrates from engineered barrier structures requiring specialized extrusion assets.
- Plastic:Ethylene-vinyl alcohol copolymer and nylon coextrusions form the backbone of high-barrier frozen food protection. FDA 21 CFR food contact substance notifications drive reformulation cycles among Midwest converters serving cross-border U.S.-Canada supply chains.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate substrates are accelerating compostable trials under California and New York extended producer responsibility mandates. Technical limitations in moisture resistance constrain adoption to short-distribution-radius applications.
- Cardboard:Clay-coated solid bleached sulfate boards support frozen pizza and bakery cartons with grease-resistant barriers.
- Aluminum:Foil laminates sustain premium seafood and specialty entree segments requiring absolute light and oxygen exclusion.
Plastic substrates dominate installed capacity; biodegradable films are expanding most quickly.
End User:
Customer type determines order cadence, specification complexity, and converter margin structure across the value chain.
- Food Service Providers:Institutional procurement teams at quick-service restaurant chains specify proprietary formats locking in multi-year supply agreements. Minneapolis and Chicago hub proximity enables same-week sample turnaround that distant competitors cannot match.
- Online Grocery:Fulfillment center dimensional weight optimization drives flexible pouch specification for frozen vegetables and prepared meals. California-based e-commerce operators are piloting biodegradable film formats to preempt state-level compliance deadlines.
- Retail Chains:National grocery banners balance shelf differentiation against supply chain standardization for private-label frozen lines.
- Hypermarkets:Club store operators demand bulk collation formats with pallet-level cube efficiency for frozen protein cases.
Food service providers anchor converter revenue stability; online grocery is climbing the fastest.
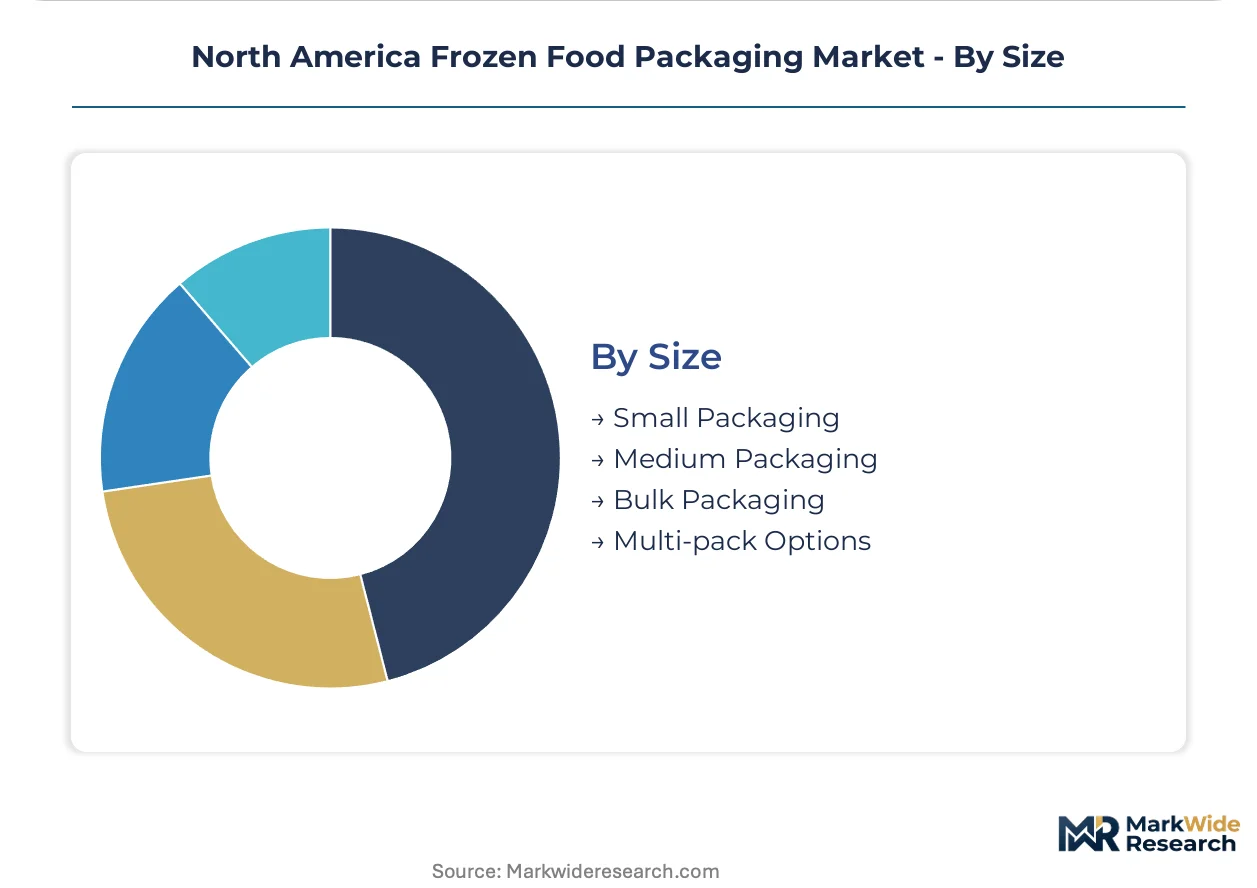
Size:
Volume scale separates mass-market commodity formats from specialized equipment-dependent production runs.
- Small Packaging:Single-serve 8-12 ounce formats command tooling premiums for microwave-venting features in premium entree segments. New York and California regulations on recycled content are forcing substrate redesigns in this specification-intensive category.
- Bulk Packaging:5-10 pound foodservice formats standardize around commodity polyolefin structures with minimal barrier requirements. Midwest meat processors near Minneapolis specify these formats for institutional quick-service restaurant supply.
- Medium Packaging:Family-size 16-24 ounce retail formats balance cube efficiency against shelf presence for mainstream frozen vegetables and prepared meals.
- Multi-pack Options:Collation formats for club stores bundle 4-6 individual units with shrink-wrap secondary containment.
Small packaging captures premium margin concentration; bulk packaging sustains volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping converter investment patterns as producers migrate toward jurisdictions with streamlined compliance pathways and clustered cold-chain infrastructure. FDA and Health Canada notification requirements create divergent cost structures that influence where multilayer film capacity expands.
United States
Midwest frozen food production clusters near Chicago and Minneapolis processing hubs concentrate converter activity for just-in-time film delivery. FDA 21 CFR food contact substance notifications drive reformulation cycles among Illinois and Wisconsin-based suppliers serving cross-border supply chains. California and New York state-level extended producer responsibility laws are accelerating compostable substrate trials among West Coast and Northeast converters.
Canada
Health Canada and PMRA parallel safety standards for cross-border packaged goods force substrate suppliers to maintain dual-compliant inventories and documented chain-of-custody records. Ontario and Quebec frozen vegetable packagers operating near the U.S. border are consolidating supplier relationships to reduce audit complexity under overlapping regulatory frameworks. Toronto-area converters are positioning for integrated resin-to-reel supply agreements with protein processors.
Mexico
Nuevo León and Jalisco food processing corridors are attracting flexible pouch capacity to serve quick-service restaurant supply chains with compressed qualification cycles. Mexican regulators under COFEPRIS are aligning food contact substance standards with FDA frameworks to facilitate northbound export compliance. Monterrey-based converters are leveraging proximity to Texas distribution networks for e-commerce fulfillment optimization.
North America Frozen Food Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable substrate specialization and microwave-venting format innovation. The market structure consolidates around integrated resin-to-reel platforms and proprietary hinged-lid container lines. Three archetypes dominate: multinational converters with regulatory affairs functions, mid-tier regional suppliers dependent on third-party certification, and niche specialists in vacuum skin technologies. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters secure long-term supply agreements with protein processors.
Within the integrated platform tier, Amcor PLC and Sealed Air exemplify archetypes leveraging captive resin supply and vacuum skin technologies respectively. Pactiv Evergreen Inc. anchors the foodservice channel position through proprietary format development. These three entities represent distinct strategic postures: backward integration into resin supply, technology differentiation in barrier systems, and institutional buyer relationship lock-in through customized container designs.
| Leading Market Players |
|---|
| Amcor PLC |
| Pactiv Evergreen Inc. |
| ProAmpac LLC |
| Ball Corporation Inc. |
| Aptar-Food Protection Inc. |
| Sonoco Products Company |
| Sealed Air |
| Berry Global Inc. |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
California and New York extended producer responsibility laws gate both qualified supply and premium-tier pricing access, as converters demonstrating compostable substrate capabilities command material premiums while non-compliant suppliers face exclusion from institutional procurement pipelines.
Pricing Analysis
Input-cost pass-through from ethylene-vinyl alcohol copolymer and resin feedstocks dominates contract negotiations, with multilayer film converters indexing annual adjustments to petrochemical benchmarks. Pricing stratifies across premium, standard, and economy tiers based on barrier performance specifications and FDA 21 CFR certification depth. Cost compression in standard-tier commodity films is intensifying because Asian resin supply concentration exposes Midwest converters to freight volatility and tariff exposure. Foodservice providers anchor the least price-sensitive segment through multi-year proprietary format agreements, while retail private-label buyers exhibit acute sensitivity to per-unit differentials.
Supply Chain Analysis
Workforce availability constraints in Illinois and Wisconsin extrusion corridors are forcing automation investments that reshape regional capacity economics. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on ethylene-vinyl alcohol copolymer, polypropylene resins, and nylon coextrusions sourced from Asian petrochemical producers. Single-source vulnerability in high-barrier substrate supply creates exposure to geopolitical trade friction. Distribution runs through just-in-time delivery models anchored to Chicago and Minneapolis processing hubs, with cross-border Health Canada documentation adding compliance layers for Ontario and Quebec supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
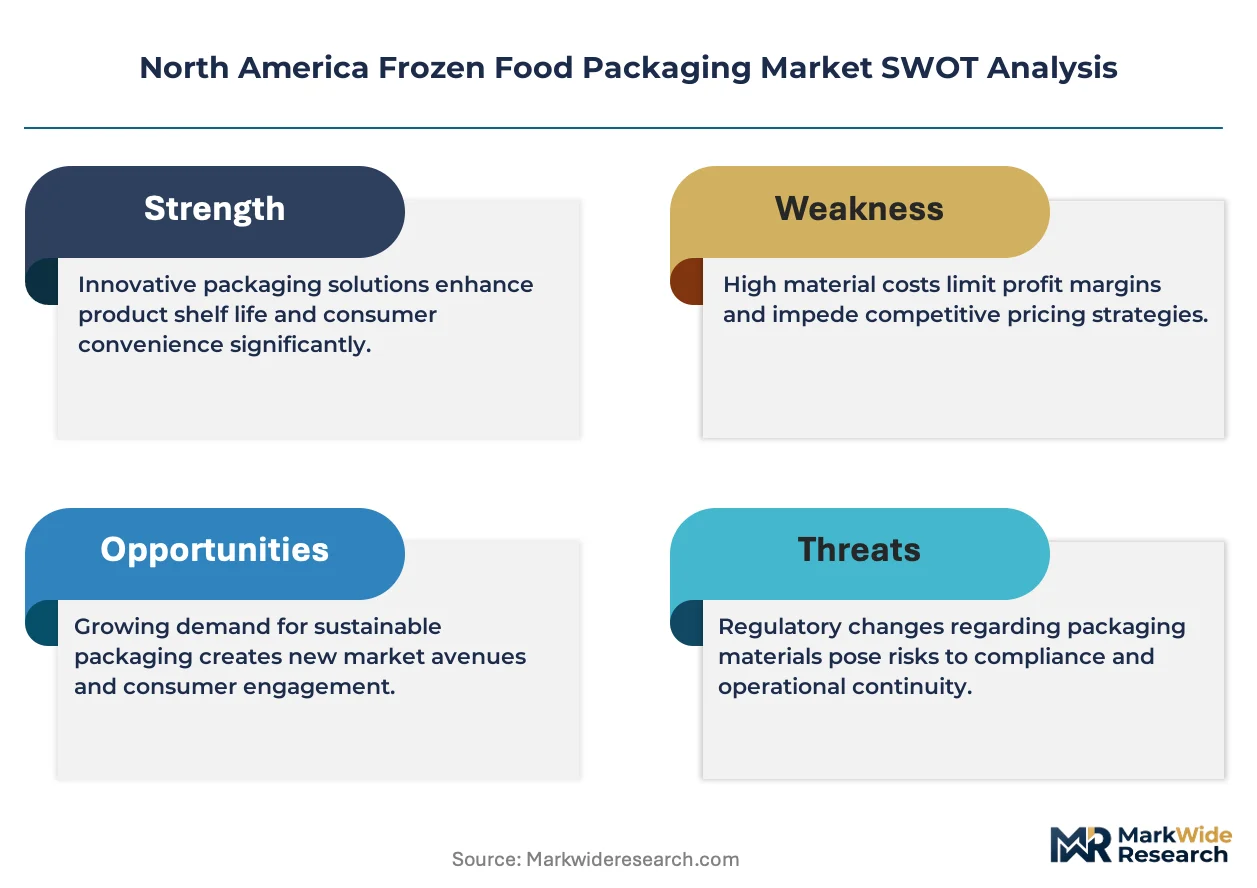
Geographic-arbitrage opportunities emerge from regulatory cost differentials between California's accelerated compostable mandates and federal harmonization delays, rewarding early-mover positioning in biodegradable substrate capacity.
For Market Incumbents: Lock in long-term resin supply agreements and captive extrusion capacity to defend against emerging biodegradable specialists capturing ESG-driven procurement shifts. Prioritize backward integration into polymer compounding to secure margin control amid volatile feedstock markets. Consolidate regulatory affairs functions to manage dual FDA and Health Canada compliance burdens that constrain mid-tier competitors. For New Entrants and Emerging Players: Launch via direct converter relationships with quick-service restaurant chains seeking compressed nine-month qualification cycles for proprietary hinged-lid formats. Target the biodegradable film segment as the most penetrable white space under pending state-level recycled content mandates. Pursue partnership models with Midwest protein processors facing distribution radius constraints for vacuum skin technology adoption. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional converters because dual-compliance inventory burdens and specialized cryogenic handling certifications create barriers that favor scaled platforms with dedicated regulatory infrastructure. Monitor California and New York state-level recycled content mandate implementation timelines as the critical inflection signal for substrate reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Substrate Scale-Up | California EPR deadlines force capacity commitments before federal harmonization emerges. |
| Vacuum Skin Technology Licensing | Cryovac systems extend frozen seafood shelf life for protein processors facing cold-chain constraints. |
| Midwest Hub Proximity Investment | Chicago and Minneapolis cluster concentration enables same-week sample turnaround for institutional buyers. |
| Dual-Compliance Certification Program | Parallel FDA and Health Canada documentation reduces audit complexity for cross-border vegetable packagers. |
| Recycled Content Formulation Partnership | Resin supplier alliances preempt state-level post-consumer resin requirements before mandate enforcement. |
Research Methodology
Multiple input streams — converter production data, resin supplier pricing indices, and regulatory filing documentation — were reconciled against primary interviews with multilayer film plant managers, quick-service restaurant procurement directors, protein processor supply chain leads, and FDA regulatory affairs specialists. Secondary validation drew from U.S. Customs trade records, FDA 21 CFR food contact substance notifications, Health Canada PMRA safety standards, and OSHA cryogenic handling compliance databases. Bottom-up capacity modeling and top-down demand estimation were triangulated to anchor volume projections.
Historical shipment patterns were cross-referenced against expert panel inputs to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, end-user channel, and size tier alongside regional production hub clustering. CAGRs were derived from trend extrapolation moderated by capacity constraint analysis and regulatory implementation timelines. Forecast inputs incorporated e-commerce fulfillment center dimensional weight optimization trends and quick-service restaurant channel expansion trajectories.
Several conditions sit outside the modeled scope, including unannounced federal harmonization of state-level extended producer responsibility laws and breakthrough advances in biodegradable film moisture resistance. Forecasts reflect documented assumptions about resin supply continuity and regulatory notification approval timelines. Practitioners should monitor California and New York mandate enforcement schedules and FDA food contact substance notification backlog clearance rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
PET Food Trays Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Canada Disposable Tableware Market