
 Chocolate Packaging Market | 2026-2036
Chocolate Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Packaging Market Analysis
Gourmet and bean-to-bar chocolatiers is unwinding the historical dominance of mass-market confectionery in packaging value capture. Mondelez International leverages its global manufacturing footprint to standardize flexible formats across multiple continents. Ferrero Group anchors its premium positioning through distinctive rigid box architectures that resist commoditization. Barry Callebaut specializes in supply-chain-integrated packaging solutions that bridge industrial chocolate production and finished goods presentation.
Chocolate packaging encompasses the protective and decorative enclosures engineered from paper, plastic, aluminum, or glass to preserve cocoa-based confectionery against moisture, oxidation, and thermal degradation while enabling brand communication at retail. Barrier properties typically target water vapor transmission rates below 10 g/m²/day and oxygen permeability under 50 cm³/m²/day to prevent fat bloom and flavor degradation. Paper-based foldable boxes and pouches lead volume deployment across mainstream segments, while rigid boxes command disproportionate margin contribution in gift and seasonal categories. Aluminum wraps retain functional importance for single-serve portions despite sustainability-driven substitution pressures.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recycled content thresholds that reshape material selection across European supply chains. FDA food contact substance notifications govern barrier coatings and adhesives in the United States, while ISO 22000 frameworks shape hazard control protocols for packaging manufactured in direct food-contact environments. Stakeholders must monitor evolving state-level packaging EPR legislation in the United States and assess whether bio-based barrier technologies can achieve cost parity with incumbent multilayer plastic structures before regulatory deadlines tighten material compliance windows.
Market Dynamics
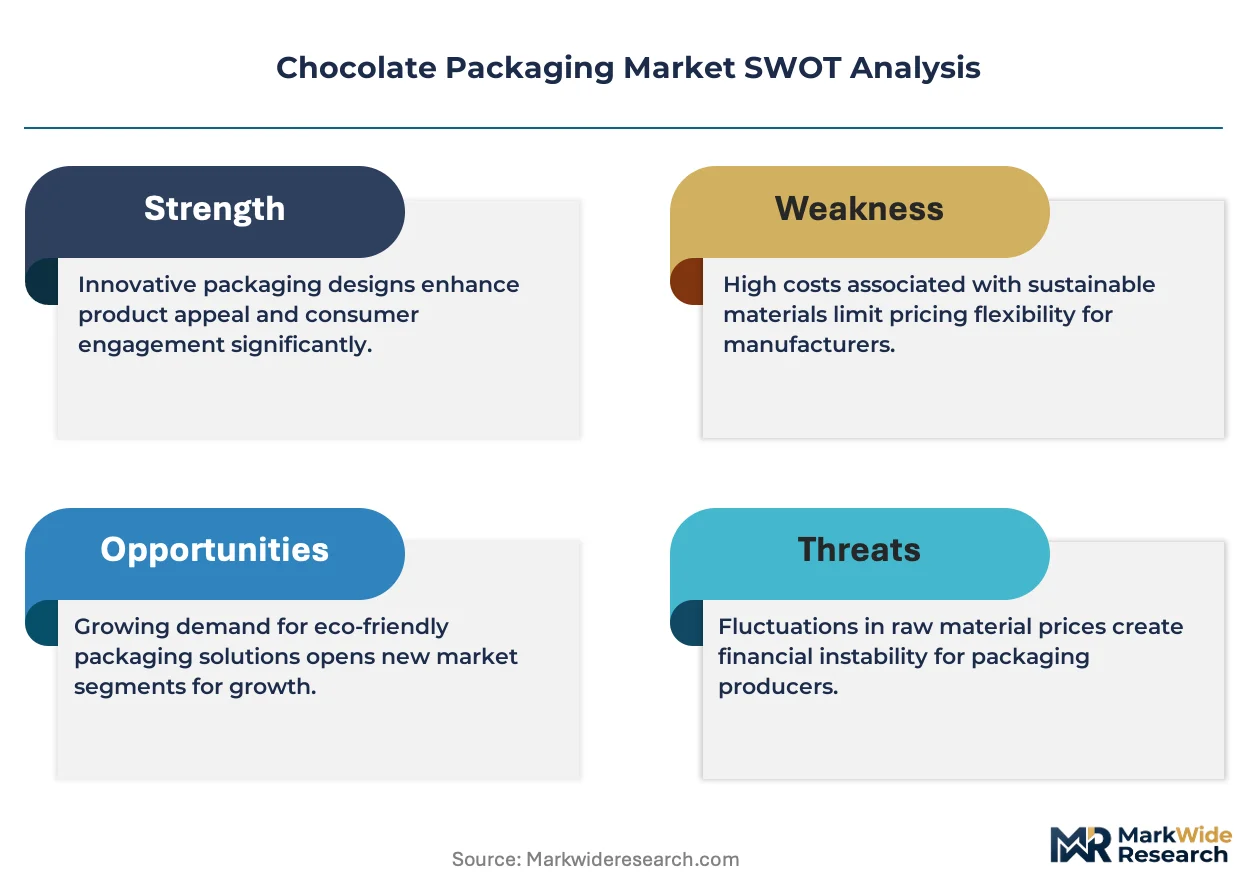
EU Packaging and Packaging Waste Regulation mandates are compressing material selection windows for chocolate converters, forcing accelerated substitution away from multilayer plastic structures before compliance deadlines tighten.
Growth Catalysts
- Recycled Content Mandates:EU member states now enforce minimum recycled thresholds in rigid packaging, pulling fiber-based alternatives into mainstream chocolate gift formats previously dominated by virgin plastics.
- Bean-to-Bar Expansion:Small-batch chocolatiers in France, Belgium, and Switzerland require premium presentation formats that command margin premiums unavailable to mass-market flexible wraps.
- Aluminum Recovery Infrastructure:Germany's dual-system collection networks achieve higher recovery rates for metalized wraps than competing bio-based films, sustaining functional barrier deployment.
Market Restraints
- Multilayer Technical Lock-In:Oxygen barrier requirements below 50 cm³/m²/day currently demand aluminum or ethylene vinyl alcohol interlayers that resist mechanical recycling streams.
- Pulp Supply Concentration:Nordic kraft pulp producers control specialty fiber grades required for grease-resistant chocolate boxboard, exposing converters to input price volatility.
- Compostable Certification Gaps:Industrial composting infrastructure remains patchy across Southern and Eastern Europe, limiting geographic deployment of certified bio-based films.
Strategic Opportunities
- Swiss Premium Cluster:Geneva and Zurich-based luxury chocolate houses sustain willingness-to-pay for rigid box architectures with magnetic closures and foil stamping.
- Digital Watermark Integration:HolyGrail 2.0 sorting technology converges with printed electronics to enable automated material identification at European recycling facilities.
- Direct-to-Consumer Channels:Subscription chocolate services bypass retail shelf constraints, permitting unconventional formats like reusable tins and minimal outer wraps.
Industry Challenges
- Barrier Coating Reformulation:Food contact notification timelines at FDA and EFSA extend 18-24 months for novel bio-based coatings, delaying product launches.
- Heat Seal Compatibility:Legacy filling lines calibrated for polypropylene structures require retooling to handle fiber-based pouch formats with divergent seal initiation temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Packaging Market |
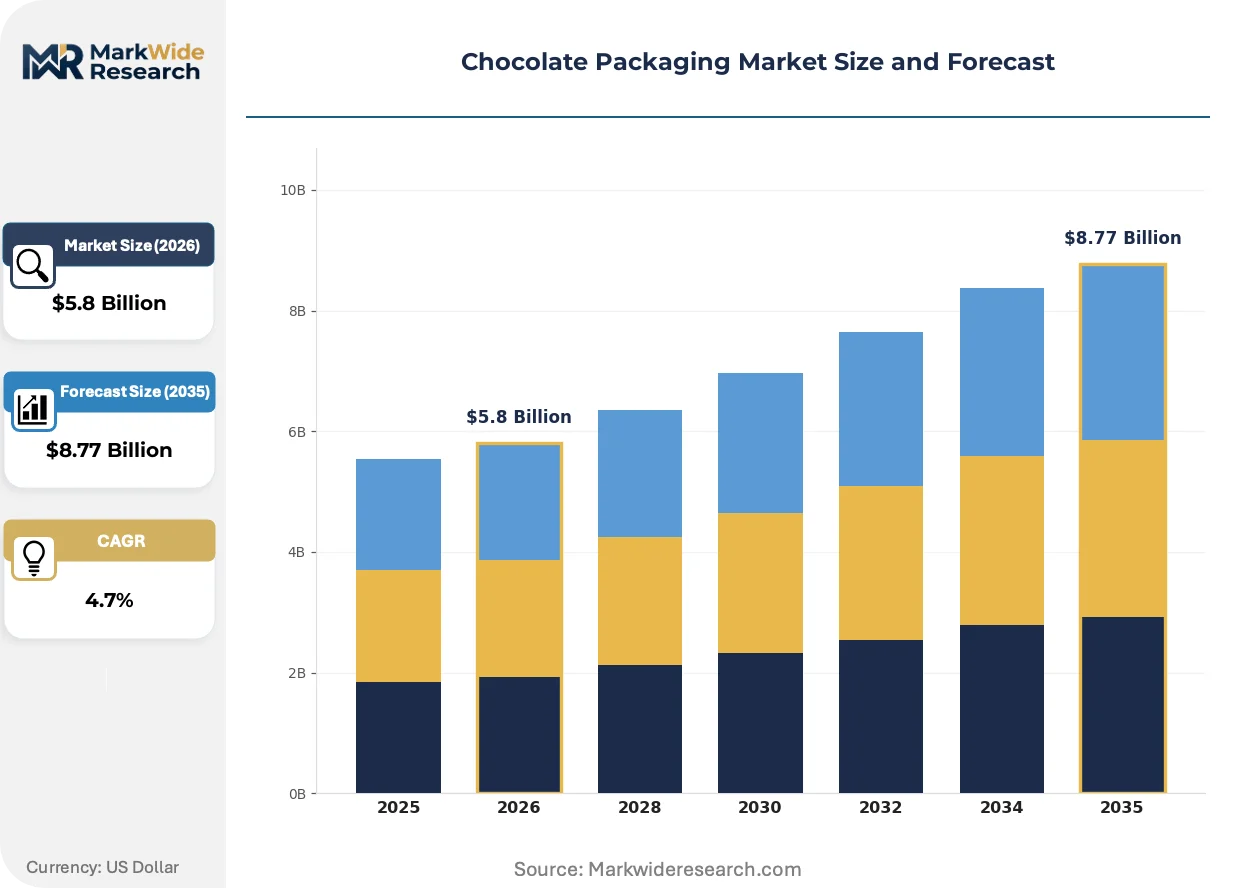
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Paper, Plastic, Aluminum, Glass Type: Foldable Boxes, Rigid Boxes, Pouches, Wraps Closure Type: Zip Lock, Heat Seal, Rigid Lock, Snap Lock Design: Printed, Embossed, Laminated, Custom Shapes |
| Companies Covered | Nestlé SA, Chocoladefabriken Lindt & Sprüngli AG, Mondelez International, Meiji Co. Ltd., Pladis, Mars Inc., The Hershey Company, Barry Callebaut, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Packaging Market Emerging Trajectories
Material science advances and sorting infrastructure upgrades are destabilizing incumbent packaging architectures across European chocolate supply chains. Three concurrent developments are reconfiguring competitive advantage.
Cellulose nanofiber barrier coatings are fragmenting the oxygen protection landscape previously monopolized by aluminum and ethylene vinyl alcohol laminates. Mid-tier Belgian and Dutch chocolatiers are piloting these coatings at commercial scale for 12-month shelf life targets. The technology is fragmenting converter relationships as paper specialists capture barrier functionality from film extruders.
EU Green Deal packaging requirements are accelerating design-for-recycling protocols across member state enforcement networks. Extended producer responsibility fees now vary by recyclability tier, creating direct cost penalties for complex multilayer structures. German and French chocolate brands are responding with simplified mono-material pouches and fiber-based gift boxes that qualify for reduced EPR contributions.
Seasonal gifting patterns are compressing production planning cycles for rigid box converters. Valentine's and Easter peaks now account for disproportionate annual volume, forcing capacity investments that sit idle during off-peak months. Swiss and Austrian premium houses are addressing this through modular box platforms that adapt graphics without structural retooling.
Chocolate Packaging Market Segmentation
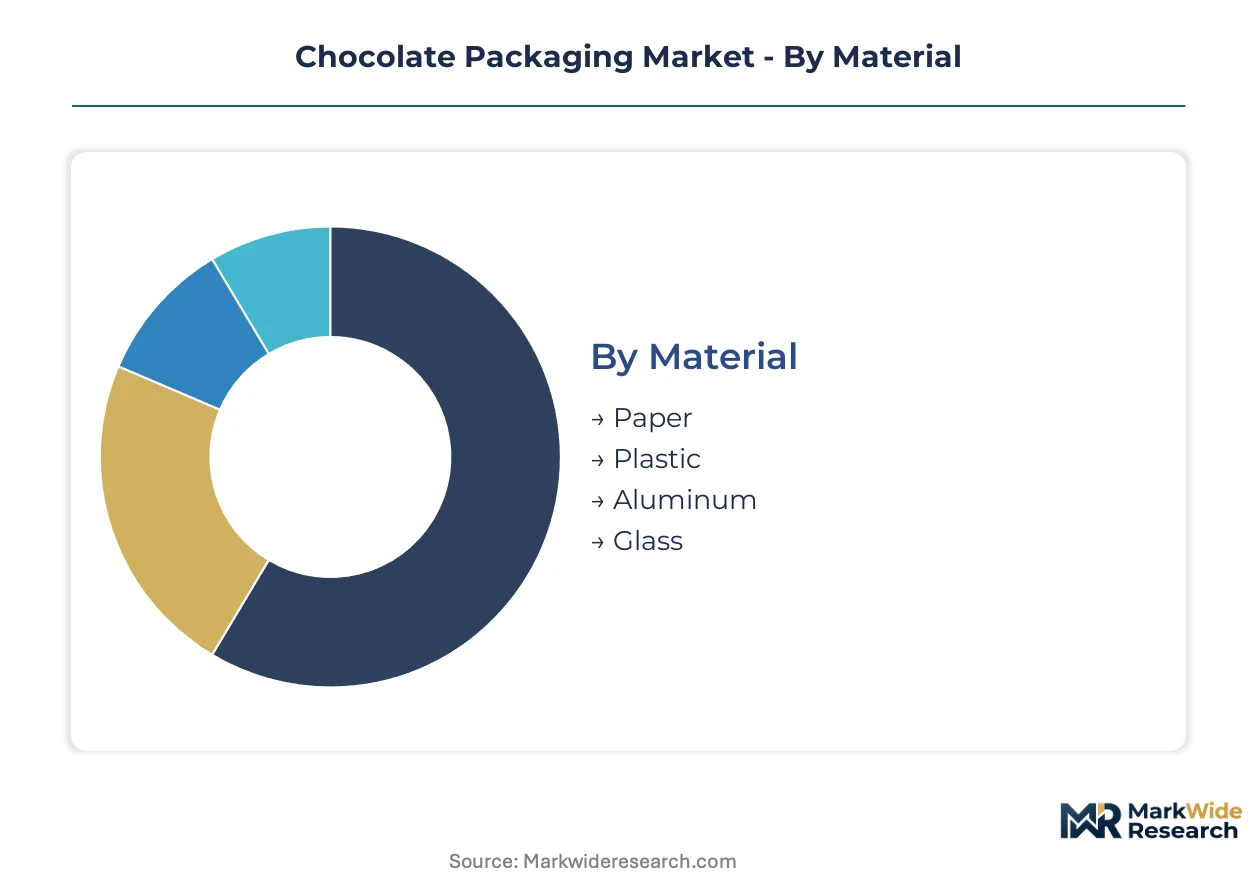
Chocolate packaging segmentation reveals how material selection and format architecture map to distinct channel economics. Premium gift formats command margin multiples unavailable to commodity flexible wraps, while regulatory pressure on recyclability is fragmenting traditional material hierarchies.
Material:
Paper-based formats flow disproportionately through retail gift and seasonal channels, while aluminum and multilayer plastics dominate single-serve and convenience store distribution.
- Paper:Kraft and sulfate boards with grease-resistant barrier coatings form the structural backbone of foldable gift boxes and premium rigid formats. Belgian and Swiss chocolatiers concentrate demand here for bean-to-bar presentation layers that signal craft authenticity. EU recycled content mandates are accelerating substitution away from plastic laminates in this segment.
- Plastic:Polypropylene and polyethylene structures dominate flexible wraps and pouches for mass-market tablets and countlines. Mondelez International and Ferrero Group standardize these formats across high-volume production lines in Germany, Italy, and Poland. Multilayer technical lock-in persists where oxygen barriers below 50 cm³/m²/day remain mandatory.
- Aluminum:Metalized foils and laminates preserve single-serve chocolate bars against moisture and oxidation in vending and convenience channels. Germany's dual-system collection infrastructure sustains deployment despite sustainability-driven substitution pressures from fiber-based alternatives.
- Glass:Premium jar and bottle formats serve chocolate spreads, drinking chocolate, and limited-edition gifting lines. Specialty chocolatiers in France and Switzerland deploy glass for ultra-premium positioning where unit economics permit heavier logistics.
Paper dominates installed base by volume. Aluminum is where expansion concentrates as recovery infrastructure improves.
Type:
Format architecture determines production tooling investment and seasonal capacity planning, with rigid structures requiring capital-intensive equipment that sits idle outside peak gifting periods.
- Foldable Boxes:Paperboard cartons with tuck or glue closures represent the volume workhorse across mainstream chocolate tablets and assortments. Barry Callebaut integrates these formats into supply-chain-integrated solutions for industrial chocolate customers. Cost efficiency and flat-pack shipping economics sustain dominance in supermarket channels.
- Rigid Boxes:Set-up boxes with thick board walls and magnetic or ribbon closures anchor premium and seasonal gifting segments. Geneva and Zurich-based luxury houses sustain willingness-to-pay for foil-stamped architectures with velvet inlays. Modular platform designs are emerging to compress retooling cycles between Valentine's and Easter peaks.
- Pouches:Stand-up and flat pouches with resealable features serve sharing bags and premium snacking formats. Dutch and Belgian converters are piloting mono-material structures to qualify for reduced EU extended producer responsibility fees.
- Wraps:Single-serve foil and film laminates preserve portion control in vending, hospitality, and impulse channels. Heat seal compatibility requirements with legacy filling lines constrain rapid material transition.
Foldable boxes dominate installed base. Rigid boxes are where expansion concentrates.
Closure Type:
Seal technology selection correlates with shelf life requirements and resealability expectations, mapping directly to consumption occasion and channel format.
- Zip Lock:Press-to-close interlocking strips enable resealability in sharing pouches and premium snacking formats. French and German brands deploy these for premium chocolate assortments where portion control extends consumption.
- Heat Seal:Thermal bonding of multilayer films remains the default for single-serve wraps and portion packs. Legacy line calibration to polypropylene seal initiation temperatures creates retooling friction for fiber-based substitutes.
- Rigid Lock:Magnetic catches and mechanical clasps on premium gift boxes deliver unboxing experience and reuse potential. Swiss premium houses differentiate through patented closure mechanisms.
- Snap Lock:Plastic hinge and tab mechanisms on thermoformed trays serve countline and assortment formats. Cost efficiency sustains deployment in value-tier chocolate selections.
Heat seal dominates installed base. Zip lock is where expansion concentrates.
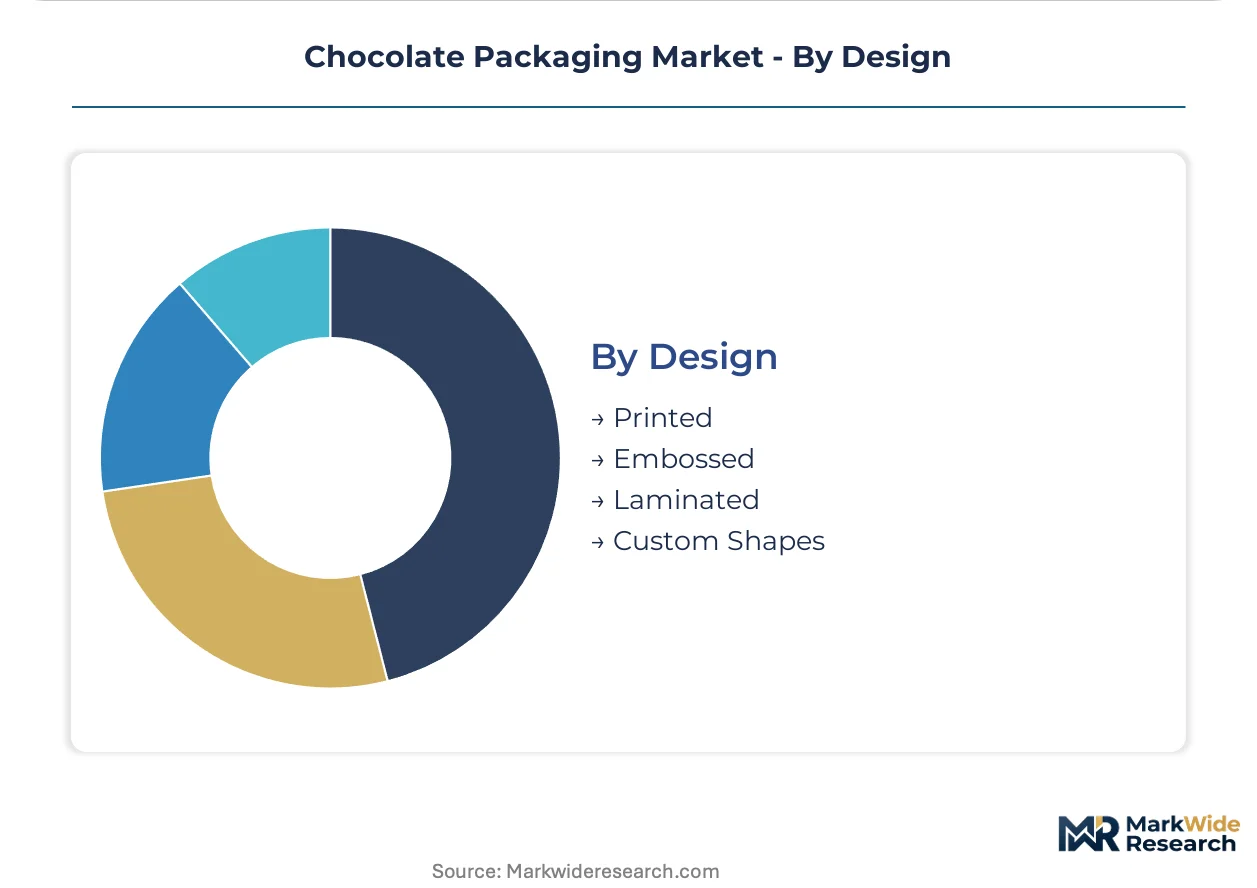
Design:
Surface treatment and dimensional customization separate commodity formats from brand-differentiated presentation layers, with digital printing enabling shorter runs for limited editions.
- Printed:Rotogravure and flexographic decoration carries brand identity and regulatory information across all format categories. Digital watermark integration with HolyGrail 2.0 sorting technology is emerging for automated material identification.
- Embossed:Tactile surface relief on paperboard and foil signals premium positioning in gift and seasonal segments. Austrian and German converters specialize in deep embossing for chocolate assortments.
- Laminated:Multilayer film and foil combinations deliver barrier performance and visual depth. EPR fee differentiation by recyclability tier is forcing simplification of laminate complexity.
- Custom Shapes:Die-cut and molded dimensional formats serve character licensing and seasonal theming. Easter egg and heart-shaped boxes concentrate demand in Belgian and Italian production.
Printed designs dominate installed base. Custom shapes are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Western European industrial corridors where regulatory pressure and premium chocolate demand converge. Belgium, Germany, and Switzerland concentrate specialized folding carton and rigid box production for artisan chocolatiers. France, Italy, and the Netherlands anchor secondary supply nodes serving mass-market and private-label channels.
Germany
Dual-system collection infrastructure achieves higher aluminum recovery rates than competing bio-based films, sustaining functional barrier deployment for single-serve formats. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility fees that vary by recyclability tier, forcing simplification of multilayer structures. The Cologne-Düsseldorf corridor concentrates flexible film extrusion capacity serving Mondelez International and Ferrero Group production lines.
Switzerland
Geneva and Zurich-based luxury chocolate houses sustain willingness-to-pay for rigid box architectures with magnetic closures and foil stamping. Swissmedic oversees food contact substance compliance for premium packaging materials used in ultra-premium segments. The Lake Geneva region anchors specialized set-up box manufacturing for artisan bean-to-bar brands.
Belgium
Mid-tier Belgian chocolatiers pilot cellulose nanofiber barrier coatings at commercial scale for 12-month shelf life targets, fragmenting converter relationships. EFSA notification timelines for novel bio-based coatings extend 18-24 months, delaying product launches. The Brussels-Antwerp corridor concentrates paperboard lamination expertise for foldable gift formats.
France
French brands deploy zip-lock resealable features for premium chocolate assortments where portion control extends consumption. ANSM enforces food contact substance standards for barrier coatings and adhesives in direct food-contact environments. The Paris basin concentrates rotogravure printing capacity for seasonal gifting graphics and limited-edition surface treatments.
Italy
Italian converters specialize in custom die-cut dimensional formats for Easter egg and heart-shaped seasonal boxes. CE marking requirements govern packaging machinery interoperability across European production networks. The Turin-Milan corridor concentrates thermoformed tray production for countline and assortment formats.
Chocolate Packaging Market Vendor Landscape
Concentration sits with diversified confectionery conglomerates that leverage global manufacturing footprints to standardize flexible formats across multiple continents. The vendor base spans three strategic tiers: multinational CPG giants with captive packaging engineering, specialized chocolate-focused converters with supply-chain integration capabilities, and regional artisan suppliers serving premium gift segments. Dominant competitive moves include backward integration into barrier coating formulation and geographic expansion through converter acquisitions in high-growth European markets.
Within the multinational tier, Mondelez International, Ferrero Group, and Barry Callebaut exemplify divergent strategic postures. Mondelez International occupies a position emphasizing scale-driven standardization across high-volume production lines. Ferrero Group anchors premium positioning through distinctive rigid box architectures that resist commoditization. Barry Callebaut represents supply-chain-integrated specialization, bridging industrial chocolate production and finished goods presentation layers.
| Leading Market Players |
|---|
| Nestlé SA |
| Chocoladefabriken Lindt & Sprüngli AG |
| Mondelez International |
| Meiji Co. Ltd. |
| Pladis |
| Mars Inc. |
| The Hershey Company |
| Barry Callebaut |
| Ferrero Group |
| Others |
Supply Flow & Price Mechanics
Converter capacity utilization rates above 85% in the Cologne-Düsseldorf corridor sustain pricing power for multilayer film structures while compressing margin availability for mid-tier chocolatiers seeking fiber-based alternatives. Scale advantages at Mondelez International and Ferrero Group production networks establish price floors that smaller bean-to-bar brands struggle to match without sacrificing barrier performance or shelf life integrity.
Pricing Analysis
Volume-discount tiering structures separate premium rigid box formats from commodity flexible wraps and economy-grade foldable cartons. Price differentiation rests on barrier certification grade and customization level, with Swissmedic-compliant food contact coatings commanding substantial premiums over standard kraft board. Cost compression in the flexible wrap segment is intensifying as EU extended producer responsibility fees penalize multilayer complexity. Mass-market tablet manufacturers exhibit highest price sensitivity, while Geneva-based luxury houses demonstrate minimal elasticity for foil-stamped gift architectures.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for specialty pulp grades sourced from Nordic producers. Geographic supply concentration centers on Germany, Belgium, and Switzerland for converter capacity, while kraft pulp feedstocks draw from Sweden and Finland. Single-source vulnerability persists for cellulose nanofiber barrier coatings where Belgian pilot-scale production remains the sole commercial source. Distribution runs through brand-owned logistics networks for premium segments and retail consolidation platforms for mass-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as HolyGrail 2.0 digital watermark interoperability creates winner-take-most dynamics among converters achieving automated sorting certification.
For Market Incumbents: Compound defensive moats through backward integration into barrier coating formulation and captive supply of certified food contact substrates. Mondelez International and Ferrero Group should accelerate CE marking alignment for packaging machinery interoperability across European production networks. Cellulose nanofiber patent positioning represents the priority lever for differentiation. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription formats that bypass retail shelf constraints and permit unconventional reusable tin architectures. The Swiss premium cluster offers the most penetrable white-space for artisan converters lacking scale economies. Target modular rigid box platforms that compress retooling cycles between seasonal peaks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with demonstrated EFSA notification pathways for novel bio-based coatings. Long-term viability hinges on sorting infrastructure convergence rather than material innovation alone. Acquisition targets should demonstrate HolyGrail 2.0 integration capability. The signal to watch is German dual-system collection rate improvements for metalized wraps versus fiber alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Backward Integration | Captive supply of cellulose nanofiber formulations reduces EFSA notification dependency for Belgian converters. |
| Digital Watermark Certification | HolyGrail 2.0 interoperability qualifies packaging for reduced EU extended producer responsibility fee tiers. |
| Modular Rigid Box Platform | Swiss premium houses compress Valentine's-to-Easter retooling cycles without structural reinvestment. |
| Direct-to-Consumer Channel Launch | Subscription formats bypass retail consolidation platforms and permit unconventional reusable tin architectures. |
| CE Marking Alignment | Packaging machinery interoperability certification ensures seamless production network integration across Germany and Poland. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the chocolate packaging value chain, including folding carton procurement managers at Belgian and Swiss chocolatiers, barrier coating R&D directors at Dutch converters, retail category buyers in German supermarket chains, and logistics planners at aluminum recovery facilities. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, EFSA food contact substance notification databases, HolyGrail 2.0 pilot program disclosures, and customs records for kraft pulp trade flows. Bottom-up capacity estimates for converter installations were triangulated against top-down demand projections derived from chocolate production volume data.
Across the analysis window, volume and value outputs reflect segmentation by material substrate, format architecture, closure technology, and surface treatment design, with additional modeling for premium versus mass-market channel economics. CAGRs were computed from annualized growth trajectories fitted to historical shipment data and projected capacity expansion announcements. Industry-specific forecast inputs included EPR fee schedule implementations and cellulose nanofiber commercialization timelines.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation enforcement and EFSA notification processing protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food Green Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Foam Food Container Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Bamboo Plate Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market