
 North America Canned Food Packaging Market | 2026-2036
North America Canned Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Canned Food Packaging Market Analytics
Private-label retailers is redrawing procurement patterns across the North America canned food packaging landscape. Crown Holdings, Inc. leverages its integrated steel supply and beverage-to-food can conversion capacity to capture volume from grocery chains. Silgan Holdings Inc. anchors the North American market through its dominant position in metal closures and food can manufacturing for branded and store-label customers. Ball Corporation competes aggressively in aluminum food can niches, extending its beverage-grade metal expertise into seafood and vegetable applications.
Canned food packaging encompasses rigid metal, glass, and composite containers engineered to hermetically seal thermally processed foods against microbiological degradation, with three-piece steel cans typically specifying tinplate between 0.16 mm and 0.30 mm and aluminum two-piece cans drawn to wall thicknesses below 0.13 mm for weight-critical applications. The primary commercial purpose centers on shelf-stable distribution of proteins, produce, and prepared meals without refrigerated logistics. Steel cans retain the largest installed base across vegetables and soups, though aluminum cans are gaining fastest in premium seafood and ready-meal segments where light weighting and printability command price premiums. Flexible pouches remain marginal in canned food but attract niche investment in retortable barrier films for pet food and ethnic cuisine formats where shape differentiation drives retail visibility.
The FDA enforces 21 CFR Part 113 and Part 114 regulations governing low-acid and acidified canned foods, mandating thermal process filing and container integrity testing that directly shapes plant capital allocation and quality staffing levels. The EPA regulates volatile organic compound emissions from can coating operations, pushing manufacturers toward waterborne and UV-cured interior linings that eliminate bisphenol-A migration concerns. USDA FSIS oversight of meat and poultry canning adds a parallel inspection layer for protein-focused packers. Stakeholders must monitor how California's Proposition 65 enforcement trends and forthcoming EPA coating standards will reshape material qualification timelines and regional plant investment decisions.
Market Dynamics
Private-label procurement consolidation is restructuring supplier relationships across the North America canned food packaging landscape, with grocery chains demanding volume commitments that favor converters with captive steel supply and multi-plant regional coverage.
Growth Catalysts
- Wet pet food volume surge:Pet food manufacturers are expanding metal can orders as consumers shift toward premium wet formulations requiring hermetic steel packaging.
- FDA Food Safety Modernization Act traceability mandates:The FDA's FSMA rules are pushing converters toward smart packaging integration with QR-coded lot tracking and blockchain-enabled supply chain visibility.
- Southeast U.S. processing cluster proximity:Demand is concentrating in the U.S. Southeast where protein processing facilities and canmaking plants operate within tight logistics radii.
Market Restraints
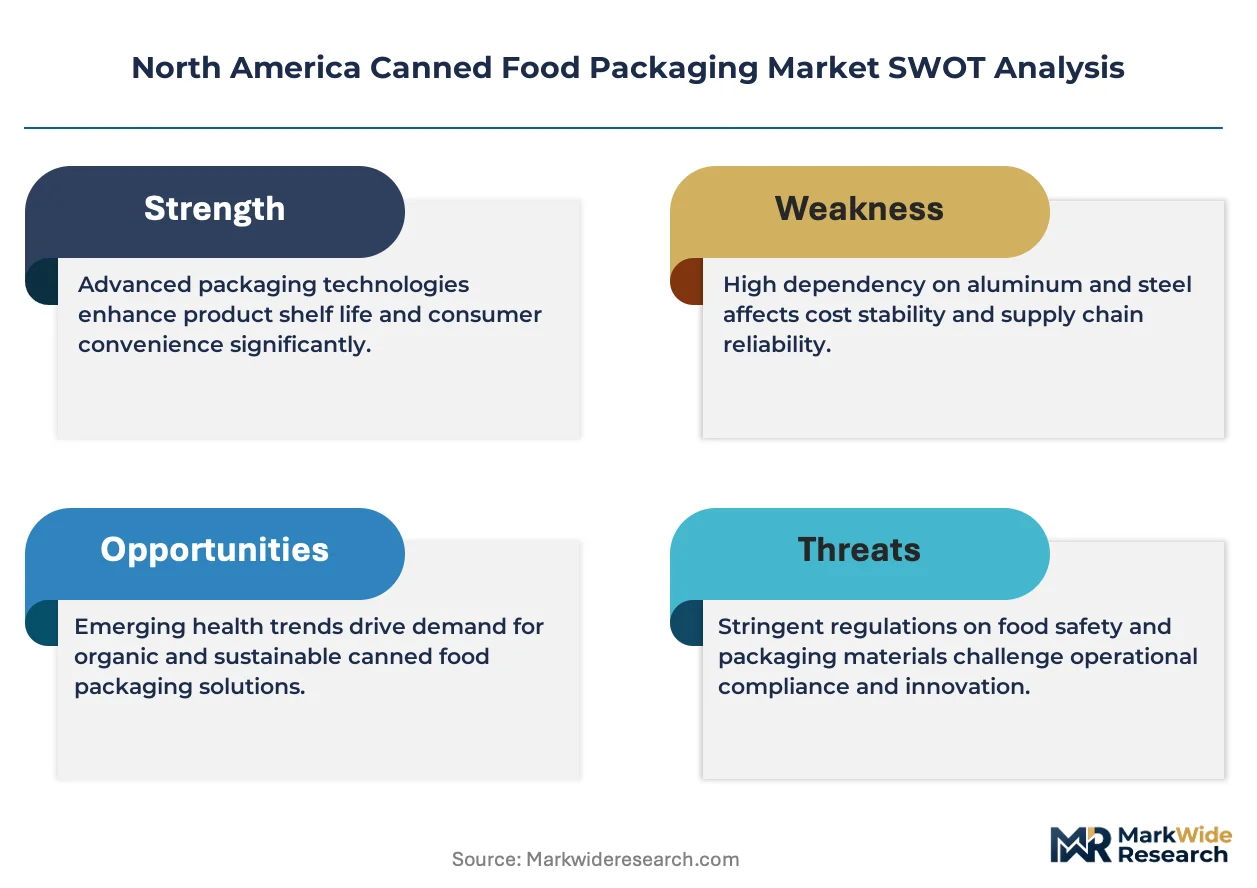
- Tinplate input cost volatility:Steel sheet pricing fluctuations and tin coating surcharges compress converter margins on three-piece vegetable and soup cans.
- Domestic canmaking capacity concentration:Limited North American two-piece aluminum food can lines create supply bottlenecks for seafood and ready-meal packers seeking lightweight alternatives.
- BPA-free coating transition costs:EPA volatile organic compound regulations and California Proposition 65 enforcement are forcing capital-intensive shifts to waterborne and UV-cured interior linings.
Strategic Opportunities
- Retortable flexible pouch expansion:Barrier film pouches for ethnic cuisine and premium pet food segments offer shape differentiation where steel cans dominate.
- USDA FSIS-inspected protein canning:Meat and poultry canning regulations create qualified supplier scarcity that converters can exploit with dedicated inspection infrastructure.
- Smart packaging-ERP convergence:Integration of IoT sensors with enterprise resource planning systems enables predictive inventory management for retail chain customers.
Industry Challenges
- Thermal process engineering talent scarcity:FDA 21 CFR Part 113 filing requirements demand specialized food safety engineers that converter plants struggle to recruit.
- Legacy coating line retrofit timelines:Waterborne and UV-cured system conversions require extended plant shutdowns that disrupt contract fulfillment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Canned Food Packaging Market |
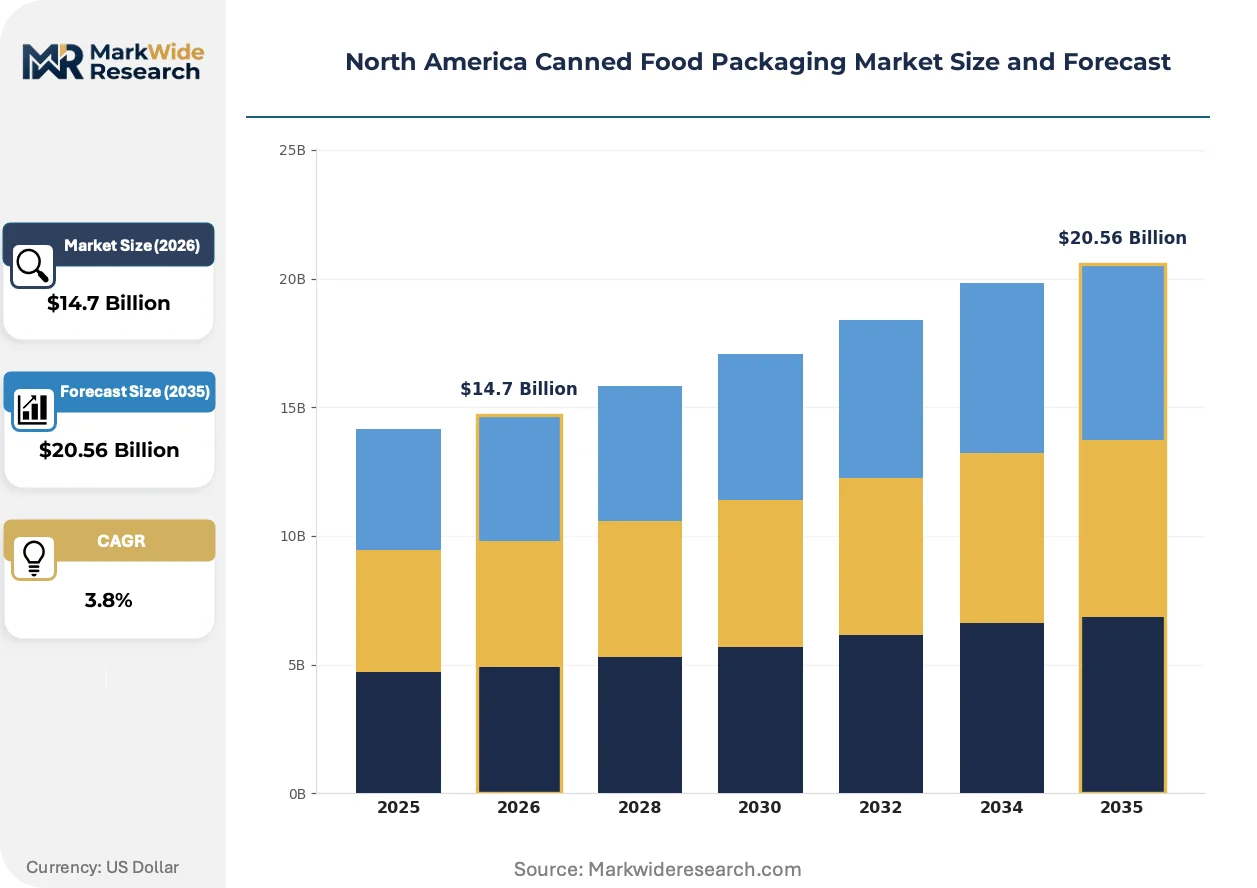
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $20.56 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Steel Cans, Aluminum Cans, Glass Jars, Flexible Pouches End User: Retail, Food Service, Industrial, Households Closure Type: Pull-Tabs, Twist-Off, Can Ends, Screw Caps Size: Small, Medium, Large, Extra Large |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Silgan Holdings Inc., Amcor plc, CANPACK S.A., Ardagh Group S.A., Sonoco Products Company, Trivium Packaging B.V., Allstate Can Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Canned Food Packaging Market Evolving Landscape
Material science advances and regulatory compliance pressures are driving simultaneous evolution in can construction, interior coatings, and supply chain traceability across North American converter operations.
Digital printing on aluminum food cans is fragmenting traditional label-based branding economics. Seafood and premium ready-meal packers are adopting direct-to-can decoration at accelerating rates. This technology is fragmenting minimum order quantity thresholds and enabling SKU proliferation that lithographic labeling cannot support.
The EPA's forthcoming coating emission standards are accelerating waterborne and UV-cured interior lining adoption. Can manufacturers face capital allocation trade-offs between compliance timelines and production continuity. Protein-focused packers under USDA FSIS oversight are experiencing the most intensive qualification delays as they dual-track coating approvals with inspection protocol updates.
Direct sourcing contracts between retail grocery chains and regional can plants are compressing traditional distributor intermediation. Store-label procurement teams now negotiate volume commitments directly with converters possessing integrated steel supply. The U.S. Southeast exhibits the most visible disintermediation as Walmart, Kroger, and Publix establish preferred supplier relationships with Crown Holdings and Silgan plants in Georgia and Alabama.
North America Canned Food Packaging Market Segmentation
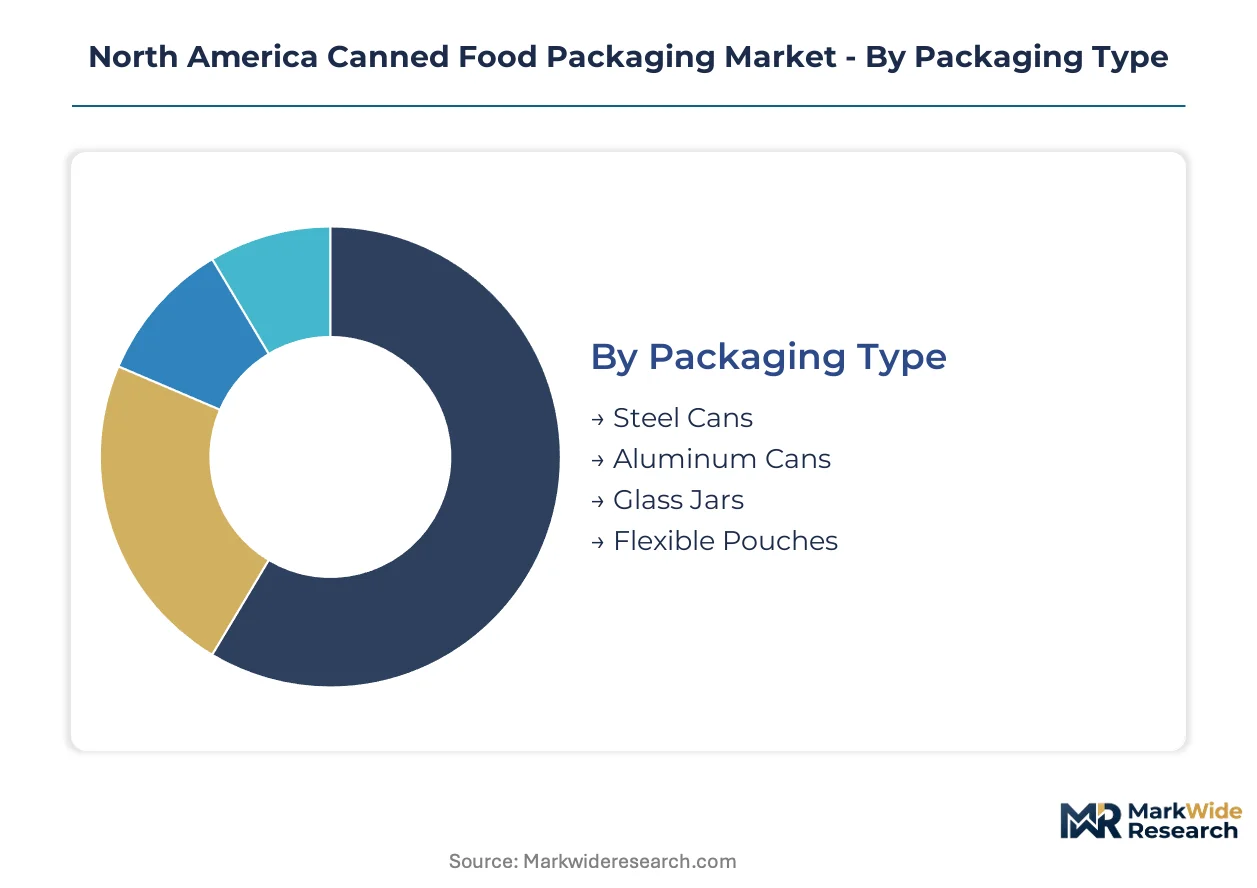
Packaging type and end-user dynamics in North American canned food markets diverge sharply between domestic retail channels and export-oriented protein processing. Understanding these splits enables converters to align capacity investments with demand geography.
Packaging Type:
Domestic retail channels favor steel and aluminum formats, while export volumes concentrate in lightweight aluminum for seafood and premium vegetable shipments to Caribbean and Latin American markets.
- Steel Cans:Three-piece tinplate construction between 0.16 mm and 0.30 mm thickness dominates vegetable and soup applications. Demand concentrates in the U.S. Southeast where Crown Holdings and Silgan operate integrated steel supply plants adjacent to protein processing clusters.
- Aluminum Cans:Two-piece drawn wall thickness below 0.13 mm enables weight-critical premium seafood and ready-meal formats. Export-led growth accelerates as Mexican and Canadian buyers seek lightweight alternatives for cross-border distribution.
- Glass Jars:Acidified foods and premium sauces retain glass preference for visual product display, though breakage rates limit export adoption.
- Flexible Pouches:Retortable barrier films capture niche ethnic cuisine and pet food segments where shape differentiation drives retail visibility in domestic specialty channels.
Steel cans hold the largest share; momentum sits with aluminum cans.
End User:
Cost tier stratification separates high-volume retail procurement from specialized food service specifications requiring smaller batch flexibility.
- Retail:Grocery chains and mass merchandisers drive procurement consolidation through direct converter contracts, with Walmart, Kroger, and Publix establishing preferred supplier relationships in Georgia and Alabama.
- Food Service:Institutional buyers and restaurant distributors specify #10 institutional cans and portion-controlled formats for back-of-house efficiency, with demand clustering in Texas and California metro corridors.
- Industrial:Ingredient suppliers and co-manufacturers purchase bulk aseptic totes and institutional sizes for further processing into sauces, soups, and prepared meals.
- Households:Direct-to-consumer subscription models and emergency preparedness purchasing spiked during recent supply disruptions, sustaining above-average growth in variety pack configurations.
Retail commands volume leadership; food service exhibits the steepest expansion trajectory as away-from-home consumption rebounds.
Closure Type:
Application-specific requirements separate easy-open convenience from resealable functionality across protein, produce, and prepared meal segments.
- Pull-Tabs:Full-aperture aluminum ends dominate ready-to-eat seafood and single-serve vegetable applications where tool-free opening drives consumer preference in convenience-oriented retail channels.
- Twist-Off:Glass jar applications in sauces, salsas, and preserves leverage lug-style metal closures for resealability, with Silgan Holdings anchoring North American supply.
- Can Ends:Two-piece steel and aluminum ends for three-piece cans retain cost advantage in high-volume vegetable and soup processing, though easy-open conversion rates climb.
- Screw Caps:Composite and plastic closures for retortable pouches and wide-mouth jars enable portion control and resealability in premium pet food and ethnic cuisine formats.
Can ends retain installed base dominance; pull-tabs gain share fastest as convenience specifications penetrate mid-tier retail.
Size:
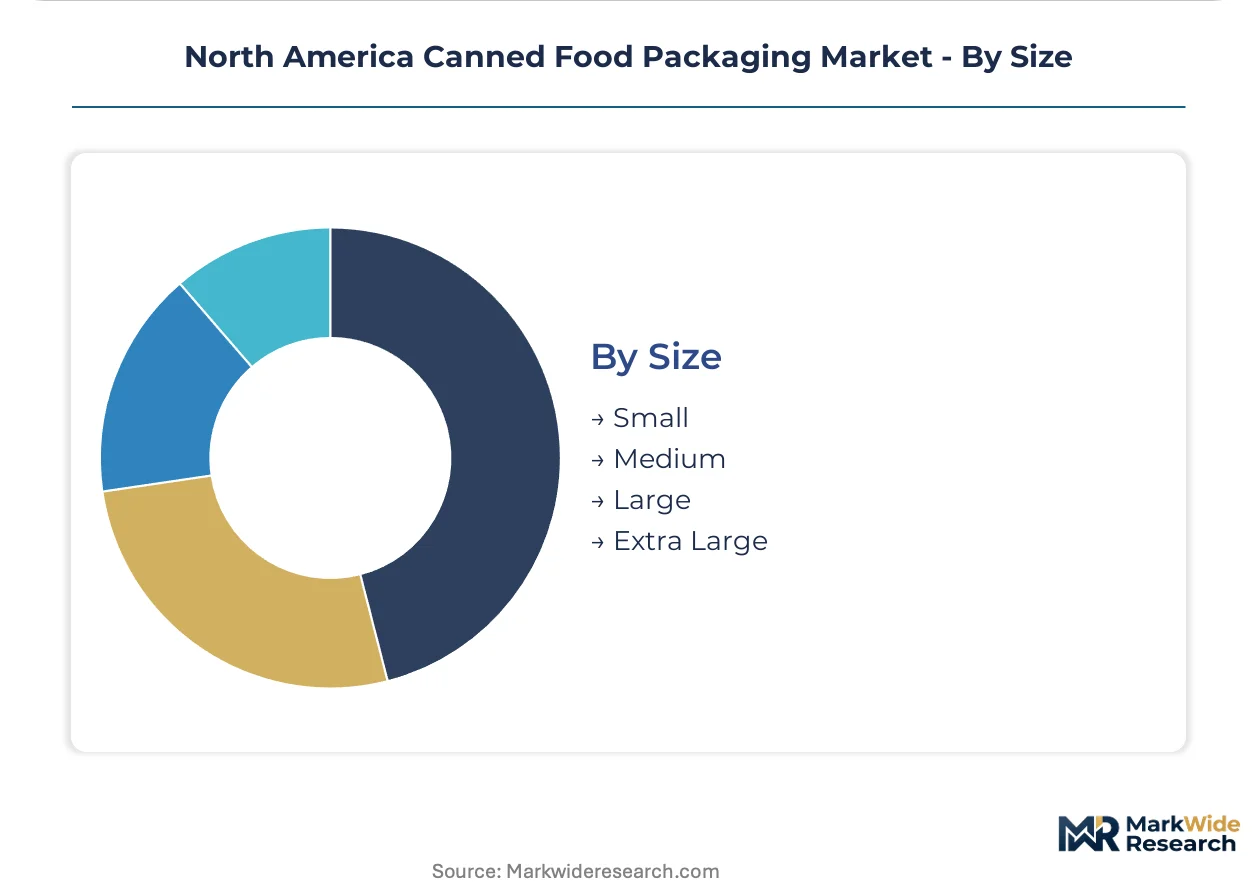
Volume scale economics separate commodity institutional formats from premium single-serve positioning in retail and food service channels.
- Small:Single-serve 4-8 oz formats target portion-controlled meal solutions and premium pet food, with aluminum construction enabling lightweight e-commerce fulfillment.
- Medium:10-16 oz family-size vegetables, soups, and ready meals represent the revenue core for Midwest and Southeast retail distribution networks.
- Large:28-32 oz value formats and #10 institutional cans serve food service back-of-house and industrial ingredient processing in Texas protein corridors.
- Extra Large:Bulk aseptic drums and totes for ingredient supply and export co-packing concentrate in Pacific Northwest and California central valley processing clusters.
Medium sizes anchor revenue; small formats climb fastest as single-serve convenience and direct-to-consumer channels expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steel supply and canmaking plants cluster in the U.S. Southeast, creating tight logistics radii with protein processing facilities. Canada and Mexico serve as export corridors for aluminum food cans, while regional regulatory divergence shapes coating qualification timelines. FDA and EPA mandates in the United States, CFIA standards in Canada, and COFEPRIS requirements in Mexico each redirect capital toward compliance infrastructure.
United States
Wet pet food manufacturers and premium seafood packers drive aluminum can demand in Georgia and Alabama processing corridors. FDA 21 CFR Part 113 thermal process filings and EPA volatile organic compound regulations force coating line retrofits in Crown Holdings and Silgan plants. Southeast protein clusters concentrate canmaking capacity within 150-mile logistics radii of Walmart and Kroger distribution centers.
Canada
Cross-border aluminum can exports to U.S. seafood packers and domestic maple syrup glass jar applications split demand between metal and rigid formats. Health Canada and CFIA alignment with FDA low-acid canned food standards streamlines qualification for integrated North American suppliers. Ontario and Quebec can plants serve as overflow capacity for U.S. Northeast retail procurement consolidation.
Mexico
Seafood export processing zones in Baja California and Sinaloa demand lightweight aluminum cans for U.S. and Latin American distribution. COFEPRIS sanitary registration requirements and NOM-130-SCFI-1999 packaging standards create dual-track compliance for multinational converters. Northern border states concentrate maquiladora can assembly for just-in-time delivery to Texas protein processing corridors.
North America Canned Food Packaging Market Competitive Landscape
Concentration sits with integrated metal packaging conglomerates possessing captive steel supply and multi-plant regional coverage. Three archetypes dominate: steel-integrated giants with beverage-to-food conversion flexibility, aluminum specialists leveraging beverage-grade expertise, and closure-dominant players controlling metal end supply. Competitive moves center on direct retail chain procurement contracts and waterborne coating line retrofits to meet EPA emission deadlines.
Among North American metal packaging conglomerates, Crown Holdings, Inc. and Silgan Holdings Inc. exemplify the steel-integrated archetype with Southeast U.S. plant networks, while Ball Corporation occupies a position as the aluminum specialist extending beverage metal expertise into food applications. These three anchors represent the supplier consolidation that grocery chains now engage directly for volume commitments, bypassing traditional distributor intermediation in Georgia and Alabama procurement corridors.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Silgan Holdings Inc. |
| Amcor plc |
| CANPACK S.A. |
| Ardagh Group S.A. |
| Sonoco Products Company |
| Trivium Packaging B.V. |
| Allstate Can Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at integrated steel mills in the U.S. Southeast anchors price floors across three-piece tinplate formats, concentrating converter bargaining power in Georgia and Alabama corridors where Crown Holdings and Silgan operate captive supply. This scale geometry compresses margins for regional independents while rewarding multi-plant networks with volume-commitment leverage against grocery chain procurement teams.
Pricing Analysis
Volume-discount tiering structures separate contract-based long-term offtake agreements from spot-market transactions across vegetable and soup can lines. Price differentiation rests on tin coating grade and steel gauge specification, with FDA 21 CFR Part 113 thermal process certification adding qualification premiums. Cost compression in standard three-piece formats intensifies as private-label retailers consolidate procurement, while premium seafood packers show lowest price sensitivity due to aluminum lightweighting requirements.
Supply Chain Analysis
Just-in-time inventory preferences dominate protein processing clusters in Georgia and Alabama, where canmaking plants sit within 150-mile logistics radii of USDA FSIS-inspected facilities. Raw material dependencies draw from domestic steel sheet production, tin ingot imports, and epoxy-phenolic coating resins. Tariff exposure on Chinese tinplate inputs creates supply chain risk. Distribution runs through direct converter-retail contracts that disintermediate traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America canned food packaging market functions as a defensive moat anchored in regulatory entrenchment — FDA thermal process filing requirements and EPA coating compliance create qualified-supplier scarcity that protects incumbent positions.
For Market Incumbents: Secure captive steel supply agreements and waterborne coating line retrofits ahead of EPA emission deadlines. Threats from flexible pouch substitutes in pet food segments demand defensive capacity conversion in retortable barrier films. Channel control through direct Walmart and Kroger contracts remains the critical lever. For New Entrants and Emerging Players: Smart packaging integration gaps where incumbents under-serve FSMA traceability mandates offer white-space entry. Target USDA FSIS-inspected protein canning in Texas corridors where qualified converter scarcity persists. Go-to-market positioning around blockchain-enabled lot tracking separates new entrants from legacy lithographic suppliers. For Investors and Strategic Acquirers: Regional can plants with integrated steel supply and Southeast logistics positioning represent the acquisition target archetype. Long-term viability hinges on coating compliance infrastructure and retail direct-contract penetration. Watch California Proposition 65 enforcement intensity as inflection indicator for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Coating Line Retrofit | EPA volatile organic compound compliance protects operating licenses for Crown Holdings and Silgan plants. |
| Direct Retail Chain Contracting | Walmart and Kroger volume commitments in Georgia disintermediate traditional distributor networks. |
| Retortable Flexible Pouch Capacity | Barrier film expansion captures wet pet food volume surge outside traditional steel can formats. |
| Smart Packaging-ERP Integration | IoT sensor convergence with enterprise systems enables predictive inventory for FSMA traceability. |
| USDA FSIS Inspection Infrastructure | Dedicated protein canning qualification creates supplier scarcity that converters exploit for margin. |
Research Methodology
Cross-validation between converter plant managers and grocery chain procurement directors anchors the qualitative findings in operational reality. Primary interviews with steel mill metallurgists, EPA compliance officers, FDA thermal process specialists, and private-label category buyers combined with secondary validation from SEC 10-K filings, EPA emission disclosure databases, and USDA FSIS inspection records. Bottom-up capacity modeling and top-down retail channel triangulation produced convergent volume estimates.
Sensitivity analysis across tinplate pricing scenarios and coating transition timelines stress-tested projection robustness. Segmentation dimensions modeled include packaging material type, end-user channel, closure mechanism, and geographic processing cluster. CAGRs derived from installed capacity expansion schedules and retail procurement consolidation trajectories. Industry-specific inputs incorporated wet pet food formulation shifts and FSMA implementation phasing.
Material uncertainties — steel tariff volatility, EPA standard finalization dates, and BPA-free coating qualification delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance timelines and retail consolidation continuity. Revision becomes warranted when tinplate input cost fluctuations exceed historical bands or California Proposition 65 enforcement triggers accelerated coating line shutdowns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Burger Boxes Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Probiotics Packaging Market