
 APAC Canned Food Packaging Market | 2026-2036
APAC Canned Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Canned Food Packaging Market Outlook
Supermarket private-label supply chains are reshaping procurement patterns across the APAC Canned Food Packaging Market. Crown Holdings leverages its regional manufacturing footprint to serve multinational retail contracts. Toyo Seikan Group Holdings Ltd. anchors Japanese demand through advanced surface-coating technologies. Tata Tinplate competes on cost-efficient tinplate sourcing from Indian integrated steel mills.
APAC canned food packaging encompasses metal containers engineered from aluminum, steel, or tinplate substrates, typically formed through draw-and-wall-iron or three-piece welding processes, with internal epoxy-phenolic linings to prevent corrosion and preserve shelf stability for 24-60 months. The primary commercial purpose is hermetic sealing that blocks oxygen, light, and microbial ingress for processed proteins, vegetables, and ready meals. Aluminum material type leads volume in Southeast Asian seafood exports due to lightweight logistics and rapid chilling compatibility. Small-size cans represent the fastest-growing dimension, driven by single-serve urban consumption and airline-catering contracts across Singapore and Hong Kong.
Japan's METI enforces strict JIS standards for can-coating migration limits, while China's SAMR mandates GB-compliant food-contact declarations for all imported packaging substrates. Australia's TGA-aligned state food authorities impose additional thermal-processing verification for low-acid canned goods entering Pacific trade lanes. Stakeholders must monitor evolving biodegradable material certifications, as India's FSSAI and Thailand's FDA draft parallel standards that could fragment compliance requirements across the region.
Market Dynamics
Supermarket private-label supply chains are consolidating procurement power across the APAC Canned Food Packaging Market, forcing converters to restructure volume commitments and coating specifications around retail-dictated standards rather than brand-owner requirements.
Growth Catalysts
- India's BIS certification requirements:Food-contact material standards are tightening quality benchmarks, pushing regional suppliers toward epoxy-phenolic lining upgrades and migration-limit testing protocols.
- Urban ready-to-eat meal adoption:Single-serve can demand from Singapore and Hong Kong airline-catering contracts is expanding addressable volume for small-dimension formats.
- Aluminum lightweight logistics:Southeast Asian seafood exporters are prioritizing rapid-chill-compatible substrates to reduce freight costs and cold-chain energy intensity.
Market Restraints
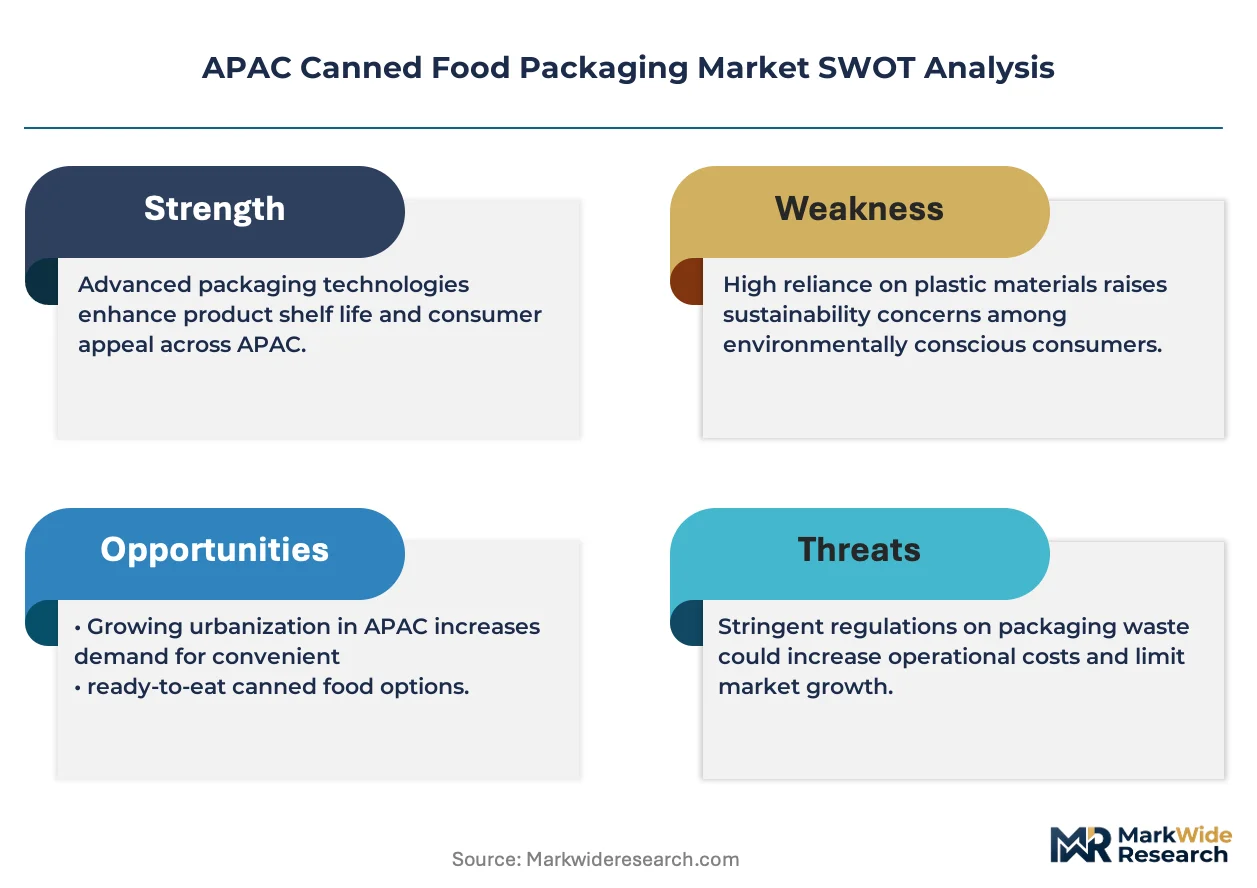
- Tinplate input cost volatility:Indian integrated steel mill pricing swings directly compress margin structures for regional can manufacturers dependent on domestic tinplate sourcing.
- Japan METI migration-limit enforcement:JIS coating standards create technical barriers for imported substrates that lack documented phenolic-epoxy compliance histories.
- Flexible pouch substitution:Retortable laminate formats are capturing ambient protein segments where shelf stability requirements permit non-rigid alternatives.
Strategic Opportunities
- Vietnam export-processing zones:Seafood canning clusters around Ho Chi Minh City offer underpenetrated demand for hermetic-sealing equipment and local coating application services.
- Thailand FDA biodegradable standards:Draft certification frameworks for bio-based can linings create first-mover positioning for epoxy-alternative chemistries.
- Digital print-to-can integration:Variable-data decoration convergence with draw-and-wall-iron forming enables short-run private-label responsiveness for Japanese convenience retail.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for low-migration epoxy-phenolic systems is concentrating at Japanese and Korean research centers, constraining regional capacity expansion.
- China SAMR import-declaration timelines:GB-compliant food-contact documentation requirements extend certification cycles for cross-border substrate shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Canned Food Packaging Market |
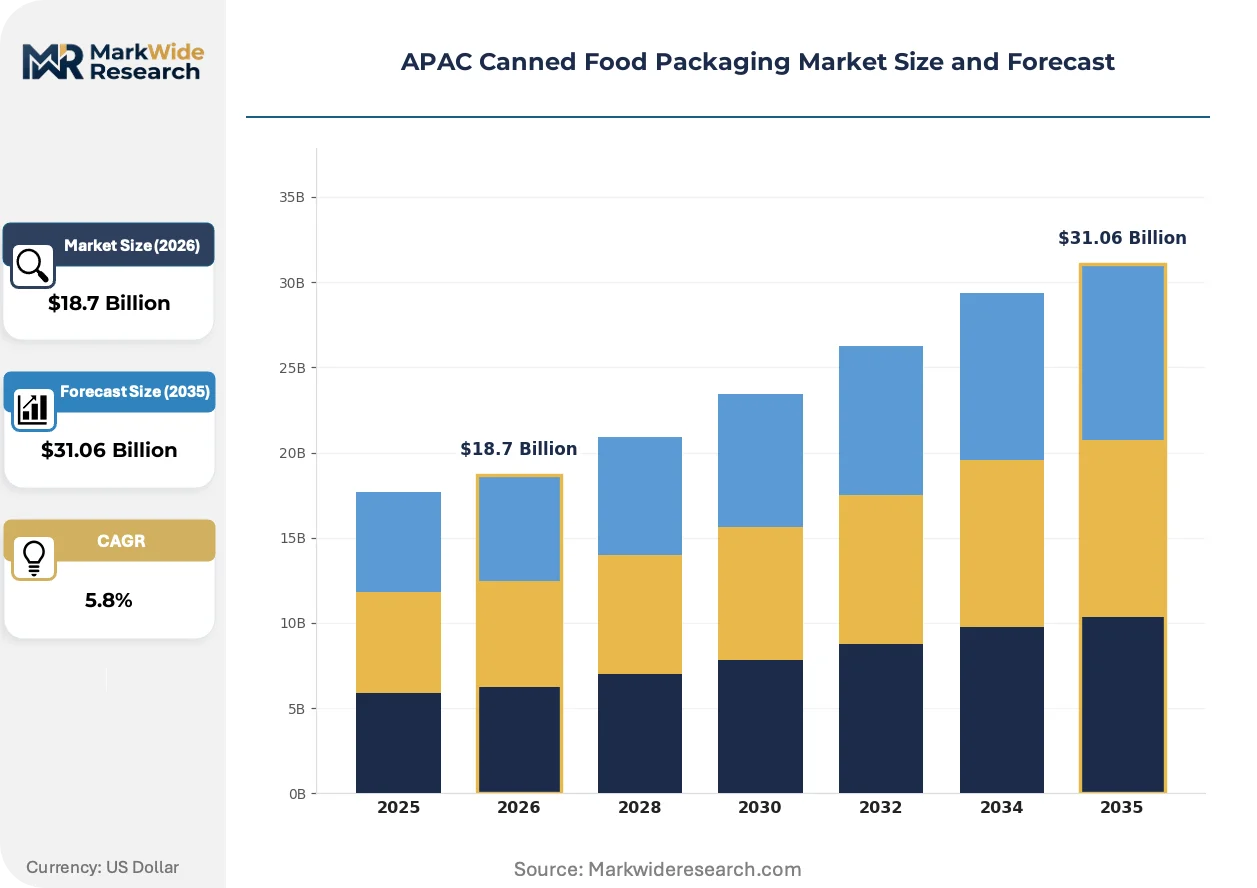
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
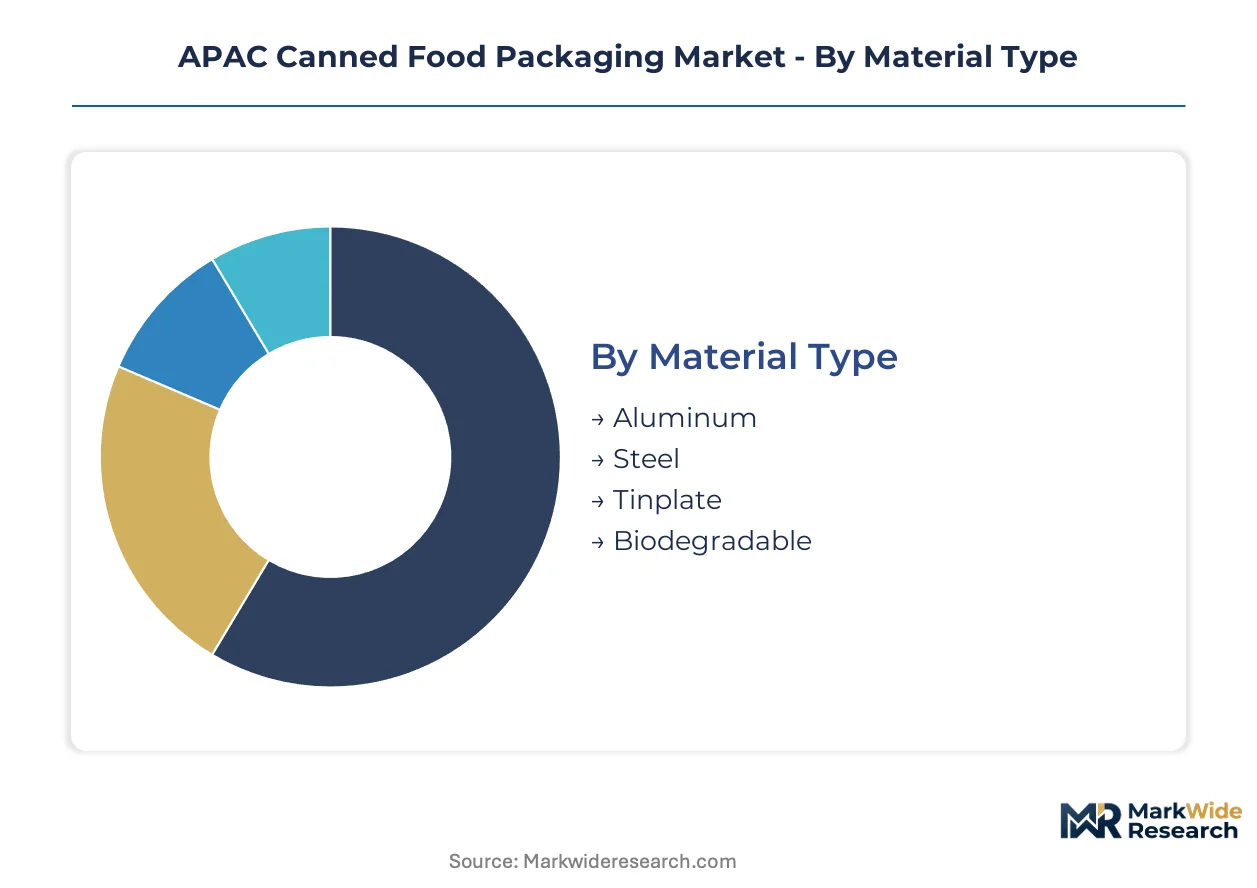
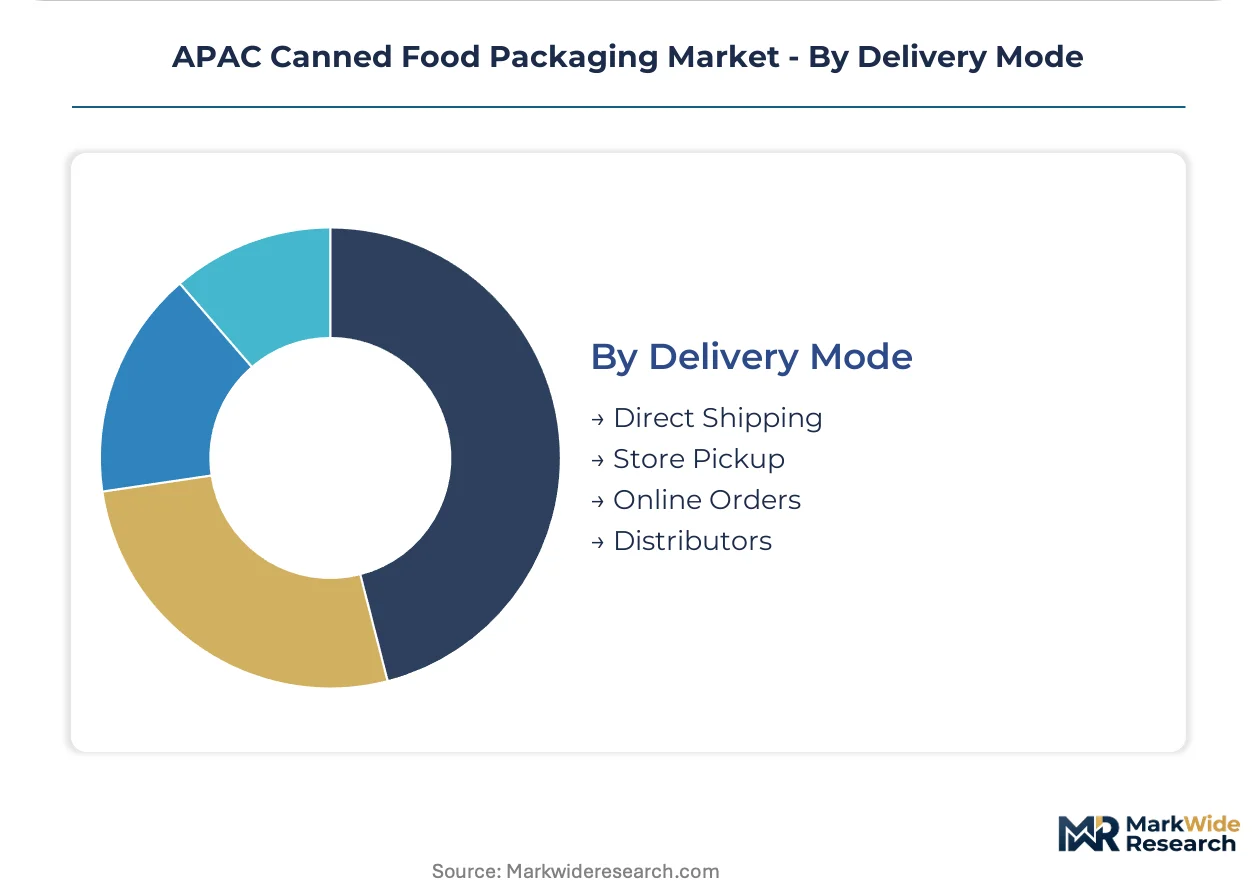
| Segmentation | Material Type: Aluminum, Steel, Tinplate, Biodegradable End User: Retail, Food Services, Exporters, Manufacturers Size: Small, Medium, Large, Family Size Delivery Mode: Direct Shipping, Store Pickup, Online Orders, Distributors |
| Companies Covered | Crown Holdings, Inc., Ball Corporation, Ardagh Group, Can-Pack S.A., Silgan Holdings Inc., Trivium Packaging, Toyo Seikan Group Holdings Ltd., Tata Tinplate, Visy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Canned Food Packaging Market Strategic Shifts
Surface-coating digitization and substrate lightweighting are redefining competitive capability boundaries across APAC can manufacturing, while regulatory fragmentation around biodegradable alternatives is forcing parallel compliance investments.
Digital inkjet decoration systems are virtualizing traditional gravure-based print workflows for short-run promotional and seasonal SKUs. Japanese beverage and prepared-meal brands are piloting these systems at three-to-six-month refresh cycles. This technology is virtualizing the economics of minimum-order quantities, compressing run-length thresholds from hundreds of thousands to tens of thousands of units without cylinder-changeover penalties.
China's SAMR GB standards for food-contact declarations are mandating substrate-level traceability documentation for all imported tinplate and aluminum coil. The industrial consequence is a documentation burden shift onto Southeast Asian converters who must now maintain batch-level coating-chemistry records. Low-acid canned goods entering Pacific trade lanes through Australian ports are experiencing the most intensive thermal-processing verification requirements under TGA-aligned state protocols.
Single-serve urban consumption patterns are fragmenting volume concentration away from institutional bulk formats toward airline-catering and convenience-retail channels. Singapore and Hong Kong procurement offices are consolidating specifications across multiple retail banners, replacing fragmented brand-owner purchasing with centralized private-label sourcing. Thailand and Vietnam seafood processors are responding by dedicating separate production lines to small-dimension formats with premium surface finishes.
APAC Canned Food Packaging Market Segmentation
APAC can manufacturers configure production lines around substrate metallurgy, end-user logistics, and dimensional specifications that vary sharply across Japanese retail, Vietnamese seafood export, and Indian domestic consumption channels. Segmentation discipline determines coating chemistry investments, forming equipment selection, and inventory positioning across dispersed regional demand centers.
Material Type:
Substrate selection maps directly to thermal processing requirements, cold-chain intensity, and regulatory migration limits across the region's divergent food safety regimes.
- Aluminum:Drawn-and-ironed aluminum delivers weight advantages for Southeast Asian seafood exporters shipping to European and North American markets. Vietnam's rapid-chill processing clusters favor aluminum for its thermal conductivity and reduced freight cost burden.
- Steel:Three-piece welded steel cans dominate institutional ready-meal formats where structural rigidity withstands retort sterilization pressures. India's integrated steel mills supply cost-competitive substrate for domestic vegetable and dairy canning operations.
- Tinplate:Electrolytic tinplate remains the reference standard for acidic food categories requiring corrosion resistance through multi-year shelf stability.
- Biodegradable:Experimental bio-based linings and substrate coatings are attracting pilot investment ahead of Thailand FDA draft certification frameworks.
Established volume favors steel; emerging adoption favors aluminum.
End User:
Procurement concentration patterns split between consolidated retail banners and fragmented food service distributors.
- Retail:Supermarket private-label supply chains are consolidating specification power across Singapore and Hong Kong, forcing converters to restructure coating commitments around retail-dictated standards rather than legacy brand-owner requirements.
- Food Services:Airline-catering contractors and institutional meal providers drive small-dimension format demand with premium surface finish requirements.
- Exporters:Vietnam and Thailand seafood processors require hermetic-sealing validation for cross-Pacific shipment compliance.
- Manufacturers:Co-packing and toll-canning operations serving multinational brand owners concentrate in China's coastal manufacturing zones.
Volume concentrates with retail; margin expansion concentrates with food services.
Size:
Urban consumption fragmentation is redistributing production capacity across dimensional tiers.
- Small:Single-serve formats are climbing the fastest as Singapore and Hong Kong convenience retail and airline-catering procurement offices consolidate specifications across multiple banners.
- Medium:Standard household portions retain dominance in Japanese and Korean prepared-meal segments where METI coating standards enforce consistent migration limits.
- Large:Institutional and food service bulk formats face substitution pressure from flexible retort pouches where shelf stability permits.
- Family Size:Multi-serve cans persist in price-sensitive Indian and Indonesian mass-market channels.
Production capacity tilts toward small; margin per unit favors medium.
Delivery Mode:
Logistics configuration determines coating shelf life, inventory turns, and documentation burden.
- Direct Shipping:Large-volume contracts from Vietnamese seafood processors to European importers bypass distributor markup but require batch-level SAMR GB-compliant traceability documentation.
- Store Pickup:Japanese convenience retail chains operate on three-to-six-month refresh cycles that favor digital print-to-can integration for seasonal SKUs.
- Online Orders:E-commerce direct-to-consumer channels are gaining share fastest in South Korean and Australian urban markets where last-mile cold chain reliability supports premium positioning.
- Distributors:Traditional wholesale networks retain importance in Indonesian and Philippine archipelago logistics where inter-island shipping fragmentation complicates direct manufacturer relationships.
Efficiency concentrates in direct shipping; growth velocity concentrates in online orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification requirements for food-contact materials are tightening quality benchmarks across the region. Japan's METI enforces strict JIS standards for can-coating migration limits. China's SAMR mandates GB-compliant food-contact declarations for imported packaging substrates.
China
Coastal manufacturing zones concentrate toll-canning operations serving multinational brand owners. SAMR's GB standards mandate substrate-level traceability documentation for all imported tinplate and aluminum coil. Yangtze River Delta converters maintain batch-level coating-chemistry records to satisfy cross-border compliance requirements.
Japan
METI's JIS coating standards create technical barriers for imported substrates lacking documented phenolic-epoxy compliance histories. Kanto and Kansai regions anchor prepared-meal segments where migration limits enforce consistent quality. Tokyo-based convenience retail chains operate on three-to-six-month refresh cycles favoring digital print-to-can integration.
India
Integrated steel mills supply cost-competitive tinplate substrate for domestic vegetable and dairy canning operations. BIS certification requirements push regional suppliers toward epoxy-phenolic lining upgrades and migration-limit testing protocols. Maharashtra and Gujarat house the primary can manufacturing clusters serving mass-market channels.
Vietnam
Seafood canning clusters around Ho Chi Minh City generate underpenetrated demand for hermetic-sealing equipment and local coating application services. Rapid-chill processing favors aluminum for thermal conductivity and reduced freight cost burden. Export-processing zones concentrate procurement from European and North American importers requiring SAMR GB-compliant traceability documentation.
Thailand
Seafood processors dedicate separate production lines to small-dimension formats with premium surface finishes. FDA draft certification frameworks for bio-based can linings create first-mover positioning for epoxy-alternative chemistries. Bangkok-centered procurement offices consolidate specifications across multiple retail banners, replacing fragmented brand-owner purchasing with centralized private-label sourcing.
APAC Canned Food Packaging Market Competitive Environment
On the supply side, the industry is consolidating around multinational packaging conglomerates with regional manufacturing footprints and specialized coating technology providers. Tiered competition separates scale-driven metal container fabricators from niche specialists in surface-coating digitization and substrate lightweighting. Strategic archetypes include integrated steel-to-can manufacturers, advanced coating technology licensors, and private-label supply chain consolidators. Dominant competitive moves center on capacity expansion in Vietnamese export-processing zones and strategic partnerships for digital print-to-can integration serving Japanese convenience retail.
Among Asia-Pacific-based specialists, Toyo Seikan Group Holdings Ltd. and Tata Tinplate exemplify contrasting archetypes within the regional supply base. Toyo Seikan Group Holdings Ltd. represents the advanced coating technology tier, while Tata Tinplate occupies a position within the integrated steel-to-can manufacturing segment. Crown Holdings, Inc. anchors the multinational scale-driven tier with regional manufacturing footprint breadth. These three entities collectively illustrate the competitive segmentation between technology-led, resource-integrated, and globally scaled market positions.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Ball Corporation |
| Ardagh Group |
| Can-Pack S.A. |
| Silgan Holdings Inc. |
| Trivium Packaging |
| Toyo Seikan Group Holdings Ltd. |
| Tata Tinplate |
| Visy Industries |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Singapore container freight corridors transmit tinplate input cost volatility directly into margin structures for regional can manufacturers, concentrating pricing power among integrated steel-to-can producers while fragmenting downstream price differentiation across certification-grade tiers.
Pricing Analysis
Certification level creates the primary spread between premium JIS-compliant Japanese substrates and standard-grade Indian tinplate. Three-tier pricing structure across premium, standard, and economy levels reflects BIS migration-limit testing investments, METI documentation depth, and SAMR traceability batch records. Cost compression in economy-grade segments is intensifying because integrated Indian steel mills are passing through raw material swings. Food service distributors and airline-catering contractors show least price sensitivity due to premium surface finish requirements; mass-market Indian vegetable canners exhibit highest sensitivity to tinplate substrate movements.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk calculus for aluminum coil shipments serving seafood export processors. Raw material sourcing draws from Chinese electrolytic tinplate production, Indian integrated steel mill output, and Southeast Asian aluminum smelter capacity. Single-source vulnerability concentrates in Japanese epoxy-phenolic coating chemistry licensors. Distribution runs through Vietnamese export-processing zone clusters for European-bound seafood, Japanese convenience retail consolidation hubs for prepared meals, and Indonesian inter-island wholesale networks for archipelago penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible retort pouch substitution threatens rigid can volumes across ambient protein segments where shelf stability requirements permit non-rigid alternatives, forcing incumbents to defend through coating technology differentiation and small-format premium positioning.
For Market Incumbents: Harden JIS-compliant coating chemistry capabilities against Korean research center concentration by acquiring Southeast Asian formulation talent pools. Expand hermetic-sealing equipment deployment in Vietnamese export-processing zones to capture seafood processor line-dedication demand. Defend against flexible pouch incursion through premium small-dimension format investments targeting Singapore and Hong Kong airline-catering procurement consolidation.
For New Entrants and Emerging Players: Vietnamese seafood canning clusters around Ho Chi Minh City offer underpenetrated demand for local coating application services and hermetic-sealing equipment supply. Thailand FDA draft biodegradable certification frameworks create white-space positioning for epoxy-alternative chemistry pilot programs. Digital print-to-can integration partnerships with Japanese convenience retail chains provide the most penetrable go-to-market angle for short-run promotional SKU responsiveness.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates seeking to divest non-core regional manufacturing footprints. Long-term viability across the analysis window hinges on coating technology licensing positions and Vietnamese export-processing zone capacity access. Watch Thailand FDA finalization of bio-based lining standards as the signal for epoxy-alternative chemistry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Epoxy-Phenolic Coating Capacity Expansion | Captures BIS and METI compliance premiums tightening across Indian and Japanese regulatory regimes. |
| Backward Integration into Tinplate Sourcing | Insulates margin structures from Indian integrated steel mill pricing volatility. |
| Digital Print-to-Can Technology Partnership | Enables three-to-six-month refresh cycles for Japanese convenience retail seasonal SKUs. |
| Hermetic-Sealing Equipment Localization | Serves Vietnamese seafood export processors requiring SAMR GB-compliant traceability documentation. |
| Bio-Based Lining Certification Investment | Positions for Thailand FDA draft standards finalization ahead of epoxy-alternative demand inflection. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with coating chemists, can manufacturing plant managers, seafood export procurement officers, and airline-catering supply chain directors; alongside secondary validation through SAMR GB standard filings, BIS certification registries, Japanese METI JIS compliance documentation, customs trade data for tinplate and aluminum coil movements, and SEC filings from multinational packaging conglomerates. Bottom-up volume triangulation across material type, end user, and dimensional segments converged with top-down macroeconomic anchoring.
Forecast inputs incorporated substrate metallurgy evolution, regulatory certification timeline acceleration, and urban consumption fragmentation patterns across the projection horizon. Segmentation modeling spanned material type, end-user procurement concentration, dimensional specifications, and delivery mode logistics configuration. CAGRs were derived from growth driver elasticity analysis against observed historical volume relationships. Industry-specific forecast inputs included Thailand FDA biodegradable standard progression and Vietnam export-processing zone capacity buildout rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by flexible packaging specialists or bio-based coating technology disruptors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Pet Food Packaging Market