
 Progressive Supranuclear Palsy (PSP) Market | 2026-2036
Progressive Supranuclear Palsy (PSP) Market Size, Share, and Industry Trends Forecast 2026-2036
Progressive Supranuclear Palsy (PSP) Market Analytics
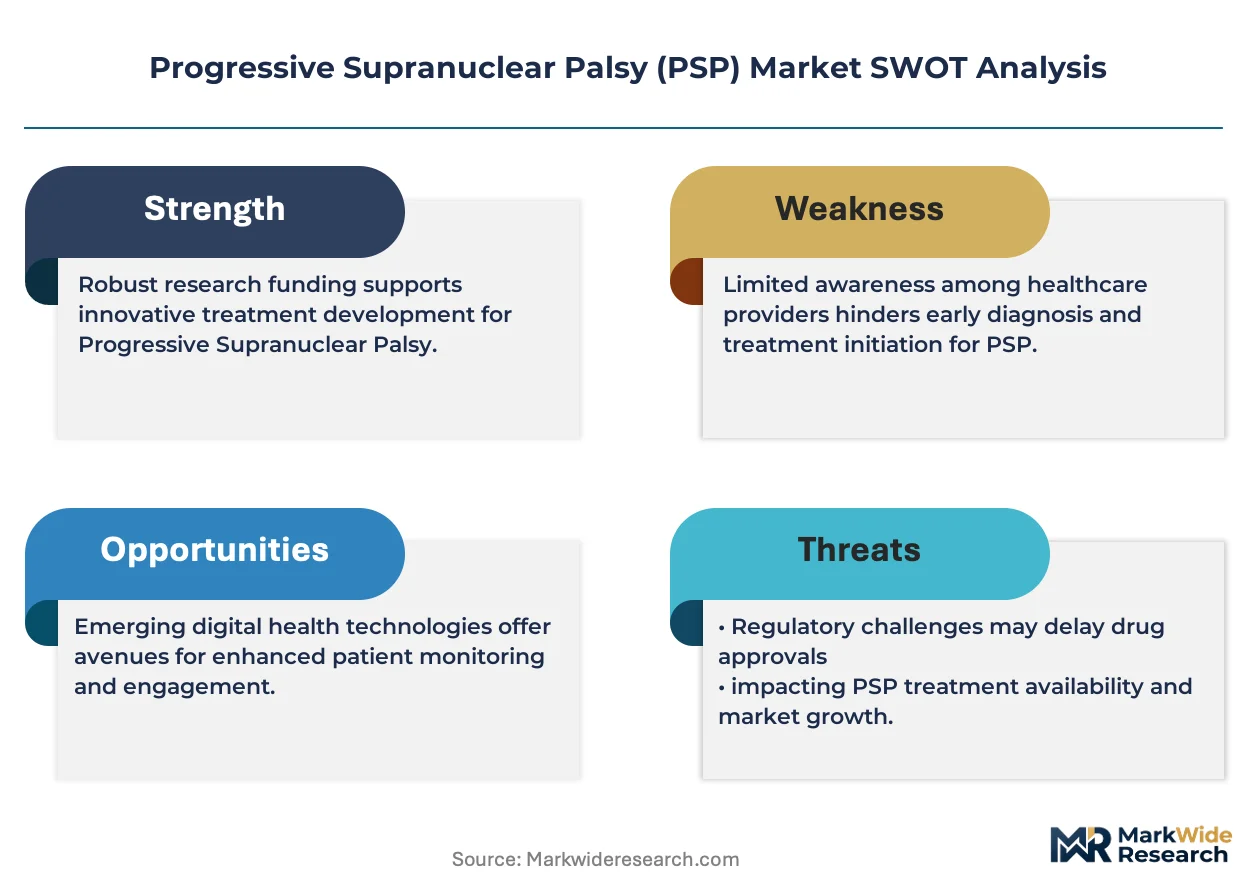
A shortage of movement disorder neurologists is unwinding patient access to timely PSP diagnosis across developed healthcare systems. Roche leverages its deep neurodegeneration pipeline to sustain research momentum in tau-targeting modalities. Biogen Inc. anchors its position through specialized rare disease infrastructure that supports complex trial enrollment. AbbVie Inc. competes by extending its parkinsonian franchise into adjacent atypical syndromes with overlapping symptomatology.
Progressive Supranuclear Palsy denotes a rare, rapidly progressive four-repeat tauopathy characterized by vertical supranuclear gaze palsy, postural instability, and frontal-subcortical cognitive decline, with pathological aggregation of tau protein in basal ganglia, brainstem, and cerebellar nuclei driving neuronal loss. The condition primarily demands disease-modifying interventions that halt tau propagation, alongside symptomatic management of mobility and speech deficits. Disease-modifying treatment commands the deepest investment intensity as candidates target tau aggregation mechanisms, while diagnostic tools represent the fastest-expanding segment as biomarker-based differentiation from Parkinson's disease becomes clinically essential. Hospitals occupy the dominant end-user position due to multidisciplinary care requirements, though home healthcare is gaining traction as oral symptomatic therapies mature.
The FDA Orphan Drug program and EMA PRIME pathway shape trial economics by granting protocol assistance and market exclusivity incentives for PSP developers. FDA breakthrough therapy designations further compress review timelines for agents demonstrating clinically meaningful endpoints in this fatal condition. Stakeholders must monitor tau PET tracer validation and fluid biomarker standardization as these will determine which development programs secure reimbursement and prescriber adoption.
Market Dynamics
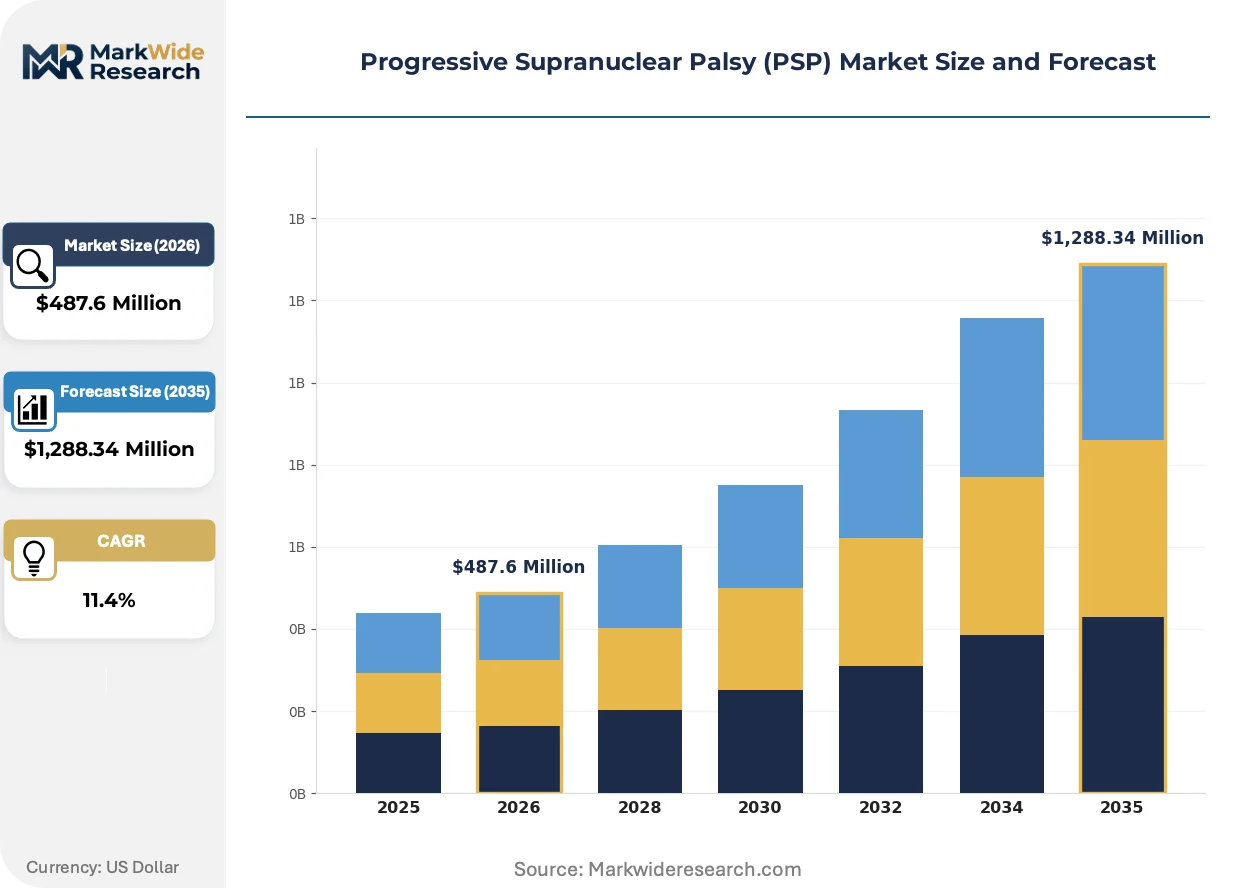
The Progressive Supranuclear Palsy market pivots on tau-targeting therapeutic development, with regulatory acceleration programs compressing trial timelines and diagnostic biomarker validation determining commercial viability.
Growth Catalysts
- FDA Orphan Drug Designation:This program grants protocol assistance and market exclusivity incentives, reducing regulatory friction for developers pursuing disease-modifying tau therapies in the United States.
- EMA PRIME Scheme:European developers gain accelerated assessment pathways and enhanced regulatory dialogue, shortening time-to-market for PSP candidates targeting unmet neurological needs.
- Movement Disorder Unit Expansion:Neurology clinics across Germany, Japan, and the United States are establishing dedicated atypical parkinsonian referral networks, tightening diagnostic capture rates.
Market Restraints
- Specialist Neurologist Scarcity:The shortage of trained movement disorder specialists across developed healthcare systems creates diagnostic bottlenecks, delaying patient identification and trial enrollment.
- Tau PET Tracer Validation Gaps:Incomplete standardization of imaging biomarkers limits reproducibility across clinical sites, constraining regulatory acceptance of surrogate endpoints.
- Fluid Biomarker Fragmentation:Competing assay platforms for cerebrospinal fluid tau species generate inconsistent readouts, complicating multi-center trial harmonization and payer evidence requirements.
Strategic Opportunities
- Home Healthcare Channel Maturation:Oral symptomatic therapies for mobility and speech deficits enable care migration from hospital settings, opening reimbursement negotiations with managed care organizations.
- Biomarker-Gated Trial Design:Stratification by tau PET or CSF profile allows enrichment strategies that reduce sample sizes and accelerate proof-of-concept readouts.
- Japan's Geriatric Neurology Infrastructure:The country's established dementia care pathways and centralized specialist networks offer streamlined access to rapidly progressing tauopathy populations.
Industry Challenges
- Neuroimaging Interpretation Skill Deficit:Radiologists and movement disorder neurologists require specialized training to distinguish PSP from Parkinson's disease and corticobasal syndrome on structural MRI and emerging tau PET.
- Multi-Site Data Integration Complexity:Heterogeneous electronic health record systems across academic medical centers impede real-world evidence collection for post-market surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progressive Supranuclear Palsy (PSP) Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Symptomatic Treatment, Disease-Modifying Treatment, Diagnostic Tools, Supportive Therapies Therapy Area: Neurology, Geriatrics, Movement Disorders, Rare Diseases End User: Hospitals, Outpatient Clinics, Research Institutions, Home Healthcare Delivery Mode: Oral, Injectable, Intranasal, Transdermal |
| Companies Covered | Novartis AG, Roche, AbbVie Inc., Biogen Inc., Teva Pharmaceutical Industries, Bristol-Myers Squibb Company, Acorda Therapeutics Inc., UCB Biopharma, Asceneuron Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progressive Supranuclear Palsy (PSP) Market Evolving Landscape
Tau-targeting modalities are fragmenting across immunotherapy, small-molecule aggregation inhibitors, and antisense approaches, while diagnostic innovation races to enable presymptomatic detection.
Tau PET ligands are bifurcating the diagnostic landscape. Second-generation tracers with higher binding affinity to four-repeat tau isoforms enable in vivo staging of pathology burden. Academic medical centers in the United States and Germany are adopting these tools for differential diagnosis protocols. The technology is bifurcating patient selection for trials, separating biomarker-confirmed from clinically probable cases and compressing enrollment timelines.
EMA's PRIME eligibility criteria are tightening evidentiary standards for breakthrough designations in neurodegeneration. Developers must now demonstrate clinically meaningful endpoint changes rather than biomarker modulation alone. European trial sponsors are responding by embedding patient-reported outcome measures and caregiver burden instruments into Phase II protocols.
Referral patterns are consolidating around tertiary movement disorder centers. Community neurologists in the United States are deferring atypical parkinsonian diagnoses to academic hubs with multidisciplinary teams. This concentration is visible most acutely in California, Massachusetts, and Pennsylvania, where dedicated PSP clinics coordinate speech therapy, physical therapy, and palliative care through single-entry portals.
Progressive Supranuclear Palsy (PSP) Market Segmentation
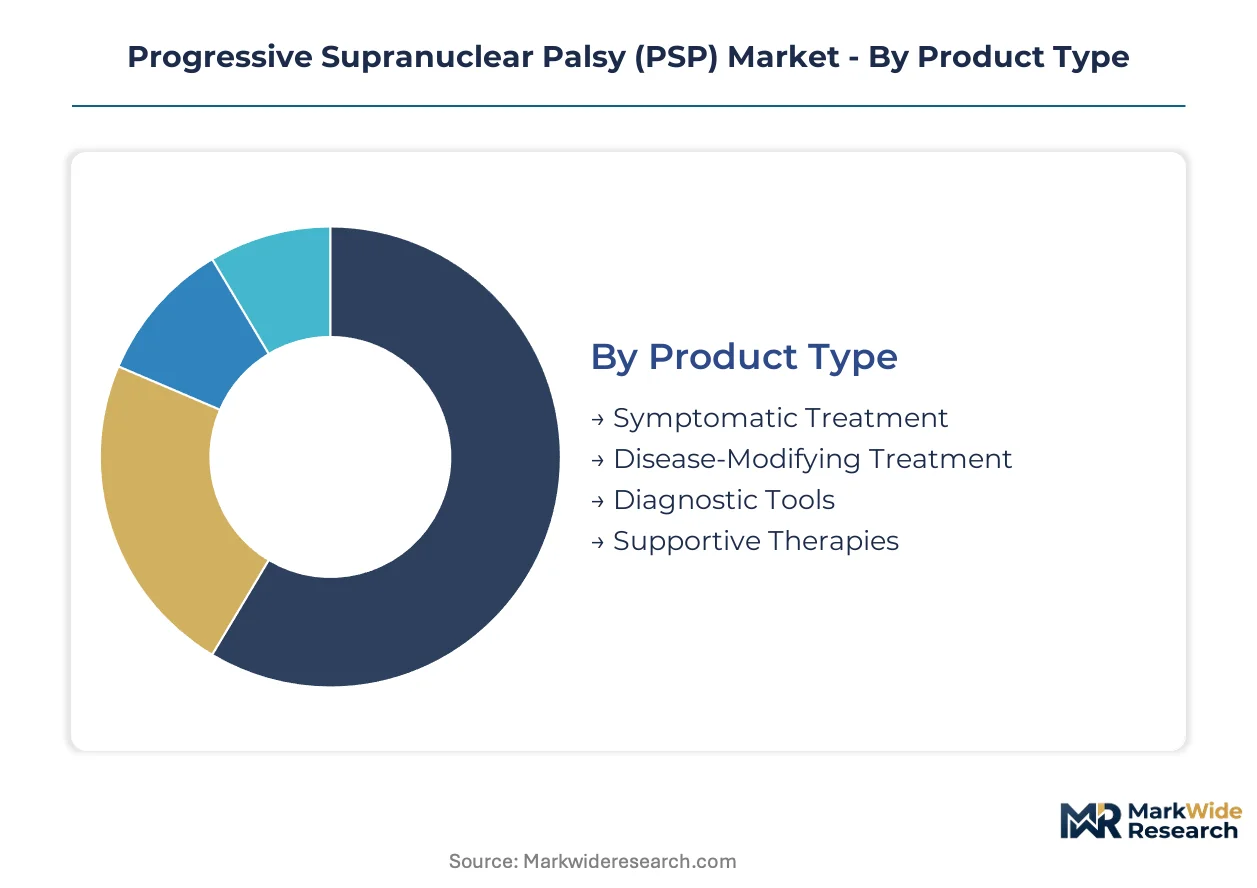
Segmentation in the PSP market reveals how therapeutic innovation, diagnostic capability, and care delivery settings interact. Each dimension shapes reimbursement pathways, prescriber access, and development priorities for tau-targeting candidates.
Product Type:
Channel flows diverge sharply: disease-modifying candidates require hospital-based infusion centers and specialized neurology units, while symptomatic and supportive therapies migrate toward retail pharmacy and home delivery channels.
- Symptomatic Treatment:Oral agents targeting mobility deficits and pseudobulbar affect dominate current prescribing. Demand clusters in movement disorder clinics across the United States and Germany, driven by immediate patient functional needs and established reimbursement for parkinsonian symptom management.
- Disease-Modifying Treatment:Tau aggregation inhibitors and immunotherapies represent the deepest R&D investment. Enrollment concentrates at academic medical centers with PET imaging capabilities and CSF biomarker processing, constrained by FDA protocol requirements and EMA evidentiary standards.
- Diagnostic Tools:Tau PET ligands and fluid biomarker assays enable differential diagnosis from Parkinson's disease and corticobasal syndrome.
- Supportive Therapies:Speech therapy adjuncts, nutritional support, and palliative care interventions address quality-of-life endpoints.
By volume, symptomatic treatment leads. By growth pace, disease-modifying treatment is expanding most quickly.
Therapy Area:
Cost tier stratification separates premium-priced biologics in rare diseases from standard-of-care neurology interventions, with geriatrics commanding intermediate reimbursement due to Medicare and national health system coverage patterns.
- Neurology:Baseline specialty managing PSP through general neurodegenerative protocols without disease-specific infrastructure.
- Geriatrics:Integrated care models addressing multimorbidity and functional decline in elderly patients with rapid disease progression.
- Movement Disorders:Deep subspecialty expertise in atypical parkinsonian syndromes, with dedicated units in California, Massachusetts, Pennsylvania, and Bavaria generating concentrated trial enrollment and diagnostic accuracy.
- Rare Diseases:Orphan drug economics and regulatory incentives shape investment, with FDA and EMA designations compressing development timelines and extending exclusivity periods.
By patient volume, neurology leads. By value per patient, rare diseases commands premium positioning.
End User:
Application logic drives site selection: complex diagnostic workups and experimental therapies anchor at hospitals and research institutions, while stabilized patients transition to outpatient and home settings.
- Hospitals:Multidisciplinary coordination of speech pathology, physical therapy, and palliative care through single-entry portals. Academic medical centers in the United States and Germany maintain dedicated PSP clinics with embedded research infrastructure.
- Outpatient Clinics:Community neurology practices deferring atypical parkinsonian diagnoses to tertiary hubs, serving as referral filters rather than definitive care sites.
- Research Institutions:Phase II and Phase III trial execution requiring biomarker confirmation and longitudinal follow-up.
- Home Healthcare:Oral symptomatic therapies and caregiver training programs enabling care migration from institutional settings.
By current revenue, hospitals dominate. By channel expansion rate, home healthcare is gaining share fastest.
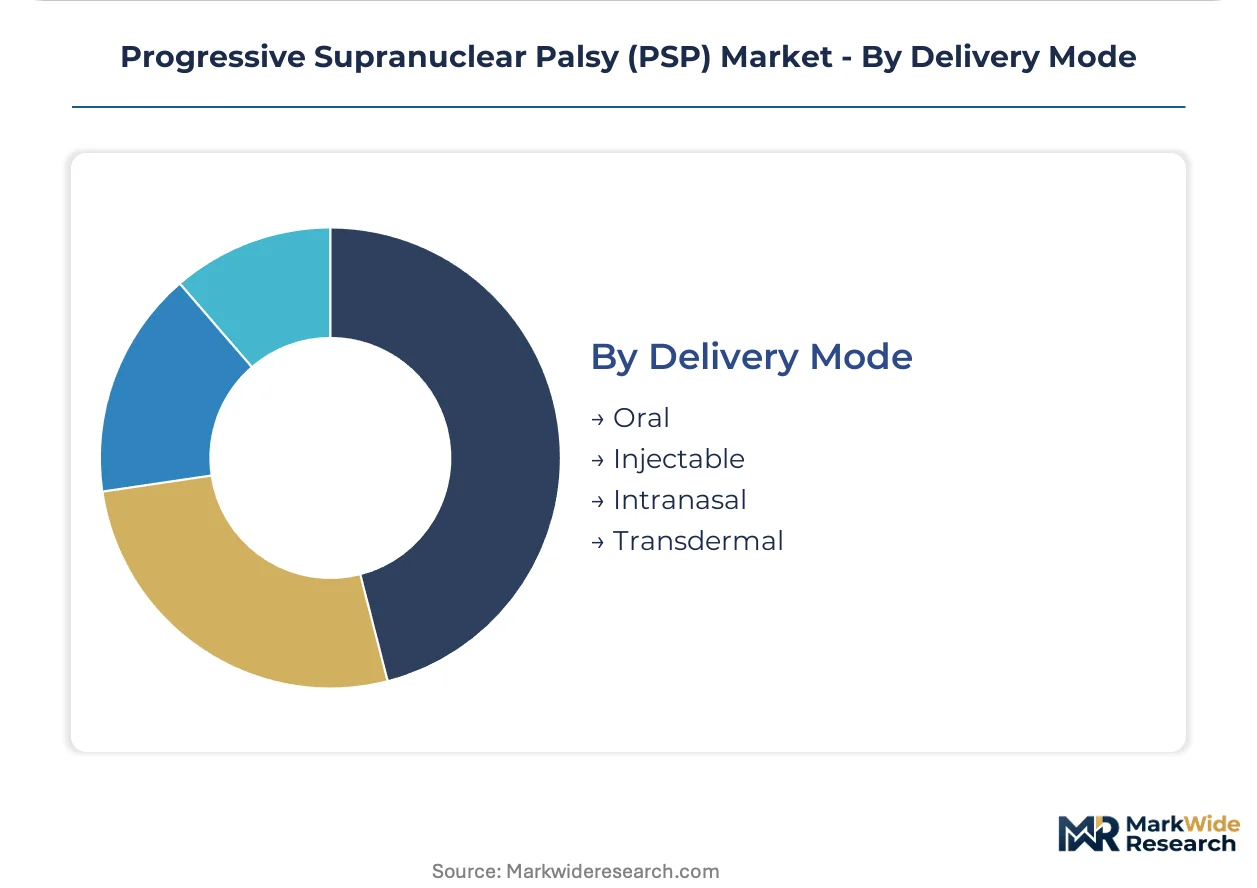
Delivery Mode:
Customer type segmentation separates institutional buyers (hospitals, research sites) seeking injectable and intranasal formulations for controlled administration from retail-oriented oral and transdermal products.
- Oral:Symptomatic agents for mobility and neuropsychiatric symptoms, distributed through retail pharmacy and mail-order channels with established Medicare Part D coverage.
- Injectable:Intravenous immunotherapies and subcutaneous disease-modifying candidates requiring infusion center infrastructure and specialized nursing.
- Intranasal:Emerging delivery for agents targeting rapid CNS penetration, with formulation stability and dosing consistency under FDA evaluation.
- Transdermal:Patch-based symptomatic therapies for continuous delivery, addressing adherence challenges in cognitively impaired populations.
By utilization, oral formulations lead. By development priority, injectable modalities show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic protocols and trial infrastructure vary sharply across major markets, with the United States concentrating experimental therapy access while Germany and Japan prioritize standardized biomarker networks. These consumption-pattern differences shape where developers allocate clinical investment and regulatory filing priorities.
United States
Academic medical centers in California, Massachusetts, and Pennsylvania operate dedicated PSP clinics with embedded tau PET imaging and longitudinal research infrastructure. The FDA Orphan Drug Designation program grants protocol assistance and market exclusivity incentives that compress development timelines for disease-modifying candidates. Movement disorder neurologist scarcity creates diagnostic bottlenecks in community settings, funneling patients toward tertiary referral hubs.
Germany
Bavarian university hospitals coordinate multicenter biomarker standardization initiatives that feed directly into EMA PRIME scheme applications. The country's statutory health insurance system reimburses specialized atypical parkinsonian diagnostics when delivered through certified movement disorder units. North Rhine-Westphalia hosts concentrated speech pathology and palliative care integration programs that reduce hospitalization duration.
Japan
Centralized geriatric neurology pathways in the Kanto and Kansai regions enable rapid identification of rapidly progressing tauopathy populations for trial enrichment. The PMDA's Sakigake designation system accelerates review timelines for agents addressing unmet needs in fatal neurodegenerative conditions. Tokyo-area medical centers maintain dedicated four-repeat tauopathy registries that support natural history studies.
United Kingdom
NHS England's specialized commissioning framework routes complex atypical parkinsonian cases toward London and Cambridge movement disorder networks with biomarker confirmation capacity. The MHRA's Innovative Licensing and Access Pathway offers regulatory flexibility for therapies targeting small, severe disease populations. Scottish academic centers contribute disproportionately to European fluid biomarker harmonization efforts.
Switzerland
Roche's Basel headquarters anchors tau-targeting R&D investment that feeds clinical trial networks across the Rhine corridor. Swissmedic maintains accelerated assessment procedures for orphan neurological indications that align with EMA PRIME eligibility criteria. Zurich and Geneva university hospitals host specialized neurodegenerative disease units with integrated PET-MRI capabilities.
Progressive Supranuclear Palsy (PSP) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with large-cap pharmaceutical companies leveraging rare disease infrastructure against emerging biotechnology firms focused on tau biology platforms. The upper tier commands trial execution capabilities and regulatory relationships that compress development timelines. Three archetypes dominate: diversified neurodegeneration players extending parkinsonian franchises, pure-play tau-targeting biotechnology companies, and diagnostic developers commercializing PET ligands and fluid biomarker assays. Competitive tension centers on biomarker-gated trial design and movement disorder unit partnerships.
Within the integrated pharmaceutical tier, Roche and Biogen Inc. exemplify contrasting approaches to neurodegenerative rare disease positioning. Roche anchors tau-targeting investment through its Basel-centered R&D infrastructure and deep clinical trial relationships with European academic centers. Biogen Inc. occupies a position emphasizing specialized rare disease operational capabilities that support complex enrollment in fatal, rapidly progressing conditions. AbbVie Inc. sits within the parkinsonian franchise extension archetype, leveraging existing prescriber relationships in overlapping movement disorder indications.
| Leading Market Players |
|---|
| Novartis AG |
| Roche |
| AbbVie Inc. |
| Biogen Inc. |
| Teva Pharmaceutical Industries |
| Bristol-Myers Squibb Company |
| Acorda Therapeutics Inc. |
| UCB Biopharma |
| Asceneuron Therapeutics |
| Others |
Value Network & Pricing Analysis
Batch-scale economies in tau PET ligand manufacturing concentrate production among three specialized radiochemistry facilities in Germany, Switzerland, and the United States, creating price floors that reflect isotope sourcing costs and cyclotron utilization rates rather than competitive pressure alone. This supply concentration amplifies pricing power for diagnostic developers while forcing therapy sponsors to absorb premium imaging costs within trial budgets.
Pricing Analysis
Long-term offtake agreements between academic medical centers and radiopharmaceutical suppliers dominate tau PET ligand procurement, with spot purchasing limited to research institutions lacking cyclotron infrastructure. Price differentiation rests on isotope half-life reliability and GMP certification tier, with FDA-validated batches commanding substantial premiums over research-grade material. Cost compression in symptomatic therapies intensifies as oral parkinsonian agents face generic substitution pressure. Hospital systems exhibit highest price sensitivity for diagnostic imaging, while biotech sponsors developing disease-modifying candidates demonstrate lowest sensitivity due to trial enrollment imperatives.
Supply Chain Analysis
Inbound logistics costs for short-lived isotopes hinge on regional cyclotron proximity, with radiopharmaceutical distribution tethered to 4-6 hour delivery radii from production sites in Massachusetts, Bavaria, and Basel. Raw material dependencies center on enriched isotope feedstock, specialized precursor chemicals, and GMP-compliant vialing components. Single-source vulnerability concentrates in isotope reactor capacity, where geopolitical disruption to European or North American nuclear infrastructure would cascade through diagnostic availability. Distribution runs through hospital-based nuclear medicine pharmacies and centralized radiopharmacy networks serving multicenter trial consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated health systems and specialized movement disorder networks that coordinate diagnostic procurement across multiple sites, fragmenting traditional hospital purchasing autonomy.
For Market Incumbents: Consolidate tau-targeting pipeline assets through targeted licensing arrangements that secure biomarker-gated trial populations. Deepen relationships with California and Massachusetts academic hubs where patient referral networks are tightening. Defend against emerging antisense platforms by accelerating immunotherapy data readouts in biomarker-enriched cohorts. For New Entrants and Emerging Players: Anchor in Japan's centralized geriatric neurology infrastructure, where streamlined patient identification offers fastest proof-of-concept timelines. Target home healthcare channels for oral symptomatic therapies as institutional care migration accelerates. Pursue partnership models with established movement disorder units rather than building independent commercial infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic developers with validated tau PET tracers and longitudinal biomarker service contracts. Long-term viability in this fatal, rapidly progressing indication depends on disease-modifying mechanism validation rather than symptomatic franchise extension. Acquisition priority rests on tau biology platforms with blood-based biomarker capabilities. Monitor FDA breakthrough therapy designation frequency as inflection signal for regulatory risk appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Tau PET Tracer Validation | FDA approval of second-generation ligands enables biomarker-gated trial enrollment at academic medical centers. |
| Orphan Drug Designation Pursuit | EMA PRIME and FDA protocol assistance compress development timelines for disease-modifying candidates. |
| Movement Disorder Unit Partnership | California and Massachusetts hub alliances secure concentrated patient access for Phase II enrollment. |
| Home Healthcare Channel Development | Oral symptomatic therapy distribution through Medicare Part D plans reduces hospital dependency. |
| Fluid Biomarker Harmonization | CSF assay standardization across Bavarian and North American sites strengthens regulatory evidence packages. |
Research Methodology
Cross-validation between primary interviews with movement disorder neurologists, regulatory affairs specialists at FDA and EMA, hospital formulary directors, and payer access managers anchors the qualitative findings. Secondary validation draws from FDA Orphan Drug Designation filings, EMA PRIME eligibility assessments, ClinicalTrials.gov protocol records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down pharmaceutical R&D expenditure analysis triangulate market sizing across the projection horizon.
Sensitivity analysis on tau PET adoption curves and disease-modifying therapy launch timing shapes the analytical framework. Segmentation dimensions include treatment intent, therapy area subspecialty, end-user site type, and delivery mode complexity. CAGRs derive from epidemiological prevalence projections, trial enrollment velocity assumptions, and pricing evolution for diagnostic and therapeutic modalities. Forecast inputs incorporate biomarker validation timelines and regulatory pathway acceleration probabilities.
Material uncertainties — tau PET tracer regulatory approval delays, movement disorder specialist workforce attrition, and disease-modifying clinical trial failures — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding biomarker adoption and reimbursement pathway evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Malabsorption Syndrome Market