
 Distributed Electric Propulsion System MRO Services Market | 2026-2036
Distributed Electric Propulsion System MRO Services Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Electric Propulsion System MRO Services Market Insights
The shift from single-source OEM captive maintenance to multi-source third-party MRO contracts is hardening across the distributed electric propulsion ecosystem. Safran Electrical & Power leverages its integrated powertrain heritage to anchor aftermarket service networks for hybrid-electric turboprop retrofits. GE Aerospace competes through its Edison Works division, which specializes in advanced electric power system validation and repair protocols for next-generation aircraft.
Distributed Electric Propulsion System MRO Services encompass inspection, repair, overhaul, and calibration of multiple electric motors, motor controllers, battery packs, and power distribution units arranged across an aircraft's lifting surfaces to provide redundant thrust and enhanced maneuverability, typically operating at voltages between 500V and 1,000V DC depending on aircraft class. These architectures demand thermally managed battery cycling protocols and non-destructive testing of composite-encased wiring harnesses to maintain airworthiness under repeated load conditions. The propulsion component dimension shows batteries and power electronics capturing concentrated margin pools due to cell degradation monitoring and inverter firmware update requirements, while inspection services lead volume as fleet operators establish baseline health metrics for novel electric propulsion configurations. Deployment mode segmentation reveals mobile service units gaining traction among urban air mobility operators seeking to minimize aircraft downtime between revenue flights.
The FAA's Part 135 adaptation for electric aircraft and EASA's SC-VTOL special condition framework are reshaping MRO credentialing requirements, with both bodies mandating technician certification in high-voltage safe handling and battery thermal runaway containment. The EU AI Act and emerging machine-learning diagnostics standards will further condition predictive maintenance algorithm validation for autonomous fault detection in distributed propulsion networks. Stakeholders must monitor regulatory divergence between FAA airworthiness directives and EASA continuing airworthiness management organization requirements when structuring transatlantic MRO service portfolios.
Market Dynamics
The transition from captive OEM maintenance to multi-source third-party MRO contracts is compressing service margins while expanding addressable volumes across distributed electric propulsion architectures. High-voltage certification requirements and battery thermal management protocols are forcing fleet operators to consolidate vendor relationships around qualified service networks.
Growth Catalysts
- FAA Part 135 Adaptation:The FAA's electric aircraft operational rules are mandating standardized MRO credentialing for high-voltage systems, creating compliant service demand across US urban air mobility corridors.
- Battery Degradation Monitoring:Cell-level health tracking requirements are generating recurring revenue streams for predictive maintenance services tied to power electronics overhaul cycles.
- Munich-Hamburg Testbed Concentration:Germany's eVTOL validation regions are anchoring early fleet maintenance contracts as commercial entry dates firm.
Market Restraints
- Lithium Price Volatility:Battery pack replacement costs fluctuate with cathode material input markets, compressing MRO margin predictability on fixed-price contracts.
- Specialized Technician Scarcity:The limited pool of FAA-certified high-voltage handlers and EASA SC-VTOL qualified engineers concentrates labor supply in California and Bavaria.
- Proprietary Diagnostic Lock-in:OEM-controlled inverter firmware and battery management system access codes restrict third-party repair scope.
Strategic Opportunities
- Mobile Service Units:Deployable maintenance vehicles are capturing urban air mobility operator demand for rapid turnaround between revenue flights.
- EU AI Act Diagnostics:Machine-learning predictive maintenance algorithms are opening validated service revenue streams under emerging European artificial intelligence conformity frameworks.
- Hybrid-Electric Retrofit Channels:Regional turboprop electrification programs are creating aftermarket entry points for powertrain overhaul specialists.
Industry Challenges
- High-Voltage Safety Certification Backlogs:Training pipeline capacity lags behind fleet induction rates, delaying technician deployment to active service locations.
- Transatlantic Regulatory Divergence:FAA airworthiness directive structures and EASA continuing airworthiness management organization requirements impose dual compliance costs on cross-border MRO operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Electric Propulsion System MRO Services Market |
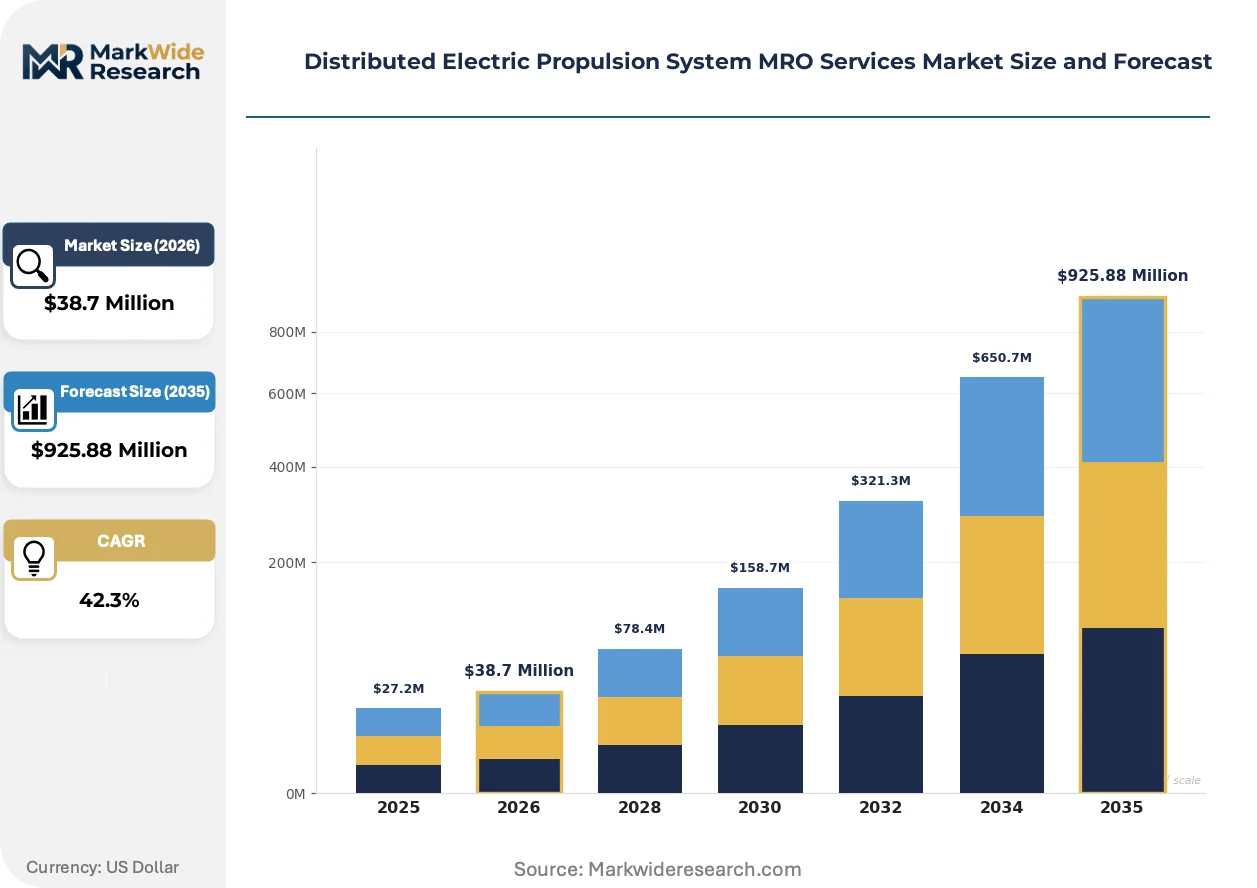
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $925.88 Million |
| CAGR (2026 – 2036) | 42.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Repair, Overhaul, Testing, Calibration Propulsion Component: Motors, Controllers, Batteries, Power Electronics, Wiring Harness End User: Aircraft OEMs, Maintenance Repair Organizations, Fleet Operators, Aerospace Tier-1 Suppliers Deployment Mode: On-Site, Off-Site, Mobile Service Units, Remote Diagnostics |
| Companies Covered | Safran Electrical & Power, GE Aerospace, RTX, Collins Aerospace, Honeywell International, Rolls-Royce, Thales Group, magniX, ZeroAvia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Electric Propulsion System MRO Services Market Trends and Innovations
Distributed propulsion architectures are forcing fundamental redesign of maintenance workflows as redundant motor configurations multiply inspection touchpoints per flight hour. Service providers are re-engineering diagnostic protocols to handle parallel power paths and fault-tolerant control systems.
Modular power electronics packaging is modularizing field-replaceable inverter units for rapid swap-out during turnaround windows. Urban air mobility operators in California's Advanced Air Mobility corridors are adopting cartridge-based motor controller replacement to minimize aircraft downtime. This architecture is modularizing inventory strategies across MRO networks, compressing spare parts lead times from weeks to hours.
EASA's SC-VTOL special condition framework is tightening continuing airworthiness requirements for battery thermal runaway containment systems. Manufacturers must now demonstrate repeatable fault detection across distributed cell monitoring networks. The power electronics segment is responding with hardened firmware validation protocols and redundant sensor architectures.
Fleet operators are unbundling predictive maintenance contracts from traditional time-and-material service agreements. Urban air mobility providers in Germany's testbed regions are contracting health monitoring separately from physical overhaul work. California-based operators are driving this shift most aggressively, demanding algorithm-driven fault alerts that trigger just-in-time parts positioning.
Distributed Electric Propulsion System MRO Services Market Segmentation
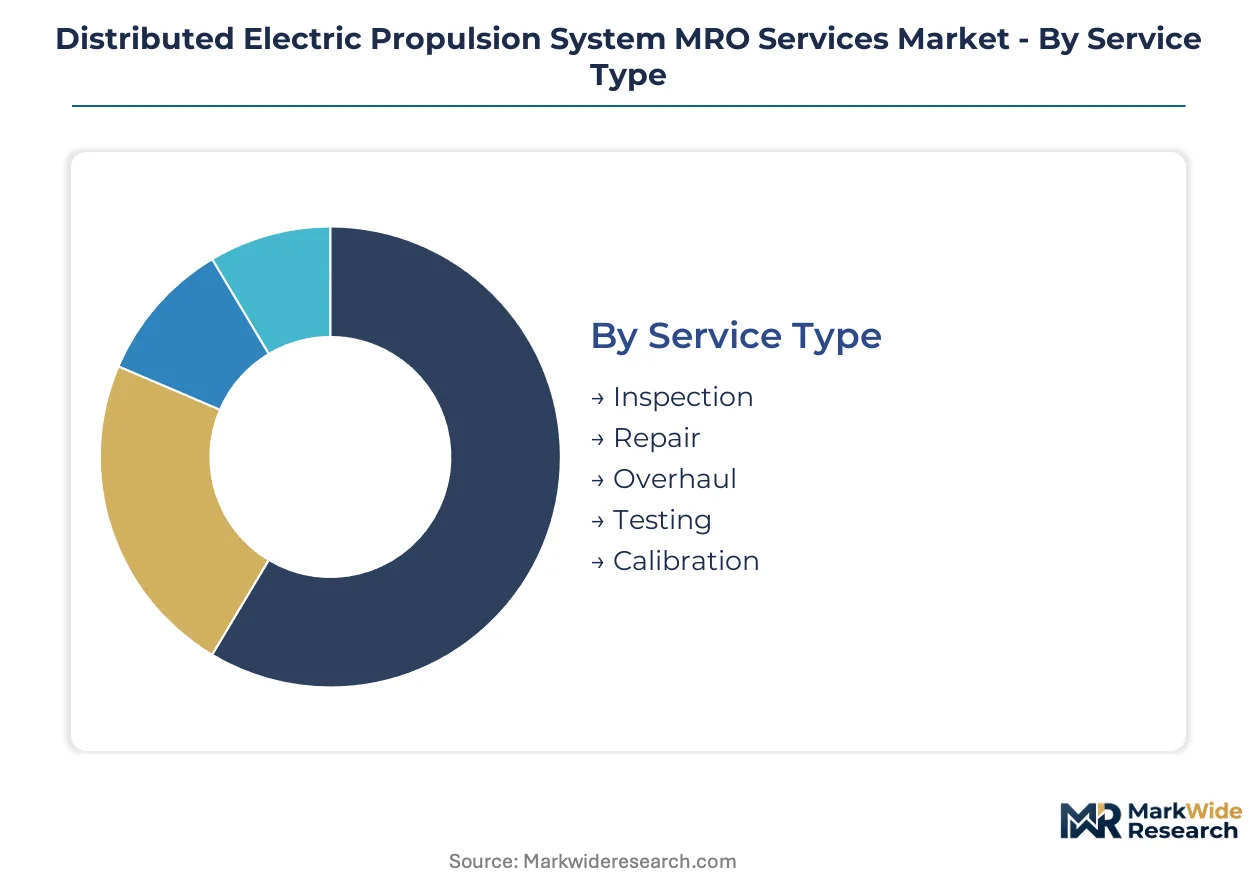
Distributed electric propulsion architectures fragment MRO demand across voltage classes and redundancy configurations. Service providers must align capabilities with specific component certifications and deployment constraints to capture contract value.
Service Type:
FAA Part 135 and EASA SC-VTOL frameworks impose distinct approval burdens on each service category, with high-voltage handling credentials required for overhaul and testing functions.
- Inspection:Baseline health assessments of motor windings, battery cell arrays, and power distribution integrity using thermal imaging and insulation resistance testing. Demand concentrates among California urban air mobility operators establishing fleet entry-into-service protocols under FAA Special Federal Aviation Regulation 107.
- Repair:Field restoration of damaged motor controllers, inverter modules, and thermal management systems. Fleet operators in Germany's Munich-Hamburg eVTOL corridors are consolidating repair contracts with EASA-approved Part-145 organizations to minimize airworthiness downtime.
- Overhaul:Complete powertrain refurbishment to zero-time condition.
- Testing:Validation of fault-tolerant control logic and redundant thrust path functionality.
- Calibration:Precision alignment of motor synchronization and battery management system thresholds.
Leading the category by volume: Inspection. Growing fastest: Repair.
Propulsion Component:
Margin concentration tracks thermal cycling intensity and firmware dependency, with power electronics and batteries commanding premium pricing due to proprietary diagnostic access.
- Batteries:Cell-level degradation monitoring and thermal runaway containment system maintenance for lithium-ion packs operating at 500V to 1,000V DC. Munich-based operators are driving demand for predictive cell replacement scheduling under EASA continuing airworthiness management organization requirements.
- Power Electronics:Inverter module overhaul, gate driver replacement, and firmware validation for silicon carbide and gallium nitride switching architectures. California Advanced Air Mobility corridors show concentrated demand for rapid swap-out programs minimizing aircraft-on-ground time.
- Motors:Winding insulation testing and bearing replacement for distributed axial-flux and radial-flux configurations.
- Controllers:Motor control unit diagnostics and PID tuning for redundant thrust vectoring systems.
- Wiring Harness:Composite-encased high-voltage cable inspection and connector integrity verification.
Dominating margin capture: Batteries and Power Electronics. Steepest expansion trajectory: Power Electronics.
End User:
Procurement authority is shifting from captive OEM networks to independent operators as fleet scales mature and third-party certification pathways stabilize.
- Fleet Operators:Urban air mobility providers and regional airlines managing distributed propulsion maintenance across multi-aircraft fleets. California-based eVTOL operators are unbundling predictive maintenance from physical overhaul work, creating separate contract vehicles for algorithm-driven health monitoring.
- Maintenance Repair Organizations:Independent Part-145 certified facilities competing for outsourced high-voltage system work. German MROs around Hamburg are capturing early eVTOL fleet contracts through EASA SC-VTOL specialized approvals.
- Aircraft OEMs:Captive service networks supporting warranty periods and initial type certification maintenance.
- Aerospace Tier-1 Suppliers:Powertrain integrators providing subsystem-level MRO support to airframe manufacturers.
Contract volume leader: Fleet Operators. Fastest contract expansion: Maintenance Repair Organizations.
Deployment Mode:
Urban air mobility operational tempo is compressing turnaround windows, favoring distributed service models over centralized depot maintenance.
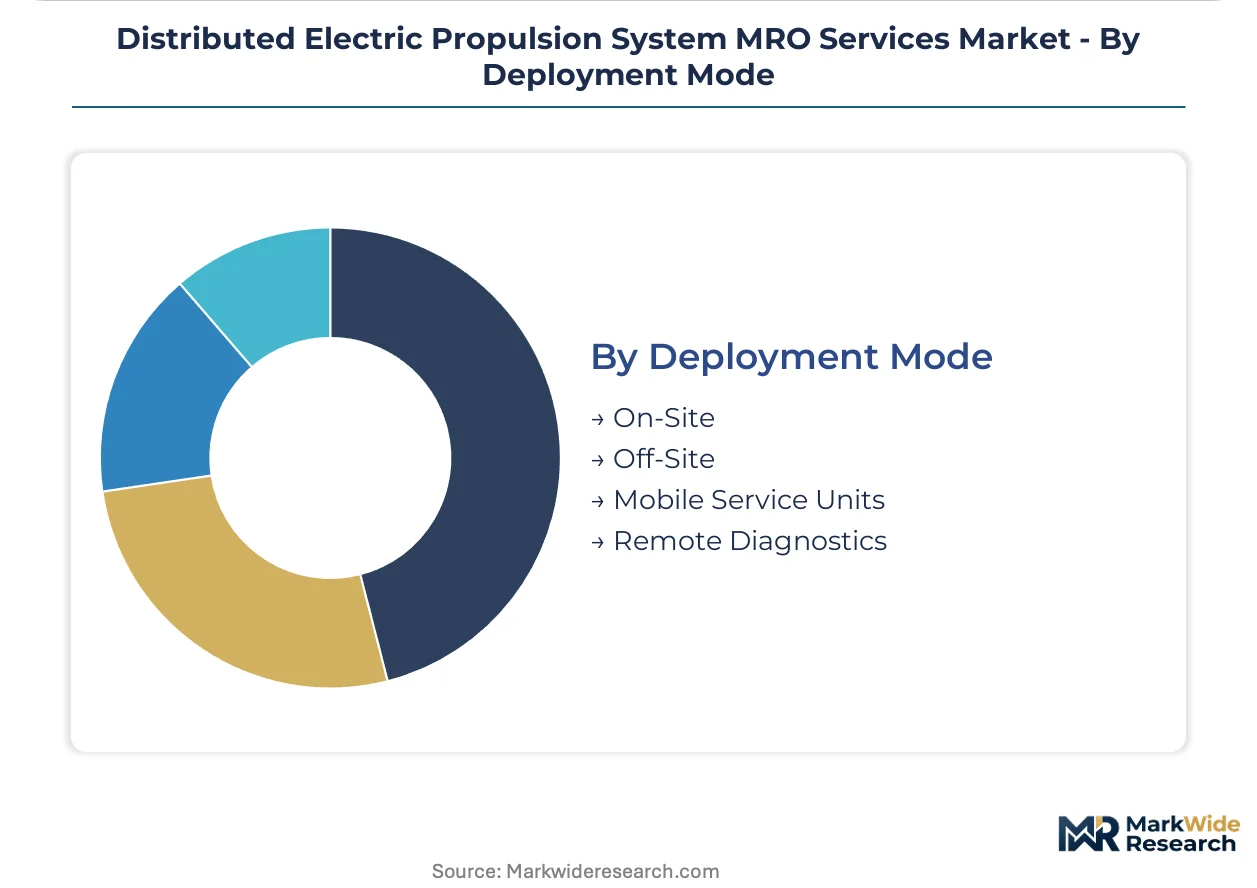
- Mobile Service Units:Deployable maintenance vehicles equipped with high-voltage safe handling equipment and rapid diagnostic tools. California operators are adopting cartridge-based motor controller replacement programs enabling sub-hour turnaround between revenue flights.
- Remote Diagnostics:Telemetry-based fault detection and predictive algorithm deployment for distributed propulsion health monitoring. Germany's testbed regions are piloting EU AI Act-compliant machine learning validation for autonomous fault isolation.
- On-Site:Fixed-base maintenance at vertiports and regional airports with permanent high-voltage infrastructure.
- Off-Site:Depot-level overhaul at centralized facilities with specialized battery cycling and power electronics test benches.
Highest utilization: Mobile Service Units. Gaining share fastest: Remote Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium supply chain nodes in Chile's Atacama and Australia's Pilbara anchor raw material flows into battery pack assembly clusters. These feedstock localities concentrate MRO demand around aircraft electrification programs in advanced economies with established aerospace certification infrastructure.
United States
Urban air mobility operators in California's Advanced Air Mobility corridors are expanding fleet maintenance contracts as eVTOL aircraft approach commercial entry. FAA Special Federal Aviation Regulation 107 mandates standardized high-voltage technician credentialing for distributed propulsion systems. The Los Angeles-San Francisco corridor concentrates mobile service unit deployment for rapid turnaround operations.
Germany
EASA SC-VTOL certification pathways are accelerating airworthiness requirements for distributed electric architectures across Munich and Hamburg testbed regions. The EU AI Act is conditioning predictive maintenance algorithm validation for autonomous fault detection in propulsion networks. Bavaria-based Part-145 organizations are capturing early eVTOL fleet contracts through specialized approvals.
China
MIIT dual carbon goals are driving regional turboprop electrification programs that create aftermarket entry points for powertrain overhaul specialists. GB standards for high-voltage aircraft systems are converging with international certification frameworks. The Yangtze River Delta aerospace cluster is developing indigenous MRO capabilities for distributed propulsion architectures.
United Kingdom
Hybrid-electric retrofit channels for regional aircraft are generating demand for power electronics overhaul services under CAA oversight. The country's national aviation regulator is adapting continuing airworthiness management organization requirements for battery thermal runaway containment. Southwest England's aerospace supply base is positioning for distributed propulsion component repair specialization.
Japan
METI funding for advanced air mobility infrastructure is stimulating MRO network development for electric vertical take-off and landing fleets. JIS standards for high-voltage aircraft wiring are informing technician training curricula at technical institutes. The Nagoya aerospace cluster is integrating distributed propulsion maintenance into existing turbofan overhaul facilities.
Distributed Electric Propulsion System MRO Services Market Competitive Landscape
Global majors compete with regional champions across certification scope and voltage class specialization. The vendor base stratifies between integrated powertrain heritage players and emerging electric-only specialists. Three archetypes dominate: legacy aerospace electrical system incumbents, pure-play electric propulsion startups, and diversified industrial conglomerates with aerospace divisions. Competitive moves center on EASA Part-145 approval acquisition and high-voltage technician training pipeline development.
Within the integrated powertrain tier, Safran Electrical & Power and GE Aerospace exemplify archetype leaders leveraging legacy electrical system expertise for aftermarket network anchoring. magniX occupies a position as a pure-play electric propulsion specialist. These three represent the structural fault line between captive OEM maintenance models and emerging third-party service competition.
| Leading Market Players |
|---|
| Safran Electrical & Power |
| GE Aerospace |
| RTX |
| Collins Aerospace |
| Honeywell International |
| Rolls-Royce |
| Thales Group |
| magniX |
| ZeroAvia |
| Others |
Pricing and Supply Chain Analysis
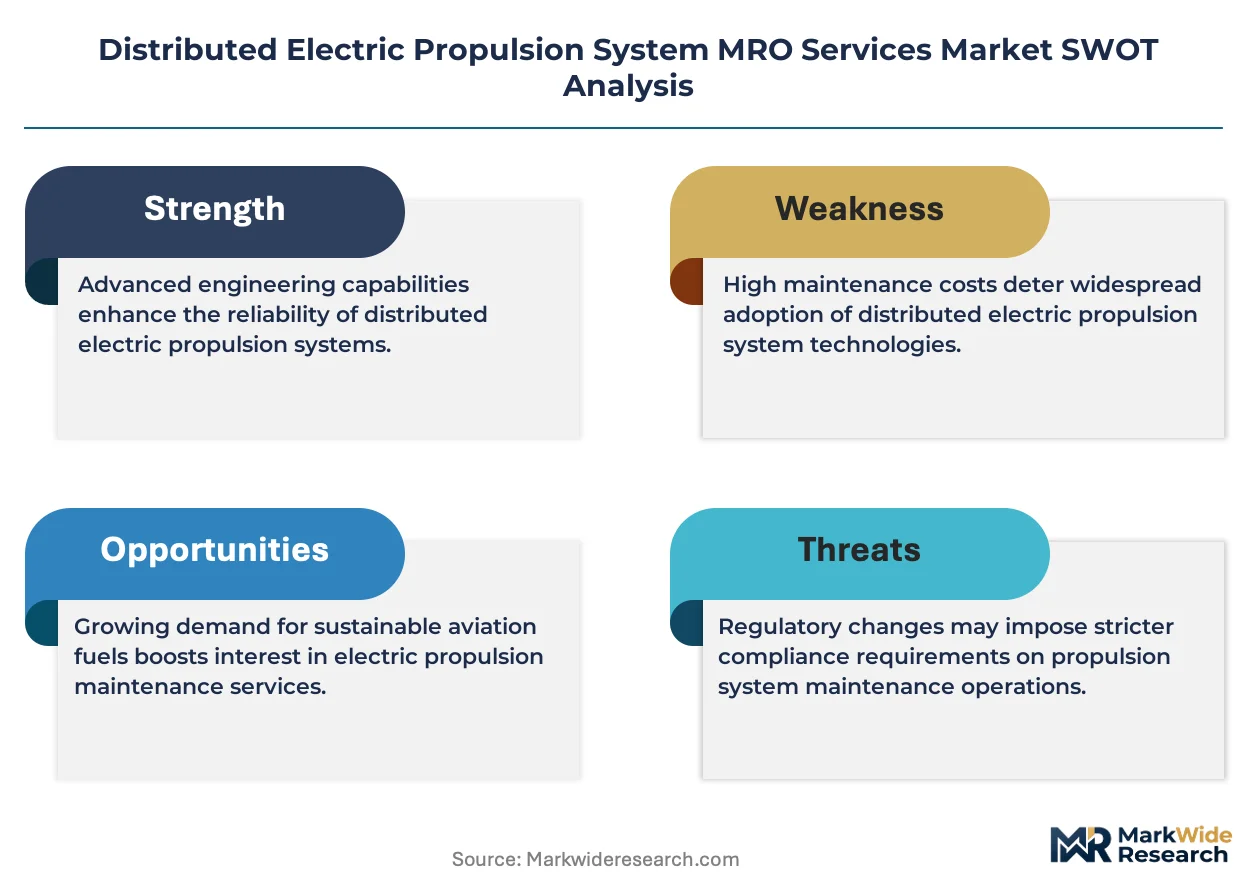
Private-equity-rolled-up MRO specialists are consolidating regional service networks across California and Bavaria, compressing field labor rates while elevating proprietary diagnostic tool premiums. This ownership pattern tightens pricing discipline on battery pack replacement cycles and loosens margin capture on commoditized inspection labor.
Pricing Analysis
Warranty bundling with predictive maintenance subscriptions separates premium-tier fleet contracts from unbundled time-and-material arrangements for smaller operators. Three-tier pricing structure across premium, standard, and economy levels tracks EASA Part-145 certification grade and fleet scale. Cost compression in standard-tier overhaul services is intensifying because lithium cathode material spot markets feed through to battery replacement quotes. Urban air mobility startups in California's Advanced Air Mobility corridors show highest price sensitivity, while legacy regional airlines with hybrid-electric retrofit commitments accept premium pricing for guaranteed uptime.
Supply Chain Analysis
Workforce availability constraints in Germany's Bavaria and Hamburg aerospace clusters are elevating technician training costs and extending spare parts positioning timelines. Cell manufacturing concentrates in China, South Korea, and Japan, while power electronics fabrication centers on Taiwan and the United States. Silicon carbide wafer supply draws from Japanese and German substrate producers, exposing MRO networks to single-source vulnerability in gate driver components. Distribution runs through captive OEM logistics hubs and independent Part-145 regional depots with localized battery cycling capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed electric propulsion architectures are displacing centralized turbine maintenance workflows, with silicon carbide inverter technology replacing silicon-based legacy power electronics across new fleet inductions.
For Market Incumbents: To counter pure-play electric propulsion specialists capturing EASA SC-VTOL certification contracts, Safran Electrical & Power and GE Aerospace should anchor aftermarket networks through backward integration into battery management system firmware access. Acquiring mobile service unit operators in California's Advanced Air Mobility corridors would secure high-voltage technician pipelines and compress response times for urban air mobility operators. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels enable rapid contract acquisition without legacy OEM channel conflicts. Mobile service unit deployment for sub-hour motor controller cartridge replacement represents the most penetrable white-space target among California eVTOL operators. A go-to-market angle emphasizing EU AI Act-compliant predictive maintenance algorithm validation would differentiate against incumbent diagnostic tool offerings in Germany's testbed regions. For Investors and Strategic Acquirers: Distressed-cycle entries favor EASA Part-145 specialists with high-voltage certification infrastructure in Munich-Hamburg corridors as lithium price volatility compresses smaller competitor margins. Long-term viability across the analysis window hinges on technician training pipeline control and proprietary battery degradation database accumulation. The signal to watch as inflection indicator is FAA Part 135 adaptation pace for electric aircraft operational rules, which would trigger fleet-scale MRO contract reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Training Pipeline Expansion | FAA-certified handler scarcity in California and Bavaria elevates labor capture value for qualified networks. |
| Proprietary Battery Degradation Database Development | Cell-level health tracking algorithms differentiate predictive maintenance subscriptions from commoditized inspection services. |
| Mobile Service Unit Fleet Deployment | Cartridge-based motor controller replacement programs address California urban air mobility sub-hour turnaround requirements. |
| EASA SC-VTOL Part-145 Certification Acquisition | Specialized approvals unlock early eVTOL fleet contracts in Germany's Munich-Hamburg testbed regions. |
| EU AI Act Diagnostics Validation Investment | Machine learning conformity frameworks open autonomous fault detection revenue streams in European markets. |
Research Methodology
Regulatory filings from FAA and EASA, trade data from customs authorities, and SEC disclosures from aerospace electrical system suppliers formed the secondary backbone of this analysis. Primary interviews with fleet maintenance directors at urban air mobility operators, EASA Part-145 organization technical leads, high-voltage safety training curriculum designers, and battery pack procurement managers at regional airlines were combined with secondary validation. Bottom-up triangulation across service type, propulsion component, and deployment mode segments was cross-checked against top-down market sizing from OEM warranty period estimates and third-party MRO contract announcements.
Historical trendline analysis of electric aircraft certification timelines and hybrid-electric retrofit program pacing informed the projection framework across the modeling period. Segmentation dimensions modeled include service type, propulsion component, end user archetype, and deployment mode, with voltage class and redundancy configuration as aerospace-specific structural variables. CAGRs were derived from fleet induction schedules, battery replacement cycle assumptions, and technician training pipeline capacity constraints. Forecast inputs incorporated EASA SC-VTOL special condition evolution and FAA Part 135 adaptation trajectories for electric aircraft operational rules.
The model holds under steady regulatory convergence between FAA and EASA high-voltage handling requirements; deviation in lithium supply chain disruption severity or sovereign subsidy withdrawal for advanced air mobility infrastructure would shift fleet induction timing and MRO contract velocity. Forecasts reflect documented assumptions on battery degradation curve steepness and proprietary diagnostic access liberalization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market