
 Wide-Body Aircraft MRO Market | 2026-2036
Wide-Body Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Wide-Body Aircraft MRO Market Analytics
Market Context
FAA airworthiness directives on aging wide-body airframes is realigning capital deployment across the MRO sector. Lufthansa Technik AG anchors European base maintenance capacity through its Hamburg and Malta facilities. ST Engineering Aerospace Ltd. dominates Asia-Pacific hangar slots with integrated airframe and component repair lines. Boeing Global Services leverages OEM technical documentation to control aftermarket pricing for 787 and 777 fleets.
Technical Definition and Segments
Wide-body aircraft MRO encompasses scheduled and unscheduled maintenance, repair, and overhaul activities for twin-aisle commercial jets typically seating 200 to 850 passengers, with airframe structures built from aluminum-lithium alloys and carbon fiber reinforced polymer composites requiring specialized non-destructive testing protocols. The primary industrial purpose is to sustain airworthiness certification, extend economic service life, and optimize dispatch reliability for high-utilization long-haul operations. Engine overhaul commands the largest value pool within the service type dimension, while third-party delivery models are capturing share from in-house airline shops as carriers outsource non-core maintenance functions. Component repair exhibits the fastest trajectory among structural segments, driven by rotable inventory scarcity and part manufacturer approval complexity.
Regulatory Frame
EASA Part-145 certification requirements, FAA Advisory Circular 120-77A on aging aircraft systems, and ICAO Annex 6 standards collectively govern market access and technical competency thresholds for wide-body MRO providers. These frameworks mandate recurrent audit cycles, specialized technician qualifications, and traceable parts documentation that elevate fixed costs for new entrants. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and corresponding carbon accounting rules that will reshape shop-floor energy profiles and waste-stream compliance obligations.
Market Dynamics
Fleet age accumulation across Boeing 777 and Airbus A380 platforms is compressing inspection cycles and redirecting capital toward structural modification programs. Airframers face mounting pressure from FAA corrosion mandates while simultaneously absorbing composite repair certification bottlenecks.
Growth Catalysts
- Composite airframe penetration:Carbon fiber reinforced polymer structures now constitute over 50% of new wide-body builds, generating specialized repair demand that traditional metal shops cannot fulfill. EASA Part-145 certification for composite NDT capabilities is creating technician premium tiers.
- Asia-Pacific fleet renewal:Singapore Airlines, Cathay Pacific, and ANA Holdings are accelerating 787 and A350 induction schedules, concentrating heavy check demand in Southeast Asian maintenance corridors.
- FAA aging aircraft directives:Airworthiness Directive 2023-18-05 mandating wing rib post inspections for 777-300ER variants is forcing operators into unscheduled depot visits, expanding addressable base maintenance hours.
Market Restraints
- Titanium alloy supply concentration:Russian VSMPO-AVISMA supplied 30-40% of aerospace titanium prior to sanctions; alternative Western smelter capacity faces 18-24 month qualification timelines, compressing engine component repair throughput.
- Specialized labor scarcity:Composite repair technician certification requires 24-month apprenticeship cycles; FAA repair station staffing ratios are tightening across US Gulf Coast facilities.
- Legacy platform retirement acceleration:Airbus A380 and Boeing 747-8 production cessation is shrinking the installed base for four-engine overhaul specialists, stranding sunk tooling investments.
Strategic Opportunities
- India MRO infrastructure buildout:GMR Aero Technic and Air India Engineering Services are expanding wide-body hangar capacity at Delhi and Hyderabad under the government's 2025 MRO policy incentives, capturing traffic currently flowing to Singapore and Dubai.
- Predictive maintenance convergence:Integration of flight data monitoring with digital twin simulations is enabling condition-based engine shop visits, creating software-services revenue pools for integrated providers.
- Sustainable aviation fuel compliance services:EU Green Deal carbon accounting mandates are requiring emissions tracking infrastructure retrofits, opening new line maintenance revenue streams for EU-145 certified stations.
Industry Challenges
- OEM technical data access restrictions:Boeing and Airbus are tightening intellectual property controls over structural repair manuals, forcing independent MROs into costly licensing negotiations or capability exclusions.
- RoHS substance compliance complexity:European F-Gas Regulation and REACH chemical restrictions are disqualifying legacy sealants and surface treatments, requiring shop-floor material substitutions with unproven field histories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide-Body Aircraft MRO Market |
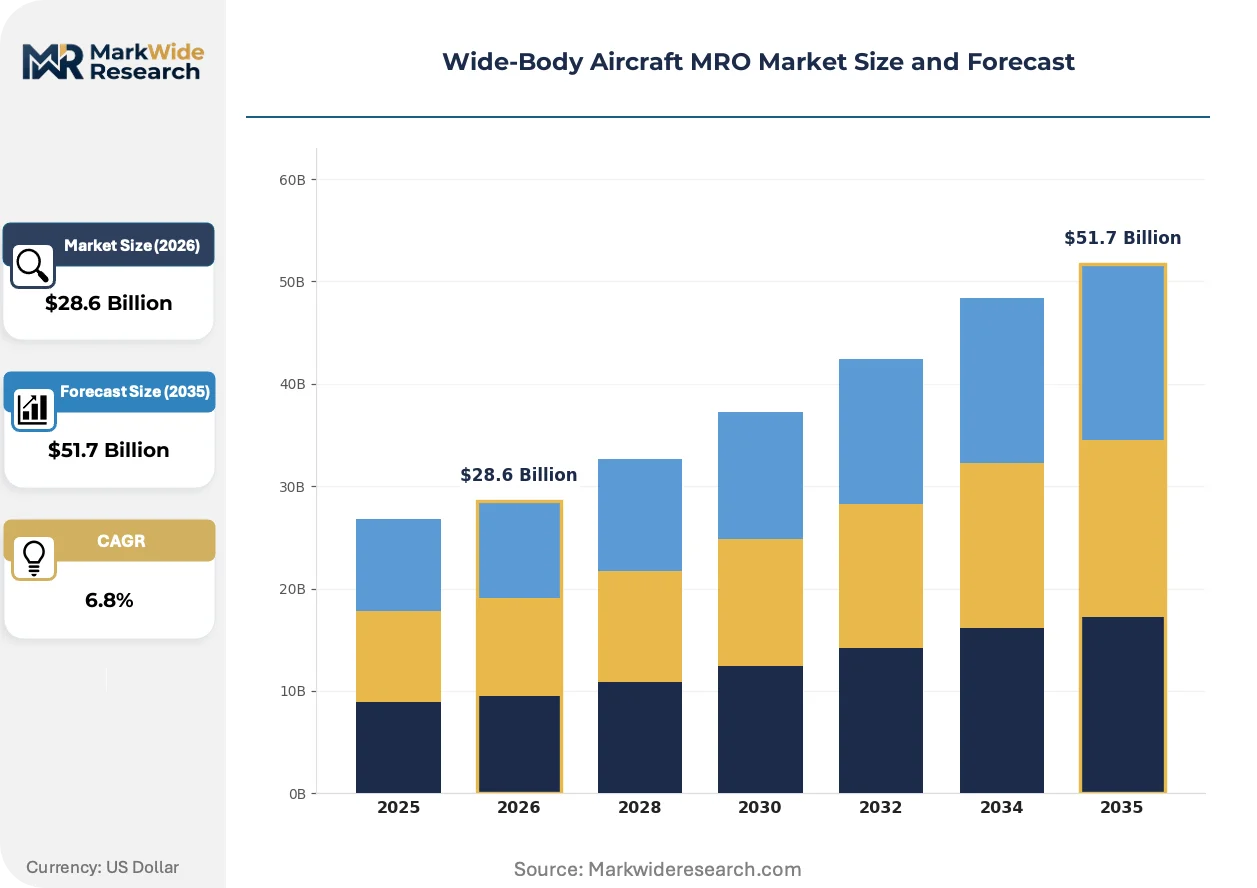
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Aircraft Modifications Delivery Model: In-house, Third-party, Mobile Services, On-site Services Maintenance Level: Line Maintenance, Base Maintenance, Modifications, Heavy Maintenance End User: Commercial Airlines, Cargo Operators, Military Operators, Leasing Companies |
| Companies Covered | ST Engineering Aerospace Ltd., MTU Aero Engines AG, Boeing Global Services, Iberia Maintenance S.A, Delta TechOps, Airbus SE, Lufthansa Technik AG, Korean Air Lines Co. Ltd., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide-Body Aircraft MRO Market Evolving Landscape
Digital thread technologies are collapsing the documentation gap between OEM engineering and shop-floor execution, compressing turnaround estimates while raising data governance standards across the maintenance network.
Automated fiber placement repair systems for composite fuselage sections is modularizing damage response protocols. Lufthansa Technik and ST Engineering are deploying robotic scarfing and re-lamination cells at Hamburg and Singapore facilities, reducing skilled labor hours per repair by 40% while tightening thickness tolerance control. This capability compression is enabling same-day structural releases that previously required week-long depot cycles.
EU Green Deal sustainability disclosure requirements are mandating carbon footprint reporting across MRO supply chains. EASA is developing environmental certification addenda to Part-145 approvals, requiring energy monitoring and waste-stream documentation that elevates compliance overhead for smaller independent shops. German and French facilities are responding with photovoltaic hangar roof installations and solvent recycling investments to maintain OEM preferred supplier status.
Airline procurement functions are unbundling engine overhaul from airframe maintenance contracts, creating standalone competitive bidding events for shop visits. This disintermediation is visible most acutely among Gulf carriers, where Emirates and Qatar Airways are separating GE90 and Trent XWB overhaul awards from line maintenance agreements previously held by single-source integrators.
Wide-Body Aircraft MRO Market Segmentation
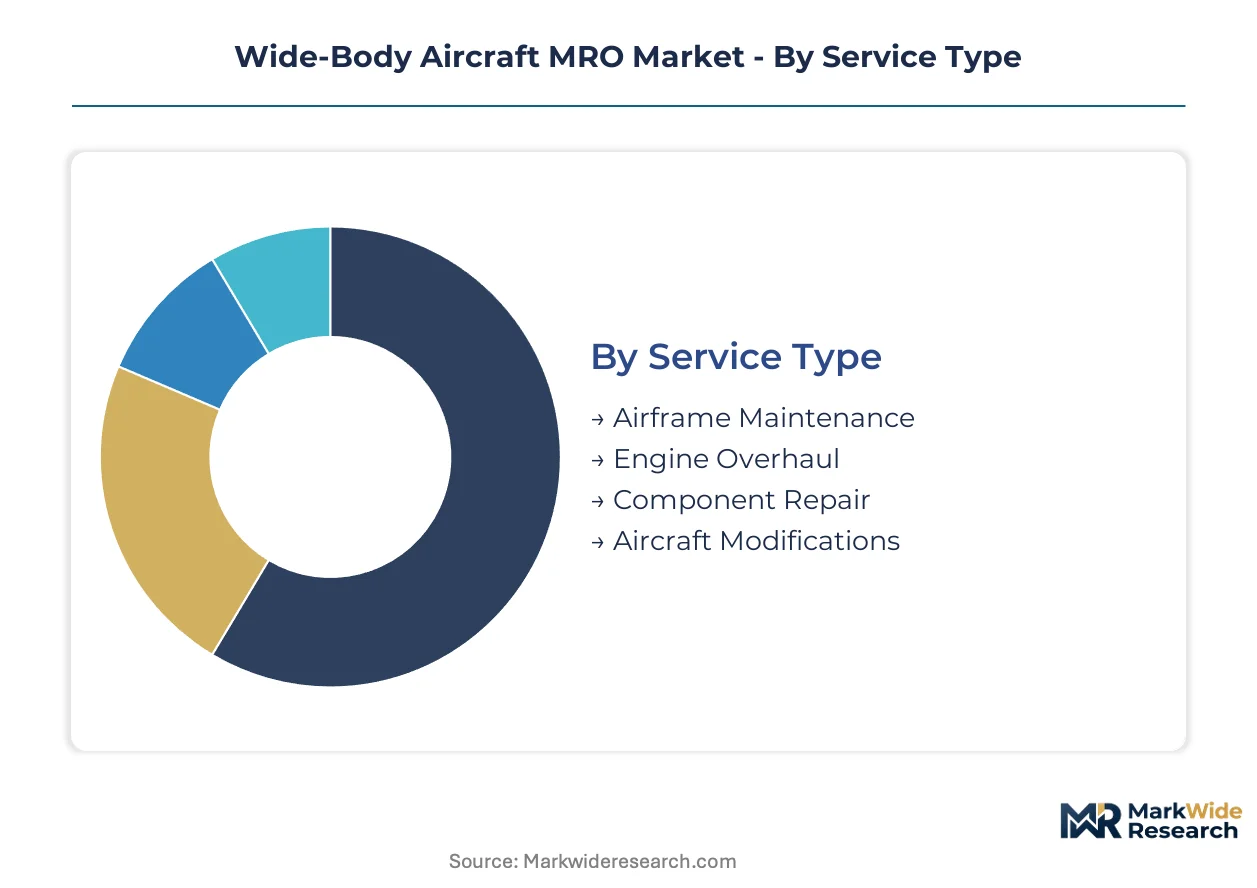
Wide-body MRO segmentation reveals how capital flows cluster around engine assets while emerging service models fragment traditional supply relationships. Each dimension exposes distinct margin structures, regulatory burdens, and capability barriers that determine competitive positioning across maintenance networks.
Service Type:
Supply concentration in engine overhaul workshops creates pricing leverage that airframe providers cannot replicate, concentrating specialist talent in narrow geographic corridors.
- Airframe Maintenance:Scheduled structural inspections and corrosion prevention programs for aluminum-lithium fuselage sections and composite wing boxes. Demand concentrates in Singapore and Hamburg as FAA aging aircraft directives compress inspection intervals for Boeing 777-300ER operators.
- Engine Overhaul:Complete disassembly, non-destructive testing, and reassembly of high-bypass turbofans including GE90 and Trent XWB powerplants. Shop visit demand clusters around Dallas, Singapore, and Cardiff where OEM-authorized facilities control technical documentation access.
- Component Repair:Rotable inventory restoration for avionics, hydraulics, and landing gear systems. EASA Part-145 certification requirements for composite NDT capabilities are creating technician premium tiers at specialized European shops.
- Aircraft Modifications:Structural reinforcements, cabin reconfigurations, and connectivity retrofits. STC approval bottlenecks and OEM intellectual property restrictions limit independent provider participation in 787 and A350 programs.
Today's leader: Engine Overhaul. Tomorrow's challenger: Component Repair.
Delivery Model:
Cost tier differentiation separates integrated carriers with captive maintenance functions from asset-light operators outsourcing non-core activities.
- In-house:Airline-operated maintenance divisions with dedicated hangar infrastructure and OEM licensing agreements. Lufthansa Technik and Air France Industries maintain full technical control over fleet airworthiness, capturing margin that third-party providers forfeit.
- Third-party:Independent MRO specialists bidding for contract maintenance across multiple airline customers. ST Engineering Aerospace and AAR Corp compete on turnaround guarantees and rotable inventory pooling.
- Mobile Services:Deployable technical teams performing A-checks and minor repairs at outstations without base maintenance infrastructure. Demand tracks expanding low-cost long-haul networks with limited home-base hangar access.
- On-site Services:Embedded personnel stationed at customer facilities for continuous line maintenance coverage. Emirates and Qatar Airways utilize this model at Dubai and Doha hubs to minimize aircraft downtime.
Third-party providers are expanding most quickly as Gulf and Asia-Pacific carriers unbundle engine and airframe contracts.
Maintenance Level:
Volume distribution skews toward line maintenance while value concentration sits in heavy check cycles that require dedicated depot capacity.
- Line Maintenance:Pre-flight, transit, and daily checks performed at airport gates or remote stands. Singapore Changi and London Heathrow concentrate activity where wide-body utilization rates exceed fourteen hours daily.
- Base Maintenance:C-check and D-check intervals requiring hangar docking and structural access. Aging A380 and 747-8 fleets are compressing these cycles as FAA corrosion mandates intensify.
- Modifications:Unscheduled structural alterations driven by airworthiness directives or customer specifications. Composite repair certification bottlenecks limit provider availability for 787 fuselage damage.
- Heavy Maintenance:Comprehensive airframe restoration including landing gear overhaul and fuel tank inspections. Specialized labor scarcity extends turnaround times at US Gulf Coast facilities.
Base Maintenance commands current value pools. Heavy Maintenance faces steepest expansion trajectory from aging fleet accumulation.
End User:
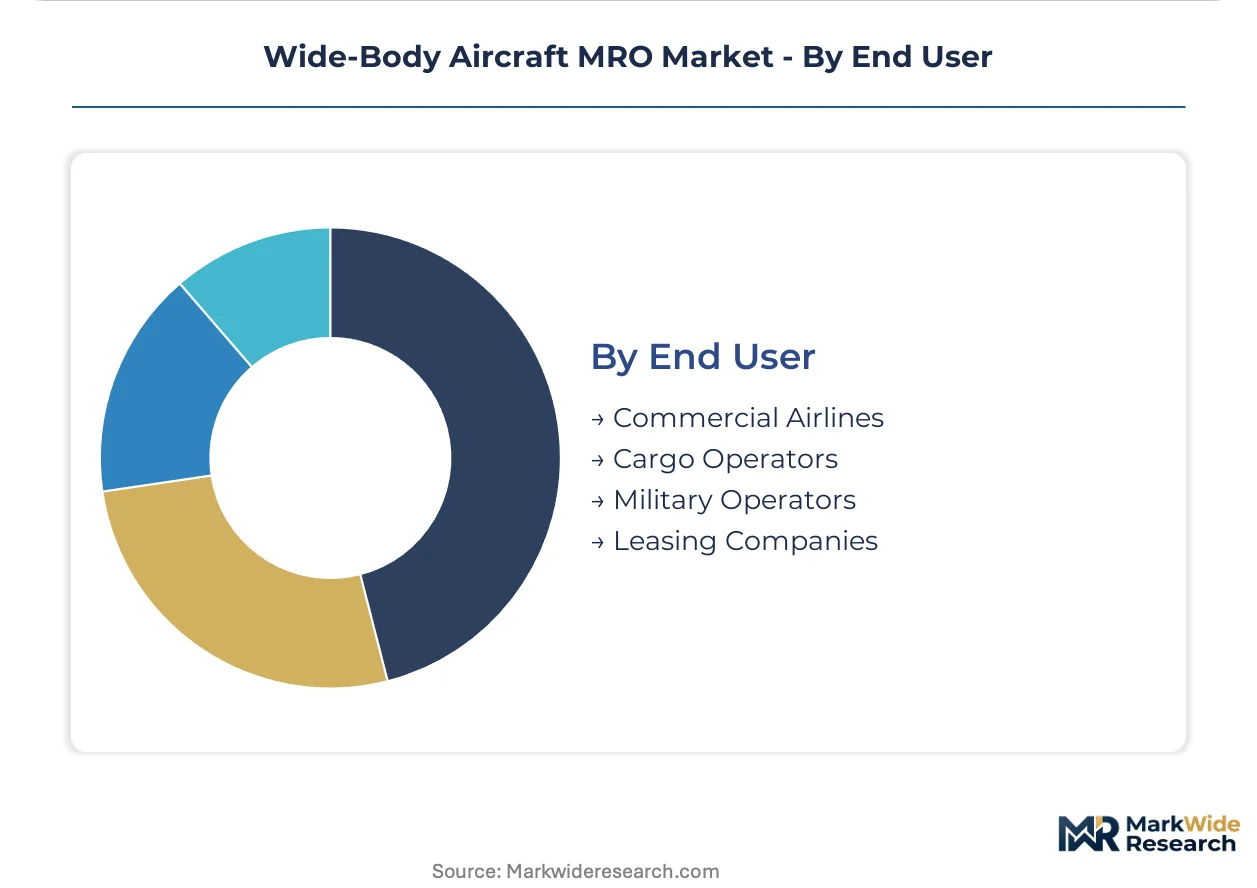
Customer type determines contract structure, with commercial airlines demanding integrated solutions while cargo operators prioritize unit cost minimization.
- Commercial Airlines:Full-service and low-cost long-haul carriers requiring scheduled maintenance programs aligned with route networks. ANA Holdings and Singapore Airlines concentrate heavy check demand in Southeast Asian corridors.
- Cargo Operators:Dedicated freighter fleets and converted passenger aircraft requiring specialized loading system maintenance. Amazon Air and FedEx Express utilize third-party providers for line maintenance at secondary hubs.
- Military Operators:Government air forces and strategic transport commands with classified technical requirements. Boeing KC-46 and Airbus A330 MRTT programs involve restricted facility access.
- Leasing Companies:Aircraft lessors enforcing return condition standards and redelivery maintenance. AerCap and SMBC Aviation Capital specify OEM-authorized repair sources in lease agreements.
Commercial Airlines anchor current demand. Cargo Operators are gaining share fastest from e-commerce freight expansion and passenger-to-freighter conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified composite repair technicians concentrate in Singapore, Hamburg, and Dallas-Fort Worth, anchoring the tripolar maintenance network that handles over sixty percent of wide-body heavy check volume worldwide.
United States
FAA airworthiness directives on aging Boeing 777-300ER wing structures are compressing inspection intervals for US-registered fleets. The FAA Repair Station certification framework mandates recurrent audit cycles that elevate fixed costs for Gulf Coast facilities. Dallas-Fort Worth and Atlanta concentrate engine overhaul capacity where GE90 and Trent XWB shop visits cluster around OEM-authorized workshops.
Germany
Lufthansa Technik AG maintains full technical control over European base maintenance through Hamburg and Malta facilities. EASA Part-145 certification requirements for composite NDT capabilities are creating technician premium tiers at specialized shops. The Hamburg maintenance corridor dominates heavy check demand from Middle East and European flag carriers operating A350 and 787 fleets.
Singapore
ST Engineering Aerospace Ltd. controls Asia-Pacific hangar slots with integrated airframe and component repair lines. The Civil Aviation Authority of Singapore enforces stringent traceable parts documentation standards aligned with ICAO Annex 6. Changi Airport's maintenance zone concentrates 787 and A350 induction schedules from ANA Holdings, Singapore Airlines, and Cathay Pacific.
India
GMR Aero Technic and Air India Engineering Services are expanding wide-body hangar capacity at Delhi and Hyderabad. The government's 2025 MRO policy incentives include tax exemptions on imported tools and reduced GST rates for maintenance services. Hyderabad's emerging aviation cluster is capturing traffic currently flowing to Singapore and Dubai for C-check and D-check intervals.
United Arab Emirates
Emirates and Qatar Airways are unbundling engine overhaul from airframe maintenance contracts, creating standalone competitive bidding events. The General Civil Aviation Authority mandates EASA-equivalent certification standards for Dubai-based facilities. Al Maktoum International Airport's maintenance zone is absorbing expanded line maintenance demand from low-cost long-haul operators with limited home-base hangar access.
Wide-Body Aircraft MRO Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards scale in engine overhaul while fragmenting airframe and component repair into regional niches. Three archetypes dominate: airline-captive divisions with full technical control, OEM-affiliated service arms leveraging proprietary documentation, and independent third-party contractors bidding on turnaround guarantees. M&A activity concentrates on composite repair capability acquisitions, while capacity expansion targets Indian and Southeast Asian greenfield hangar developments.
Within the airline-captive tier, Lufthansa Technik AG and Delta TechOps exemplify vertically integrated operators capturing margin through in-house production of heavy maintenance services. ST Engineering Aerospace Ltd. and MTU Aero Engines AG occupy positions as scale-driven specialists with geographic anchoring in Asia-Pacific and European corridors respectively. These entities represent the competitive tension between full-service integration and modular outsourcing that is reshaping contract structures across the industry.
| Leading Market Players |
|---|
| ST Engineering Aerospace Ltd. |
| MTU Aero Engines AG |
| Boeing Global Services |
| Iberia Maintenance S.A |
| Delta TechOps |
| Airbus SE |
| Lufthansa Technik AG |
| Korean Air Lines Co. Ltd. |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
Captive maintenance divisions at Lufthansa Technik and Delta TechOps anchor both supply positioning and pricing power through in-house production of heavy check services, insulating margin pools that third-party contractors forfeit to competitive bidding.
Pricing Analysis
The bundled-versus-unbundled service split is fragmenting traditional contract structures across the market. Three-tier pricing stratifies across OEM-authorized, EASA Part-145 certified, and uncertified repair tiers, with differentiation hinging on technical documentation access and technician qualification levels. Cost compression in base maintenance is intensifying because Gulf carriers are separating engine overhaul from airframe awards. Cargo operators exhibit highest price sensitivity due to unit-cost minimization mandates, while leasing companies tolerate premium pricing to enforce return condition standards.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for proprietary repair manuals and certified components. Supply concentrates in Singapore, Germany, and the United States, with specialized inputs drawing from titanium alloy smelters, carbon fiber prepregs, and avionics semiconductor fabricators. Single-source vulnerability permeates the titanium supply following Western sanctions on Russian VSMPO-AVISMA. Distribution runs through OEM-authorized service networks, independent Part-145 stations, and airline-captive shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market functions as a geographic-arbitrage play where EASA-equivalent certification costs in Dubai undercut Hamburg labor premiums by substantial margins, redirecting fleet induction schedules toward Middle Eastern corridors.
For Market Incumbents: Deploy composite repair automation to offset technician scarcity compressing turnaround times at US Gulf Coast facilities. Defend margin pools by securing exclusive OEM technical data licenses before independent shops complete certification investments. Capacity addition in Hyderabad captures traffic currently flowing to Singapore for C-check intervals. For New Entrants and Emerging Players: Capture white-space in India MRO infrastructure where government policy incentives reduce import duties on specialized tooling. Target component repair segments exhibiting fastest trajectory from rotable inventory scarcity. Pursue EASA Part-145 certification partnerships with established European shops to bypass apprenticeship cycle barriers. For Investors and Strategic Acquirers: Roll-up economics work for composite NDT specialists because certification bottlenecks create scarcity premiums for qualified technician pools. Long-term viability centers on facilities with demonstrated OEM preferred supplier status and digital twin integration capabilities. Monitor FAA airworthiness directive issuance frequency as inflection indicator for unscheduled depot visit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Repair Automation Deployment | Robotic scarfing cells at Lufthansa Technik Hamburg reduce skilled labor hours by forty percent. |
| EASA Part-145 Certification Investment | Composite NDT capability addenda unlock technician premium tiers at specialized European shops. |
| India Hangar Capacity Expansion | GMR Aero Technic Delhi facilities capture traffic diversion from Singapore maintenance corridors. |
| OEM Technical Data Licensing | Boeing Global Services proprietary documentation controls aftermarket pricing for 787 fleets. |
| Predictive Maintenance Platform Integration | Digital twin simulations enable condition-based engine shop visits at ST Engineering Singapore. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining maintenance director interviews at full-service carriers, procurement leads at leasing companies, and regulatory affairs specialists at EASA and FAA. Secondary validation draws from airworthiness directive databases, fleet induction schedules, and OEM service bulletin disclosures. Bottom-up hangar capacity modeling triangulates against top-down MRO spend estimates across the analysis window.
Rate-of-change decomposition separates fleet age effects from induction schedule acceleration and regulatory mandate compression. Segmentation dimensions include service type, delivery model, maintenance level, and end-user category, with geographic repair cluster capacity serving as an industry-specific overlay. CAGRs derive from technician supply projections, composite penetration curves, and airworthiness directive pipeline analysis.
Regulatory mandate delays, titanium supply qualification timelines, and technician apprenticeship completion rates are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on fleet retirement schedules and OEM intellectual property policy evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market