
 Global Active and Intelligent Packaging Market | 2026-2036
Global Active and Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active and Intelligent Packaging Market Analysis
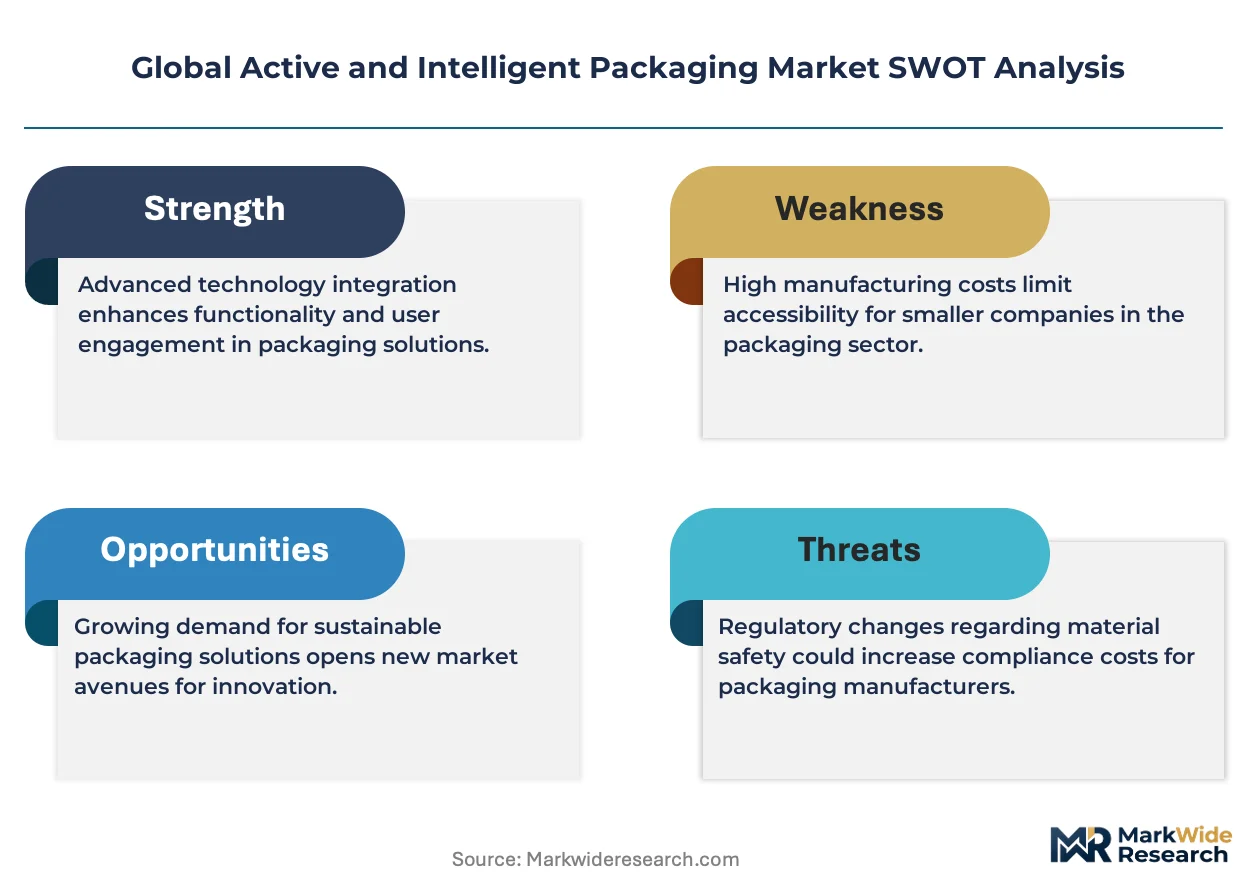
The EU Green Deal is expanding requirements for circular packaging materials across member states, forcing converters to redesign oxygen-scavenging films and moisture-regulating layers. Amcor plc leverages its European manufacturing footprint to supply compliant barrier solutions. Sealed Air Corporation sustains R&D intensity in renewable feedstock chemistry. Mondi Group anchors its position through integrated kraft paper and film operations.
Active and intelligent packaging encompasses systems that interact with contained products or external environments to extend shelf life, ensure safety, or communicate status through embedded sensors, indicators, or data carriers. These systems typically incorporate oxygen absorbers, ethylene scavengers, time-temperature indicators, or RFID inlays laminated at 13.56 MHz or UHF frequencies to enable real-time supply chain visibility. Intelligent Packaging leads commercial deployment because track-and-trace mandates from Walmart and Amazon require item-level digital identity. Active Packaging competes on total cost of ownership as food processors weigh spoilage reduction against per-unit film premiums. Sensors within the Technology dimension command margin pools due to calibration complexity and FDA validation requirements for pharmaceutical applications.
The FDA enforces 21 CFR Part 211 for pharmaceutical packaging integrity, while the EU MDR tightens traceability rules for medical device shipments. REACH restricts certain chromogenic indicator chemicals, redirecting formulation investment toward bio-based alternatives. Stakeholders must monitor how ECHA substance evaluations and emerging state-level extended producer responsibility laws in California and New York reshape material qualification timelines and regional sourcing strategies.
Market Dynamics
Biopharmaceutical cold chain expansion is compressing validation timelines for sensor-embedded packaging, forcing converters to pre-qualify multi-parameter indicators alongside primary barrier films rather than sequential testing.
Growth Catalysts
- EU Green Deal packaging mandates:Circular economy requirements for biodegradable barriers accelerate material substitution in oxygen-scavenging films across member state food sectors.
- RFID item-level serialization:Walmart and Amazon track-and-trace mandates pull UHF inlay demand into pharmaceutical and fresh produce logistics networks.
- German food waste reduction laws:Precision logistics infrastructure concentrates procurement pull for time-temperature indicators in retail distribution.
Market Restraints
- Chromogenic indicator chemistry restrictions:ECHA substance evaluations under REACH redirect formulation investment, extending qualification timelines for color-change sensors.
- Calibration complexity concentration:FDA 21 CFR Part 211 validation requirements for pharmaceutical sensors limit qualified supplier pools to specialized calibration houses.
- Biodegradable barrier cost premiums:Renewable feedstock chemistry raises per-unit film costs versus conventional multi-layer structures in price-sensitive processed food segments.
Strategic Opportunities
- India cold chain infrastructure gaps:CDSCO temperature monitoring requirements for biologics distribution create first-mover positioning for validated sensor-embedded shippers.
- Extended producer responsibility expansion:California and New York state-level EPR laws reshape material qualification toward closed-loop recovery systems.
- Printed electronics convergence:Integration of thin-film batteries with NFC inlays enables disposable temperature loggers at unit economics competitive with conventional data loggers.
Industry Challenges
- Multi-parameter sensor integration:Combining oxygen, humidity, and temperature sensing in single flexible substrates requires cross-functional expertise spanning electrochemistry and polymer processing.
- Legacy warehouse management system compatibility:RFID inlay data formats often conflict with existing ERP protocols, forcing middleware development or reader infrastructure replacement.
- ISO 17025 calibration capacity:Pharmaceutical sensor validation demand outpaces accredited laboratory throughput, creating bottlenecks for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active and Intelligent Packaging Market |
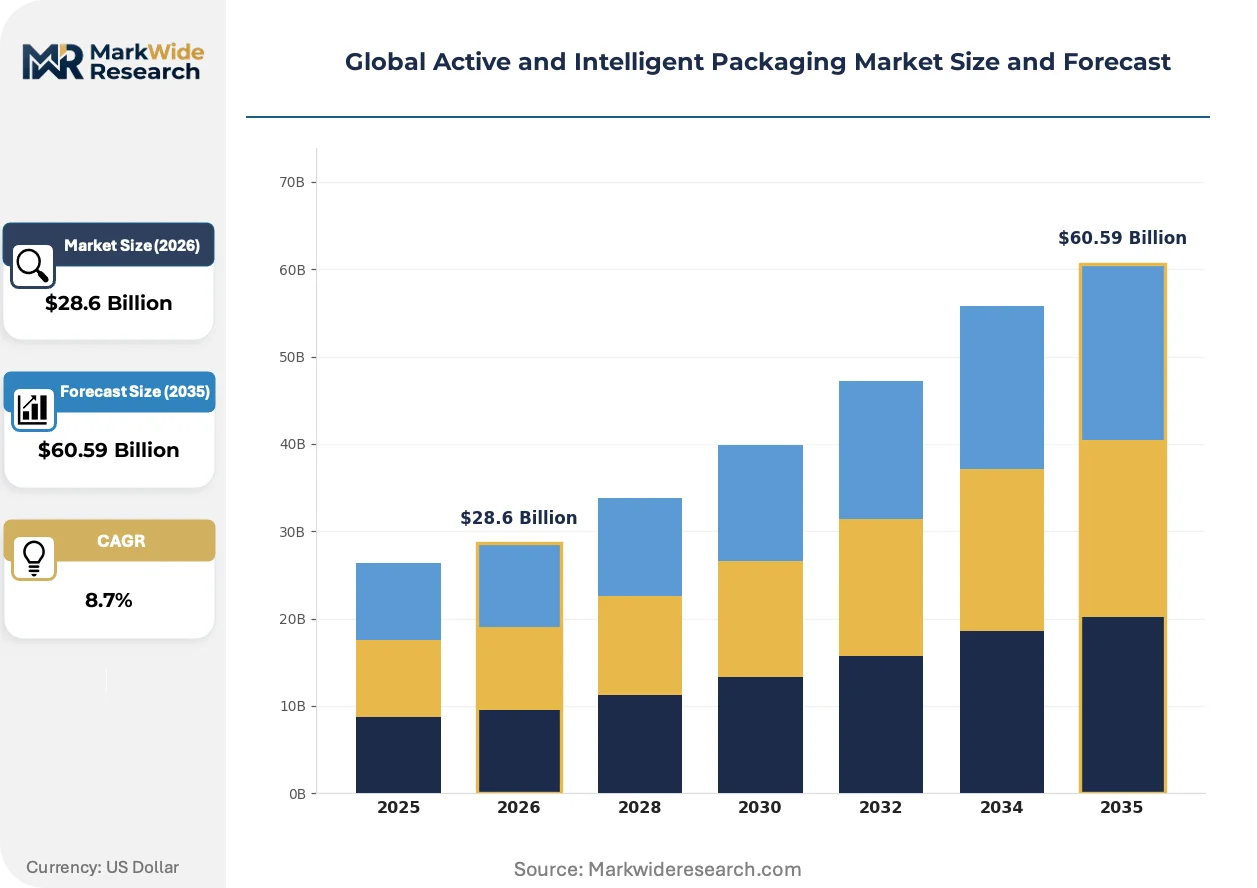
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Intelligent Packaging, Smart Labels, Modified Atmosphere Packaging End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: RFID, QR Codes, Sensors, Nanotechnology Application: Fresh Food Preservation, Track & Trace, Brand Protection, Anti-Counterfeiting |
| Companies Covered | 3M Company, Sealed Air Corporation, Amcor plc, Huhtamäki Oyj, Avery Dennison Corporation, Mondi Group, DuPont de Nemours, Inc., Multisorb Technologies, Inc., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active and Intelligent Packaging Market Emerging Trajectories
Packaging functionality is migrating from passive containment to active environmental management, with embedded intelligence becoming standard in temperature-sensitive supply chains rather than premium positioning.
Printed sensor networks is modularizing quality assurance architecture. Thin-film thermistors and humidity-sensitive resistive elements laminate directly onto corrugated substrates, replacing discrete data loggers. Pharmaceutical 3PL providers in the Benelux region adopt these substrates for last-mile biologics distribution. The technology is modularizing how cold chain documentation gets generated, shifting from device retrieval to cloud-streamed exception alerts.
EU MDR traceability expansion tightens medical device shipment documentation. Unique device identifier requirements now extend to secondary packaging, mandating human-readable and machine-scannable codes. German and French hospital procurement coalitions drive demand for combined RFID-2D matrix label systems. Converters reconfigure print lines to accommodate dual-encoding verification stations.
Fresh produce buyers now specify outcome-based shelf-life guarantees rather than material specifications. Retail chains in the Netherlands and Belgium contract directly for spoilage reduction performance, forcing packaging suppliers to assume inventory risk. This procurement model compresses supplier margins while rewarding predictive freshness algorithms. The shift is most visible in berry and leafy green categories where shrink rates historically exceeded fifteen percent.
Global Active and Intelligent Packaging Market Segmentation
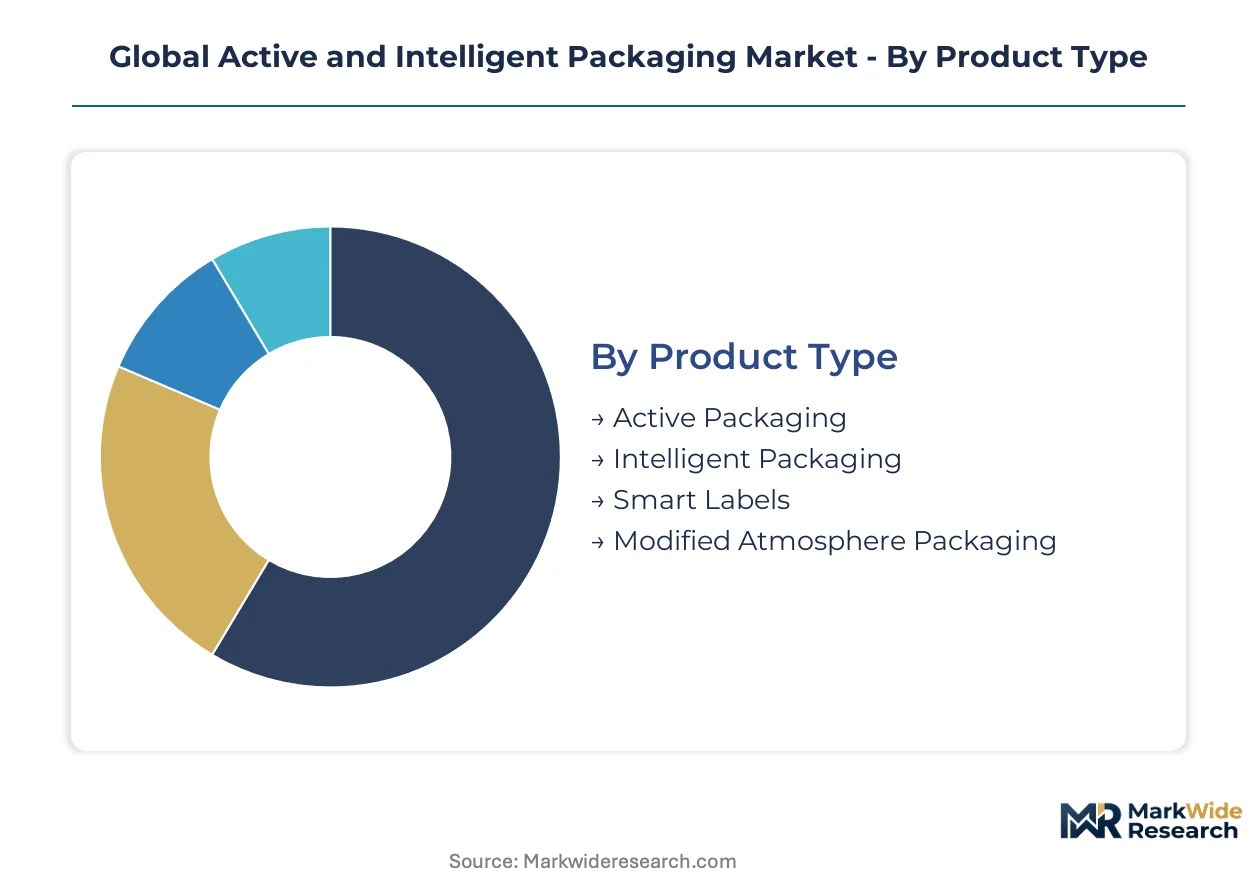
Active and intelligent packaging spans functionally distinct systems whose technical requirements diverge sharply by payload sensitivity and regulatory exposure. Segmentation reveals where sensor calibration complexity commands premium pricing versus where commodity oxygen scavengers compete on per-unit cost.
Product Type:
Standardization dominates oxygen-absorbing sachets and ethylene scavengers, while intelligent systems require bespoke sensor integration and cloud architecture customization.
- Active Packaging:Oxygen absorbers, ethylene scavengers, and moisture regulators embed directly into primary films or sachets. Food processors in Germany specify these systems under national waste reduction mandates where spoilage reduction justifies per-unit film premiums.
- Intelligent Packaging:RFID inlays, NFC tags, and printed electronics enable real-time environmental monitoring and supply chain visibility. Pharmaceutical cold chains in the Benelux region compress validation timelines for these systems as biologics shipments require continuous temperature documentation.
- Smart Labels:Time-temperature indicators and freshness sensors attach to secondary packaging for consumer-facing quality communication.
- Modified Atmosphere Packaging:Gas-flushed barrier structures with active scavenging layers extend shelf life in fresh produce and ready-to-eat categories.
Most installed capacity flows through Active Packaging. Expansion is steepest in Intelligent Packaging.
End User:
Margin concentration aligns with regulatory stringency, with pharmaceutical and food applications absorbing sensor validation costs that cosmetics and electronics segments resist.
- Food & Beverage:Oxygen-scavenging films and time-temperature indicators deploy across fresh produce, meat, and dairy supply chains. Retail chains in the Netherlands and Belgium now contract for outcome-based spoilage reduction, transferring inventory risk to packaging suppliers.
- Pharmaceuticals:Multi-parameter sensor-embedded shippers with FDA 21 CFR Part 211 validation support biologics cold chains. CDSCO temperature monitoring requirements in India create first-mover positioning for validated packaging providers as domestic biologics distribution expands.
- Cosmetics:Anti-counterfeiting features and premium unboxing experiences drive intelligent label adoption in high-value skincare.
- Electronics:Humidity indicators and shock sensors protect sensitive components during international logistics.
Pharmaceuticals captures the highest per-unit value. Food & Beverage delivers the largest addressable volume base.
Technology:
Hardware integration difficulty separates established RFID infrastructure from emerging printed sensor networks still resolving calibration standardization.
- RFID:UHF and 13.56 MHz inlays laminate onto secondary packaging for item-level serialization. Walmart and Amazon track-and-trace mandates pull demand into pharmaceutical and fresh produce networks, though legacy warehouse management system compatibility remains a deployment barrier.
- QR Codes:Low-cost optical identifiers link to cloud-hosted product provenance and authentication databases.
- Sensors:Thin-film thermistors, humidity-sensitive resistive elements, and electrochemical gas detectors enable disposable environmental logging. ISO 17025 calibration capacity constraints limit qualified supplier pools for pharmaceutical applications.
- Nanotechnology:Nanoclay barrier films and antimicrobial nanoparticle coatings enhance mechanical and biological protection.
RFID infrastructure represents the most mature installed base. Sensors are climbing the fastest as printed electronics convergence enables unit economics competitive with conventional data loggers.
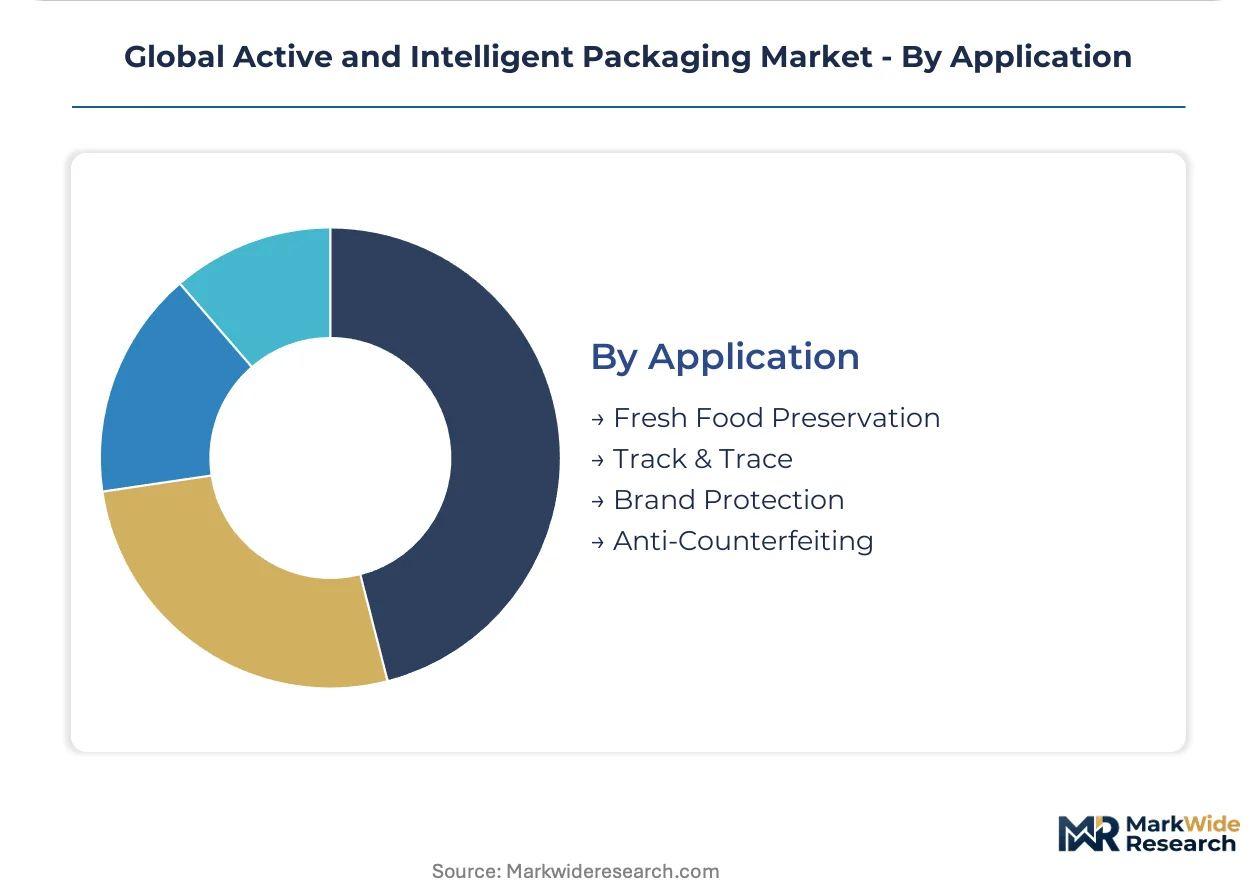
Application:
Procurement specifications are shifting from material guarantees to performance outcomes, particularly in temperature-sensitive and high-shrink categories.
- Fresh Food Preservation:Active scavenging and modified atmosphere systems reduce spoilage in berries and leafy greens where retail shrink historically exceeded fifteen percent. German food waste reduction laws concentrate procurement pull for these solutions.
- Track & Trace:RFID and 2D matrix codes satisfy EU MDR unique device identifier requirements extending to secondary packaging. German and French hospital procurement coalitions drive demand for combined encoding systems.
- Brand Protection:Covert and overt authentication features combat diversion and gray market infiltration in premium categories.
- Anti-Counterfeiting:Forensic markers, holographic elements, and blockchain-linked digital identifiers secure high-value pharmaceuticals and luxury goods.
Fresh Food Preservation commands the largest current deployment. Track & Trace is expanding most quickly as regulatory mandates proliferate across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active and intelligent packaging industrialized first in German chemical corridors during the 1990s, where oxygen-scavenging film chemistry matured alongside precision logistics infrastructure. That heritage now distributes across five demand poles where regulatory stringency and cold chain investment concentrate procurement.
Germany
Federal food waste reduction mandates and pharmaceutical distribution density pull time-temperature indicators into retail and hospital supply chains. The EU Green Deal packaging requirements accelerate biodegradable barrier film qualification at converter sites. The Rhine-Main logistics corridor hosts validation laboratories serving Benelux biopharma cold chains.
United States
Walmart and Amazon item-level serialization mandates drive UHF RFID inlay demand through pharmaceutical and fresh produce networks. FDA 21 CFR Part 211 enforcement compresses sensor calibration timelines for biologics shippers. The New Jersey-Pennsylvania pharmaceutical packaging cluster anchors East Coast cold chain infrastructure investment.
China
Domestic biologics distribution expansion and NMPA temperature monitoring guidance create procurement pull for validated sensor-embedded shippers. Dual carbon goals redirect state investment toward renewable feedstock barrier chemistry. The Yangtze River Delta concentration of cold chain 3PL providers tests printed electronics integration at scale.
India
CDSCO temperature monitoring requirements for biologics distribution open first-mover positioning as domestic vaccine and biosimilar output expands. FSSAI traceability consultations signal impending mandate expansion beyond pharmaceuticals. The Mumbai-Pune pharmaceutical manufacturing belt concentrates converter partnerships for validated packaging.
Netherlands
Fresh produce retail chains now contract for outcome-based spoilage reduction, transferring inventory risk to packaging suppliers. REACH-compliant chromogenic indicator reformulation redirects formulation investment toward bio-based alternatives. The Rotterdam port logistics zone serves as the entry node for RFID-enabled pharmaceutical shipments entering EU distribution.
Global Active and Intelligent Packaging Market Vendor Landscape
Capital-heavy integrated film producers compete with asset-light sensor designers and calibration specialists for margin pools in pharmaceutical applications. The market structures around three tiers: multinational converters with European manufacturing footprints, regional specialists in RFID inlay lamination, and accredited calibration houses serving FDA validation requirements. Consolidation pressure runs through strategic partnerships bridging film extrusion with cloud architecture, while geographic expansion targets Indian cold chain infrastructure gaps.
Among diversified packaging converters, Amcor plc and Sealed Air Corporation occupy positions spanning compliant barrier supply and renewable feedstock chemistry. Mondi Group anchors integrated kraft paper and film operations serving EU Green Deal circular economy requirements. These three exemplify the scale-driven archetype competing on qualification speed and multi-jurisdiction regulatory coverage.
| Leading Market Players |
|---|
| 3M Company |
| Sealed Air Corporation |
| Amcor plc |
| Huhtamäki Oyj |
| Avery Dennison Corporation |
| Mondi Group |
| DuPont de Nemours, Inc. |
| Multisorb Technologies, Inc. |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up calibration specialists have consolidated ISO 17025 laboratory networks across Germany and the United States, tightening pricing discipline for pharmaceutical sensor validation while fragmenting bargaining power among converters seeking multi-jurisdiction qualification coverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated multi-parameter sensor systems from unvalidated printed indicators and commodity oxygen-scavenging films. Certification grade and volume scale drive price differentiation, with pharmaceutical-grade calibration commanding substantial premiums over food-sector alternatives. Cost compression in standard-tier RFID inlays is intensifying because Walmart and Amazon serialization mandates have pulled Asian laminate capacity into oversupply. Processed food segments exhibit the highest price sensitivity, while biopharmaceutical cold chain operators absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Freight cost volatility for temperature-controlled pharmaceutical shipments has compressed converter margins on validated sensor-embedded shippers destined for Indian and Chinese biologics distribution networks. Supply concentrates in Germany, the United States, and China, with specialized calibration capacity anchored in the Rhine-Main corridor and New Jersey-Pennsylvania clusters. Raw material dependencies span chromogenic indicator chemicals, thin-film battery substrates, and UHF antenna copper etching feedstock. Single-source vulnerability in ECHA-regulated indicator formulations poses structural risk as REACH substance evaluations redirect formulation investment toward bio-based alternatives. Distribution runs through pharmaceutical 3PL providers and fresh produce retail procurement coalitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO temperature monitoring requirements in India impose validation costs that European and North American specialists can undercut against domestic Indian converters facing ISO 17025 accreditation bottlenecks.
For Market Incumbents: Hedge regulatory fragmentation by pre-qualifying multi-parameter sensor platforms across FDA, EMA, and CDSCO validation frameworks simultaneously rather than sequential jurisdiction-by-jurisdiction submission. Defend margin position through backward integration into thin-film battery substrate production, capturing printed electronics convergence before unit economics commoditize. For New Entrants and Emerging Players: Begin with outcome-based spoilage reduction contracts for Dutch and Belgian fresh produce retail chains, where inventory risk transfer to packaging suppliers has created procurement openness toward unproven predictive freshness algorithms. Target printed sensor networks for last-mile biologics distribution in the Benelux region, leveraging modular quality assurance architecture to bypass legacy data logger incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among regional RFID inlay laminators lacking cloud architecture integration capabilities but holding established converter relationships and Amazon-Walmart track-and-trace mandate compliance. The long-term viability window favors acquisition of accredited calibration houses with multi-parameter sensor expertise, as pharmaceutical cold chain expansion outpaces laboratory throughput capacity. Watch for ECHA substance evaluation announcements as inflection indicators directing formulation investment toward bio-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Qualification Acceleration | Simultaneous FDA-EMA-CDSCO validation compresses launch timelines for biopharmaceutical sensor platforms. |
| Printed Electronics Integration | Thin-film battery convergence with NFC inlays enables disposable temperature loggers at competitive unit economics. |
| Outcome-Based Contracting | Spoilage reduction guarantees transfer inventory risk from Dutch retail chains to packaging suppliers. |
| Backward Integration into Calibration | ISO 17025 laboratory acquisition secures bottlenecked pharmaceutical sensor validation capacity. |
| Bio-Based Indicator Reformulation | REACH-compliant chromogenic chemistry redirection aligns with EU Green Deal circular economy mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converters, pharmaceutical 3PL operations directors, fresh produce retail procurement managers, and accredited calibration laboratory technical leads with secondary validation against FDA 21 CFR Part 211 guidance documents, ECHA substance evaluation databases, CDSCO biologics distribution circulars, and EU MDR traceability implementation notices. Bottom-up sensor shipment data triangulated against top-down pharmaceutical cold chain infrastructure investment flows.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling spanning active versus intelligent packaging function, food versus pharmaceutical versus cosmetics end-use, RFID versus sensor versus printed electronics technology, and fresh preservation versus track-and-trace versus anti-counterfeiting application. CAGRs derived from regression analysis of regulatory mandate implementation timelines and cold chain infrastructure buildout curves, with cross-validation against converter capacity expansion announcements and 3PL provider fleet investment patterns.
Caveats apply where ECHA substance evaluation outcomes or CDSCO mandate expansion timing could materially shift the outlook for chromogenic indicator availability and Indian market entry economics. Forecasts reflect assumptions regarding REACH compliance cost pass-through and Walmart-Amazon serialization mandate enforcement consistency. A model refresh is warranted upon material change in EU MDR unique device identifier extension to tertiary packaging or state-level extended producer responsibility law passage in California and New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market