
 Ambient Packaging Market | 2026-2036
Ambient Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ambient Packaging Market Outlook
Packaging engineering talent is collapsing across European and North American manufacturing hubs as universities shutter dedicated polymer and barrier-material programs. Amcor plc leverages its integrated film-to-cup operations to dominate aseptic dairy formats in Australia and Latin America. Tetra Pak anchors its competitive position through captive aluminum-lidding supply chains and in-house filling equipment ecosystems. Mondi Group specializes in kraft-paper barrier solutions that compete directly with plastic laminates for dry-food applications.
Ambient packaging denotes sealed container systems engineered to maintain product stability without refrigeration, typically incorporating oxygen scavengers, moisture barriers, or multilayer coextrusions with water-vapor transmission rates below 0.1 g/m²/day. These systems enable shelf-stable distribution of pasteurized beverages, retorted meals, and hygroscopic pharmaceuticals across extended supply chains. Flexible packaging leads volume in emerging economies where cost-per-unit and logistics efficiency govern procurement decisions, while aseptic carton technology captures premium margin pools in liquid dairy and plant-based alternatives. Compostable materials represent the fastest-growing material segment as brand owners face compliance deadlines under extended producer responsibility frameworks.
The EU Packaging and Packaging Waste Regulation, FDA food-contact substance notifications, and BIS certification requirements for plastic food-contact articles collectively reshape material selection and regional market access protocols. EFSA migration-limit assessments and state-level extended producer responsibility laws in California and New York add compliance layers that favor large-format suppliers with dedicated regulatory affairs teams. Stakeholders must monitor divergence between EU recyclability mandates and U.S. state-level patchwork rules when configuring regional product portfolios.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design timelines for multilayer barrier films as recyclability mandates override legacy oxygen-scavenger chemistries. Material suppliers face forced requalification of entire product portfolios.
Growth Catalysts
- Retort pouch adoption:Food processors in Thailand and Vietnam are converting canned seafood and curry production lines to flexible retort formats, cutting logistics cube by 40%.
- EU Green Deal packaging targets:Mandatory recycled-content thresholds for plastic food-contact articles are pulling investment into chemical recycling infrastructure for polyolefin recovery.
- Aluminum-lidding supply security:Captive smelter arrangements in the Middle East are stabilizing input costs for aseptic dairy carton producers serving African export markets.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:Three Japanese and Korean suppliers control 80% of global EVOH capacity for oxygen-barrier layers, exposing converters to force majeure risk.
- EFSA migration-limit uncertainty:Pending reassessments of mineral oil saturated hydrocarbons in recycled paperboard are freezing investment in fiber-based food-contact packaging lines.
- Glass jar substitution in premium sauces:Mediterranean and Latin American brand owners are reverting to glass for visual differentiation, capping growth in retortable polypropylene tubs.
Strategic Opportunities
- Indonesian cold-chain gaps:Archipelago geography and unreliable refrigeration create addressable white space for shelf-stable UHT coconut milk in aseptic cartons.
- Bio-based barrier coatings:Convergence of enzymatic hydrolysis and plasma deposition is enabling cellulose nanofibril films with sub-1 g/m²/day water-vapor transmission.
- California SB 54 EPR credits:Early compliance with extended producer responsibility frameworks generates tradable recycling credits that subsidize compostable material premiums.
Industry Challenges
- Polymer rheology expertise collapse:University closures of dedicated extrusion and coextrusion programs in Germany and Ohio are narrowing the pipeline for barrier-film process engineers.
- Multilayer delamination certification:Recyclability protocols requiring demonstrable layer separation are extending qualification timelines from 18 to 36 months for new laminate structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambient Packaging Market |
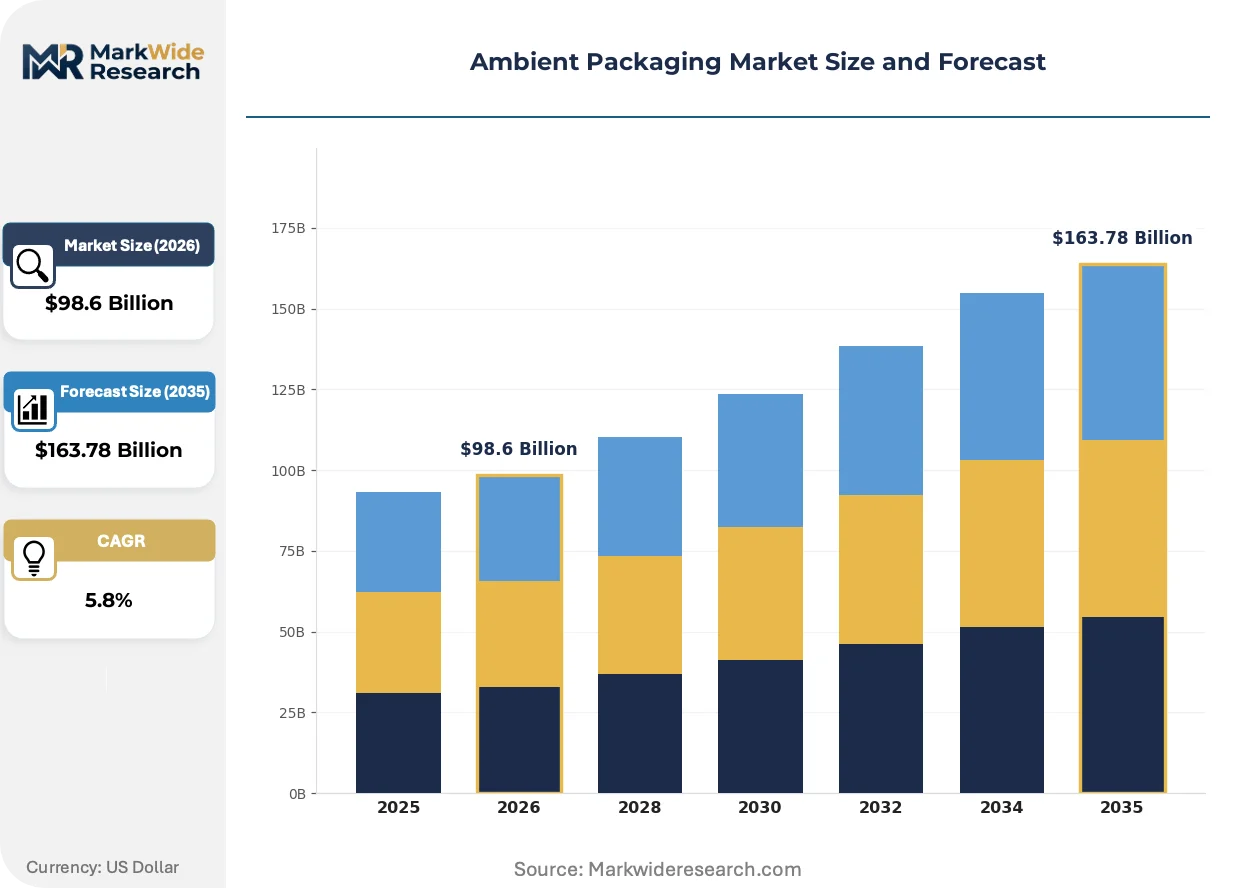
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Metal Containers, Glass Containers Material: Plastic, Paper, Aluminum, Compostable Materials End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Technology: Modified Atmosphere Packaging, Vacuum Packaging, Aseptic Packaging, Active Packaging |
| Companies Covered | Amcor plc, Tetra Pak, Mondi Group, SIG Group AG, Huhtamäki Oyj, Constantia Flexibles, Berry Global Inc., Sealed Air Corporation, Crown Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambient Packaging Market Strategic Shifts
Active and intelligent packaging functionalities are migrating from pharmaceutical cold-chain applications into ambient food systems, creating new value pools around freshness verification and supply-chain transparency.
High-barrier bio-based films incorporating chitosan or alginate layers are bifurcating the dry-food segment. European snack brands with plastic-reduction commitments are piloting these materials for nut and dried-fruit applications at 10,000-ton annual volumes. The technology is compressing demand for conventional metallized oriented polypropylene in premium private-label channels.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant paperboard used for bakery and confectionery trays. German and French converters are accelerating testing of clay-based barrier coatings. The bakery segment is absorbing 70% of the compliance-driven R&D spend as migration limits tighten fastest for fat-contact applications.
Direct-to-retailer procurement contracts are displacing traditional distributor networks for ambient beverage cartons. German and Dutch supermarket chains are consolidating volume commitments to secure dedicated production slots and custom print runs. This concentration is most visible in private-label plant-based milk, where three retail groups now specify barrier specifications directly with converters.
Ambient Packaging Market Segmentation
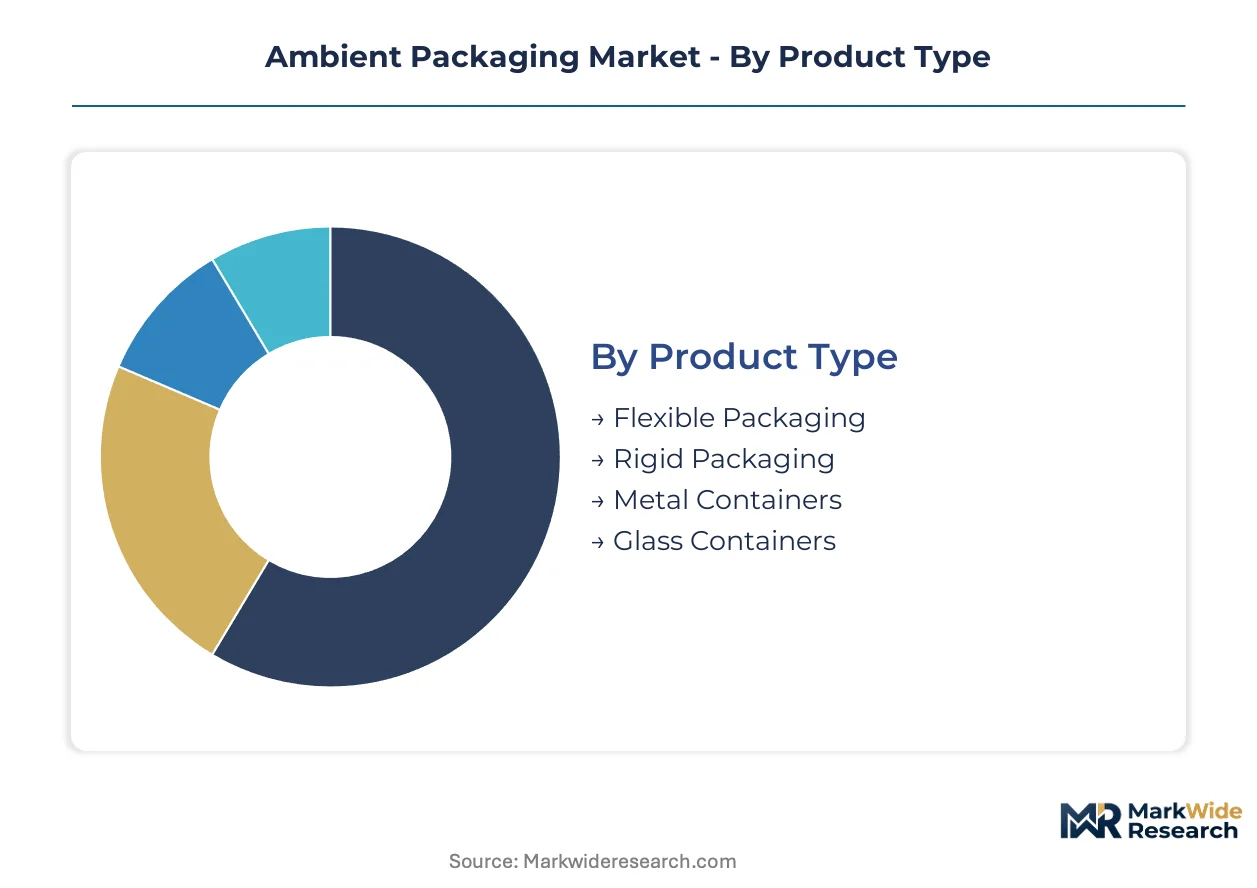
Ambient packaging procurement decisions split across material performance requirements, regulatory compliance burdens, and shelf-life specifications. Understanding these segment boundaries clarifies where converter investments concentrate versus where substitution threats reshape competitive dynamics.
Product Type:
Flexible formats face the most acute substitution pressure from rigid alternatives as brand owners weigh logistics efficiency against shelf presence and perceived quality.
- Flexible Packaging:Multilayer coextruded films and pouches with oxygen transmission rates below 0.1 cc/m²/day dominate retort meals and UHT dairy in Southeast Asian export corridors. Thai and Vietnamese food processors are converting canned seafood lines to retort pouches, cutting cube utilization by 40% and freight costs proportionally.
- Rigid Packaging:Injection-molded polypropylene tubs and thermoformed trays serve premium sauce segments where visual differentiation commands shelf price premiums. Mediterranean brand owners in Italy and Spain are reverting to glass for authentic positioning, capping rigid polymer growth in heritage product categories.
- Metal Containers:Three-piece tinplate cans and two-piece aluminum vessels retain dominance in pet food and infant formula where absolute oxygen exclusion is non-negotiable. Japanese and Korean EVOH supply concentration exposes converters to force majeure risk for barrier alternatives.
- Glass Containers:Borosilicate and soda-lime jars anchor premium positioning in artisanal sauces and condiments. Latin American markets show particular stickiness for glass in visual-first retail environments.
Flexible packaging anchors the volume base while rigid formats gain share at the steepest rate in premium private-label channels.
Material:
Cost tier stratification separates commodity resins from engineered barrier solutions and emerging bio-based alternatives.
- Plastic:Polyethylene terephthalate and polypropylene laminates constitute the baseline economics for ambient beverage and dry-food applications. EU Packaging and Packaging Waste Regulation recycled-content mandates are forcing requalification of entire polyolefin portfolios.
- Aluminum:Foil laminates and lidding stocks provide absolute moisture and light barriers for pharmaceutical and dairy applications. Middle Eastern captive smelter arrangements are stabilizing input costs for aseptic carton producers serving African export markets.
- Paper:Kraft-paper barrier solutions with clay or bio-based coatings compete directly with plastic laminates for dry-food and bakery trays. EFSA migration-limit uncertainty around mineral oil saturated hydrocarbons is freezing investment in recycled paperboard food-contact lines.
- Compostable Materials:Polylactic acid and polyhydroxyalkanoate blends with enzymatic hydrolysis surface treatments are expanding most quickly as California SB 54 extended producer responsibility credits subsidize material premiums.
Plastic retains the dominant volume position while compostable materials climb the fastest under compliance-driven procurement mandates.
End User:
Application maturity varies sharply across customer verticals, with food and beverage commanding process engineering attention while pharmaceutical requirements pull innovation investment.
- Food & Beverage:Retort pouches, aseptic cartons, and barrier trays for ready-to-eat meals, UHT milk, and shelf-stable dairy. Direct-to-retailer procurement consolidation by German and Dutch supermarket chains is reshaping converter relationships in private-label plant-based milk.
- Pharmaceuticals:High-barrier blister packs and sachets for hygroscopic APIs requiring water-vapor transmission below 0.1 g/m²/day. Active packaging with oxygen scavengers and humidity indicators is migrating from cold-chain into ambient stability applications.
- Personal Care:Tubes and sachets for creams and lotions where aesthetic finish competes with barrier performance. Asia-Pacific formulation houses are driving demand for metallized film alternatives with matte surface treatments.
- Household Products:Detergent pods and cleaning agent pouches requiring chemical resistance and child-resistant closure compatibility. Concentrated formula trends are compressing pack sizes and material throughput.
Food and beverage anchors procurement volume while pharmaceuticals drive the steepest specification escalation for barrier performance tiers.
Technology:
Customer type splits between processors seeking line-speed maximization versus those prioritizing supply-chain transparency and freshness verification.
- Aseptic Packaging:Sterilized product filling into pre-sterilized containers enables ambient distribution of liquid dairy and plant-based alternatives. Tetra Pak's captive aluminum-lidding supply chains and in-house filling equipment ecosystems create high switching costs for brand owners.
- Modified Atmosphere Packaging:Gas-flushed headspaces extend shelf life for ready-to-eat meals and fresh pasta in ambient-stable formats. European converters are integrating inline gas analyzers to verify residual oxygen levels at production speeds.
- Vacuum Packaging:Complete oxygen exclusion for cured meats and hard cheeses where anaerobic stability is paramount. Italian and Spanish processors maintain strong preference for vacuum formats in traditional product categories.
- Active Packaging:Oxygen scavengers, moisture absorbers, and freshness indicators embedded in pack structures. Intelligent functionalities from pharmaceutical cold-chain applications are migrating into ambient food systems for supply-chain transparency.
Aseptic technology commands the installed equipment base while active packaging gains share fastest through premium differentiation and regulatory traceability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA migration-limit assessments and the EU Packaging and Packaging Waste Regulation anchor compliance complexity across European supply chains, while divergent state-level extended producer responsibility laws in California and New York fragment North American market access protocols.
Germany
Retort pouch adoption among processed food exporters drives converter investment in multilayer barrier capacity. The EU Green Deal packaging targets mandate recycled-content thresholds that force polyolefin portfolio requalification. The Ruhr industrial cluster hosts chemical recycling infrastructure projects targeting polyolefin recovery for food-contact applications.
United States
State-level extended producer responsibility laws in California and New York create compliance patchwork favoring large-format suppliers with dedicated regulatory affairs teams. FDA food-contact substance notification requirements reshape material selection protocols. The Midwest manufacturing belt sees university closures of extrusion programs narrowing the barrier-film process engineer pipeline.
China
Aseptic carton capacity expansion serves domestic liquid dairy and plant-based alternative demand. GB standards for plastic food-contact articles establish migration-limit frameworks parallel to EFSA assessments. The Yangtze River Delta manufacturing cluster concentrates flexible packaging converter operations for Southeast Asian export markets.
India
BIS certification requirements for plastic food-contact articles govern regional market access for multilayer barrier films. Shelf-stable UHT dairy and ready-to-eat meal adoption accelerates among domestic food processors. Gujarat and Maharashtra industrial corridors attract investment in aseptic carton manufacturing capacity for subcontinental distribution.
Brazil
ANVISA pharmaceutical packaging regulations pull high-barrier blister and sachet specifications for hygroscopic APIs. Logistics efficiency priorities favor flexible formats in ambient beverage distribution. The São Paulo industrial belt concentrates converter operations serving Mercosur export corridors for shelf-stable food products.
Ambient Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the ambient packaging value chain. The market structure consolidates around integrated material suppliers with captive aluminum-lidding supply chains and filling equipment ecosystems, while fragmented regional converters compete on logistics proximity and custom print flexibility. Three strategic archetypes dominate: integrated multinational material-science platforms, specialized aseptic technology licensors, and regional flexible-film converters. Competitive moves concentrate on forced portfolio requalification under recyclability mandates and direct-to-retailer procurement contract consolidation bypassing traditional distributor networks.
Among integrated multinational platforms, Amcor plc, Tetra Pak, and Mondi Group exemplify divergent strategic positioning. Amcor plc represents the film-to-cup integration archetype with operations spanning Australia and Latin America. Tetra Pak occupies the aseptic technology licensor position with captive supply chain control. Mondi Group anchors the kraft-paper barrier specialization vector competing with plastic laminates.
| Leading Market Players |
|---|
| Amcor plc |
| Tetra Pak |
| Mondi Group |
| SIG Group AG |
| Huhtamäki Oyj |
| Constantia Flexibles |
| Berry Global Inc. |
| Sealed Air Corporation |
| Crown Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85 percent at Thai and Vietnamese retort pouch converters compress marginal cost curves and cement price floors for Southeast Asian export corridors. Scale concentration in flexible barrier film production creates asymmetric bargaining power against fragmented European brand owners facing EU Packaging and Packaging Waste Regulation compliance deadlines.
Pricing Analysis
Geographic price spreads between German chemical recycling output and Gulf Coast virgin polyolefin supply exceed 15 percent on delivered basis. Three-tier pricing structure across premium aseptic carton, standard multilayer film, and economy commodity resin tiers anchors contract negotiations. Price differentiation hinges on EFSA migration certification status and captive aluminum-lidding integration. Cost compression in standard-tier flexible packaging is intensifying because Thai converters are absorbing logistics cube savings from retort pouch conversion. Small-format dry-food brand owners in India exhibit highest price sensitivity; pharmaceutical multinationals in Brazil show lowest.
Supply Chain Analysis
Strategic stockpiling of EVOH resin dominates inventory strategy among European converters exposed to Japanese and Korean supply concentration. Raw material sourcing draws from Saudi Arabian ethylene feedstock, Brazilian bauxite for aluminum smelting, and Finnish kraft pulp for barrier paperboard. Single-source vulnerability concentrates in EVOH oxygen-barrier layers where three suppliers control 80 percent of global capacity. Distribution runs through direct-to-retailer procurement contracts that displace traditional distributor networks in German and Dutch supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer rheology expertise collapse across German and Ohio university programs has created acute capability scarcity in barrier-film process engineering. This talent gap constrains converter expansion timelines and elevates acquisition premiums for teams with coextrusion qualifications.
For Market Incumbents: Shield market position by securing captive aluminum-lidding supply arrangements in Middle Eastern smelter partnerships. Accelerate chemical recycling infrastructure investment in the Ruhr cluster ahead of EU Green Deal recycled-content mandates. Tetra Pak's integrated filling equipment ecosystems demonstrate how backward integration into sterilization technology creates switching costs that retard substitute format penetration.
For New Entrants and Emerging Players: Anchor in Indonesian archipelago distribution gaps where unreliable refrigeration infrastructure creates white space for UHT coconut milk in aseptic cartons. Target bio-based barrier coating development for European snack brand plastic-reduction commitments. Pursue California SB 54 extended producer responsibility credit arbitrage to subsidize compostable material premiums against conventional resin cost structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aseptic technology licensors with captive equipment ecosystems and long-term filling line service contracts. Long-term viability favors integrated material-science platforms with regulatory affairs scale across FDA, EFSA, and BIS jurisdictions. Monitor EFSA mineral oil saturated hydrocarbon reassessment outcomes as inflection indicator for fiber-based food-contact packaging investment freeze resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Middle Eastern captive arrangements stabilize input costs for aseptic dairy carton producers serving African export corridors. |
| Chemical Recycling Infrastructure Buildout | Ruhr cluster projects target polyolefin recovery for EU Green Deal food-contact recycled-content mandates. |
| Bio-Based Barrier Coating Development | Cellulose nanofibril films with sub-1 g/m²/day water-vapor transmission address REACH perfluoroalkyl substance restrictions. |
| Direct-to-Retailer Procurement Consolidation | German and Dutch supermarket chains now specify barrier specifications directly with converters for private-label plant-based milk. |
| Active Packaging Functionality Migration | Oxygen scavengers and freshness indicators from pharmaceutical cold-chain applications enter ambient food systems for supply-chain transparency. |
Study Parameters
A spread of perspectives from packaging engineering directors, polymer procurement leads at food processors, regulatory affairs specialists, and aseptic filling equipment operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, EU Packaging and Packaging Waste Regulation implementation documents, SEC filings of listed converters, and EFSA migration-limit assessment archives. Bottom-up capacity estimates from Thai and Vietnamese retort pouch lines were triangulated against top-down demand projections from German supermarket chain procurement disclosures.
Segmentation dimensions modeled span product type, material composition, end-use vertical, and sterilization technology across the analysis window. CAGRs were derived from installed base depreciation schedules, capacity expansion announcements, and regulatory compliance timeline phasing. Forecast inputs incorporated EU Green Deal recycled-content threshold enforcement calendars and EVOH supply concentration risk premiums.
Material uncertainties — force majeure events at Japanese EVOH facilities, EFSA mineral oil reassessment outcomes, and California SB 54 credit market liquidity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding polymer rheology program closure rates and direct-to-retailer procurement adoption velocity. Revision becomes warranted when BIS certification timeline delays for Indian multilayer barrier films cross thresholds that redirect investment toward alternative geographies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market