
 Active Packaging Market | 2026-2036
Active Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Active Packaging Market Analysis
Aftermarket shelf-life validation services is rewriting margin capture across the value chain. Amcor plc leverages its integrated film manufacturing network to anchor oxygen scavenger supply for protein exporters. BASF SE competes through specialty polymer R&D intensity in antimicrobial masterbatch formulations. Sealed Air Corporation dominates the North American moisture-control segment through captive equipment leasing tied to film supply contracts.
Active packaging encompasses materials engineered with scavenging, absorbing, or releasing functionalities that interact with the packaged product or its headspace atmosphere to extend quality retention, typically employing iron-based oxidation chemistries, clay desiccants, or organic acid emitters at loadings between 0.5% and 5% by film weight. Oxygen scavengers occupy the deepest margin pool due to technical complexity in controlled-release kinetics, while antimicrobial agents represent the fastest-growing product type as pharmaceutical cold-chain requirements tighten. Plastic substrates sustain volume leadership, though paper-based composites are gaining structural share in European fresh produce applications where fiber recyclability mandates apply.
The FDA governs indirect food additive migration limits under 21 CFR, while the EU F-Gas Regulation constrains certain synthetic barrier chemistries, and ISO 22000 certification shapes supplier qualification for multinational Food & Beverage procurement teams. These frameworks collectively elevate compliance costs for smaller converters while rewarding scaled players with in-house regulatory affairs capabilities. Stakeholders must monitor convergence between digital traceability mandates and material functionality requirements as intelligent packaging architectures mature.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for converters, forcing rapid abandonment of multi-layer laminates in favor of mono-material barrier structures that satisfy recyclability mandates without sacrificing oxygen transmission performance.
Growth Catalysts
- Oxygen scavenger films:Protein exporters across refrigerated supply chains are expanding deployment to reduce spoilage rates. Technical advances in iron-based oxidation chemistries now enable controlled-release kinetics matching shelf-life requirements.
- EU F-Gas Regulation:Constraints on synthetic barrier chemistries are redirecting R&D investment toward bio-based alternatives. This regulatory pressure creates first-mover advantages for converters with in-house polymer science capabilities.
- Germany:Centralized retail distribution combined with strict shelf-life labeling laws generates concentrated pull for intelligent moisture-control solutions. Food & Beverage manufacturers prioritize validated performance data over unit cost.
Market Restraints
- Ethylene-vinyl alcohol resin pricing:Volatility in this core barrier polymer input compresses margin predictability for film converters operating on fixed-price annual contracts.
- Masterbatch supply concentration:Antimicrobial additive production clusters among a limited set of European specialty chemical suppliers, creating vulnerability to capacity constraints.
- Migration testing complexity:FDA indirect food additive limits under 21 CFR require extended validation timelines, delaying commercialization for novel active chemistries.
Strategic Opportunities
- Pharmaceutical cold-chain:Tightening temperature excursion requirements create white space for antimicrobial active packaging in biologics distribution. Certification under ISO 22000 opens multinational procurement channels.
- Paper-based composites:European fresh produce applications face fiber recyclability mandates that favor substrate innovation. Clay desiccant integration into molded fiber trays bypasses plastic sorting infrastructure limitations.
- Digital traceability convergence:Intelligent packaging architectures incorporating time-temperature indicators and RFID tags enable outcome-based quality validation. This technology pairing commands premium positioning in high-value protein segments.
Industry Challenges
- Regulatory affairs specialization:Smaller converters lack in-house capability to navigate simultaneous FDA, EFSA, and member-state notification requirements, creating qualification barriers to multinational accounts.
- Legacy equipment incompatibility:Mono-material barrier structures often require modified extrusion and forming parameters, forcing capital deployment or tolling arrangements that disrupt established supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Packaging Market |
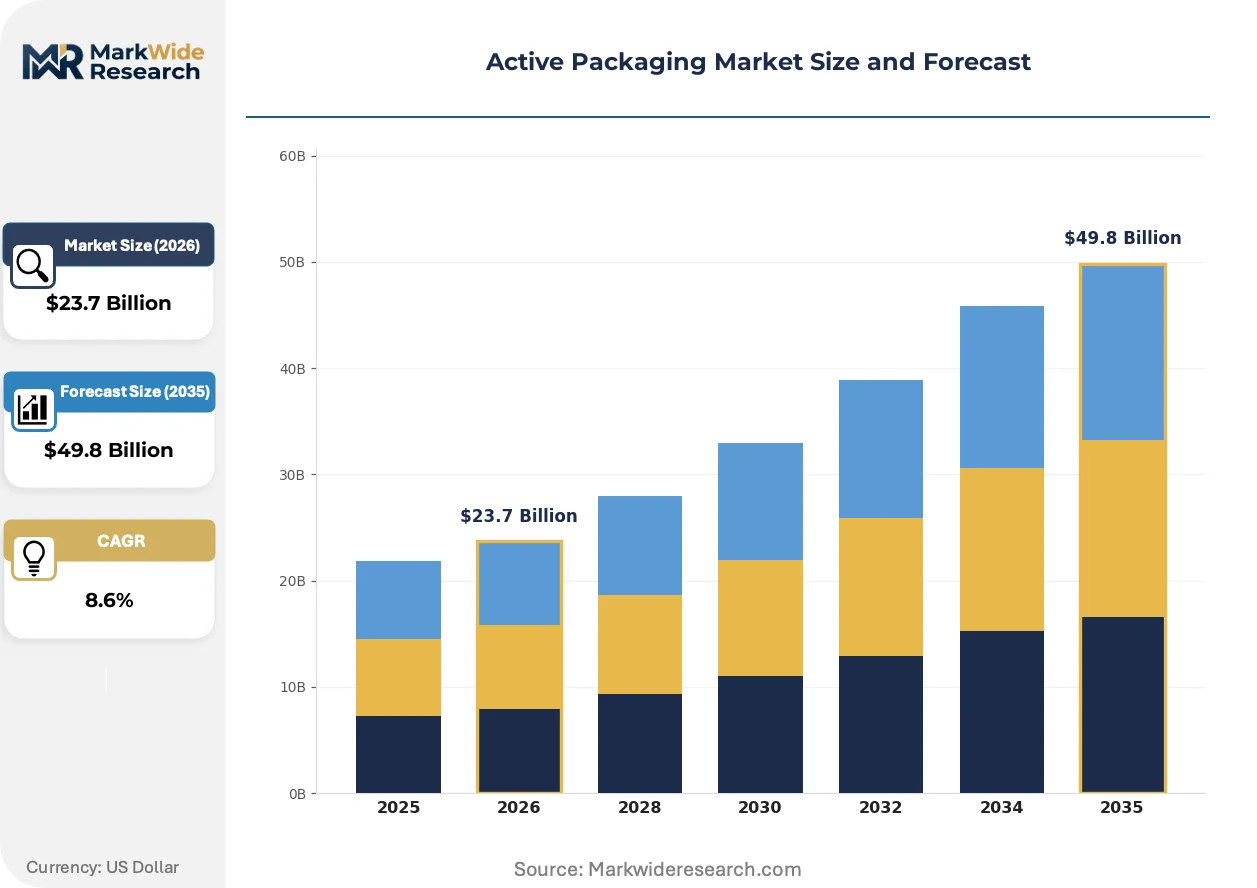
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Scavengers, Ethylene Absorbers, Moisture Control, Antimicrobial Agents End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Material: Plastic, Paper, Metal, Composites Functionality: Contamination Control, Freshness Maintenance, Shelf Life Extension, Flavor Preservation |
| Companies Covered | Avery Dennison Corporation, DowDuPont, Amcor plc, Aptar Group Inc, International Paper, 3M, BASF SE, Stora Enso, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Packaging Market Emerging Trajectories
Controlled-release kinetics engineering is collapsing traditional trade-offs between scavenging capacity and film mechanical integrity, enabling new application geometries that were previously technically inaccessible.
Iron-based oxygen scavenger technology is collapsing the performance gap between passive barrier films and active protection systems. Fresh meat processors in Germany and the Netherlands are adopting these materials at accelerated pace to satisfy retail shelf-life guarantees. The structural consequence is collapsing demand for nitrogen-flush packaging equipment as film-based solutions displace gas-modified atmosphere systems.
REACH authorization requirements for certain phthalate plasticizers are compelling reformulation of adhesive tie-layers in multi-functional laminates. Industrial consequence includes accelerated qualification of bio-based polyester alternatives by converters serving export markets. Pharmaceutical blister packaging operations face the most acute compliance pressure, with some facilities relocating polymer compounding in-house to control substance inventory.
Retail buyer consolidation across European grocery chains is compressing supplier negotiation cycles and unbundling technical validation services from material supply contracts. Protein processors now procure shelf-life testing separately from film sourcing, creating specialized service intermediaries. This pattern is most visible in Germany, where centralized distribution centers demand uniform performance documentation across regional supplier bases.
Active Packaging Market Segmentation
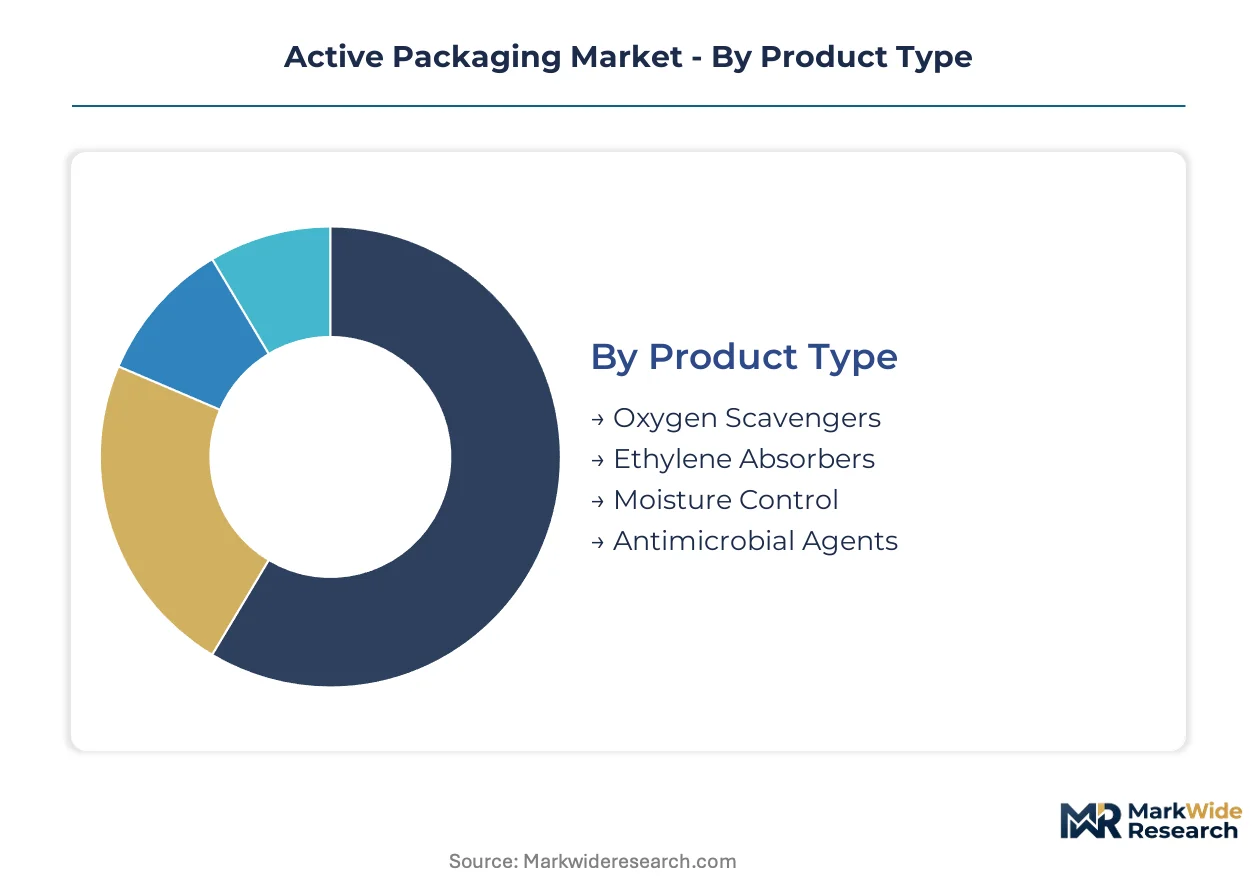
Active packaging segmentation reflects divergent technical validation requirements across end-use verticals. Food & Beverage procurement teams demand shelf-life documentation that pharmaceutical buyers rarely require, while electronics manufacturers prioritize moisture specifications over migration testing protocols.
Product Type:
After-sales technical support intensity varies dramatically by active chemistry, with oxygen scavenger deployments requiring ongoing performance monitoring that antimicrobial formulations rarely need.
- Oxygen Scavengers:Iron-based oxidation chemistries dominate protein packaging applications, with controlled-release kinetics engineered to match specific shelf-life windows. German meat processors are expanding deployment to satisfy centralized retail distribution requirements for validated quality retention.
- Antimicrobial Agents:Organic acid emitters and specialty polymer masterbatches address pharmaceutical cold-chain requirements where temperature excursion risks compound contamination threats. Biologics distributors in the Netherlands are driving qualification timelines as ISO 22000 certification becomes mandatory for multinational procurement.
- Moisture Control:Clay desiccant integration into barrier substrates serves electronics and pharmaceutical segments where humidity sensitivity dictates packaging architecture.
- Ethylene Absorbers:Potassium permanganate-based systems extend ripening control for fresh produce supply chains facing fiber recyclability mandates.
By volume, oxygen scavengers lead. By growth pace, antimicrobial agents are climbing the fastest.
End User:
Application-specific regulatory pathways create distinct margin structures across customer verticals, with pharmaceutical qualification costs far exceeding food-grade certification requirements.
- Food & Beverage:Protein exporters across refrigerated supply chains anchor demand, with shelf-life labeling laws in Germany and the Netherlands forcing documented performance validation. FDA indirect food additive limits under 21 CFR and EFSA notifications shape supplier qualification.
- Pharmaceuticals:Biologics cold-chain expansion drives antimicrobial packaging adoption as temperature excursion requirements tighten. REACH authorization constraints on certain plasticizers are compelling adhesive tie-layer reformulation for blister packaging operations.
- Personal Care:Moisture-sensitive formulations require desiccant integration into primary packaging where aesthetic transparency competes with functional performance.
- Electronics:Humidity indicator cards and scavenger sachets protect semiconductor components through multi-modal distribution channels.
Food & Beverage commands the volume base. Pharmaceuticals generate the steepest margin expansion trajectory.
Material:
Substrate selection increasingly reflects sorting infrastructure constraints rather than pure performance optimization, particularly where mono-material recyclability mandates apply.
- Plastic:Ethylene-vinyl alcohol laminates and polyethylene terephthalate structures sustain volume leadership despite volatility in barrier polymer pricing. The EU Packaging and Packaging Waste Regulation is compressing design cycles toward mono-material alternatives.
- Paper:Molded fiber trays with integrated clay desiccants are gaining structural share in European fresh produce applications where fiber recyclability mandates bypass plastic sorting limitations.
- Metal:Aluminum foil laminates serve high-barrier pharmaceutical applications where oxygen transmission specifications are non-negotiable.
- Composites:Hybrid structures combining plastic barrier layers with paperboard substrates address conflicting performance and sustainability requirements.
Plastic substrates dominate current volume. Paper-based alternatives are expanding most quickly in European regulatory environments.
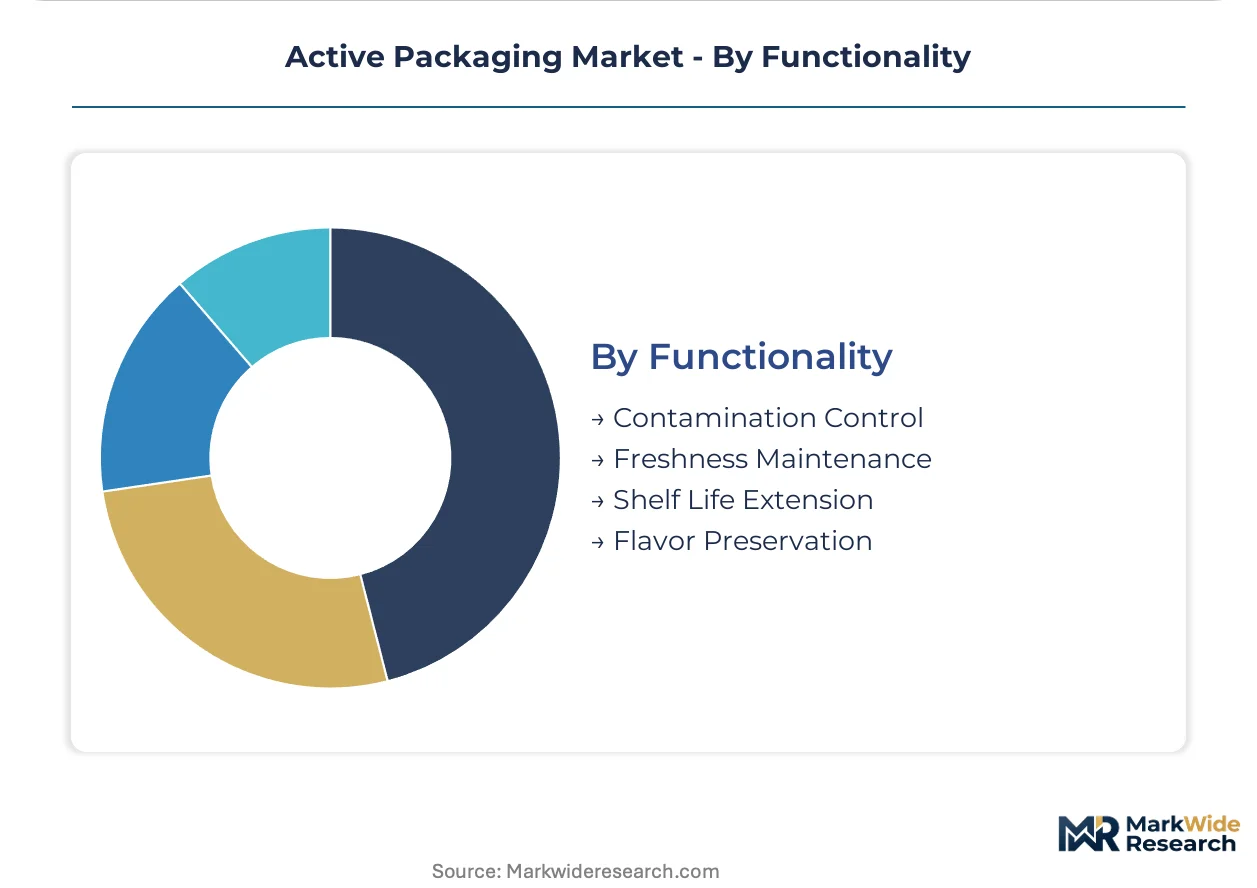
Functionality:
Functional specification priorities diverge by product perishability and regulatory exposure, with contamination control commanding premium positioning in pharmaceutical segments.
- Contamination Control:Antimicrobial and antioxidant chemistries prevent microbial proliferation in protein and pharmaceutical applications. EFSA migration limits and FDA food contact notifications govern allowable substance loadings between 0.5% and 5% by film weight.
- Shelf Life Extension:Oxygen scavenging and moisture absorption technologies reduce spoilage rates across refrigerated supply chains. German retail consolidation is unbundling technical validation services from material supply contracts.
- Freshness Maintenance:Ethylene absorption and humidity buffering preserve organoleptic properties in fresh produce distribution.
- Flavor Preservation:Volatile compound scavenging protects aromatic integrity in coffee, spices, and specialty food segments.
Shelf life extension captures the largest addressable volume. Contamination control is gaining share fastest in pharmaceutical cold-chain applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys active packaging primarily for protein shelf-life validation, while the United States emphasizes pharmaceutical cold-chain compliance and Japan targets precision electronics moisture control. This consumption-mix differential shapes distinct supplier qualification pathways across major demand centers.
United States
Protein exporters and biologics distributors anchor demand for oxygen scavenger films and antimicrobial barrier systems. FDA indirect food additive limits under 21 CFR govern migration testing protocols, extending validation timelines for novel chemistries. The Greater Boston corridor concentrates pharmaceutical packaging operations where ISO 22000 certification opens multinational procurement channels.
Germany
Centralized retail distribution networks generate concentrated pull for intelligent moisture-control solutions with documented performance validation. The EU Packaging and Packaging Waste Regulation compresses design cycles toward mono-material barrier structures that satisfy recyclability mandates. Meat processors in Lower Saxony are expanding iron-based scavenger deployment to satisfy shelf-life labeling laws.
Netherlands
Biologics cold-chain expansion drives antimicrobial packaging adoption as temperature excursion requirements tighten. REACH authorization constraints on certain phthalate plasticizers compel adhesive tie-layer reformulation for blister packaging operations. Rotterdam-Antwerp port logistics clusters concentrate pharmaceutical distribution facilities requiring validated active protection systems.
Japan
Electronics manufacturers prioritize moisture-control specifications for semiconductor component protection through multi-modal distribution channels. METI industrial standards shape barrier polymer qualification requirements for high-value device shipments. The Kanto region around Tokyo anchors precision electronics packaging demand where humidity indicator integration is non-negotiable.
China
Domestic protein processors and emerging pharmaceutical cold-chain operators represent expanding addressable volume for oxygen scavenger and antimicrobial systems. NMPA pharmaceutical packaging regulations and SAMR food contact material standards create dual-track compliance requirements. The Yangtze River Delta concentrates converter operations serving export markets with REACH-aligned formulation capabilities.
Active Packaging Market Vendor Landscape
Capability concentration sits with specialty chemical developers; scale advantage sits with integrated film manufacturers. The market structure tiers between multinational material science conglomerates with captive polymer R&D and regional converters focused on toll coating and lamination. Three archetypes dominate: integrated packaging conglomerates controlling upstream resin supply, specialty chemical suppliers mastering active agent masterbatch formulation, and equipment-integrated film providers leasing machinery to lock in material offtake. Competitive moves center on backward integration into active agent production and strategic partnerships with protein processors for co-developed shelf-life validation protocols.
Within the integrated packaging tier, Amcor plc and Sealed Air Corporation exemplify scale-driven positioning through film manufacturing networks and captive equipment leasing arrangements. Among specialty chemical developers, BASF SE occupies a position representing R&D-intensive masterbatch formulation capabilities. These three anchors demonstrate how competitive positioning splits between material supply integration and functional chemistry specialization.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| DowDuPont |
| Amcor plc |
| Aptar Group Inc |
| International Paper |
| 3M |
| BASF SE |
| Stora Enso |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Ethylene-vinyl alcohol resin price volatility determines both pricing tier spreads and supply chain shape across active packaging markets, compressing margin predictability for converters locked into fixed-price annual contracts while forcing raw material sourcing diversification toward bio-based barrier alternatives.
Pricing Analysis
Long-term offtake agreements dominate oxygen scavenger film procurement between protein exporters and integrated manufacturers, though spot purchasing persists for specialty antimicrobial masterbatches where formulation complexity creates supplier stickiness. Price differentiation hinges on ISO 22000 certification tier and volume scale, with multinational Food & Beverage accounts commanding standard rates while smaller regional processors absorb premium pricing for validated performance documentation. Cost compression in mono-material barrier grades is intensifying because REACH authorization constraints on legacy plasticizers are forcing adhesive reformulation. Pharmaceutical cold-chain buyers exhibit the least price sensitivity, prioritating temperature excursion guarantees over unit economics, whereas fresh produce distributors in Southern Europe remain highly price-sensitive due to thin retail margins.
Supply Chain Analysis
EU F-Gas Regulation restrictions on synthetic barrier chemistries limit technology flows from German and Dutch specialty chemical developers toward converters lacking in-house polymer science capabilities. Active agent masterbatch production concentrates in Germany, Belgium, and Switzerland, with clay desiccant feedstocks drawing from Spanish and Portuguese mineral processors. Single-source vulnerability pervades iron-based oxidation chemistry supply, where capacity constraints at European specialty chemical suppliers create qualification bottlenecks for novel protein packaging deployments. Distribution runs through centralized retail distribution centers in Germany and the Netherlands, with protein processors increasingly unbundling technical validation services from material supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by refrigerated supply chain expansion post-infrastructure investment cycles, with protein exporters and biologics distributors rebuilding active packaging inventories after prior destocking periods.
For Market Incumbents: Build regulatory affairs specialization as a moat against smaller converters lacking simultaneous FDA, EFSA, and member-state notification capabilities. Consolidate backward integration into iron-based oxidation chemistry production to defend against masterbatch supply concentration risks. Expand captive equipment leasing arrangements in North America to lock in material offtake and preempt tolling competitors. For New Entrants and Emerging Players: China's Yangtze River Delta converter cluster offers the most penetrable geography, where NMPA pharmaceutical packaging regulations and SAMR food contact standards create dual-track compliance demand that multinational incumbents serve suboptimally. Target paper-based composite substrates for European fresh produce applications facing fiber recyclability mandates. Pursue co-development partnerships with protein processors for shelf-life validation protocols as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty chemical developers with REACH-aligned formulation capabilities and captive polymer R&D infrastructure. Long-term viability centers on converters controlling upstream active agent production rather than toll coating operations exposed to raw material volatility. Monitor FDA indirect food additive approval timelines for novel chemistries as the critical inflection signal distinguishing scalable platforms from stranded technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Agent Production | Captive supply of iron-based oxidation chemistries insulates converters from European specialty chemical capacity constraints. |
| Mono-Material Barrier Structure Qualification | EU Packaging and Packaging Waste Regulation compliance opens centralized retail distribution channels in Germany. |
| ISO 22000 Certification Investment | Multinational Food & Beverage procurement teams mandate this qualification for oxygen scavenger film suppliers. |
| Co-Developed Shelf-Life Validation Protocols | Protein processors in the Netherlands unbundle technical services from material contracts, creating specialized intermediaries. |
| Pharmaceutical Cold-Chain Partnership Expansion | Biologics distributors in Greater Boston demand antimicrobial packaging as temperature excursion requirements tighten. |
Methodological Framework
Desk research of EU regulatory filings, FDA indirect food additive petitions, and specialty chemical trade association reports preceded structured interviews with film converter plant managers, protein processor procurement leads, pharmaceutical packaging engineers, and retail category buyers. Primary fieldwork combined telephone interviews and facility observations across German meat processing clusters and Rotterdam-Antwerp pharmaceutical distribution hubs. Secondary validation drew from ECHA REACH authorization databases, EFSA scientific opinions, and customs trade data for ethylene-vinyl alcohol resin flows. Bottom-up unit economics for oxygen scavenger film production were triangulated against top-down market sizing from end-use demand aggregation.
Assumptions held fixed include current EU Packaging and Packaging Waste Regulation recyclability mandates, FDA migration limits under 21 CFR, and ISO 22000 certification requirements for multinational procurement qualification across the analysis window. Variables included ethylene-vinyl alcohol resin price trajectories, REACH authorization timelines for phthalate plasticizer alternatives, and the pace of paper-based composite substrate adoption in European fresh produce. Segmentation modeling spanned product type (oxygen scavengers, antimicrobial agents, moisture control, ethylene absorbers), end-use vertical (Food & Beverage, pharmaceuticals, electronics), material substrate (plastic, paper, metal, composites), and functionality (contamination control, shelf life extension, freshness maintenance). CAGRs were derived from regression analysis against protein export volumes, pharmaceutical cold-chain infrastructure investment, and refrigerated supply chain mileage expansion.
Practitioners should monitor FDA novel food contact substance notification approval delays, EU F-Gas Regulation expansion to additional synthetic barrier chemistries, and German retail buyer consolidation patterns for early signals requiring forecast revision. Material shifts in REACH authorization scope for active packaging additives or sudden ethylene-vinyl alcohol supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market