
 United Arab Emirates Packaging Market | 2026-2036
United Arab Emirates Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Packaging Market Analytics
Multi-source procurement among food and beverage manufacturers is expanding as brands diversify supplier bases beyond single-origin plastic film contracts. Hotpack Packaging Industries LLC leverages its domestic manufacturing footprint to sustain rapid fulfillment cycles for hospitality and retail clients. Amcor plc anchors premium flexible packaging demand through advanced barrier film technologies. Gulf East Paper and Plastic Industries LLC competes aggressively in corrugated segments serving Jebel Ali's logistics tenants.
Packaging in the UAE context encompasses protective and promotional enclosures manufactured from plastic resins, paperboard, aluminum alloys, or silica-based glass, typically specified by barrier properties, tensile strength, and shelf-life extension parameters designed to preserve product integrity across desert-climate supply chains. Flexible packaging dominates value pools in food and beverage applications where lightweight, heat-sealable laminates reduce freight costs. Rigid packaging retains structural importance in pharmaceuticals, where MOHAP mandates child-resistant closures and moisture barriers for temperature-sensitive formulations. Paper-based formats are gaining share in e-commerce end-user channels as brands respond to consumer preference shifts.
MOHAP governs food-contact safety and pharmaceutical packaging standards, while the Emirates Authority for Standardization and Metrology (ESMA) administers technical regulations for biodegradable and compostable material claims. ESMA's UAE System for Conformity Assessment imposes pre-market certification that filters out non-compliant imports and elevates quality benchmarks. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in local recycling infrastructure or secure certified recyclable supply agreements.
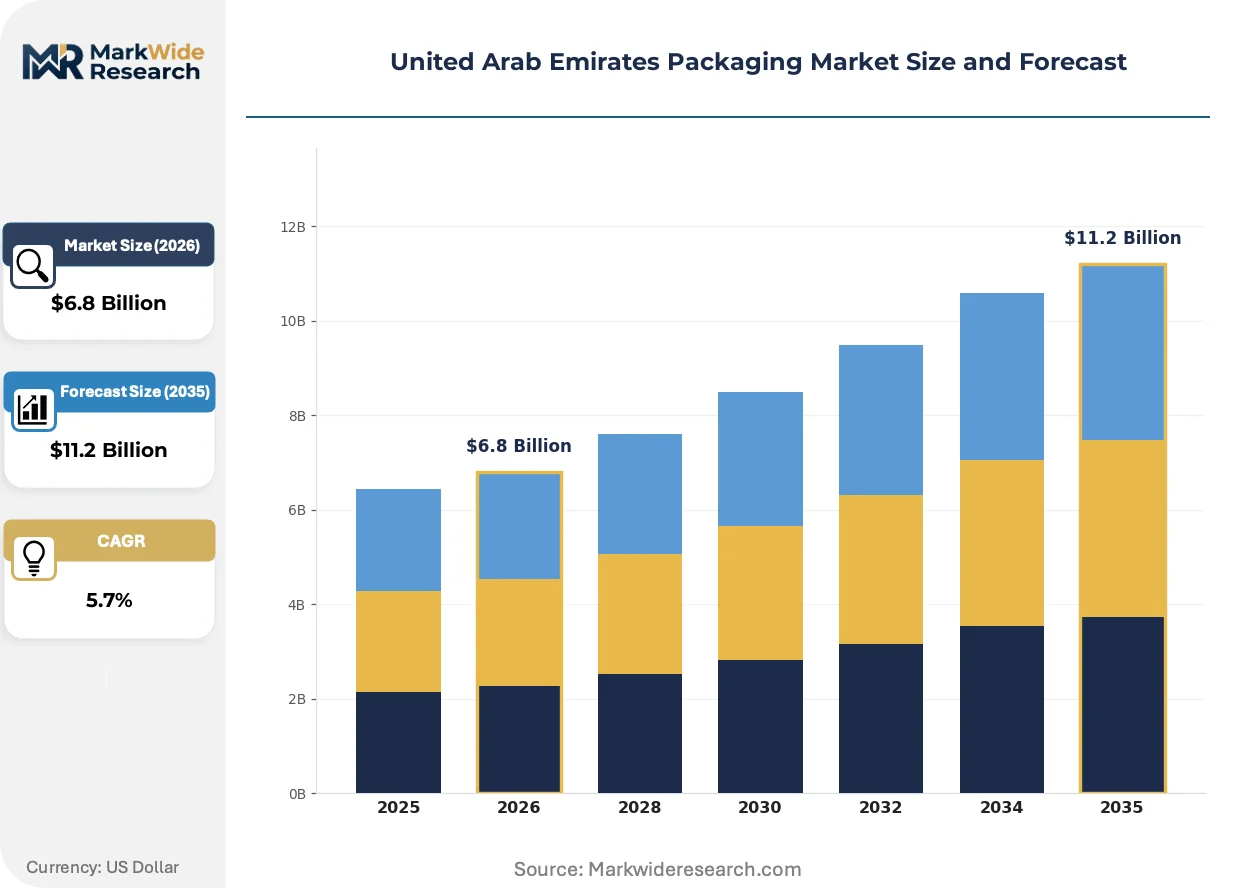
Market Dynamics
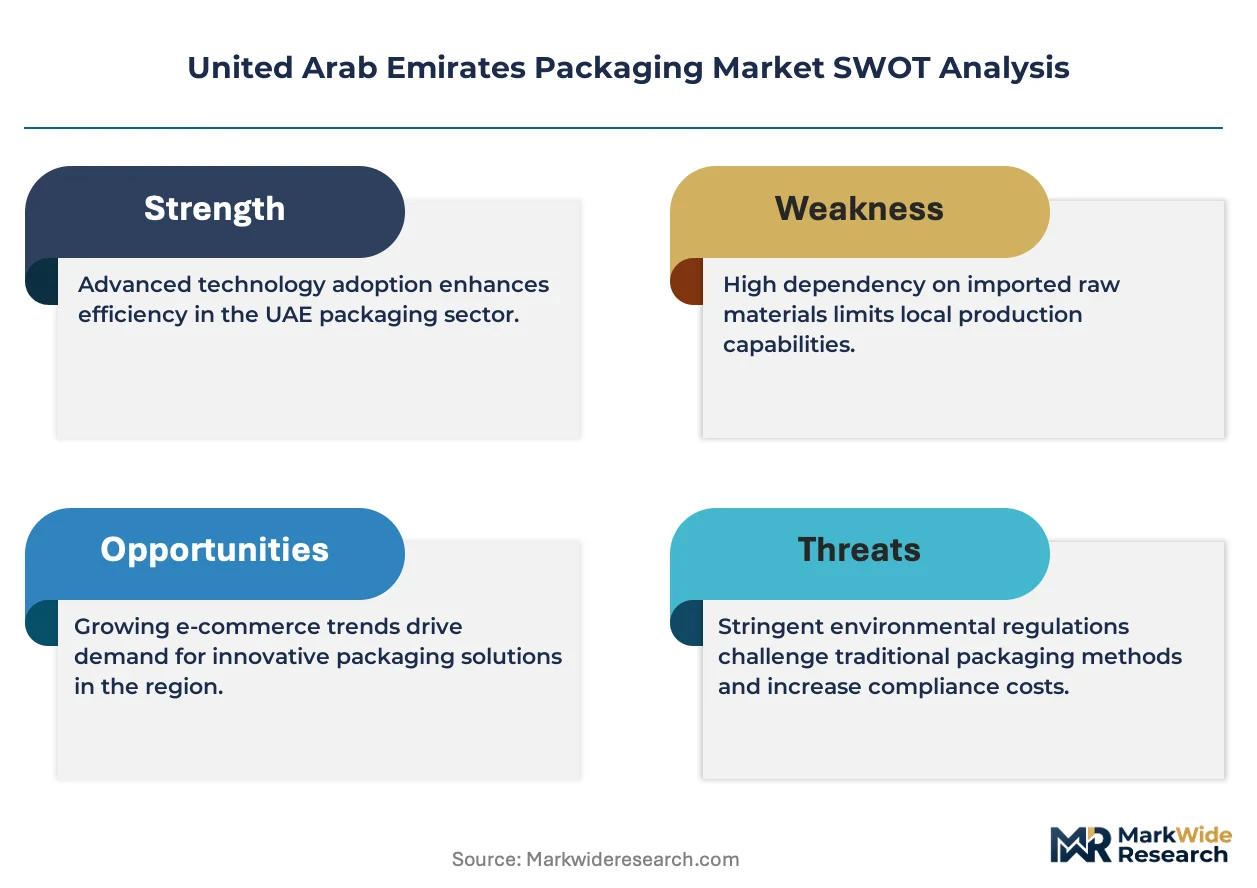
E-commerce fulfillment centers in Dubai and Abu Dhabi are compressing order-to-delivery windows, forcing packaging specifications toward lightweight corrugated and flexible formats that minimize dimensional weight charges while surviving desert-climate logistics.
Growth Catalysts
- MOHAP Food-Contact Standards:Tightened compliance requirements for importers are filtering out substandard suppliers and elevating quality benchmarks across food and beverage packaging procurement.
- Jebel Ali Logistics Cluster:Concentrated warehousing and manufacturing tenants in Dubai's industrial corridor generate bulk procurement demand for protective packaging formats.
- Barrier Film Technology:Advanced multilayer laminates with oxygen and moisture resistance are extending shelf life for temperature-sensitive pharmaceuticals and perishables.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices track regional oil benchmarks, compressing margin predictability for domestic converters.
- Single-Origin Import Dependence:Limited local polymer production forces reliance on Saudi Arabian and Qatari resin suppliers, concentrating supply risk.
- ESMA Pre-Market Certification:The UAE System for Conformity Assessment imposes documentation burdens that delay product launches for biodegradable material claims.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:Pending regulations around packaging waste accountability will reward early investors in closed-loop recycling infrastructure.
- Hospitality Sector Premiumization:Hotels and foodservice operators in Dubai are specifying branded, sustainable packaging as guest-experience differentiators.
- Digital Printing Convergence:Integration of inkjet systems with flexible film lines enables short-run customization for promotional campaigns.
Industry Challenges
- Retrofitting Legacy Extrusion Lines:Converting equipment for recyclable mono-material structures requires capital outlays that mid-scale converters struggle to finance.
- MOHAP Pharmaceutical Certification Timelines:Child-resistant closure testing and moisture-barrier validation extend product approval cycles for temperature-sensitive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Labeling, Pouches Material: Plastic, Paper, Metal, Glass Application: Food & Beverage, Pharmaceuticals, Personal Care, Consumer Goods End User: Retail, E-commerce, Manufacturing, Healthcare |
| Companies Covered | Tetra Pak International, Hotpack Packaging Industries LLC, Amcor plc, Mondi plc, Gulf East Paper and Plastic Industries LLC, Arabian Packaging LLC, Amber Packaging Industries LLC, Al Bayader International LLC, ENPI Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Packaging Market Evolving Landscape
Active and intelligent packaging systems are penetrating UAE supply chains as brands compete on freshness assurance and supply-chain transparency. Three developments are compressing traditional specification norms.
Smart labels embedded with time-temperature indicators are electrifying quality assurance protocols for cold-chain pharmaceuticals and premium perishables. Pharmaceutical distributors in Dubai Healthcare City are mandating these sensors for insulin and biologic shipments. The technology is compressing insurance liability exposure while enabling real-time intervention before product degradation occurs.
ESMA's technical regulations for biodegradable claims are tightening material certification requirements across flexible packaging imports. The framework now mandates third-party compostability verification for products marketed as environmentally preferable. Food and beverage brands sourcing films are reformulating toward certified home-compostable structures to preempt enforcement actions.
Direct-to-consumer subscription models are fragmenting order profiles and compressing minimum order quantities for packaging suppliers. Beauty and wellness brands operating from Dubai Internet City are specifying digitally printed folding cartons in runs below five thousand units. This behavior is visible most acutely among venture-backed startups prioritizing unboxing experience over unit cost minimization.
United Arab Emirates Packaging Market Segmentation
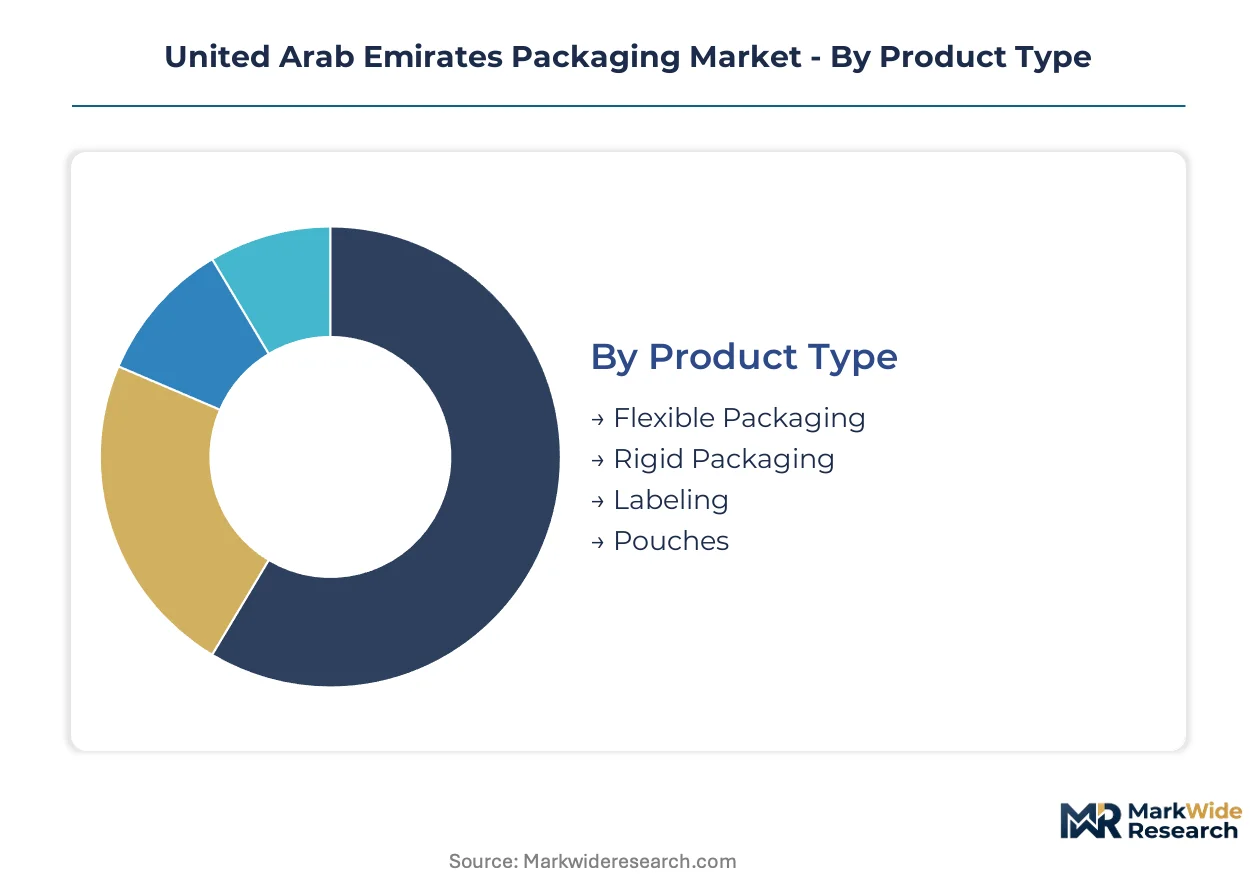
Packaging procurement patterns across the Emirates diverge sharply by product protection requirements, climate resilience specifications, and channel-specific fulfillment speeds. Segment boundaries are hardening as MOHAP compliance tiers and ESMA certification pathways filter supplier capabilities.
Product Type:
Upgrade cycles favor formats that reduce dimensional weight charges while surviving desert-climate logistics stressors.
- Flexible Packaging:Multilayer laminates and heat-sealable films dominate food and beverage applications where freight cost minimization drives specification. Dubai's Jebel Ali logistics tenants are consolidating procurement around oxygen-barrier structures for perishable imports. MOHAP's tightened food-contact standards are filtering out non-compliant film imports.
- Rigid Packaging:Injection-molded containers and thermoformed trays retain structural importance in pharmaceutical distribution where child-resistant closures are mandatory. Abu Dhabi's healthcare cluster generates concentrated demand for moisture-barrier vials and blister packs. Certification timelines for temperature-sensitive formulations extend procurement cycles.
- Labeling:Pressure-sensitive and shrink-sleeve formats serve branding and regulatory compliance functions across retail channels.
- Pouches:Stand-up and spouted structures are gaining share in personal care and convenience food segments.
Volume placements concentrate in flexible formats; the faster expansion belongs to rigid pharmaceutical-grade structures.
Material:
Cost tiers separate petrochemical-derived inputs from fiber-based alternatives responding to hospitality sector premiumization.
- Plastic:Polypropylene and polyethylene resins anchor flexible film and rigid container production, though feedstock volatility tied to regional oil benchmarks compresses margin predictability. Limited local polymer production forces reliance on Saudi Arabian and Qatari suppliers.
- Paper:Corrugated board and folding cartons are capturing e-commerce channel share as brands respond to consumer preference shifts. Dubai Internet City startups specify digitally printed cartons in sub-five-thousand-unit runs for unboxing differentiation.
- Metal:Aluminum alloys serve aerosol and barrier applications in personal care.
- Glass:Silica-based containers retain premium positioning in beverage and pharmaceutical segments.
Plastic retains volume dominance; paper is climbing the fastest on e-commerce penetration.
Application:
Application-level procurement intensity tracks perishability risk and regulatory scrutiny depth.
- Food & Beverage:Barrier film specifications and shelf-life extension parameters dominate procurement conversations. ESMA's compostability verification requirements are reformulating supplier selection criteria toward certified home-compostable structures.
- Pharmaceuticals:MOHAP-mandated moisture barriers and temperature validation protocols elevate technical qualification thresholds. Dubai Healthcare City distributors are mandating time-temperature indicator integration for insulin and biologic shipments.
- Personal Care:Branded packaging serves guest-experience differentiation for hospitality operators.
- Consumer Goods:Protective formats balance unit cost against damage rate minimization.
Food and beverage anchors procurement volume; pharmaceuticals show the steepest expansion trajectory on cold-chain infrastructure buildout.
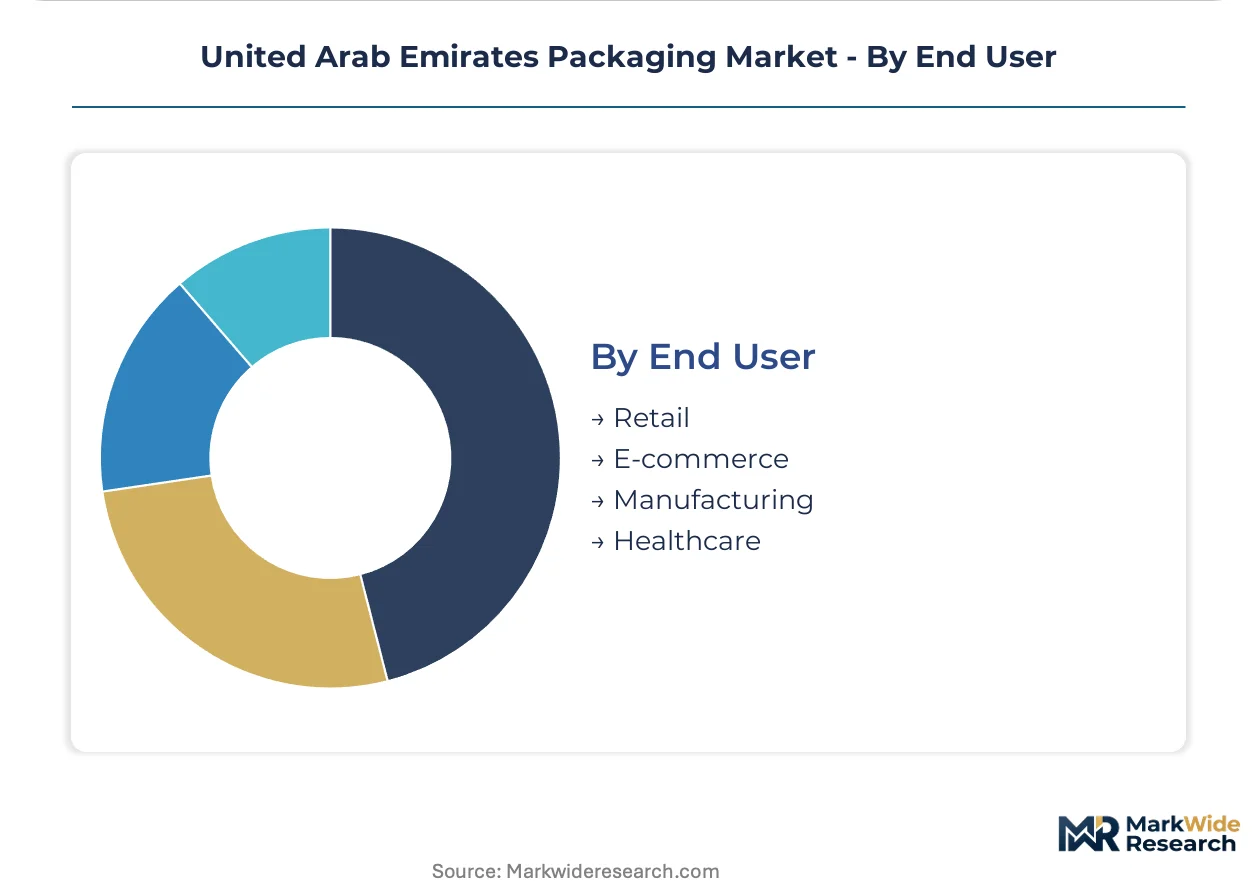
End User:
Customer type determines order profile fragmentation and minimum quantity flexibility.
- Retail:Hypermarket and supermarket chains generate bulk, standardized procurement with long-term contract structures.
- E-commerce:Fulfillment centers in Dubai and Abu Dhabi are compressing order-to-delivery windows, forcing specifications toward lightweight corrugated and flexible formats. Subscription model fragmentation is pushing digitally printed short runs.
- Manufacturing:Industrial tenants in Jebel Ali anchor protective packaging demand for inbound component and outbound finished goods flows.
- Healthcare:Hospital and pharmacy networks drive pharmaceutical-grade packaging qualification volumes.
Manufacturing and retail concentrate legacy volume; e-commerce is gaining share fastest on fulfillment infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging procurement across the Emirates clusters in four distinct economic zones, each shaped by sector-specific demand drivers and regulatory enforcement intensity. Dubai and Abu Dhabi concentrate the majority of logistics infrastructure and manufacturing capacity.
Dubai
Jebel Ali's logistics corridor anchors bulk corrugated and flexible film procurement for warehousing and e-commerce fulfillment operations. MOHAP's food-contact material standards filter supplier qualifications for importers operating through the emirate's free zones. Dubai Internet City startups are compressing minimum order quantities for digitally printed folding cartons.
Abu Dhabi
KIZAD industrial zone tenants generate protective packaging demand for petrochemical and aluminum sector outbound shipments. The emirate's healthcare cluster drives pharmaceutical-grade rigid container qualification volumes under MOHAP temperature-validation protocols. Abu Dhabi Ports logistics infrastructure supports cold-chain packaging specifications for temperature-sensitive imports.
Sharjah
Hamriyah Free Zone converters serve mid-scale food and beverage manufacturers with flexible film and labeling formats. ESMA's pre-market certification requirements for biodegradable claims extend product launch timelines for Sharjah-based importers. The emirate's industrial areas concentrate lower-cost corrugated production for domestic distribution.
Northern Emirates
Ras Al Khaimah and Fujairah manufacturing zones attract packaging converters seeking lower operational costs outside Dubai-Abu Dhabi rent corridors. Limited logistics connectivity restricts these zones to standardized bulk formats rather than customized short-run production. Federal environmental regulations are beginning to filter waste management accountability to Northern Emirates industrial tenants.
United Arab Emirates Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic converters retrofit extrusion lines for recyclable mono-material structures. The vendor base spans three tiers: multinational film specialists with barrier technology portfolios, mid-scale regional converters leveraging geographic proximity, and local corrugated producers serving Jebel Ali logistics clusters. Strategic archetypes include premium flexible film licensors, vertically integrated paperboard converters, and hospitality-focused short-run specialists. M&A activity and strategic partnerships concentrate around technology transfer agreements for active packaging systems.
Among UAE-based converters, Hotpack Packaging Industries LLC and Gulf East Paper and Plastic Industries LLC exemplify the mid-scale regional archetype, while Amcor plc occupies a position representing multinational barrier film specialization. Tetra Pak International anchors aseptic carton technology licensing within the premium tier, and Mondi plc exemplifies integrated paperboard and flexible film capabilities. Arabian Packaging LLC and Al Bayader International LLC sit within the hospitality and retail supply segment, serving shorter fulfillment cycles for Dubai and Abu Dhabi foodservice operators.
| Leading Market Players |
|---|
| Tetra Pak International |
| Hotpack Packaging Industries LLC |
| Amcor plc |
| Mondi plc |
| Gulf East Paper and Plastic Industries LLC |
| Arabian Packaging LLC |
| Amber Packaging Industries LLC |
| Al Bayader International LLC |
| ENPI Group |
| Others |
Value Network & Pricing Analysis
Extrusion technician density in Sharjah's Hamriyah Free Zone compresses labor-cost differentials, widening pricing spreads between premium barrier-film tiers and economy-grade corrugated alternatives. MOHAP certification requirements and ESMA pre-market documentation burdens concentrate value capture among converters with in-house compliance teams, while mid-scale competitors absorb margin erosion through unfavorable resin procurement terms.
Pricing Analysis
Warranty and technical service bundling separates premium flexible film suppliers from transactional corrugated vendors serving Jebel Ali logistics tenants. Three-tier pricing structure across premium, standard, and economy levels tracks MOHAP food-contact certification tiers and barrier performance specifications. Pricing pressure stems from petrochemical feedstock volatility tied to Saudi Arabian and Qatari resin benchmarks, compressing predictability for domestic converters. E-commerce fulfillment centers exhibit highest price sensitivity on dimensional weight-optimized formats, while pharmaceutical distributors prioritize moisture-barrier validation over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for corrugated board collection remains underdeveloped across Dubai and Abu Dhabi industrial zones, limiting closed-loop recycling economics. Raw material supply concentrates in Saudi Arabia and Qatar for polypropylene and polyethylene resins, with India and China anchoring specialty film and equipment imports. Supply chain risk centers on single-source polymer dependence and tariff exposure on Chinese converting machinery. Distribution runs through Jebel Ali free zone warehousing clusters, with final-mile fulfillment compressing order-to-delivery windows for e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE packaging market functions as a supply-constrained environment where certified converter capacity bottlenecks prop pricing power for compliant incumbents. Local resin production deficits and extended MOHAP approval timelines restrict rapid capacity scaling.
For Market Incumbents: Deepen backward integration into Saudi Arabian resin supply agreements to secure feedstock priority during regional petrochemical volatility. Expand barrier-film R&D investment targeting pharmaceutical cold-chain applications, defending against Gulf East Paper and Plastic Industries LLC's corrugated expansion. Lock in long-term contracts with Dubai Healthcare City distributors before ESMA's extended producer responsibility frameworks elevate compliance costs for smaller competitors.
For New Entrants and Emerging Players: The mid-tier price-point gap between Amcor plc's premium laminates and Hamriyah Free Zone economy producers creates white-space opportunity in certified home-compostable flexible films. Target Northern Emirates manufacturing zones where lower operational costs offset logistics connectivity limitations. Pursue digital printing convergence for sub-five-thousand-unit folding carton runs serving Dubai Internet City subscription brands, leveraging short-run flexibility as entry wedge.
For Investors and Strategic Acquirers: The window for entry favors mid-scale converters with existing ESMA certification infrastructure and Jebel Ali logistics corridor proximity. Acquisition targets should demonstrate established MOHAP pharmaceutical packaging qualification timelines and relationships with KIZAD petrochemical tenants. Monitor ESMA enforcement actions on biodegradable material claims as inflection signal for compliant capacity scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene sourcing from Saudi Arabian producers insulates margin compression during oil benchmark volatility. |
| ESMA Certification Infrastructure Buildout | Pre-market conformity assessment capability accelerates product launches for biodegradable flexible film claims. |
| Digital Printing Line Integration | Inkjet-flexible film convergence enables short-run customization for Dubai Internet City direct-to-consumer brands. |
| Pharmaceutical Cold-Chain Partnership | Time-temperature indicator integration with Dubai Healthcare City distributors secures insulin and biologic packaging mandates. |
| Northern Emirates Capacity Expansion | Ras Al Khaimah manufacturing footprint captures cost advantages outside Dubai-Abu Dhabi rent corridors for standardized bulk formats. |
Research Methodology
Document review covered MOHAP regulatory filings, ESMA technical regulations, customs and trade data from UAE Federal Customs Authority, and SEC disclosures from multinational packaging parents, complemented by interviews with plant managers at Jebel Ali corridor converters, procurement leads at Dubai Healthcare City pharmaceutical distributors, hospitality sector packaging specification officers, and corrugated production heads at Sharjah free zone operators. Secondary validation drew from Emirates Authority for Standardization and Metrology certification databases, Gulf petrochemical producer supply disclosures, and e-commerce fulfillment center infrastructure reports. Bottom-up demand modeling triangulated against top-down macroeconomic projections across the analysis window.
Cross-referencing historical volume trajectories with expert panel input on MOHAP compliance timeline evolution shaped the analytical framework. Segmentation dimensions modeled include product type, material grade tier, application sector, and end-user channel across the projection horizon. CAGRs derived from regression analysis of import volume trends and domestic production capacity utilization, incorporating pharmaceutical cold-chain infrastructure buildout rates and e-commerce fulfillment center expansion schedules as industry-specific forecast inputs.
Inputs from MOHAP regulatory update releases and ESMA certification registries were available through the study window; gaps in real-time resin price transmission data from Saudi Arabian and Qatari suppliers introduce uncertainty bands around converter margin projections. Forecasts reflect documented assumptions on petrochemical feedstock correlation stability and certification timeline continuity. Practitioners should monitor ESMA enforcement action frequency and extended producer responsibility framework progression for early signals of compliant capacity scarcity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market