
 Global Controlled Intelligent Packaging Market | 2026-2036
Global Controlled Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Controlled Intelligent Packaging Market Analysis
Asset-light leasing models for RFID-enabled packaging systems are reshaping competitive entry barriers for mid-sized pharmaceutical distributors. Amcor plc leverages its integrated film manufacturing network to sustain cost leadership in intelligent barrier substrates. Avery Dennison Corporation anchors the smart-label segment through proprietary inlay production capabilities that reduce third-party dependency.
Controlled intelligent packaging integrates active or responsive materials—oxygen scavengers, moisture regulators, time-temperature indicators, and printed electronics—into primary or secondary packaging to monitor, communicate, or modify internal conditions in real time. These systems typically incorporate RFID inlays operating at 860–960 MHz UHF or 13.56 MHz HF bands, coupled with sensor films measuring parameters between −30°C and 60°C for cold-chain validation. Smart Labels dominate current deployment volumes due to their retrofit compatibility with existing carton and pallet formats, while Sensors command premium margins as pharmaceutical-grade multi-parameter loggers replace disposable chemical indicators. Intelligent Films represent the fastest-growing structural category, driven by roll-to-roll printed electronics that embed NFC antennas directly onto flexible substrates for unit-level traceability.
The FDA Drug Supply Chain Security Act and EU Falsified Medicines Directive enforce unit-level serialization that directly expands demand for track-and-trace smart labels in transatlantic pharmaceutical corridors. REACH restrictions on certain chromic indicator chemicals are accelerating migration to electronic time-temperature sensors across European supply chains. Stakeholders must evaluate whether backward integration into sensor chip sourcing or partnerships with semiconductor foundries offers more durable cost control as silicon supply tightens.
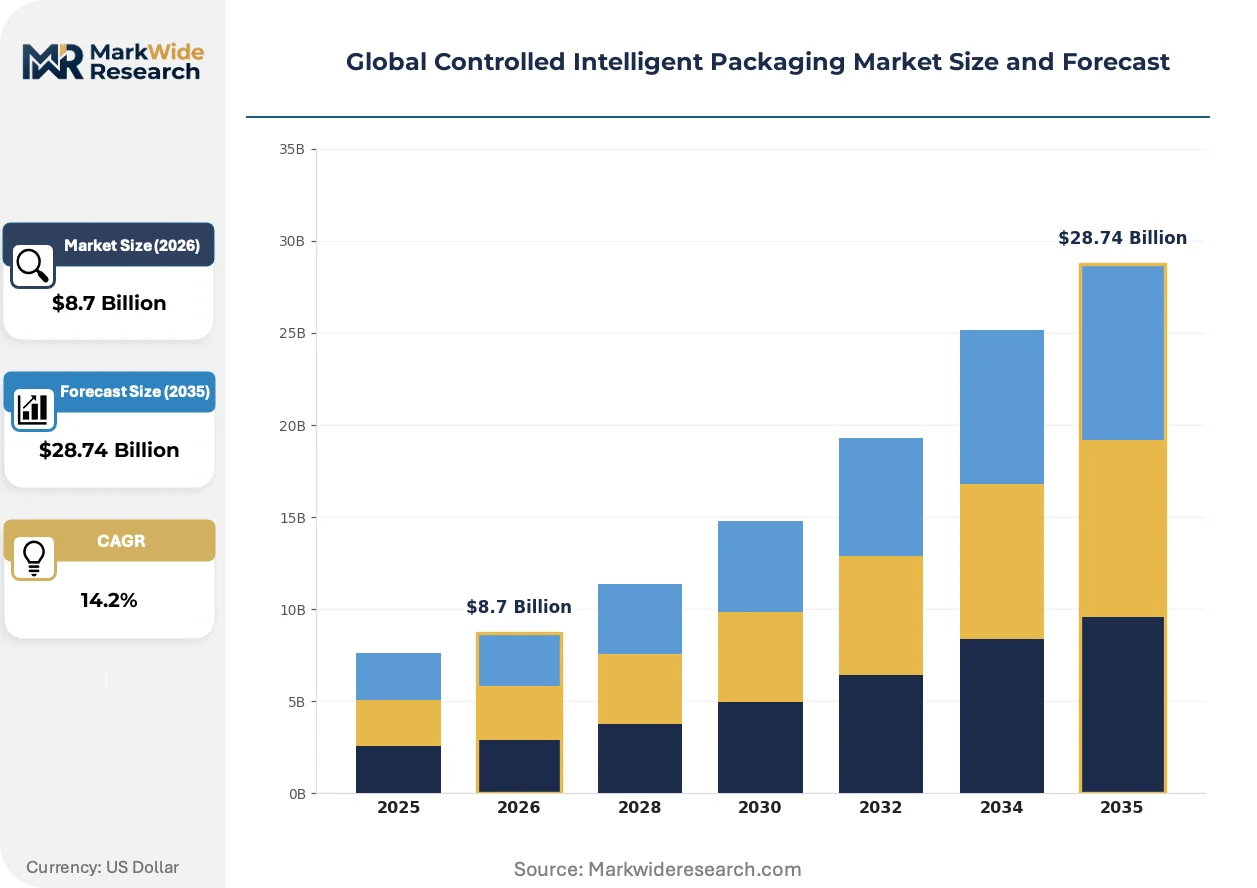
Market Dynamics
Pharmaceutical serialization mandates are compressing deployment timelines for track-and-trace infrastructure, forcing packaging converters to choose between captive sensor production and foundry partnerships before silicon supply tightens further.
Growth Catalysts
- FDA DSCSA unit-level serialization:The 2023 enforcement deadline for prescription drug traceability is pulling RFID-enabled cartons and aggregation systems into wholesale distribution networks across the United States.
- Cold-chain integrity failures in biologics:Temperature excursions during COVID-19 vaccine distribution exposed gaps in chemical indicator reliability, accelerating electronic logger adoption for gene therapies and mRNA products.
- EU MDR device traceability expansion:Medical device unique device identification requirements are extending intelligent packaging demand beyond pharmaceuticals into sterile barrier systems for implants and surgical instruments.
Market Restraints
- Silicon wafer supply concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node production for NFC and UHF sensor chips, creating single-source vulnerability for packaging integrators.
- REACH substance restrictions:ECHA classification of certain chromic dyes as substances of very high concern is forcing reformulation of visual temperature indicators before electronic alternatives achieve cost parity.
- Flexible printed circuit yield rates:Roll-to-roll antenna printing on polymer substrates suffers 15-20% defect rates at commercial scale, constraining intelligent film throughput below demand growth.
Strategic Opportunities
- India pharmaceutical export corridor:CDSCO alignment with WHO prequalification standards is creating first-mover advantage for serialization-ready packaging in generic drug shipments to Africa and Southeast Asia.
- Reusable sensor leasing models:Asset-light subscription structures for multi-trip data loggers are lowering entry barriers for mid-sized 3PLs serving temperature-sensitive agriculture and specialty chemicals.
- NFC-Blockchain convergence:Integration of near-field communication tags with distributed ledger verification is opening anti-counterfeiting applications for high-value spirits and luxury cosmetics.
Industry Challenges
- Serialized packaging engineer scarcity:Cross-functional expertise spanning RFID physics, pharmaceutical regulations, and line integration is concentrated among fewer than 200 specialists globally, inflating implementation timelines.
- Legacy warehouse management system retrofitting:ERP platforms lacking EPCIS 2.0 event capture capabilities require middleware development, delaying pharma distributor onboarding by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Controlled Intelligent Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Labels, Smart Containers, Intelligent Films, Sensors Technology: RFID, NFC, QR Codes, Blockchain End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Application: Supply Chain Management, Inventory Tracking, Quality Assurance, Anti-Counterfeiting |
| Companies Covered | Amcor plc, Avery Dennison Corporation, Sealed Air Corporation, 3M Company, Huhtamaki Oyj, Mondi Group, Ball Corporation, BASF SE, PakSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Controlled Intelligent Packaging Market Emerging Trajectories
Printed electronics manufacturing is collapsing the cost curve for unit-level intelligence, enabling sensor migration from pallet to primary package while computational packaging architectures rewrite hardware-software boundaries.
Printed NFC antennas on biodegradable cellulose substrates are virtualizing the traditional smart label supply chain by eliminating etched copper inlay dependency. European cosmetic brands piloting these films for refillable packaging report 40% reduction in embedded electronics mass. The technology is virtualizing hardware authentication into software-verifiable digital twins, compressing anti-counterfeiting system deployment from months to weeks.
REACH authorization requirements for cobalt dichloride-based humidity indicators are forcing migration to conductive polymer sensors across European pharmaceutical packaging. ECHA's 2024 sunset date for legacy chromic technologies is accelerating electronic alternatives in moisture-sensitive drug formulations. German and French contract packagers are prioritizing capacitive humidity loggers to maintain CE-marked barrier system compliance.
Subscription-based sensor recovery programs are displacing single-use chemical indicators in temperature-controlled logistics. Large pharmaceutical 3PLs in the United States now specify returnable data loggers with cloud analytics dashboards, unbundling hardware from software service fees. This procurement model shift is most visible in California and Massachusetts biotech clusters where sustainability metrics factor directly into vendor scorecards.
Global Controlled Intelligent Packaging Market Segmentation
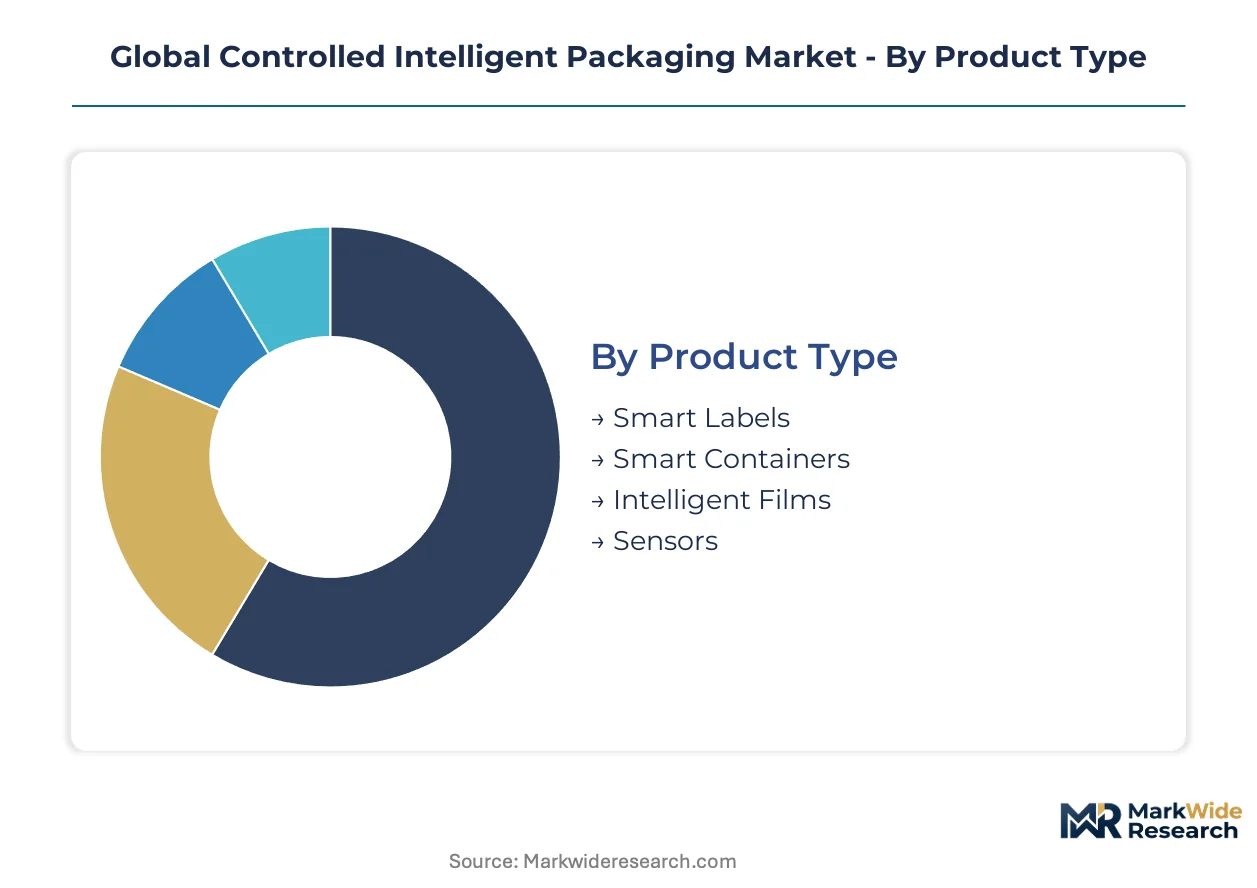
Segmentation in controlled intelligent packaging reveals divergent service intensity requirements across hardware categories. Product complexity dictates aftermarket support models, with sensor-enabled systems demanding calibration services that smart labels rarely require.
Product Type:
After-sales service intensity varies dramatically across product categories, with multi-parameter sensors requiring field calibration and cloud analytics subscriptions that passive labels never need.
- Smart Labels:Printed electronics on paper or synthetic substrates embed RFID inlays or NFC antennas for unit-level identification. Pharmaceutical distributors in Germany and the United States retrofit existing carton lines with these labels to meet FDA DSCSA and EU Falsified Medicines Directive serialization mandates without capital-intensive line replacement.
- Sensors:Electronic data loggers measure temperature, humidity, shock, and light exposure across −30°C to 60°C ranges with ±0.5°C accuracy. Cold-chain logistics providers serving mRNA biologics in Massachusetts and California specify these devices with cloud dashboard subscriptions, creating recurring revenue streams that chemical indicators cannot match.
- Smart Containers:Reusable totes and pallets integrate active RFID tags with environmental monitoring for multi-trip pharmaceutical distribution. Return logistics networks in the Benelux region recover these assets from hospital pharmacies.
- Intelligent Films:Roll-to-roll printed electronics embed sensing circuits directly onto flexible barrier substrates. Biodegradable cellulose variants eliminate copper inlay dependency for European cosmetic refill programs.
By volume, Smart Labels leads. By growth pace, Intelligent Films is ahead.
Technology:
Cost tier differentiation separates high-performance active systems from passive alternatives, with semiconductor content driving price stratification.
- RFID:UHF 860–960 MHz systems enable 10-meter read ranges for pallet-level aggregation in warehouse environments. Wholesale pharmaceutical distributors deploy these for EPCIS 2.0 event capture compliance.
- NFC:13.56 MHz HF protocols support smartphone-readable authentication without dedicated infrastructure. Luxury spirits brands in France pilot NFC-Blockchain convergence for anti-counterfeiting verification.
- QR Codes:Optical 2D barcodes provide lowest-cost entry for generic drug exporters in India meeting WHO prequalification traceability requirements.
- Blockchain:Distributed ledger verification creates immutable custody records for high-value pharmaceutical shipments. Integration complexity limits deployment to premium product categories.
RFID dominates shipment value. NFC expands most quickly in consumer-facing applications.
End User:
Application maturity separates regulated pharmaceutical deployments from emerging cosmetic and electronics adoption.
- Pharmaceuticals:Serialization mandates drive track-and-trace infrastructure investment. Gene therapy cold chains specify electronic loggers after COVID-19 vaccine distribution exposed chemical indicator failures.
- Food & Beverage:Temperature monitoring for fresh produce and protein shipments. Subscription-based sensor recovery programs displace single-use indicators in California agricultural logistics.
- Cosmetics:Anti-counterfeiting and refill authentication for premium skincare. REACH restrictions on chromic dyes accelerate electronic alternatives in German and French contract packaging.
- Electronics:Humidity and shock monitoring for semiconductor and component shipments. Moisture-sensitive device packaging drives capacitive sensor adoption.
Pharmaceuticals commands highest unit value. Cosmetics shows steepest expansion trajectory.
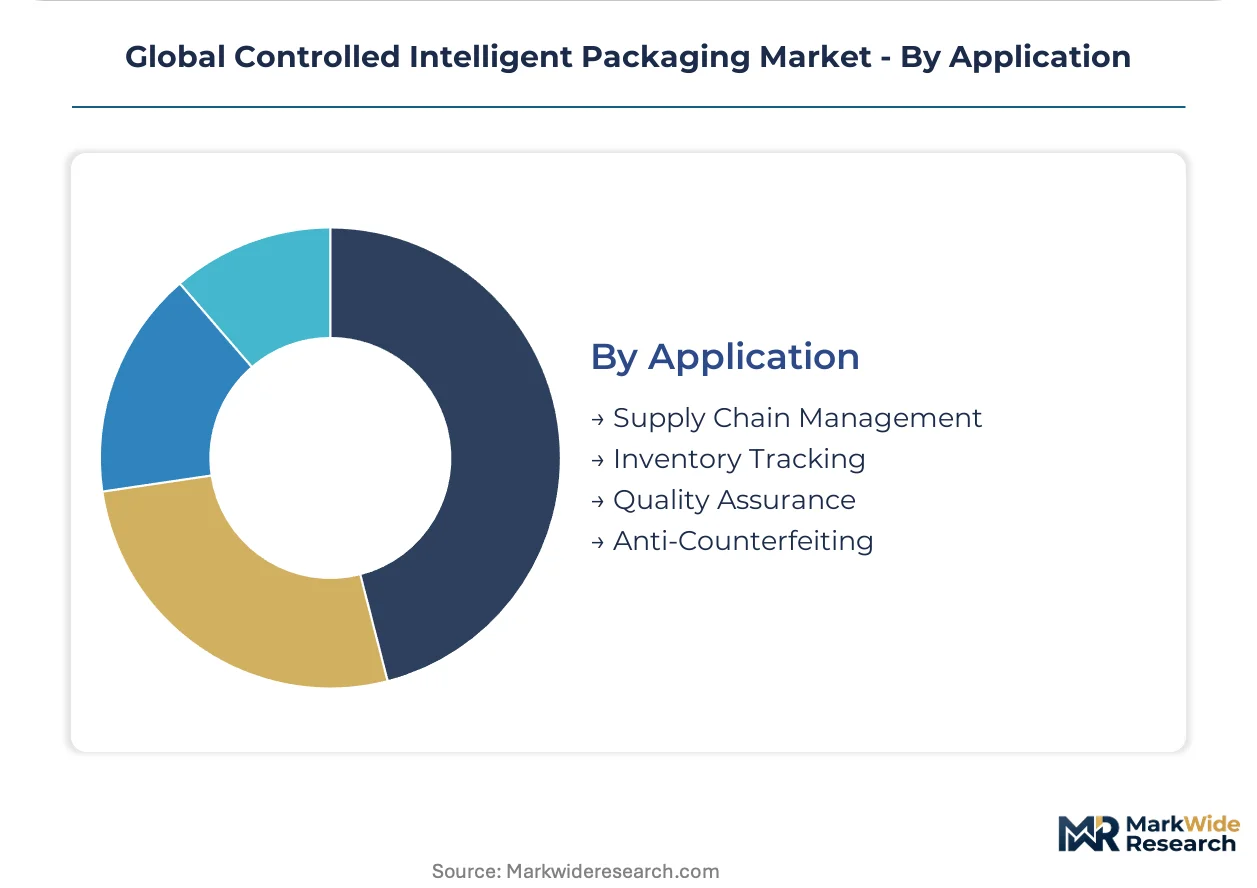
Application:
Customer type stratification separates enterprise pharmaceutical distributors from mid-sized 3PLs with differing integration capabilities.
- Supply Chain Management:End-to-end visibility platforms integrating packaging-level data with ERP and WMS systems. Legacy middleware development delays pharma distributor onboarding by 8–14 months.
- Anti-Counterfeiting:Product authentication through serialized identifiers and consumer verification. NFC-Blockchain convergence compresses deployment timelines from months to weeks.
- Inventory Tracking:Real-time location systems for warehouse and in-transit assets. Asset-light leasing models lower entry barriers for mid-sized logistics providers.
- Quality Assurance:Environmental condition monitoring for temperature-sensitive and moisture-critical products. Electronic alternatives displace chemical indicators as REACH sunset dates approach.
Supply Chain Management captures largest deployment spend. Anti-Counterfeiting gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pharmaceutical and perishable goods are concentrating intelligent packaging demand in manufacturing hubs with stringent cold-chain requirements. Countries with active serialization mandates and biologics production clusters dominate deployment volumes. Regulatory enforcement timelines are compressing adoption curves in transatlantic corridors.
United States
FDA DSCSA unit-level serialization deadlines are forcing wholesale distributors to retrofit carton aggregation systems with RFID-enabled infrastructure. Massachusetts and California biotech clusters specify electronic temperature loggers for mRNA and gene therapy cold chains after COVID-19 vaccine distribution exposed chemical indicator failures. Cloud-integrated sensor recovery programs now dominate procurement in these corridors.
Germany
EU MDR device traceability expansion and REACH sunset dates for chromic humidity indicators are accelerating electronic sensor migration in pharmaceutical contract packaging. Bavarian and North Rhine-Westphalian packaging converters prioritize capacitive polymer loggers to maintain CE-marked barrier compliance. German distributors are retrofitting sterile barrier systems for implantable medical devices.
India
CDSCO alignment with WHO prequalification standards is creating first-mover demand for serialization-ready packaging in generic drug exports to Africa and Southeast Asia. Maharashtra and Gujarat pharmaceutical manufacturing clusters are upgrading carton lines to meet track-and-trace requirements for regulated export markets. Indian contract manufacturers face compressed timelines to deploy EPCIS 2.0 event capture infrastructure.
China
NMPA drug traceability regulations and domestic biologics production expansion are pulling intelligent packaging into cold-chain logistics serving domestic vaccine and insulin distribution. Yangtze River Delta pharmaceutical manufacturers are integrating sensor-enabled secondary packaging for temperature-sensitive biologics. Local packaging converters are developing NFC-Blockchain convergence pilots for high-value pharmaceutical authentication.
France
ANSM enforcement of EU Falsified Medicines Directive serialization and luxury cosmetics anti-counterfeiting demand are bifurcating the intelligent packaging market. Île-de-France pharmaceutical distributors deploy UHF RFID aggregation systems, while Provence-Alpes-Côte d'Azur cosmetic brands pilot NFC-enabled refill authentication for premium skincare lines. REACH restrictions on chromic dyes are accelerating electronic alternatives in both segments.
Global Controlled Intelligent Packaging Market Vendor Landscape
On the supply side, the industry is consolidating around integrated film manufacturers and specialized smart-label converters with captive inlay production capabilities. Three archetypes dominate: diversified packaging conglomerates with materials science depth, adhesive and label specialists with RFID physics expertise, and chemical companies with active packaging material portfolios. Competitive moves center on backward integration into sensor chip sourcing and roll-to-roll printed electronics capacity expansion.
Among diversified packaging conglomerates, Amcor plc and Mondi Group exemplify the materials-integrated archetype through barrier substrate manufacturing networks. Avery Dennison Corporation occupies a distinct position as an adhesive and label specialist with proprietary inlay production capabilities that reduce third-party semiconductor dependency. These three companies represent the primary competitive vectors: film-based integration, smart-label specialization, and upstream materials control.
| Leading Market Players |
|---|
| Amcor plc |
| Avery Dennison Corporation |
| Sealed Air Corporation |
| 3M Company |
| Huhtamaki Oyj |
| Mondi Group |
| Ball Corporation |
| BASF SE |
| PakSense |
| Others |
Supply Flow & Price Mechanics
Single-source silicon wafer dependency in Taiwan and South Korea determines both tiered pricing spreads and supply chain resilience architecture for packaging integrators. FDA DSCSA and EU MDR enforcement timelines compress procurement cycles while semiconductor foundry concentration limits downward price mobility across sensor-enabled product tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the controlled intelligent packaging market. Pharmaceutical-grade multi-parameter sensors with cloud analytics subscriptions command premium positioning against passive smart labels serving generic drug exporters. Price differentiation hinges on certification grade—FDA-validated cold-chain loggers versus CE-marked standard tier—and volume scale with enterprise distributors. Cost compression in the standard tier is intensifying because foundry capacity constraints inflate NFC chip input costs. Generic drug exporters in India exhibit highest price sensitivity, while Massachusetts biotech clusters prioritize validated performance over unit cost.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing and Samsung Foundry hold captive capacity for advanced-node NFC and UHF sensor chips that pharmaceutical packaging integrators require. Geographic supply concentration centers on Taiwan, South Korea, and Germany for semiconductor fabrication, printed electronics manufacturing, and pharmaceutical contract packaging respectively. Raw material dependencies draw from silicon wafers, conductive polymer films, and cobalt-free humidity sensing materials. Single-source vulnerability in advanced lithography creates structural supply chain risk. Distribution runs through pharmaceutical 3PL networks with asset-light sensor leasing models displacing direct hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as serialization mandates splinter demand across pharmaceutical, medical device, and cosmetic verticals with divergent compliance timelines. Each vertical rewards specialized packaging converters with regulatory depth over generalist competitors.
For Market Incumbents: Harden sensor chip supply security through foundry partnerships or backward integration into semiconductor sourcing before Taiwan capacity constraints tighten further. Expand roll-to-roll printed electronics capacity in Germany to capture EU MDR-driven sterile barrier system demand. Certification investment in FDA-validated cold-chain loggers defends margin position against Asian competitors pursuing WHO prequalification alignment. For New Entrants and Emerging Players: Mid-market pharmaceutical distributors in India represent the most penetrable entry point, as CDSCO alignment with WHO standards creates first-mover demand for serialization-ready packaging without entrenched incumbent relationships. Reusable sensor leasing models for temperature-sensitive agriculture and specialty chemicals offer second white-space target with lower regulatory barriers. Go-to-market through cloud-integrated subscription structures unbundles hardware from software fees, lowering customer capital commitment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors smart-label converters with proprietary inlay production capabilities and pharmaceutical regulatory expertise. Long-term viability across the projection horizon rests on backward integration into sensor chip sourcing or foundry partnership durability. Watch Taiwan Semiconductor Manufacturing capacity allocation announcements as inflection indicator for packaging integrator margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Structuring | Secures NFC chip allocation for FDA-validated cold-chain logger production. |
| Roll-to-Roll Capacity Expansion | Enables printed antenna migration from copper inlay to biodegradable cellulose substrates. |
| Regulatory Certification Investment | Accelerates CE-marked barrier system compliance ahead of REACH sunset deadlines. |
| Cloud Platform Integration | Unbundles sensor hardware from recurring analytics subscription revenue streams. |
| Asset-Light Leasing Model Launch | Lowers entry barriers for mid-sized 3PLs in California agricultural logistics corridors. |
Methodological Framework
Operator-level perspectives from packaging converters, pharmaceutical supply chain directors, cold-chain logistics operators, and semiconductor foundry account managers anchored the qualitative base for this study. Primary interviews with RFID physics specialists and pharmaceutical regulatory affairs leads combined with secondary validation from FDA DSCSA guidance documents, EMA MDR implementation reports, ECHA REACH substance restriction databases, and SEC filings of diversified packaging conglomerates. Bottom-up shipment volume modeling and top-down market sizing triangulation cross-verified segment-level estimates.
Scenario-bracketing around regulatory enforcement timelines and silicon supply volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type complexity, technology cost tier, end-user regulatory maturity, and geographic compliance cluster. CAGRs derived from installed base growth rates and replacement cycle analysis for disposable versus reusable sensor systems. Forecast inputs incorporated pharmaceutical serialization mandate deadlines and REACH substance restriction sunset dates.
Practitioners should monitor foundry capacity allocation shifts, ECHA substance restriction enforcement, and FDA DSCSA compliance extension announcements for early signals requiring forecast revision. Quarterly review of semiconductor lead time indicators and pharmaceutical distributor EPCIS 2.0 implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market