
 Easy Open Packaging Market | 2026-2036
Easy Open Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Easy Open Packaging Market Analysis
Packaging engineering talent scarcity is redrawing competitive boundaries in easy-open formats. Amcor plc leverages captive polymer science labs to sustain film-to-lid integration across pharmaceutical blister lines. Crown Holdings anchors metal easy-open end production through beverage can specialization in North America. Sealstrip Corporation differentiates via adhesive tear-strip technology for flexible food pouches.
Easy open packaging denotes consumer-accessible sealed containers incorporating mechanical features—tear notches, pull tabs, thumb lifts, or scored perforations—that reduce opening force below standard thresholds, typically targeting sub-15 Newton activation for elderly or impaired users. These structures employ oriented polypropylene films, laminated paperboard, or aluminum-composite substrates processed through precision scoring, laser perforation, or integrated strip welding to guarantee seal integrity while enabling finger-operated rupture. Flexible film pouches with tear-notch features currently occupy the largest volume position across food and beverage end uses, whereas child-safe mechanisms command premium positioning in pharmaceutical blister and bottle formats due to compliance burdens and liability exposure. Rigid containers in aluminum and composite materials lead margin pools where dual-function child-resistance and senior-accessibility standards apply, particularly in OTC medication and supplement categories.
FDA 21 CFR Part 310 packaging guidelines and the EU MDR accessibility provisions shape product development priorities for pharmaceutical easy-open applications, while EPA substrate regulations influence material selection in food-contact films. ISO 8317 child-resistant standards and ASTM D3475 senior-friendly protocols create dual-certification requirements that filter market access for new entrants. Stakeholders must monitor evolving accessibility mandates across Japan's PMDA and Germany's BfArM as aging demographics intensify regulatory pressure for inclusive design.
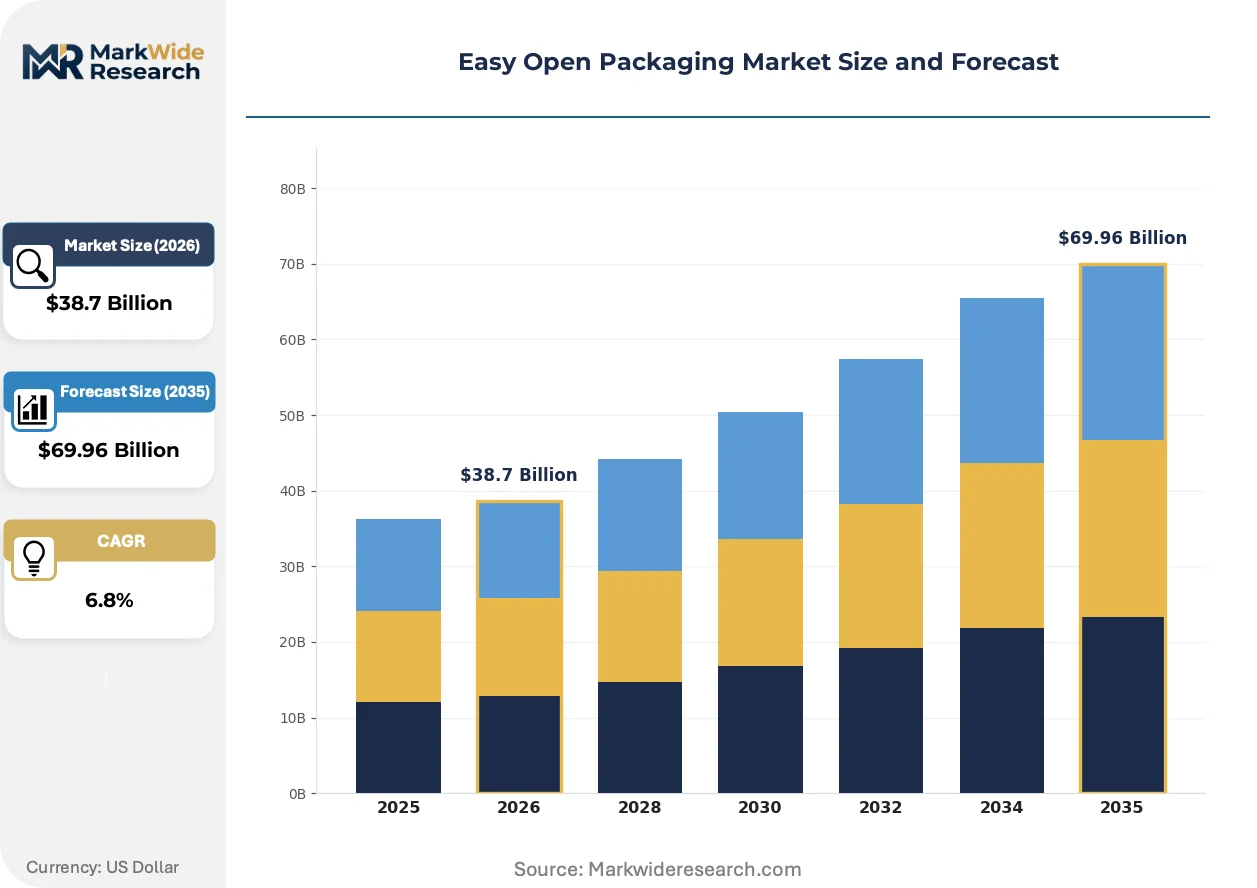
Market Dynamics
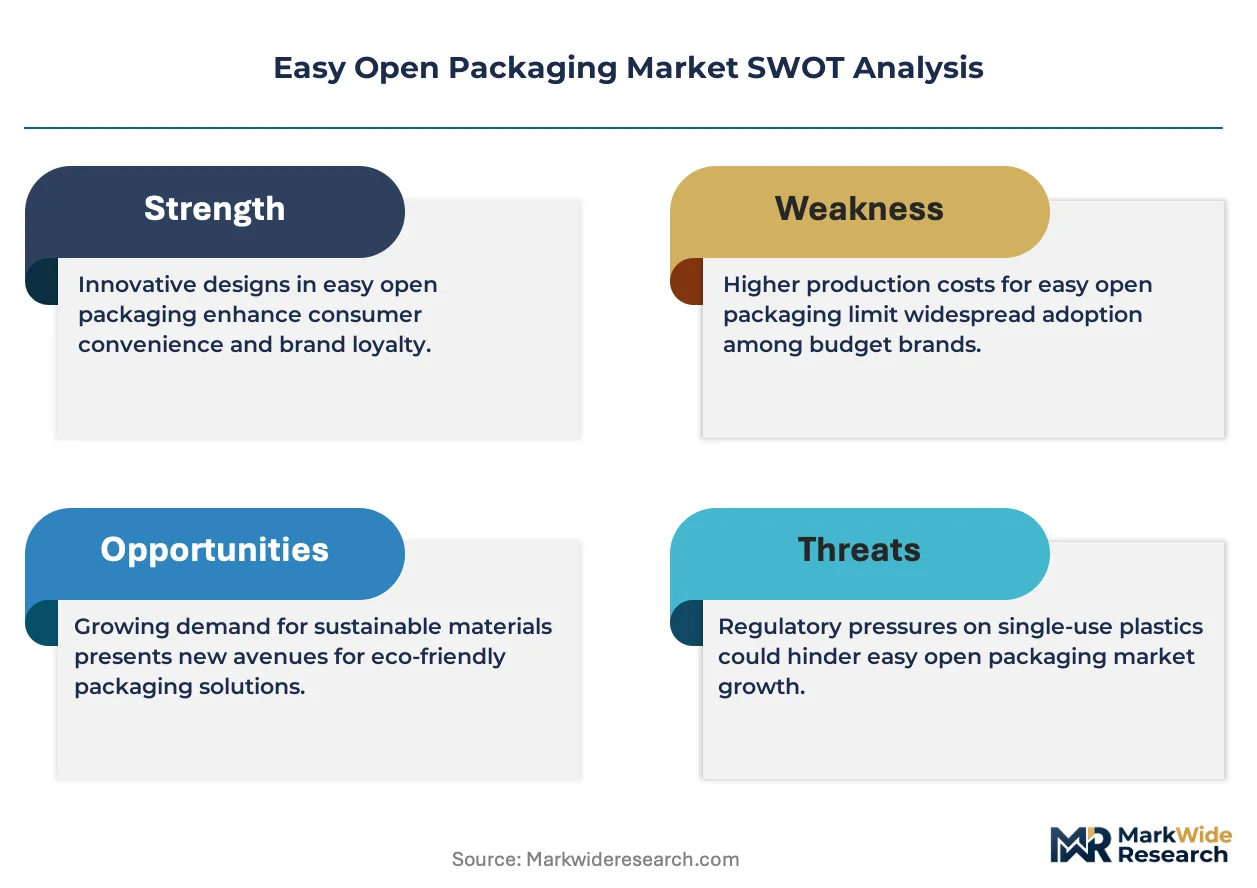
Pharmaceutical accessibility mandates are compressing development cycles across easy-open packaging formats, forcing manufacturers to reconcile ISO 8317 child-resistance certification with ASTM D3475 senior-friendly thresholds within single SKU designs.
Growth Catalysts
- Japan's PMDA senior-accessibility guidance:Regulatory pressure from Japan's aging demographic is accelerating tear-notch and thumb-lift adoption in blister packaging for arthritis-affected consumers.
- OTC medication formats:Self-medication trends are expanding demand for dual-function child-resistant yet senior-accessible bottles and sachets in retail pharmacy channels.
- Laser perforation systems:Precision scoring technology is enabling thinner film substrates to maintain seal integrity while reducing activation force below 15 Newton thresholds.
Market Restraints
- Aluminum price volatility:Composite lidstock and metal end production faces margin compression from commodity input swings in raw material markets.
- Polymer science talent scarcity:Specialized adhesive formulation and oriented polypropylene film engineering expertise concentrates in Germany's medical packaging cluster.
- Dual-certification timelines:ISO 8317 and ASTM D3475 parallel testing requirements extend product launch windows by 8-14 months for new entrants.
Strategic Opportunities
- India's PLI scheme for packaging:Domestic manufacturing incentives are creating localized production capacity for export-oriented pharmaceutical blister lines.
- Smart packaging convergence:NFC-enabled tear strips combining accessibility with authentication are opening premium positioning in anti-counterfeit pharmaceutical segments.
- E-commerce direct-to-patient channels:Subscription pharmacy models are demanding ship-ready easy-open formats that survive last-mile handling without compromising accessibility.
Industry Challenges
- Adhesive strip welding precision:Maintaining consistent tear propagation across humidity-variable climates requires recalibration of hot-melt application systems.
- Legacy filling line retrofit costs:Pharmaceutical contract manufacturers face capital-intensive modifications to accommodate modified-blister geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Easy Open Packaging Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Film, Rigid Container, Lidding, Pouches Material: Plastic, Paper, Aluminum, Composite End User: Food & Beverage, Personal Care, Pharmaceutical, Household Feature: Child-Safe, Tear Notch, Easy Thumb Lift, Pull Tab |
| Companies Covered | Youpeng Packaging, BSI Group, Crown Holdings, Inc., FlexPak Services, Sealstrip Corporation, Amcor plc, Creative Packaging Solutions, LivingPackets SA, Better Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Easy Open Packaging Market Emerging Trajectories
Material science breakthroughs are fragmenting traditional substrate hierarchies, with bio-based alternatives and precision manufacturing methods rewriting cost-performance tradeoffs across pharmaceutical and food-contact applications.
Laser micro-perforation technology is decomposing the historical barrier between seal integrity and accessibility performance. Pharmaceutical blister manufacturers in Germany are adopting femtosecond scoring systems to create fracture zones that activate at 8-12 Newton force while maintaining moisture vapor transmission rates. This precision is compressing the need for multi-layer laminate structures, enabling thinner oriented polypropylene films to replace aluminum-composite substrates in humidity-stable formulations.
EU MDR accessibility provisions are forcing redesign of elderly-targeted dosing formats across the European pharmaceutical supply chain. The regulation's senior-friendly packaging requirements now apply to all new OTC registrations, compelling manufacturers to submit human-factors validation data with marketing authorization applications. German regulators at BfArM are enforcing these standards most stringently, rejecting submissions lacking documented arthritis-user testing.
Direct-to-patient pharmacy subscriptions are reshaping packaging durability requirements beyond the traditional retail shelf-life model. Mail-order pharmaceutical channels in the United States now specify drop-test survival criteria that conflict with easy-open tear-notch designs, forcing engineers to reinforce corner geometries without increasing activation force. This tension is most acute in humidity-exposed regions where adhesive-based tear strips risk premature delamination during transit.
Easy Open Packaging Market Segmentation
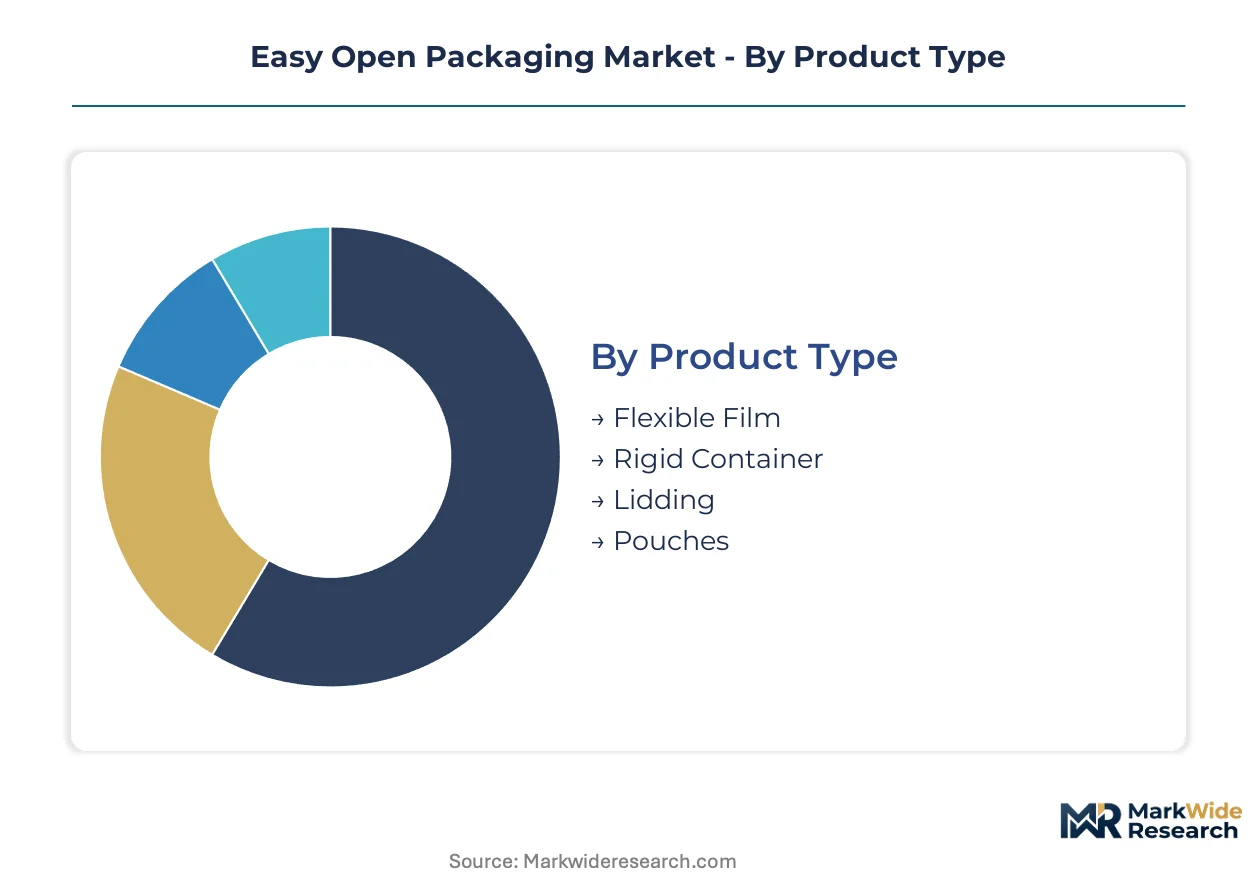
Easy open packaging procurement decisions diverge sharply across regulatory jurisdictions. Pharmaceutical buyers prioritize ISO 8317 child-resistance certification alongside ASTM D3475 senior-accessibility thresholds, while food-contact purchasers weigh EPA substrate compliance against shelf-life performance.
Product Type:
FDA 21 CFR Part 310 and EU MDR accessibility provisions create divergent performance specifications across format categories, with pharmaceutical blister lines demanding dual-certification compliance that flexible food pouches rarely require.
- Flexible Film:Oriented polypropylene and laminated polyethylene structures dominate food-contact applications through tear-notch and scored perforation features. Germany's medical packaging cluster sources precision-scored films for arthritis-accessible pharmaceutical sachets under BfArM enforcement of senior-friendly standards.
- Rigid Container:Aluminum-composite and injection-molded polymer vessels serve dual-function child-resistant and senior-accessible requirements in OTC medication. Japan's PMDA guidance on aging-population accessibility accelerates thumb-lift adoption in supplement bottles.
- Lidding:Peelable foil and paperboard laminates seal pharmaceutical blisters and ready-meal trays. Laser micro-perforation systems enable 8-12 Newton activation force while maintaining moisture barriers.
- Pouches:Stand-up and flat formats with adhesive tear strips command flexible food packaging volume. Humidity-variable climates challenge consistent tear propagation in tropical distribution corridors.
Established volume favors flexible film; emerging adoption favors rigid containers.
Material:
Cost tier stratification separates commodity substrates from performance-engineered laminates required for pharmaceutical certification compliance.
- Plastic:Polypropylene and polyethylene films offer tunable seal strength and tear propagation through coextrusion layering. Germany's polymer science talent scarcity concentrates formulation expertise in medical packaging clusters serving arthritis-affected consumers.
- Paper:Kraft and glassine substrates provide renewable alternatives in food-contact applications with limited moisture-barrier performance. Fiber-based formats rarely achieve pharmaceutical moisture vapor transmission requirements.
- Aluminum:Foil and formed metal ends deliver absolute barrier properties for humidity-sensitive pharmaceuticals. Aluminum price volatility compresses margins in composite lidstock production.
- Composite:Multi-layer laminates combining plastic, foil, and paperboard serve premium pharmaceutical and retort food applications. Precision scoring technology is displacing thicker traditional structures with thinner engineered alternatives.
Margin concentration sits with composites; volume leadership remains with plastics.
End User:
Application-specific regulatory burdens fragment procurement specifications across customer categories.
- Food & Beverage:Tear-notch pouches and peelable lidding dominate retail shelf presence. E-commerce direct-to-consumer channels impose drop-test durability requirements that conflict with easy-open activation thresholds.
- Personal Care:Flip-top and disc-cap formats serve accessibility needs in shampoo and lotion categories with lighter regulatory certification burdens than pharmaceutical equivalents.
- Pharmaceutical:Blister packs and bottles face the most stringent dual-certification requirements under FDA, EMA, and PMDA jurisdictions. Human-factors validation data now accompanies marketing authorization submissions.
- Household:Cleaning product containers balance child-resistance with senior accessibility in less regulated categories. Trigger sprayers and pour spouts incorporate ergonomic enhancements without formal certification protocols.
Certification intensity peaks in pharmaceuticals; volume scale concentrates in food and beverage.
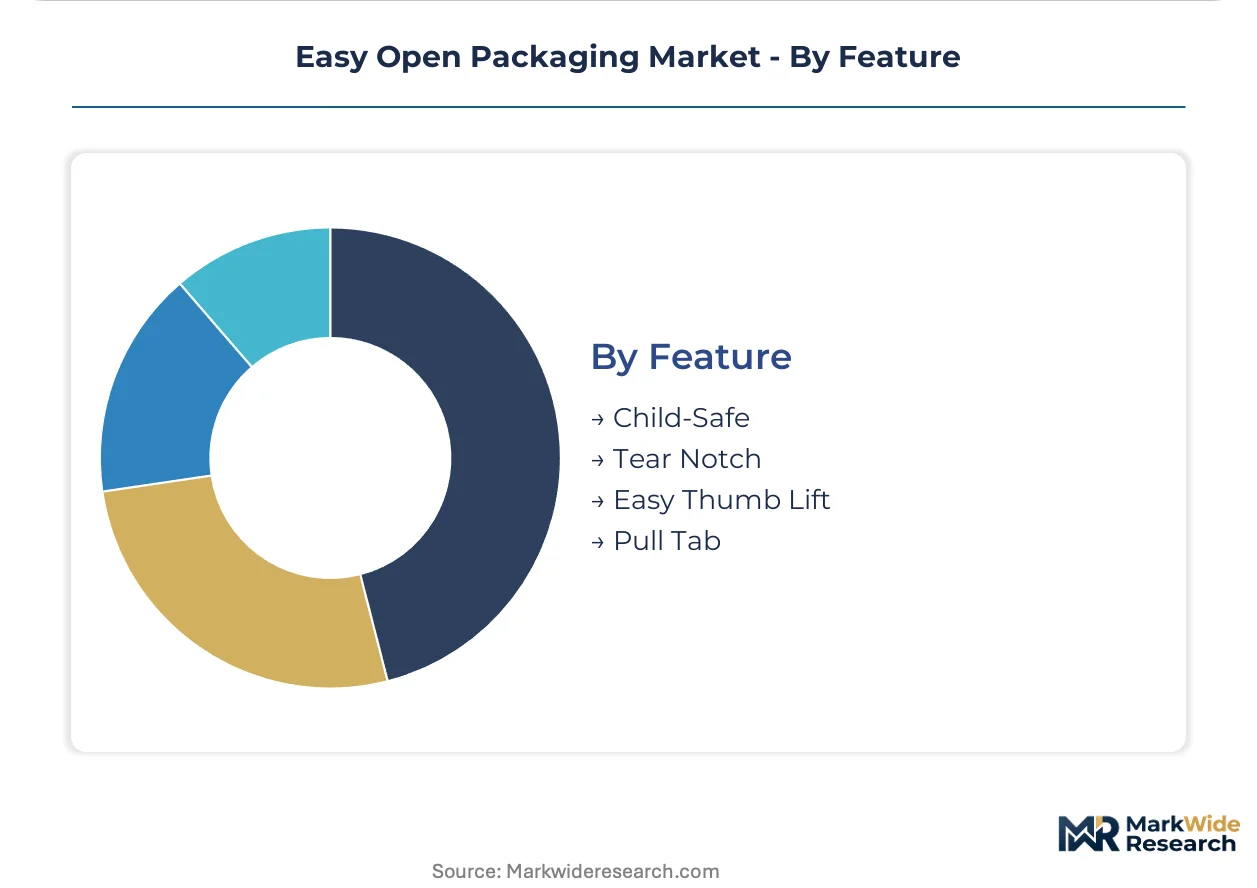
Feature:
Customer type differentiation separates institutional buyers demanding documented compliance from retail channels prioritizing shelf differentiation.
- Child-Safe:Push-and-turn caps and senior-friendly blister formats require ISO 8317 testing protocols. Dual-function designs combining child-resistance with arthritis-accessible activation command premium positioning.
- Tear Notch:V-shaped or linear scored cuts in flexible films and pouches reduce opening force below 15 Newton thresholds. Laser perforation systems are refining precision to maintain seal integrity across humidity extremes.
- Easy Thumb Lift:Integrated tab structures on blister lidding and bottle closures serve Japan's aging demographic under PMDA accessibility guidance. Thumb-lift designs dominate Germany's medical packaging cluster output.
- Pull Tab:Extended strip or ring features on metal ends and flexible pouches enable finger-operated rupture. Adhesive tear-strip welding precision determines consistent propagation across climate zones.
Regulatory momentum favors child-safe and thumb-lift integration; cost efficiency sustains tear notch prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's BfArM enforces the EU MDR's senior-friendly packaging requirements most stringently, anchoring European demand for arthritis-accessible pharmaceutical formats. Japan's PMDA guidance and India's PLI manufacturing incentives are reshaping production geography across three continents.
United States
Mail-order pharmacy subscriptions from CVS and Amazon Pharmacy are forcing tear-notch redesigns for drop-test survival. FDA 21 CFR Part 310 guidelines mandate child-resistance certification for OTC blister packs. Chicago-area contract manufacturers are retrofitting legacy filling lines to accommodate modified-blister geometries for arthritis-affected consumers.
Germany
BfArM regulators reject pharmaceutical submissions lacking documented arthritis-user testing under EU MDR accessibility provisions. The country's medical packaging cluster in the Rhine-Ruhr region concentrates polymer science talent for precision-scored film development. Femtosecond laser perforation systems in Bavaria enable 8-12 Newton activation force while maintaining moisture barriers.
Japan
METI and PMDA guidance on aging-population accessibility accelerates thumb-lift adoption in supplement bottles for 65-plus consumers. Osaka-based pharmaceutical packagers integrate tear-notch features into humidity-sensitive blister lines. Kansai industrial corridors supply precision-scored laminates to domestic OTC manufacturers facing senior-accessibility mandates.
India
The PLI scheme for packaging is creating localized production capacity for export-oriented pharmaceutical blister lines to Europe and Africa. CDSCO aligns with ISO 8317 child-resistance standards for domestic OTC registration. Gujarat's polymer processing hubs are expanding oriented polypropylene film output for tear-notch sachets targeting arthritis-affected rural populations.
China
NMPA pharmaceutical packaging regulations are converging with ASTM D3475 senior-friendly protocols for export-oriented manufacturers. Yangtze River Delta converters supply laser-perforated lidding to global pharmaceutical contract packagers. Shanghai-area R&D centers are developing humidity-stable adhesive tear strips for tropical distribution corridors.
Easy Open Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in easy open packaging supply. Consolidated film-to-lid integrators and metal end specialists command premium positioning through captive polymer science capabilities. Three archetypes dominate: diversified packaging conglomerates with pharmaceutical certification depth, precision-scoring technology specialists, and regional flexible film converters. Competitive moves center on laser perforation system acquisitions and backward integration into oriented polypropylene resin supply.
Within the diversified conglomerate tier, Amcor plc and Crown Holdings, Inc. exemplify scale-driven certification depth across pharmaceutical and beverage end uses. Sealstrip Corporation anchors the adhesive tear-strip specialist segment. These three entities occupy positions spanning film lamination, metal forming, and precision adhesive welding—each representing a distinct technical pathway to sub-15 Newton activation thresholds.
| Leading Market Players |
|---|
| Youpeng Packaging |
| BSI Group |
| Crown Holdings, Inc. |
| FlexPak Services |
| Sealstrip Corporation |
| Amcor plc |
| Creative Packaging Solutions |
| LivingPackets SA |
| Better Packaging |
| Others |
Supply Flow & Price Mechanics
ISO 8317 child-resistance certification gates both supplier qualification and price differentiation simultaneously, creating tiered access where dual-certified formats command substantial premiums over single-standard alternatives while raw material volatility compresses margins at the commodity end.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical blister supply relationships, insulating converters from aluminum spot-price swings while locking in volume commitments. Pricing stratifies across premium, standard, and economy tiers based on certification depth and polymer science formulation complexity. Cost compression in standard-tier flexible film is intensifying because oriented polypropylene resin supply concentrates in Germany's medical packaging cluster. Retail pharmacy chains exhibit highest price sensitivity, whereas pharmaceutical OEMs prioritize compliance assurance over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision-scored film and laser-perforation equipment production for arthritis-accessible pharmaceutical formats. Raw material flows draw from Saudi Arabia for polymer feedstock, Australia for bauxite-derived aluminum, and South Korea for specialty adhesive resins. Single-source vulnerability concentrates in femtosecond laser scoring systems where Bavarian equipment makers hold dominant market positions. Distribution runs through pharmaceutical contract manufacturers and retail pharmacy networks with direct-to-patient subscription channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Easy open packaging is evolving into a service-attach opportunity where validation consulting and certification management subscriptions expand faster than substrate hardware sales as regulatory complexity deepens.
For Market Incumbents: Shield market position by deepening captive polymer science capabilities in Germany's Rhine-Ruhr cluster to offset talent scarcity, while accelerating NFC-enabled tear strip development to defend against smart packaging specialists. Certification investment in dual ISO 8317 and ASTM D3475 protocols remains the critical lever for pharmaceutical margin defense.
For New Entrants and Emerging Players: Laser perforation retrofit services for legacy filling lines represent a service-layer gap where incumbents under-serve, creating entry pathways for precision-scoring technology specialists. India's PLI scheme subsidized production capacity offers the most penetrable geography, with go-to-market traction through pharmaceutical export channels to Africa and Southeast Asia.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across flexible film conversion as precision manufacturing displaces multi-layer laminate thickness requirements, improving returns for technology-acquisitive mid-caps. Acquisition targets should profile adhesive formulation specialists with humidity-stable tear strip IP. Watch BfArM enforcement stringency as the signal indicating European pricing power inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Perforation System Acquisition | Femtosecond scoring technology from Bavarian equipment makers compresses activation force thresholds below 12 Newton. |
| Backward Integration into Polymer Resin | Captive oriented polypropylene supply insulates margin compression from Saudi feedstock price volatility. |
| Dual-Certification Investment | Parallel ISO 8317 and ASTM D3475 validation opens access to Japan's PMDA-regulated OTC registration pathways. |
| Smart Packaging Convergence | NFC-enabled tear strips combine accessibility with anti-counterfeit authentication for premium pharmaceutical positioning. |
| Regional Manufacturing Footprint | India's PLI scheme subsidized capacity captures export demand from European pharmaceutical contract packagers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment manufacturer disclosures. Primary interviews engaged packaging engineers at pharmaceutical OEMs, procurement leads at retail pharmacy chains, regulatory affairs specialists at notified bodies, and polymer scientists at German medical packaging clusters. Secondary validation drew from FDA 21 CFR Part 310 guidance documents, EU MDR accessibility provisions, BfArM rejection data, and PMDA senior-accessibility guidance. Bottom-up volume modeling triangulated against top-down market sizing across substrate categories.
Segmentation dimensions modeled include product type, material substrate, end-user industry, and accessibility feature complexity across the projection horizon. CAGRs were derived from regression analysis of historical adoption curves in aging-population markets, weighted by regulatory enforcement intensity and pharmaceutical registration timelines. Forecast inputs incorporated laser perforation equipment deployment rates and polymer science talent concentration indices.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA jurisdictions; material policy shifts such as expanded senior-accessibility mandates or child-resistance standard revisions would require re-modeling. Aluminum price volatility, adhesive supply disruptions, and certification timeline extensions represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market