
 Intelligent Packaging Market | 2026-2036
Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Packaging Market Outlook
Multi-source procurement for smart label substrates is hardening as converters diversify away from single polymer suppliers. Avery Dennison Corporation leverages its North American adhesive coating capacity to anchor premium RFID inlay production. Sealed Air Corporation sustains leadership in active packaging films through integrated barrier polymer research. Mondi Group differentiates via European paper-based smart packaging lines that compete against plastic incumbents.
Intelligent packaging combines sensors, indicators, and communication interfaces into primary or secondary packaging to monitor condition, authenticate origin, or enable traceability throughout distribution. Active oxygen scavengers and time-temperature indicators typically embed iron-based compounds or enzymatic layers that react to environmental deviations, preserving pharmaceutical efficacy or food safety across extended supply chains. Active Packaging captures mature margin pools in oxygen control for meat and dairy, while NFC Tags represent the fastest-expanding segment as smartphone-native authentication displaces dedicated scanners. Smart Labels occupy a transitional position where cost-per-unit declines are unlocking mid-tier food and beverage adoption.
FDA traceability mandates for pharmaceutical distribution reshape serialization requirements, compelling packagers to integrate machine-readable identifiers at unit level. EU Green Deal packaging regulations and REACH substance restrictions jointly accelerate substitution of conventional plastics with biodegradable substrates certified under industrial composting standards. Stakeholders must weigh compliance investment timelines against the pace at which NFC and sensor costs fall toward mass-market thresholds.
Market Dynamics
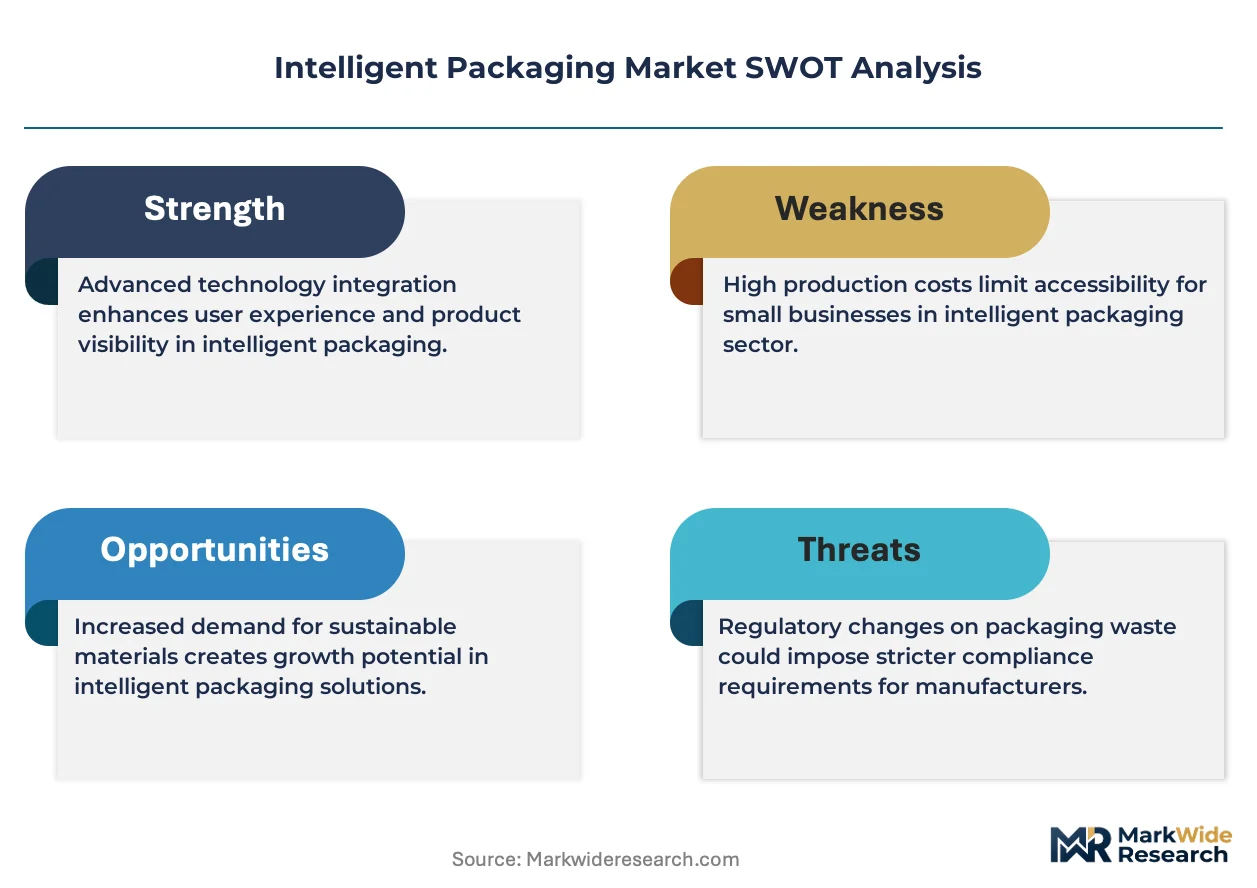
Pharmaceutical serialization mandates and EU packaging waste directives are forcing converters to rebuild substrate portfolios around biodegradable alternatives, compressing legacy polymer margins while opening premium positions for RFID-integrated paperboard.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level traceability requirements for pharmaceutical distribution drive embedded sensor adoption across cold-chain logistics networks.
- Biologics expansion:Temperature-sensitive monoclonal antibodies and cell therapies require time-temperature indicators across extended distribution chains.
- Munich-Hamburg industrial corridor:German packaging clusters integrate RFID-enabled supply chains, creating demonstration effects for adjacent European markets.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Barrier film supply hinges on Asian petrochemical complexes, exposing converters to feedstock volatility and freight cost spikes.
- NFC inlay yield rates:Semiconductor-grade antenna etching produces scrap rates above 15% at volumes below 10 million units, elevating effective unit costs for mid-tier adopters.
- REACH substance restrictions:Candidate list expansion for microplastics and persistent organic pollutants forces reformulation of oxygen scavenger iron-based compounds.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO alignment with FDA serialization standards creates demand for machine-readable secondary packaging in bulk generic distribution.
- Smartphone-native authentication:NFC tag costs approaching passive barcode parity enable direct-to-consumer provenance verification for premium food and cosmetics.
- EU Green Deal packaging regulations:Mandatory recycled content thresholds and industrial composting certification accelerate substitution of multilayer plastic with fiber-based smart substrates.
Industry Challenges
- Electronics-packaging hybrid skill scarcity:Converters lack embedded systems engineers capable of integrating antenna design with high-speed folding-carton lines.
- Multimaterial certification timelines:Biodegradable substrates with printed electronics require sequential testing under EN 13432 composting and FCC electromagnetic compliance, extending qualification cycles.
- Legacy ERP integration:Serialization data streams from packaging lines conflict with existing warehouse management systems, demanding middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Packaging Market |
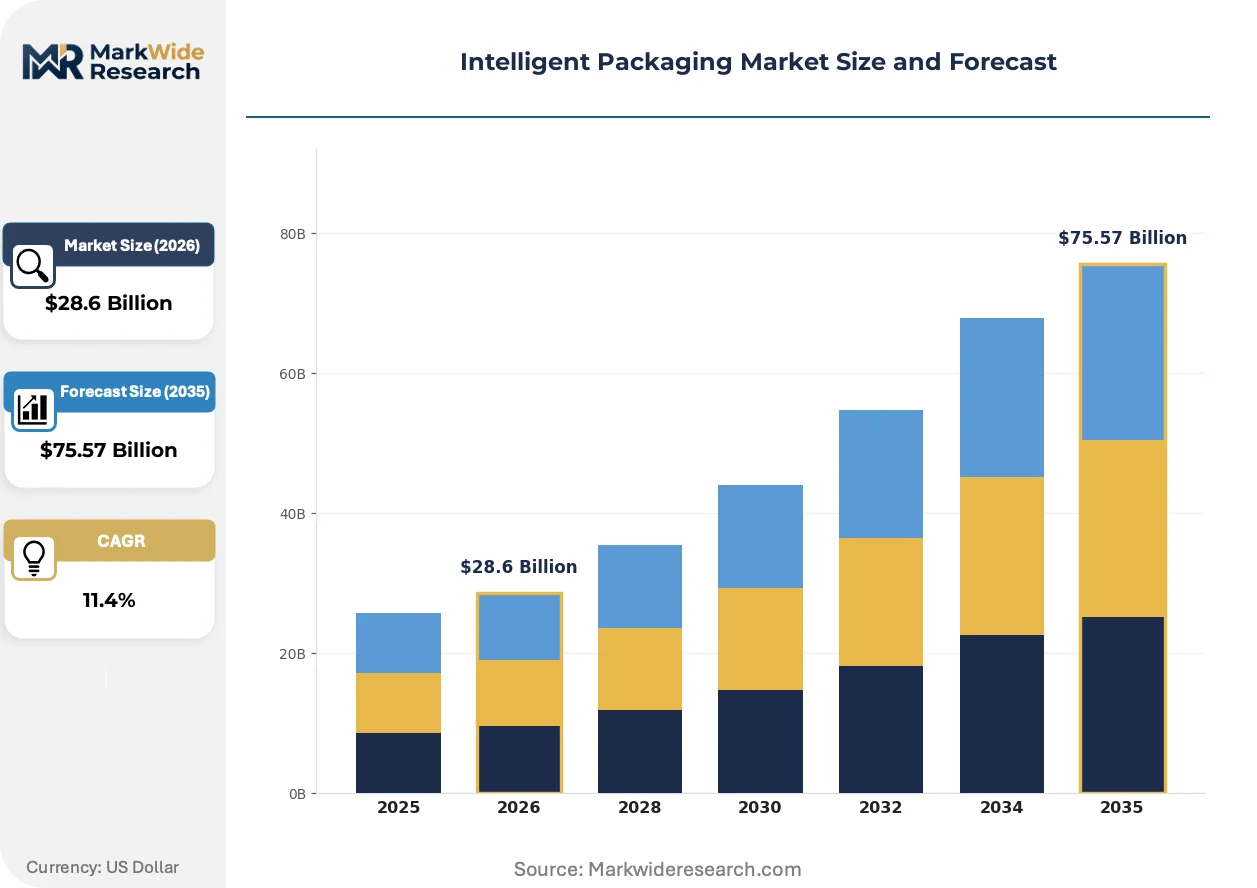
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Smart Labels, Sensors, NFC Tags Application: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Material: Plastic, Paper, Glass, Biodegradable Materials End User: Retail, Healthcare, Logistics, Manufacturing |
| Companies Covered | Amcor plc, Avery Dennison Corporation, Sealed Air Corporation, 3M Company, Mondi Group, Smurfit Kappa Group, Berry Global Inc., Constantia Flexibles, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Packaging Market Strategic Shifts
Decentralized sensing architectures and substrate material pivots are collapsing the distinction between passive containment and active supply chain intelligence, redefining converter value capture.
Printed graphene humidity sensors is decentralizing quality assurance by embedding conductive ink patterns directly onto corrugated fiberboard. Pharmaceutical distributors in the Benelux region are piloting these at pallet level, eliminating separate data logger procurement. The technology is compressing cold-chain monitoring costs toward commodity packaging economics.
EU Green Deal packaging waste directives and F-Gas Regulation are jointly accelerating fluoropolymer phase-out in barrier films. Active packaging developers are substituting plasma-deposited silicon oxide coatings for modified atmosphere meat preservation. German dairy processors face the steepest compliance curves, with 2025 targets already triggering line retrofits.
Direct-to-retailer procurement of serialized secondary packaging is bypassing traditional wholesale distributors in North American pharmaceutical channels. Hospital systems and specialty pharmacies now specify machine-readable aggregation at case level, shifting converter customer relationships toward long-term data service contracts. This pattern concentrates in oncology and rare disease biologics distribution.
Intelligent Packaging Market Segmentation
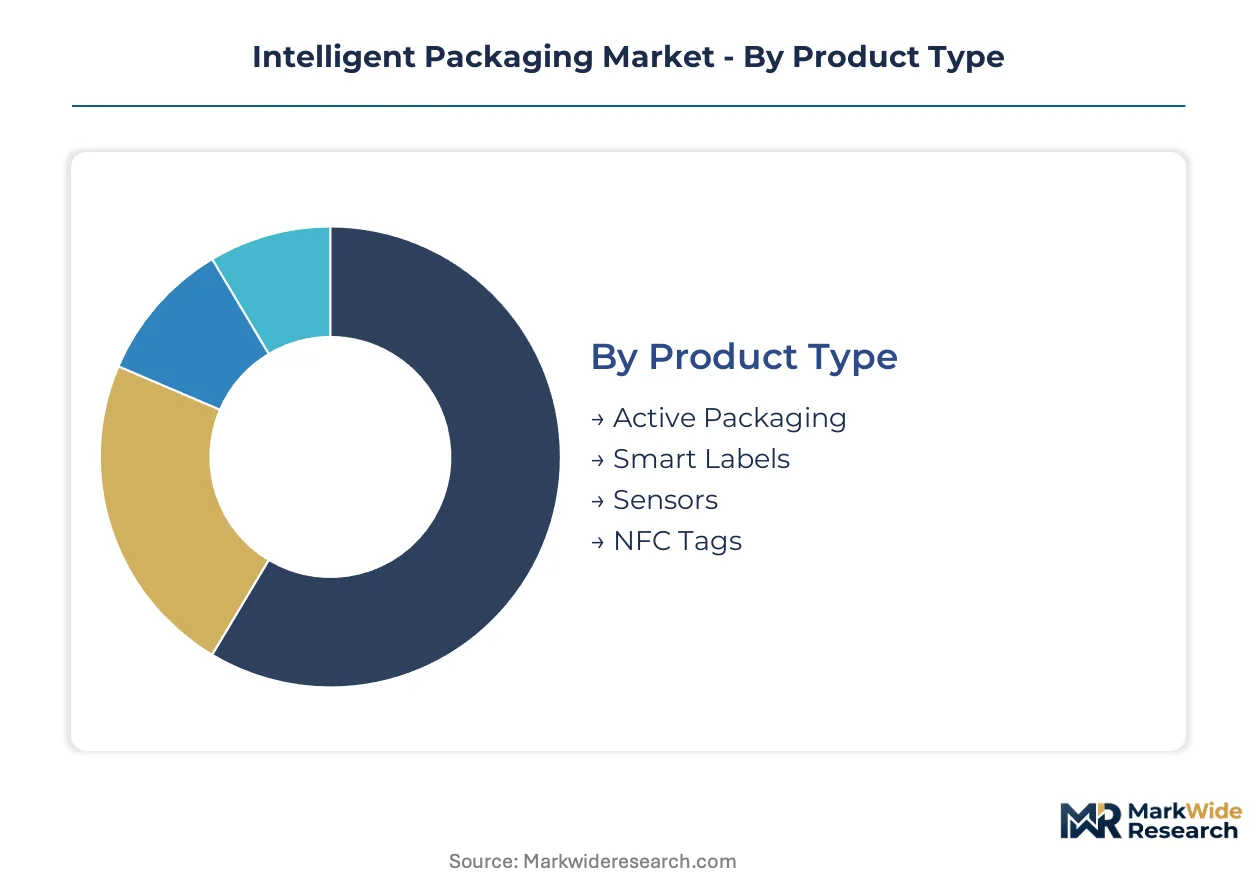
Intelligent packaging segments diverge sharply by upgrade urgency. Pharmaceutical serialization deadlines and EU packaging waste mandates are forcing parallel transitions—electronics integration in one cluster, material substitution in another—creating distinct procurement timelines and supplier qualification cycles across converter portfolios.
Product Type:
Upgrade cycles vary dramatically by product type, with some technologies requiring line retrofits while others slot into existing equipment with minimal reconfiguration.
- Active Packaging:Oxygen scavengers and moisture absorbers embed iron-based compounds or desiccant layers directly into barrier films. Meat and dairy processors in Germany drive mature demand, though REACH substance restrictions on iron particulates are forcing reformulation toward enzymatic alternatives.
- NFC Tags:Near-field communication inlays combine etched copper or aluminum antennas with semiconductor chips for smartphone-native authentication. Cosmetics brands in France and Benelux are piloting direct-to-consumer provenance verification, displacing dedicated scanner infrastructure.
- Smart Labels:RFID-enabled adhesive constructs bridge passive barcodes and full sensor integration, with declining inlay costs unlocking mid-tier food and beverage adoption.
- Sensors:Printed electronics and microelectromechanical systems enable real-time condition monitoring across temperature, humidity, and shock parameters.
Volume placements concentrate in Active Packaging; the faster expansion belongs to NFC Tags.
Application:
Application segments stratify by regulatory pressure intensity, with compliance timelines rather than pure commercial return shaping investment sequencing.
- Pharmaceuticals:Cold-chain biologics and serialized distribution dominate sensor and indicator demand. FDA Drug Supply Chain Security Act mandates and EMA serialization requirements force unit-level traceability infrastructure across US and European distribution networks.
- Food & Beverage:Modified atmosphere packaging and time-temperature indicators preserve quality across extended supply chains. German dairy processors face steep EU Green Deal compliance curves, accelerating biodegradable substrate adoption.
- Cosmetics:Premium brands deploy NFC authentication to combat counterfeiting and enable ingredient transparency.
- Electronics:Anti-static and humidity-sensitive indicators protect high-value components through multimodal logistics.
Pharmaceuticals commands the premium tier; Food & Beverage delivers the broadest installed base expansion.
Material:
Material selection now pivots on certification velocity rather than performance optimization alone, with composting and electromagnetic compliance timelines running in parallel.
- Biodegradable Materials:Fiber-based substrates with printed electronics require sequential EN 13432 composting and FCC electromagnetic validation. German and Dutch converters lead qualification efforts for pharmaceutical secondary packaging.
- Plastic:Multilayer barrier films with ethylene vinyl alcohol cores face feedstock volatility from Asian petrochemical concentration, compressing legacy margins.
- Paper:European paper-based smart packaging lines compete against plastic incumbents, with Mondi Group and similar converters integrating RFID inlays into molded fiber structures.
- Glass:Limited intelligent packaging penetration due to surface integration challenges, though smart closures gain traction in premium spirits.
Plastic retains volume dominance; biodegradable materials are climbing the fastest.
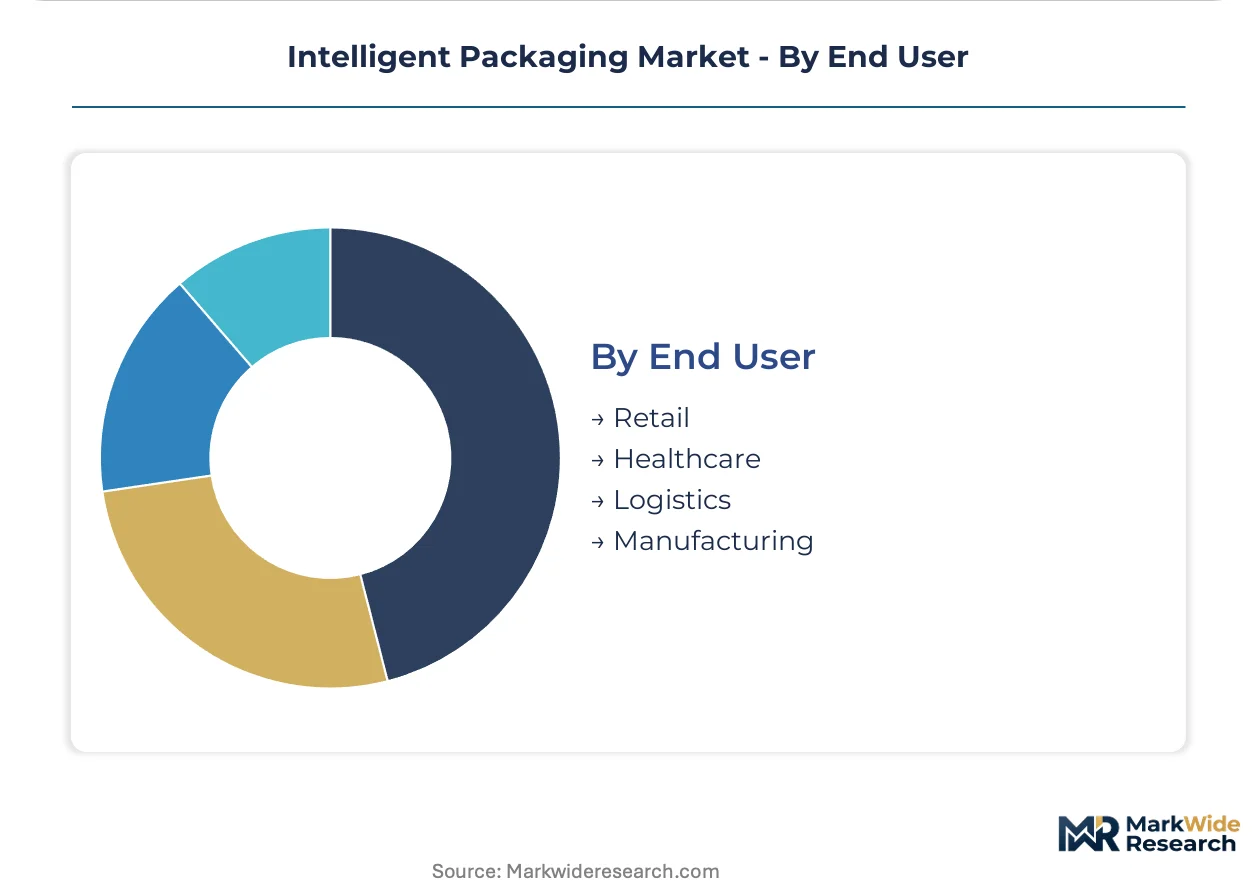
End User:
End user segments diverge by data integration maturity, with some verticals demanding real-time telemetry while others prioritize post-hoc verification.
- Healthcare:Hospital systems and specialty pharmacies specify machine-readable aggregation at case level, shifting converter relationships toward long-term data service contracts concentrated in oncology and rare disease distribution.
- Logistics:Third-party cold-chain operators deploy pallet-level sensing to eliminate separate data logger procurement, with Benelux pharmaceutical distributors piloting printed graphene humidity sensors on corrugated fiberboard.
- Retail:Direct-to-retailer procurement of serialized secondary packaging bypasses traditional wholesale distributors in North American pharmaceutical channels.
- Manufacturing:Original equipment manufacturers integrate intelligent packaging for inbound component tracking and outbound finished goods authentication.
Healthcare anchors premium pricing; Logistics is gaining share fastest through operational cost compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene vinyl alcohol resin supply from Asian petrochemical complexes shapes converter economics across major demand centers. Pharmaceutical serialization mandates and EU packaging waste directives are accelerating regional divergence in substrate qualification timelines.
United States
FDA Drug Supply Chain Security Act deadlines drive unit-level traceability infrastructure across pharmaceutical distribution networks. The country's national pharmaceutical regulator enforces serialization requirements that elevate embedded sensor adoption in cold-chain logistics. Greater Boston anchors biologics distribution clusters where hospital systems specify machine-readable aggregation at case level.
Germany
Munich-Hamburg industrial corridors integrate RFID-enabled supply chains for pharmaceutical and dairy processors. EU Green Deal packaging regulations and REACH substance restrictions force parallel transitions in material substitution and electronics integration. Bavarian dairy processors face steep 2025 compliance curves for biodegradable substrate adoption in modified atmosphere packaging lines.
India
CDSCO alignment with FDA serialization standards creates demand for machine-readable secondary packaging in bulk generic pharmaceutical exports. The country's national pharmaceutical regulator mandates traceability infrastructure that mirrors US requirements. Maharashtra pharmaceutical clusters around Mumbai and Pune are retrofitting lines for RFID-integrated export packaging.
China
Domestic biologics expansion and NMPA serialization pilots drive temperature-sensitive packaging demand for monoclonal antibodies. The country's national pharmaceutical regulator is implementing traceability standards that converge with international norms. Yangtze River Delta pharmaceutical manufacturing zones are deploying time-temperature indicators across extended distribution chains.
Netherlands
Benelux pharmaceutical distributors pilot printed graphene humidity sensors on corrugated fiberboard at pallet level. ECHA REACH restrictions on microplastics accelerate fluoropolymer phase-out in barrier films for meat preservation. Randstad logistics hubs are eliminating separate data logger procurement through embedded sensing architectures.
Intelligent Packaging Market Competitive Environment
Global majors compete with regional champions across substrate technology and regulatory compliance capabilities. The vendor base stratifies into three tiers: integrated material-science conglomerates with captive polymer supply, specialized converters focused on RFID integration, and emerging paper-based smart packaging specialists. Electronics-packaging hybrid capability scarcity concentrates premium positioning among players with embedded systems engineering depth. Competitive moves center on M&A for antenna design expertise and capacity expansion in biodegradable substrate lines.
Within the integrated material-science tier, Amcor plc and Sealed Air Corporation exemplify scale-driven positions spanning barrier film and active packaging technologies. Avery Dennison Corporation occupies a specialist position in adhesive-coated RFID inlay production. Mondi Group anchors the fiber-based smart packaging vector, competing against plastic incumbents through European paper-based production lines.
| Leading Market Players |
|---|
| Amcor plc |
| Avery Dennison Corporation |
| Sealed Air Corporation |
| 3M Company |
| Mondi Group |
| Smurfit Kappa Group |
| Berry Global Inc. |
| Constantia Flexibles |
| International Paper Company |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging waste directives and FDA serialization mandates are forcing converters to dual-source biodegradable substrates and RFID inlays simultaneously, compressing procurement timelines while elevating qualification costs across substrate tiers.
Pricing Analysis
Warranty and data-service bundling now separates premium converter relationships from transactional supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and serialization integration depth. Pricing pressure stems from NFC inlay yield scrap rates above 15% at sub-scale volumes. Mid-tier food and beverage brands exhibit highest price sensitivity; pharmaceutical cold-chain operators accept premium positioning for traceability assurance.
Supply Chain Analysis
Dual-sourcing mandates from German pharmaceutical and dairy processors require simultaneous qualification of Asian and European polymer suppliers. Feedstock concentration in China, South Korea, and Japan shapes ethylene vinyl alcohol resin availability. Copper antenna etching and semiconductor chip supply rest on Taiwan and South Korea fabrication capacity. Single-source vulnerability runs through Asian petrochemical complexes for barrier films. Distribution feeds from converter lines through third-party logistics hubs to hospital systems and retail pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent packaging is becoming a vertical-integration race where converters must capture upstream polymer supply or downstream data-service revenue to defend margin pools.
For Market Incumbents: To counter Asian petrochemical feedstock volatility, secure captive supply of biodegradable substrates through backward integration into European pulp networks or long-term offtake agreements with certified composting-grade fiber suppliers. Simultaneously embed serialization data platforms to convert one-time packaging sales into recurring pharmaceutical compliance service contracts. For New Entrants and Emerging Players: Begin with smartphone-native NFC authentication for premium cosmetics and organic food verticals where brand provenance commands price premiums. Target French and Benelux markets where direct-to-consumer verification displaces dedicated scanner infrastructure. Pursue pilot-to-scale contracting with mid-sized dairy processors facing 2025 EU Green Deal compliance deadlines. For Investors and Strategic Acquirers: The window for entry favors electronics-packaging hybrid specialists with embedded systems engineering depth and existing EN 13432 composting certification. Long-term viability hinges on antenna design expertise and high-speed folding-carton integration capability. Watch for inflection when NFC tag costs approach passive barcode parity in mid-tier food and beverage procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Substrates | Captive fiber supply insulates converters from EU Green Deal plastic substitution mandates. |
| Antenna Design Specialist Acquisition | Embedded systems engineering scarcity concentrates premium positioning among hybrid-capable players. |
| Serialization Data Platform Launch | Recurring compliance service contracts shift converter economics toward pharmaceutical long-term relationships. |
| High-Speed Folding-Carton Line Retrofit | RFID inlay integration at pharmaceutical throughput rates unlocks FDA-mandated unit-level traceability contracts. |
| Industrial Composting Certification Program | EN 13432 validation opens EU pharmaceutical secondary packaging procurement blocked to plastic incumbents. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with packaging converters, pharmaceutical supply chain directors, RFID inlay manufacturers, and dairy processing procurement leads. FDA DSCSA guidance documents, EMA serialization requirements, EU Green Deal implementation texts, and REACH candidate list updates provided regulatory boundary conditions. Bottom-up volume builds across substrate types triangulated against top-down market sizing from customs trade flows.
Granularity extended to product type, application vertical, material substrate, and end-user data integration maturity across the analysis window. Pharmaceutical serialization deadlines and EU packaging waste compliance curves supplied segment-specific growth anchors. CAGRs derived from slope-matching historical adoption patterns to regulatory mandate timelines, with cross-validation against converter capacity expansion announcements.
Underlying measurement precision varies by segment; pharmaceutical cold-chain and German dairy processing carry tighter precision than emerging cosmetics NFC pilots. Forecasts reflect assumptions about semiconductor cost decline curves and composting certification velocity. Deviation in EU Green Deal enforcement timing or REACH substance list expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market