
 Multi-Sensory Packaging Market | 2026-2036
Multi-Sensory Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Sensory Packaging Market Foresight
Subscription-based packaging redesign services is realigning how brands refresh tactile and olfactory touchpoints without full line overhauls. ProAmpac leverages its flexible film expertise to embed micro-encapsulated aroma layers for food clients. Sealed Air anchors North American scale in automated scent-application equipment for e-commerce unboxing. Mondi Group differentiates through paperboard-based haptic textures that replace plastic laminates in premium segments.
Multi-sensory packaging integrates engineered substrates, micro-encapsulation chemistry, and digital triggers to deliver tactile, olfactory, auditory, or augmented visual stimuli at the point of consumer interaction. Flexible packaging dominates volume due to compatibility with scratch-and-sniff films and pressure-activated sound chips, though rigid formats command margin pools in spirits and cosmetics where structural heft signals quality. Augmented reality features represent the fastest-expanding feature category as smartphone-native consumers scan codes for immersive brand storytelling, while aroma release maintains maturity in food and beverage applications where olfactory cues directly influence purchase intent.
The EPA regulates volatile organic compound emissions from scent-releasing adhesives under TSCA, while the EU REACH framework restricts certain fragrance allergens in packaging materials that contact food or skin. FDA food-contact notification requirements determine which aroma compounds migrate legally into edible product zones, creating compliance bottlenecks for cross-border launches. Stakeholders must monitor evolving state-level extended producer responsibility laws and biopolymer certification standards as these will determine which multi-sensory material platforms retain market access.
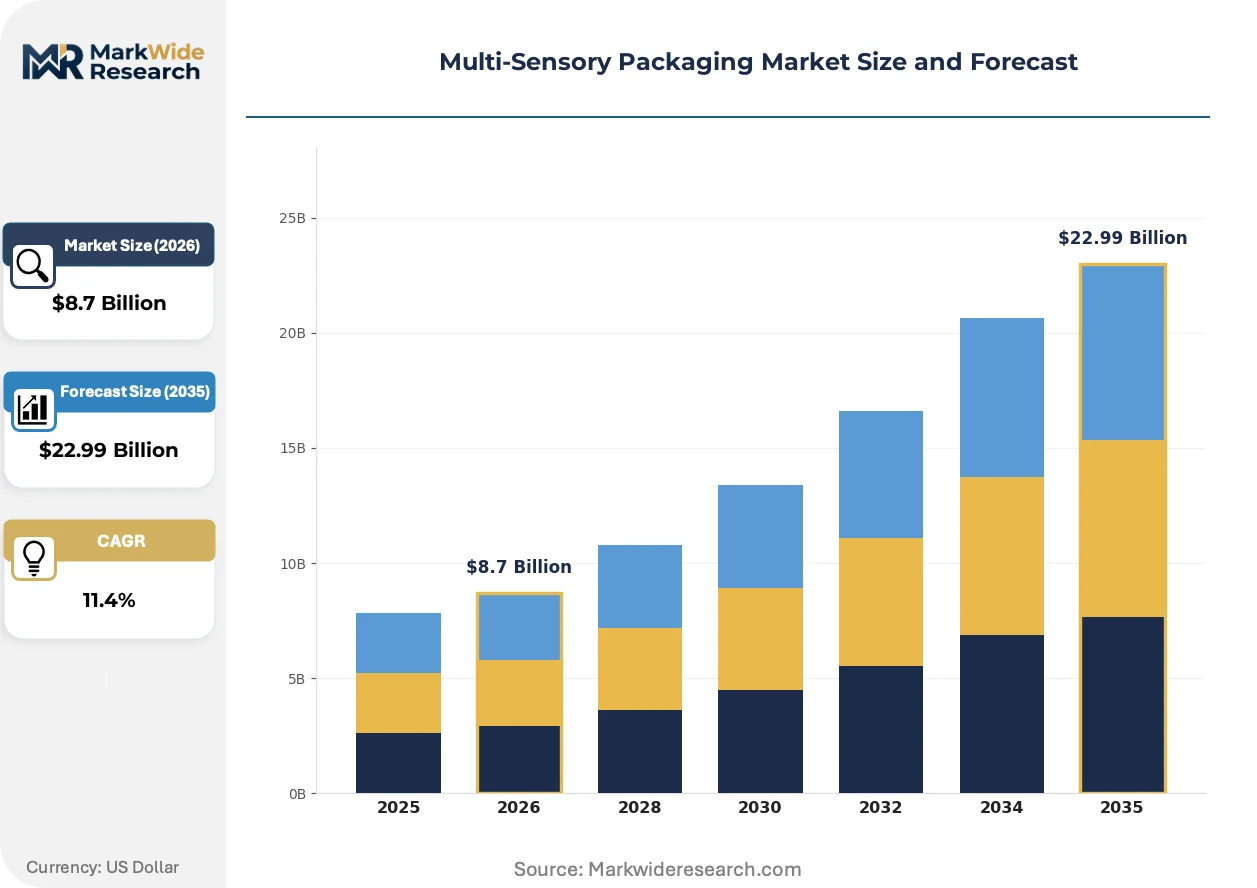
Market Dynamics
Micro-encapsulation chemistry breakthroughs are collapsing cost curves for aroma-release films, enabling mid-market brands to deploy sensory layers previously reserved for luxury categories and compressing the premium-mass gap in packaging differentiation.
Growth Catalysts
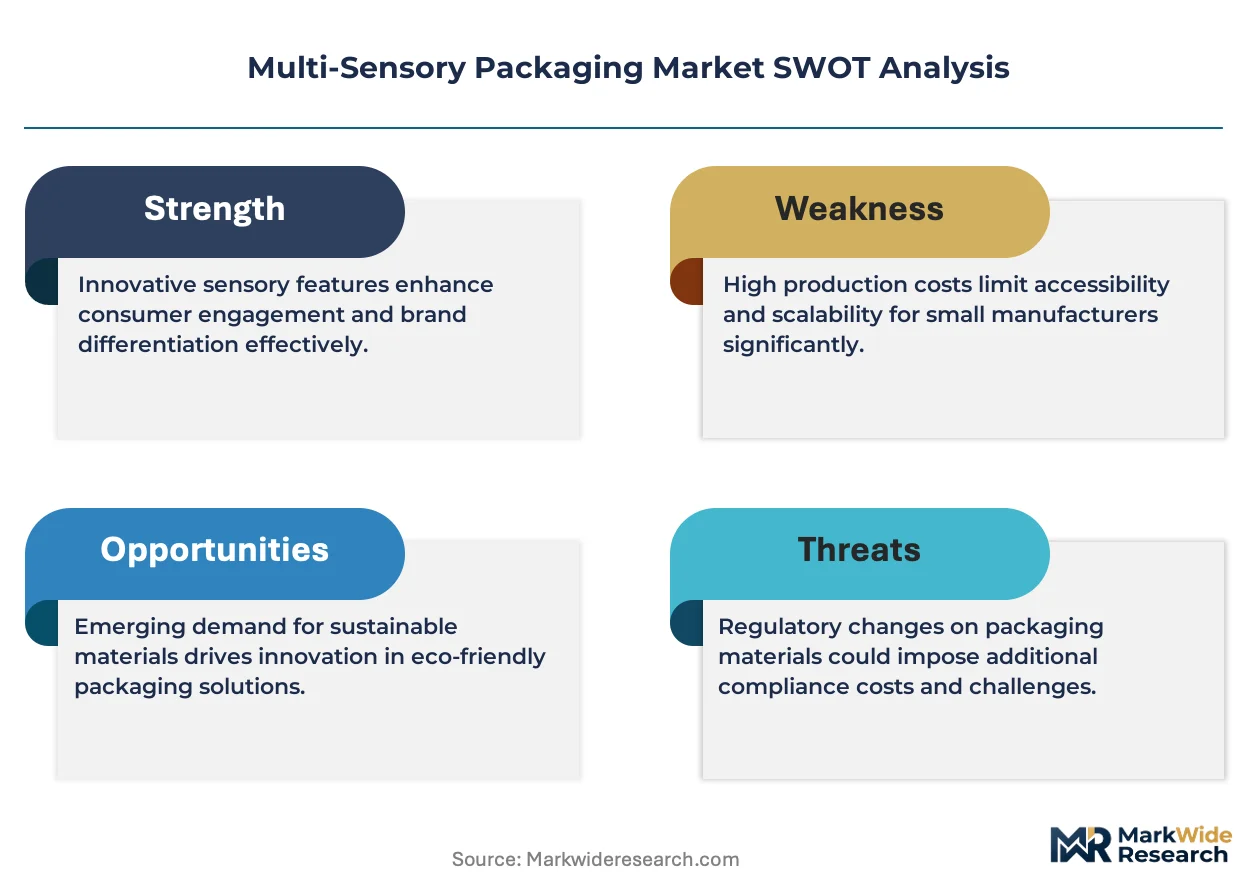
- EU REACH fragrance allergen restrictions:Compliance investments by German converters are creating certified supply pools that export-ready brands now prioritize for cross-border launches.
- Flexible film compatibility:Scratch-and-sniff and pressure-activated substrates integrate with existing high-speed filling lines, removing retrofit barriers for food and beverage packagers.
- Cosmetics unboxing sequences:Premium beauty brands embed haptic textures and timed aroma release to strengthen brand recall and social media shareability.
Market Restraints
- Volatile organic compound adhesives:EPA TSCA emission controls on scent-releasing chemistries raise formulation costs and limit supplier options in North American production.
- Biopolymer certification gaps:Inconsistent compostability standards across national bodies fragment material platforms and complicate multi-sensory substrate selection.
- Extended producer responsibility laws:State-level packaging waste fees in multiple US jurisdictions add compliance overhead to multi-layer sensory constructions.
Strategic Opportunities
- India PLI scheme for packaging machinery:Domestic equipment subsidies could localize micro-encapsulation coating capacity for Asian fragrance and spice exporters.
- Augmented reality code integration:Smartphone-native consumers scanning packaging for immersive storytelling creates white space beyond static olfactory cues.
- Subscription box channel:Monthly unboxing experiences reward predictable sensory refresh cycles without full line overhauls.
Industry Challenges
- Cross-functional formulation expertise:Chemists, packaging engineers, and brand marketers must align on sensory trigger timing and substrate compatibility.
- Legacy line integration:Retrofitting existing flexo or gravure presses for scent-application modules requires downtime and skilled technician availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Sensory Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Resealable Packaging, Eco-Friendly Packaging Material: Plastic, Glass, Metal, Paperboard Feature: Augmented Reality, Sound Activation, Textures, Aroma Release End User: Food & Beverage, Cosmetics, Pharmaceuticals, Consumer Electronics |
| Companies Covered | ProAmpac, Filigram, Amcor, AptarGroup, Packhelp, Sealed Air, Mondi Group, Footprint, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Sensory Packaging Market Shifts & Advancements
Digital trigger technologies are merging with engineered substrates to transform passive packaging into interactive consumer touchpoints, reshaping how brands justify premium price positions through measurable engagement metrics.
Micro-encapsulation is consolidating as the dominant aroma-delivery mechanism for food-contact applications, replacing bulk fragrance impregnation with timed-release precision. Mid-market snack and ready-meal brands in Germany and the United States are adopting these films at accelerating rates as unit economics improve. This consolidation is compressing the supplier base toward chemical specialists with FDA food-contact notification and EU REACH dual certification.
REACH fragrance allergen restrictions are tightening substrate safety requirements for skin-contact and food-contact packaging across European supply chains. Formulators must now document absence of restricted compounds in aroma layers, extending certification timelines by six to twelve months for cross-border launches. Cosmetics and premium spirits segments are responding by consolidating supplier relationships with ECHA-registered compounders.
Buyer procurement patterns are fragmenting as brand managers seek modular sensory upgrades without capital-intensive line replacements. Subscription packaging redesign services are displacing traditional three-year refresh cycles in North American e-commerce channels. This shift is most visible in direct-to-consumer beauty and specialty food verticals where unboxing video performance directly influences repurchase rates.
Multi-Sensory Packaging Market Segmentation
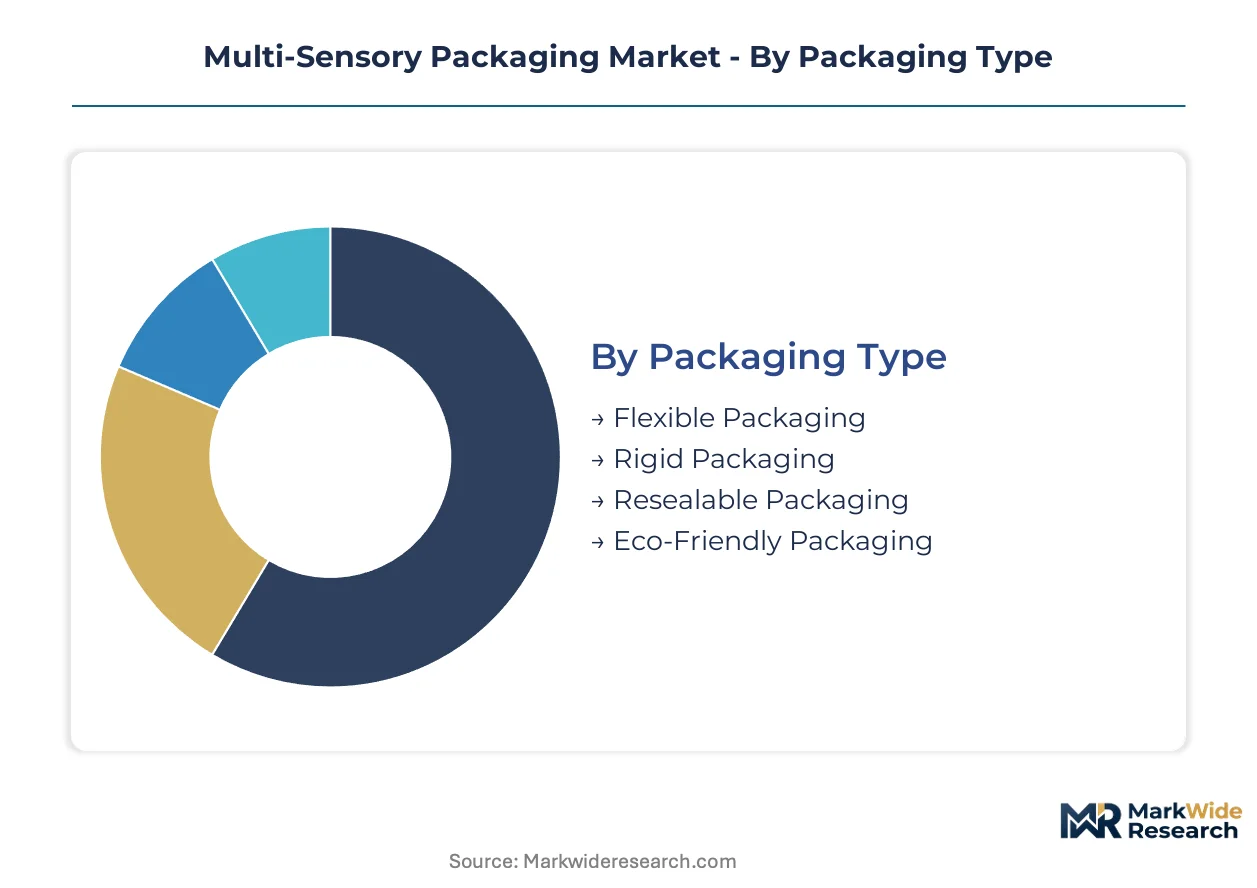
Multi-sensory packaging segments reflect divergent technical requirements for substrate compatibility, regulatory clearance, and consumer interaction depth. Brand procurement teams navigate trade-offs between flexible film versatility and rigid format premium positioning when selecting sensory integration architectures.
Packaging Type:
Standalone flexible formats dominate high-volume deployment, while rigid and resealable systems embed sensory layers into structural permanence.
- Flexible Packaging:Polymer substrates accommodate micro-encapsulated aroma films and pressure-activated sound chips through standard lamination processes. German food exporters favor these formats for REACH-compliant scratch-and-sniff layers in snack applications.
- Rigid Packaging:Structural heft in glass and thick-walled plastics enables haptic texture molding and embedded AR trigger placement. Spirits and premium cosmetics brands specify these formats where unboxing weight signals quality authenticity.
- Resealable Packaging:Zip-lock and slider mechanisms integrate scent-preservation chambers that release aroma upon each opening cycle.
- Eco-Friendly Packaging:Biopolymer and recyclable paperboard substrates carry compostable aroma layers certified under fragmented national standards.
Volume placements concentrate in Flexible Packaging; the faster expansion belongs to Eco-Friendly Packaging.
Material:
Substrate selection determines which sensory chemistries achieve regulatory clearance and which consumer touchpoints remain technically feasible.
- Plastic:Multi-layer coextrusions host micro-encapsulation coatings with FDA food-contact notification pathways already established. North American converters exploit this regulatory maturity for rapid product launches.
- Paperboard:Mondi Group and comparable specialists engineer tactile surface embossing that replaces plastic laminates in premium unboxing sequences. EU single-use plastic directives accelerate brand migration toward these fiber-based alternatives.
- Glass:In-mold labeling and direct screen printing enable visual and haptic layering without substrate flexibility.
- Metal:Aerosol-compatible aroma release and temperature-reactive coatings suit beverage and personal care can formats.
Plastic substrates capture the largest installed base; paperboard formats are climbing the fastest as sustainability mandates tighten.
Feature:
Sensory feature deployment spans passive environmental triggers and active digital engagement requiring consumer device participation.
- Augmented Reality:Smartphone-scannable codes overlay immersive brand storytelling onto physical packaging without substrate modification. Direct-to-consumer beauty brands measure scan rates as direct engagement metrics justifying premium positioning.
- Aroma Release:Micro-encapsulation chemistry delivers timed olfactory cues through scratch, peel, or pressure activation. Food and beverage applications concentrate in Germany and the United States where FDA and REACH dual certification streamlines cross-border supply.
- Sound Activation:Pressure-triggered audio chips embed in rigid gift boxes and seasonal confectionery for momentary auditory surprise.
- Textures:Surface embossing and soft-touch coatings provide sustained haptic differentiation in cosmetics and spirits segments.
Aroma Release commands the deepest regulatory investment; Augmented Reality features are gaining share fastest among smartphone-native demographics.
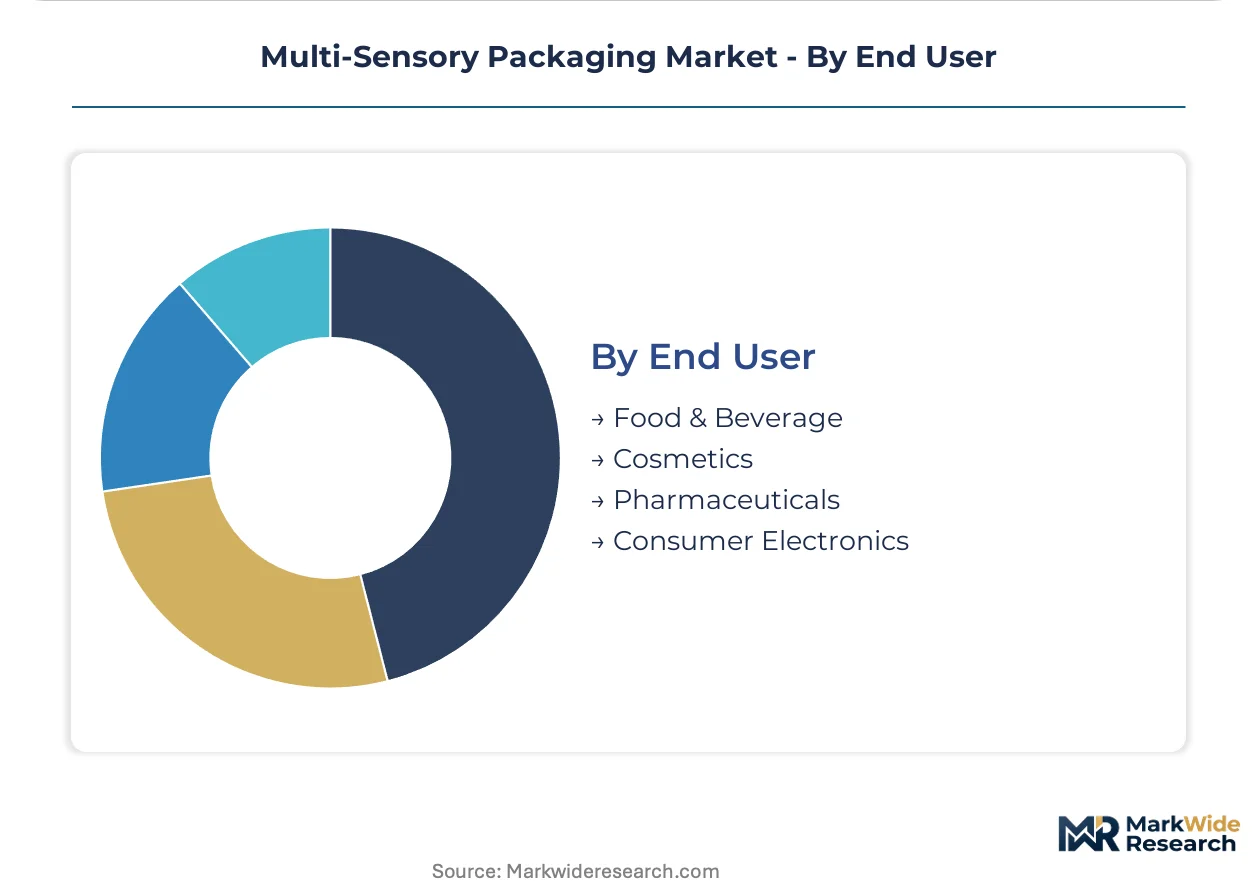
End User:
End-use verticals impose distinct sensory timing requirements, from immediate purchase influence to extended unboxing narrative construction.
- Food & Beverage:Olfactory cues directly influence impulse purchase intent at retail shelf edge. Mid-market snack brands adopt micro-encapsulated films as unit economics improve.
- Cosmetics:Premium beauty houses orchestrate multi-stage unboxing sequences combining haptic textures, timed aroma release, and AR code reveals. Social media shareability drives repurchase rates in subscription box channels.
- Pharmaceuticals:Compliance-heavy sector limits sensory innovation to tamper-evident textures and child-resistant haptic cues rather than promotional layers.
- Consumer Electronics:Protective packaging incorporates sound activation and premium surface feel to justify high-value product positioning.
Food & Beverage applications absorb the highest unit volumes; Cosmetics segments pursue the steepest expansion trajectory through subscription channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German packaging machinery clusters, while consumption spreads across North American e-commerce channels and Asian export markets. Supply-side capacity in flexible film coating and micro-encapsulation chemistry lags behind brand demand for REACH-compliant and FDA-cleared sensory substrates.
United States
E-commerce unboxing experiences drive demand for pressure-activated sound chips and haptic textures in subscription beauty boxes. EPA TSCA emission controls on scent-releasing adhesives raise formulation costs for domestic converters. Chicago and New Jersey packaging corridors host automated scent-application equipment serving direct-to-consumer brands.
Germany
REACH fragrance allergen restrictions compel converters to document absence of restricted compounds in aroma layers. ECHA-registered compounders in the Rhine-Ruhr and Bavarian industrial zones export certified supply pools to cross-border brands. Stuttgart-area machinery builders integrate micro-encapsulation coating modules into existing flexo presses.
China
Dual carbon goals and evolving GB standards on food-contact materials constrain volatile organic compound emissions from packaging adhesives. Yangtze River Delta converters develop biopolymer-compatible aroma layers for domestic snack brands. Shenzhen electronics packaging clusters experiment with AR-triggered unboxing for consumer electronics exports.
India
PLI scheme subsidies for packaging machinery could localize micro-encapsulation coating capacity for fragrance and spice exporters. FSSAI food-contact regulations determine which aroma compounds migrate legally into edible product zones. Maharashtra and Gujarat industrial corridors attract investment in flexible film lamination for sensory applications.
Japan
METI standards on sustainable packaging accelerate brand migration toward fiber-based haptic alternatives to plastic laminates. Premium cosmetics houses in the Kanto region orchestrate multi-stage unboxing sequences combining timed aroma release with soft-touch coatings. Osaka-area converters specialize in rigid gift box formats with embedded auditory features.
Multi-Sensory Packaging Market Competitive Landscape
Top-tier vendors anchor flexible film and rigid format supply, while mid-tier specialists occupy niche sensory technology segments. The vendor base organizes around three strategic archetypes: integrated packaging conglomerates with cross-material portfolios, chemical specialists with dual REACH-FDA certification, and digital-physical hybrid providers layering AR triggers onto conventional substrates. Dominant competitive moves include backward integration into micro-encapsulation chemistry and geographic expansion through machinery partnerships in high-growth Asian markets.
Within the integrated packaging tier, ProAmpac and Sealed Air exemplify scale-driven positions spanning flexible film expertise and automated equipment deployment. Mondi Group occupies a distinct fiber-based specialization, representing the migration toward paperboard haptic textures that replace plastic laminates under EU single-use plastic directives. These three anchors illustrate how competitive positioning fragments across material platforms rather than consolidating around unified sensory technology stacks.
| Leading Market Players |
|---|
| ProAmpac |
| Filigram |
| Amcor |
| AptarGroup |
| Packhelp |
| Sealed Air |
| Mondi Group |
| Footprint |
| Tetra Pak |
| Others |
Supply & Pricing Matrix
Micro-encapsulation coating technology is collapsing production cost curves for aroma-release films while simultaneously concentrating supply among REACH-FDA dual-certified compounders in Germany and the United States, reshaping who captures margin in multi-sensory substrate procurement.
Pricing Analysis
Margin tightening in mid-market flexible packaging reflects micro-encapsulation chemistry commoditization as German machinery builders license coating modules to Asian converters. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered compounders from uncertified regional suppliers, with FDA food-contact notification tiers commanding substantial premiums. Price differentiation hinges on certification grade and volume scale, with subscription-box beauty brands showing lowest price sensitivity due to unboxing video ROI metrics.
Supply Chain Analysis
REACH and FDA dual-certification gating restricts viable aroma-layer suppliers to Rhine-Ruhr compounders and Chicago-area chemical specialists, creating bottleneck conditions for cross-border launches. Raw material dependencies center on specialty polymer resins, micro-encapsulation shell chemistries, and pressure-sensitive adhesive substrates. Single-source vulnerability concentrates in ECHA-registered fragrance compounders, with tariff exposure rising on Chinese biopolymer alternatives. Distribution runs through converter-direct relationships and packaging machinery OEM bundled supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-sensory packaging is transitioning from static olfactory cues to AR-integrated digital triggers, with micro-encapsulation chemistry replacing bulk fragrance impregnation as the dominant production method across food-contact applications.
For Market Incumbents: Deploy backward integration into micro-encapsulation chemistry to defend against Asian machinery cost advantages. Capture ECHA-registered compounder relationships before certification timelines extend further. Anchor capacity in Stuttgart-area machinery corridors where flexo press retrofit expertise concentrates. For New Entrants and Emerging Players: Mid-market snack brands in India and Southeast Asia represent the most penetrable buyer archetype, underserved by REACH-certified supply pools. Localize coating capacity under PLI scheme subsidies to serve fragrance and spice exporters. Lead with subscription-box channel partnerships rather than retail shelf disruption. For Investors and Strategic Acquirers: Re-rating potential sits with dual-certified chemical specialists given EU fragrance allergen restriction tightening. Five-to-ten year viability favors compounders with established FDA notification pathways over equipment-only players. Watch for India PLI scheme localization announcements as inflection signals for Asian supply reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Micro-Encapsulation Chemistry | Captures margin pools from REACH-FDA dual-certified compounders serving cross-border food exporters. |
| AR Code Integration Partnership | Enables smartphone-native engagement metrics that justify premium positioning for direct-to-consumer beauty brands. |
| PLI Scheme Machinery Localization | Positions coating capacity near Maharashtra and Gujarat fragrance exporters under Indian equipment subsidies. |
| Subscription Box Channel Exclusive | Locks predictable sensory refresh cycles without capital-intensive line overhauls for North American e-commerce. |
| Biopolymer Certification Investment | Secures market access under fragmented national compostability standards for eco-friendly packaging tiers. |
Research Methodology
Multi-period observation of micro-encapsulation coating adoption rates, REACH certification timelines, and FDA food-contact notification volumes anchored the trend analysis, supplemented by interviews with packaging machinery OEM product managers, flexible film procurement leads at snack and cosmetics brands, ECHA regulatory affairs specialists, and flexo press operations directors. Secondary validation drew from SEC filings of listed packaging conglomerates, ECHA substance registration databases, FDA food-contact notification logs, and German packaging machinery association production statistics. Bottom-up unit economics triangulated against top-down market sizing across material and feature segments.
Input-output matrix modeling structured projections across packaging type, material substrate, sensory feature, and end-use vertical dimensions throughout the forecast period. CAGRs derived from segmented growth rate assumptions weighted by base-year volume shares. Industry-specific forecast inputs included micro-encapsulation chemistry cost curve trajectories and smartphone AR adoption penetration curves by demographic cohort.
Revisions become necessary when EU REACH fragrance allergen restrictions expand compound scope, FDA food-contact notification pathways stall for novel aroma chemistries, or India PLI scheme subsidies accelerate Asian machinery localization. A model refresh is warranted upon material change in biopolymer certification standard harmonization across major export markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Active Packaging Market