
 Isothermal Packaging Market | 2026-2036
Isothermal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Isothermal Packaging Market Analysis
Phase-change material (PCM) integration is reshaping thermal protection architecture for temperature-sensitive payloads. Pelican BioThermal leverages proprietary PCM formulations to sustain payload stability across multi-day transit lanes. Sonoco ThermoSafe anchors North American pharmaceutical distribution through reusable shipper systems. Cryopak specializes in single-use vacuum-insulated panel solutions for last-mile vaccine delivery.
Isothermal packaging comprises engineered thermal barriers—typically polyurethane foam, expanded polystyrene, or vacuum-insulated panels combined with gel packs or PCM—to maintain defined temperature bands between minus eighty degrees Celsius and plus twenty-five degrees Celsius for forty-eight to one hundred twenty hours. The pharmaceutical application commands premium positioning as biologics and cell therapies require validated cold chain integrity from manufacture to administration. Polyurethane material types capture expanding share where thinner profiles and superior thermal resistance reduce dimensional weight charges in air freight. E-commerce end users represent the fastest-growing channel as direct-to-patient specialty pharmacy models proliferate.
The FDA enforces strict temperature documentation through 21 CFR 211 for drug distribution, while the EU GDP guidelines mandate qualified equipment and continuous monitoring for medicinal products shipped within member states. The International Safe Transit Association (ISTA) publishes thermal transit test protocols that shape product qualification standards across North America and Europe. Stakeholders must weigh reusable system economics against single-use convenience as carbon accounting pressures intensify and reverse logistics networks mature.
Market Dynamics
The EU F-Gas Regulation is forcing rapid refrigerant phase-down across temperature-controlled logistics networks. Biopharmaceutical cold chain integrity requirements are simultaneously tightening payload validation standards. These dual pressures are compressing equipment replacement cycles and reshaping supplier qualification protocols.
Growth Catalysts
- Biologics proliferation:Cell therapies and monoclonal antibodies require validated minus eighty to plus twenty-five Celsius stability corridors. Pharmaceutical distributors are retrofitting fleets to handle these temperature bands.
- EU F-Gas Regulation:The mandated hydrofluorocarbon phase-down is accelerating replacement of high-GWP refrigerants in insulated shipping containers. Equipment manufacturers are qualifying natural refrigerant alternatives.
- Direct-to-patient pharmacy models:Specialty pharmacies are bypassing wholesale distribution to ship temperature-sensitive medications to residential addresses. This channel requires last-mile thermal protection systems.
Market Restraints
- Polyurethane feedstock volatility:Isocyanate and polyol prices fluctuate with crude oil derivatives. Thinner-profile foam panels depend on these inputs for thermal resistance.
- Vacuum-insulated panel supplier concentration:Core manufacturing for ultra-low-temperature shippers clusters in East Asian foundries. Disruption risks concentrate in this geography.
- Reusable system economics:Reverse logistics infrastructure for returnable thermal shippers remains underdeveloped outside Germany and the Netherlands. Capital recovery timelines extend beyond single-use alternatives.
Strategic Opportunities
- Indian pharmaceutical distribution:CDSCO cold chain guidelines are tightening for vaccine and biologic transport. Domestic manufacturers lack qualified thermal packaging capacity.
- Phase-change material convergence with IoT:Embedded temperature loggers are integrating with PCM formulations to provide real-time payload stability data. This enables predictive intervention.
- Carbon accounting mandates:EU CSRD reporting requirements are elevating lifecycle emissions scrutiny. Reusable shipper providers can monetize carbon reduction claims.
Industry Challenges
- ISTA thermal certification timelines:Protocol validation for new shipper designs requires extended transit simulation cycles. Product launches face twelve-to-eighteen-month qualification periods.
- PCM formulation IP fragmentation:Proprietary eutectic salt and paraffin blends are locked behind competing patent estates. License negotiations complicate product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isothermal Packaging Market |
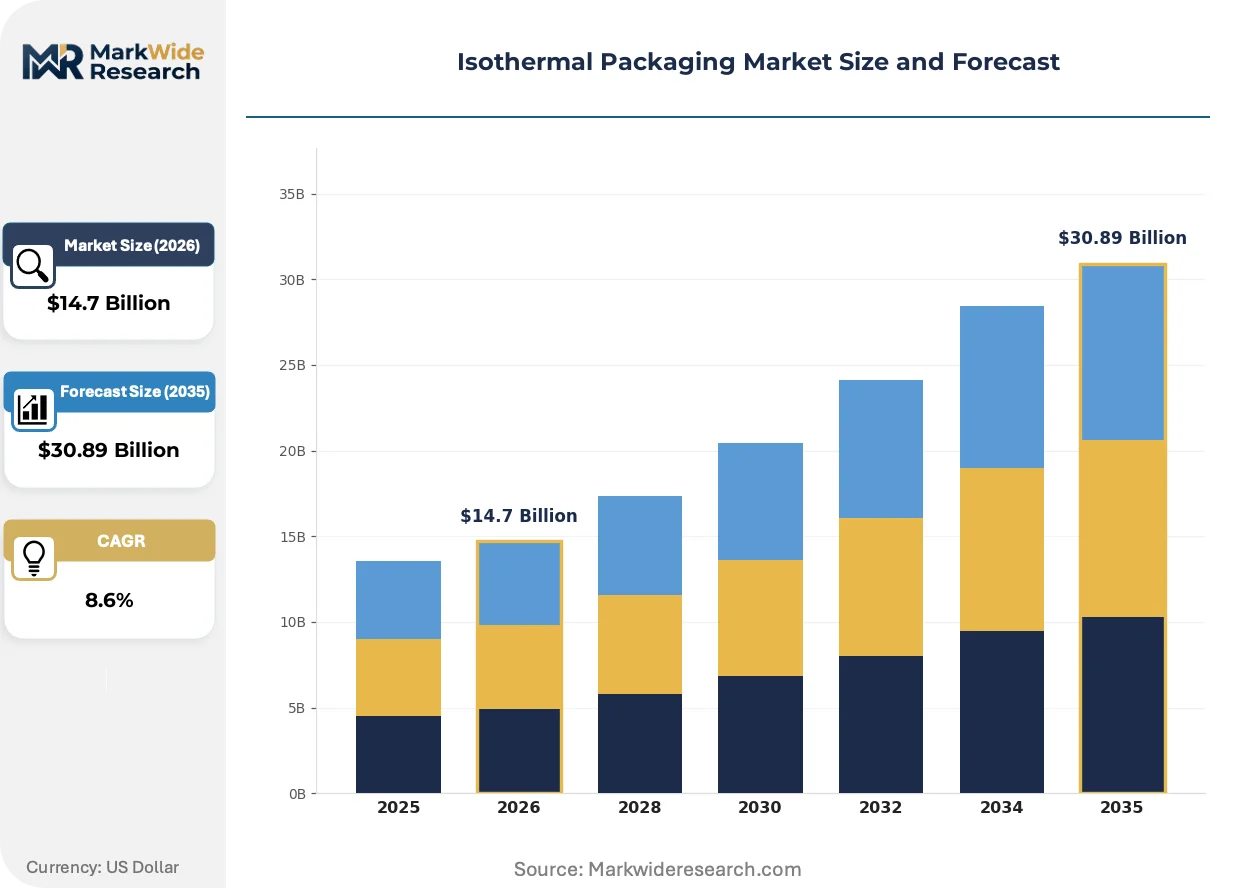
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polystyrene, Polyurethane, Cardboard Application: Pharmaceuticals, Food & Beverage, Cosmetics, Electronics Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers End User: Hospitals, Restaurants, Supermarkets, E-commerce |
| Companies Covered | Pelican BioThermal, Sonoco ThermoSafe, Cryopak, Sofrigam, Thermo Fisher Scientific, Berry Global, Sealed Air Corporation, Tempack, Isovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isothermal Packaging Market Emerging Trajectories
Material science advances are compressing thermal protection profiles while extending duration windows. Regulatory chemistry restrictions are forcing refrigerant and insulation reformulations. Digital integration is transforming passive thermal systems into monitored, intervention-capable assets.
Vacuum-insulated panel technology is migrating from ultra-low-temperature vaccine shippers into standard two-to-eight Celsius pharmaceutical lanes. Biologics distributors are adopting these thinner-profile solutions to reduce dimensional weight charges in air freight. The technology is migrating from premium specialty applications into mainstream cold chain infrastructure.
The EU F-Gas Regulation is banning hydrofluorocarbons with GWP above one hundred fifty in new mobile refrigeration equipment. Equipment manufacturers are qualifying hydrocarbon and carbon dioxide alternatives for insulated shipping containers. Pharmaceutical logistics providers in Germany and France face accelerated fleet replacement schedules.
Hospital and clinic buyers are consolidating thermal packaging procurement under group purchasing organizations. Specialty pharmacy networks are displacing fragmented supplier relationships with contracted reusable shipper programs. This concentration is most visible in United States oncology drug distribution channels.
Isothermal Packaging Market Segmentation
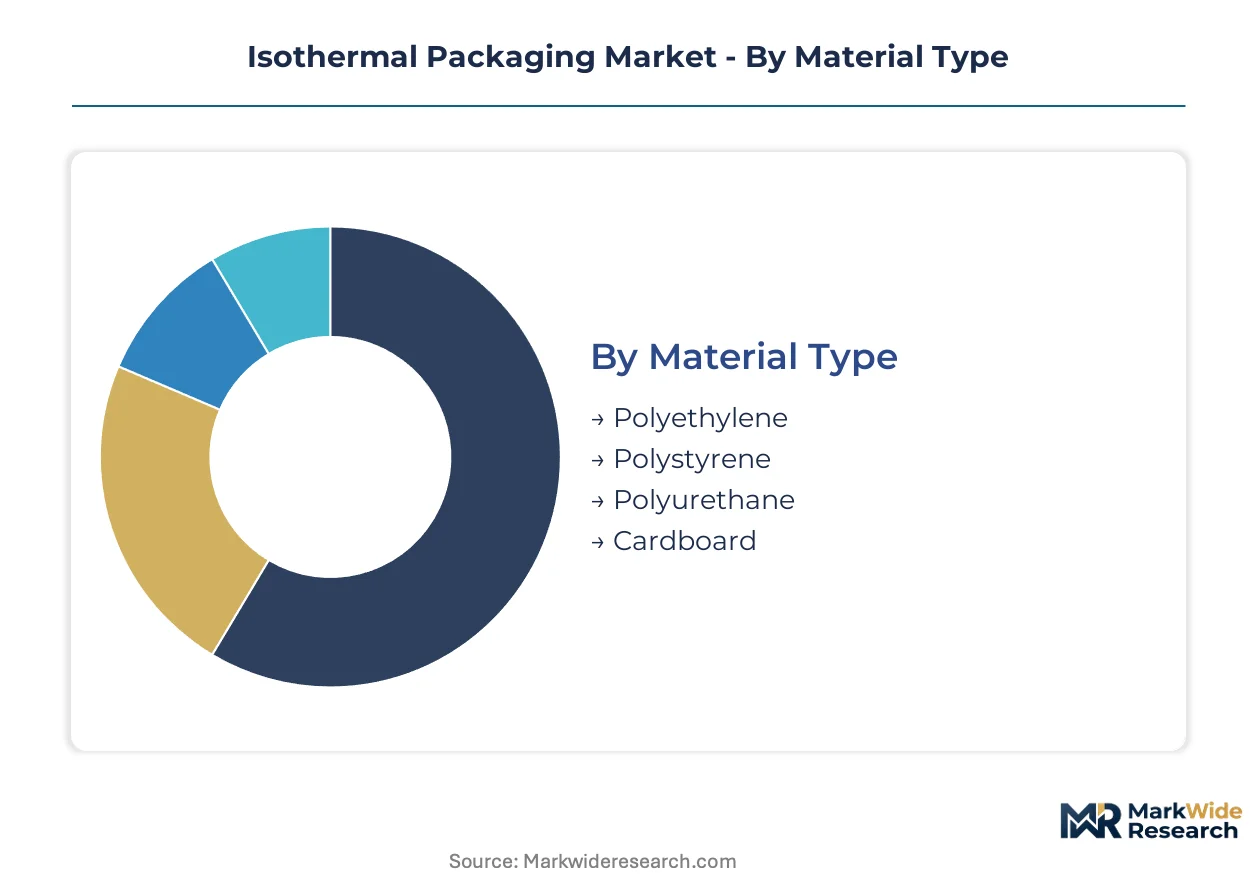
Material selection dictates thermal performance duration and cost recovery cycles across isothermal packaging deployments. Application-specific validation requirements create divergent replacement frequencies, with pharmaceutical shippers demanding shorter recertification intervals than food service equivalents.
Material Type:
Polyurethane and vacuum-insulated panels command extended replacement cycles due to durability, while cardboard and expanded polystyrene solutions turn over rapidly in single-use pharmaceutical lanes.
- Polyurethane:Closed-cell foam chemistry delivers superior thermal resistance in thinner profiles, enabling dimensional weight reduction for air freight. German pharmaceutical distributors specify polyurethane for validated two-to-eight Celsius lanes serving monoclonal antibody distribution.
- Polystyrene:Expanded polystyrene dominates single-use vaccine shippers where cost minimization outweighs reuse economics. Indian cold chain expansion relies heavily on polystyrene for last-mile vaccine delivery under CDSCO guidelines.
- Polyethylene:Rotomolded polyethylene shells protect reusable PCM-based shippers through thousands of handling cycles. The material resists cracking in ultra-low-temperature minus eighty Celsius applications.
- Cardboard:Corrugated fiberboard with metallized liners serves short-duration food delivery where thermal protection spans hours rather than days. E-commerce meal kit providers specify recyclable cardboard to meet EU packaging waste directives.
Polystyrene anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Margin structures diverge sharply across applications, with pharmaceutical validation requirements supporting premium pricing versus commoditized food service segments.
- Pharmaceuticals:Cell therapies and biologics demand validated temperature corridors from manufacture to administration. FDA 21 CFR 211 documentation requirements and EU GDP guidelines mandate continuous monitoring integration.
- Food & Beverage:Fresh protein and dairy distribution drives demand for multi-day thermal protection in refrigerated trucking lanes. Cold chain integrity failures trigger spoilage liability that shapes packaging specification.
- Cosmetics:Temperature-sensitive active ingredients in premium skincare require stable two-to-eight Celsius storage during transit. Direct-to-consumer beauty subscription boxes specify isothermal protection for summer delivery windows.
- Electronics:Lithium battery transport and temperature-sensitive semiconductor components require thermal buffering against ambient extremes. ISTA thermal protocols govern qualification for electronics logistics providers.
Pharmaceutical applications command the highest margin tier while food and beverage generates the greatest shipment velocity.
Distribution Channel:
Channel selection determines shipper returnability economics, with direct sales enabling reusable system deployment that online retail channels cannot support.
- Direct Sales:Pharmaceutical manufacturers contract directly with thermal packaging providers for qualified shipper programs. Long-term agreements amortize development costs across multi-year validation cycles.
- Wholesalers:Medical and food distribution wholesalers aggregate demand from fragmented buyer bases. Inventory pooling reduces per-unit qualification costs for mid-tier pharmaceutical distributors.
- Online Retail:Third-party marketplace sales of isothermal packaging concentrate in small-volume food service and consumer segments. Product qualification documentation varies widely across seller profiles.
- Offline Retail:Brick-and-mortar packaging suppliers serve immediate-need restaurant and catering procurement. Stock-and-sell economics favor standardized polystyrene and gel pack configurations.
Direct sales channels concentrate the highest-value contracts while online retail expands most quickly in small-format meal delivery.
End User:
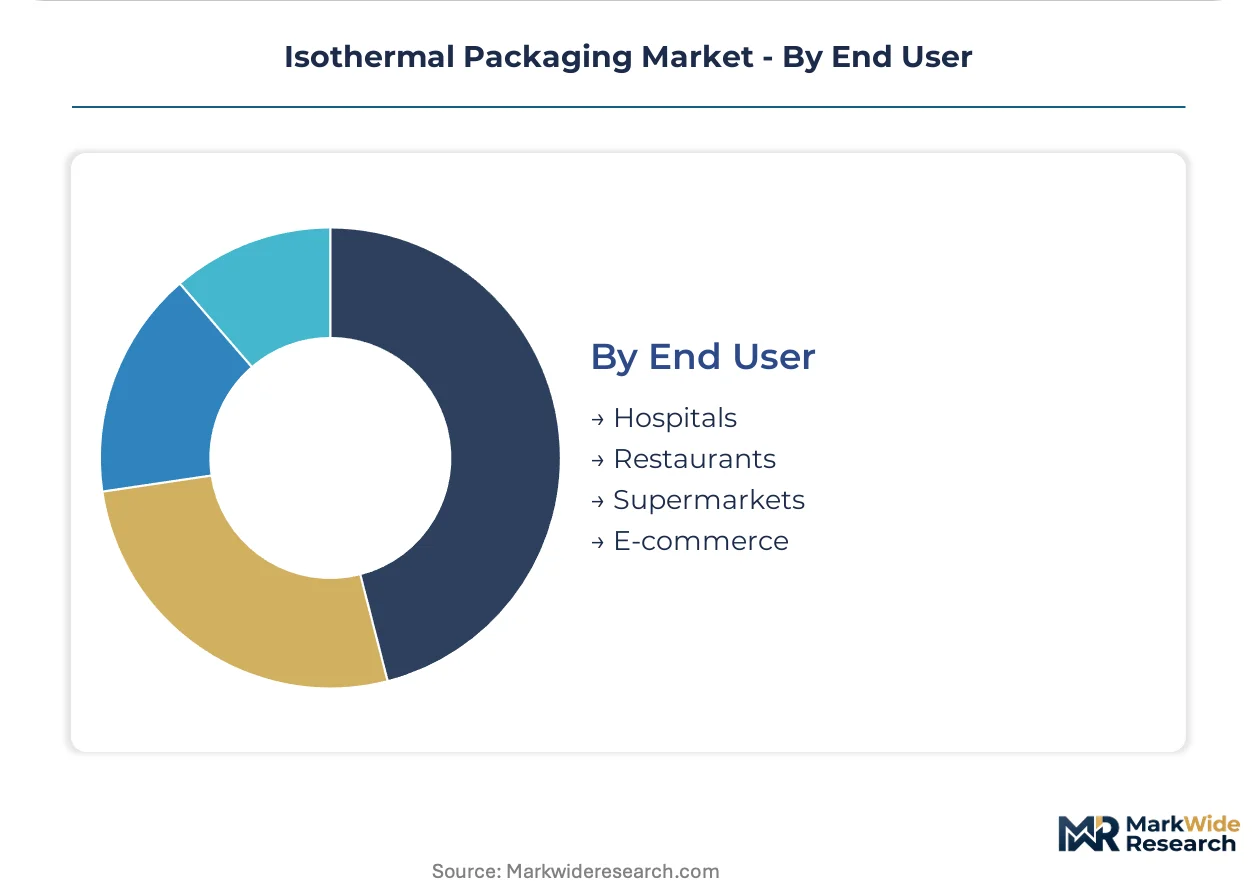
Hospital and supermarket procurement patterns favor contracted reusable programs, whereas restaurant and e-commerce operators prioritize single-use convenience.
- Hospitals:Pharmacy departments within hospital systems consolidate thermal packaging procurement under group purchasing organizations. Oncology drug handling protocols specify validated shipper performance.
- E-commerce:Direct-to-patient specialty pharmacy models bypass wholesale distribution entirely. Last-mile residential delivery requires thermal protection adapted to uncontrolled ambient exposure.
- Supermarkets:Click-and-collect grocery services deploy isothermal totes for curbside pickup of frozen and refrigerated categories. Return logistics infrastructure enables reusable system economics.
- Restaurants:Third-party delivery platform integration drives demand for short-duration thermal bags. Driver-owned equipment models displace operator-controlled packaging decisions.
Hospital systems anchor the qualification-intensive segment while e-commerce climbs the fastest on direct-to-patient pharmacy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distributors and specialty pharmacy networks concentrate procurement authority in markets with stringent cold chain regulations. Buyer archetypes span hospital group purchasing organizations, direct-to-patient pharmacy operators, and biologics manufacturers with validated shipper requirements.
Germany
Frankfurt and Munich host Europe's densest pharmaceutical distribution hub clustering, with cold chain logistics providers retrofitting fleets for monoclonal antibody transport. The EU F-Gas Regulation mandates hydrofluorocarbon phase-down in mobile refrigeration equipment, compressing equipment replacement cycles. Bavaria's thermal packaging manufacturers are qualifying natural refrigerant alternatives for insulated shipping containers ahead of compliance deadlines.
United States
FDA 21 CFR 211 documentation requirements enforce strict temperature monitoring for drug distribution, driving demand for integrated data logger systems. Oncology drug handling protocols within hospital group purchasing organizations specify validated shipper performance for cell therapies. The Greater Boston biotech corridor anchors specialty pharmacy networks shipping temperature-sensitive medications direct-to-patient.
India
CDSCO cold chain guidelines are tightening for vaccine and biologic transport, exposing domestic capacity gaps in qualified thermal packaging. The PLI scheme incentives for pharmaceutical manufacturing are expanding production volumes without matching logistics infrastructure. Maharashtra's vaccine distribution networks rely on expanded polystyrene shippers for last-mile delivery under new regulatory mandates.
France
ANSM pharmaceutical distribution oversight aligns with EU GDP guidelines for continuous temperature monitoring of medicinal products. Paris-region biologics distributors are consolidating procurement under group purchasing organizations to amortize qualification costs. The Île-de-France cluster is accelerating adoption of vacuum-insulated panel technology to reduce air freight dimensional weight charges.
Japan
PMDA cold chain integrity standards for regenerative medicine products require validated minus eighty Celsius stability corridors for cell therapy transport. METI industrial policy supports domestic manufacturing of phase-change material formulations to reduce import dependency. The Kanto region's pharmaceutical logistics providers are integrating IoT-enabled temperature loggers with passive thermal protection systems.
Isothermal Packaging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented qualification tiers. The vendor base spans multinational packaging conglomerates with integrated cold chain divisions, mid-sized thermal engineering specialists, and regional fabricators serving single-use vaccine distribution. Three archetypes dominate: reusable system providers amortizing capital across reverse logistics networks, single-use disposable specialists optimizing for last-mile convenience, and integrated cold chain operators bundling packaging with logistics services. Competitive moves concentrate on strategic partnerships with pharmaceutical distributors and technology licensing for phase-change material formulations.
Within the reusable system tier, Pelican BioThermal and Sonoco ThermoSafe exemplify archetypes competing on validation depth and fleet recovery economics. Cryopak occupies a position among single-use specialists emphasizing vacuum-insulated panel configurations for ultra-low-temperature lanes. These three anchors represent divergent strategic postures on the reuse-versus-disposability spectrum that shapes procurement decisions across hospital and specialty pharmacy channels.
| Leading Market Players |
|---|
| Pelican BioThermal |
| Sonoco ThermoSafe |
| Cryopak |
| Sofrigam |
| Thermo Fisher Scientific |
| Berry Global |
| Sealed Air Corporation |
| Tempack |
| Isovation |
| Others |
Supply Flow & Price Mechanics
Isocyanate feedstock volatility from crude oil derivatives determines both the spread between premium polyurethane and economy polystyrene tiers and the geographic clustering of foam panel manufacturing around German chemical corridors. Buyers face widening cost differentials as thinner-profile thermal barriers command freight savings that justify material premiums.
Pricing Analysis
Cost-plus contracts with polyol and isocyanate indexation dominate procurement between pharmaceutical distributors and foam panel suppliers. Price differentiation rests on validation depth—FDA 21 CFR 211-qualified shippers capture 40-60% premiums over unvalidated equivalents—and customization for minus eighty Celsius cell therapy corridors. Pricing pressure stems from expanded polystyrene substitution in Indian vaccine distribution under CDSCO cost constraints. Hospital group purchasing organizations exhibit lowest price sensitivity due to bundled oncology drug margins, while third-party meal delivery platforms drive commoditization in short-duration thermal bags.
Supply Chain Analysis
Contract manufacturing for vacuum-insulated panel cores concentrates in South Korean and Chinese foundries, with German converters adding qualification layers for pharmaceutical lanes. Raw material flows draw from Saudi petrochemical isocyanate, Belgian polyol specialties, and Japanese silica core substrates. Single-source vulnerability clusters in East Asian VIP manufacturing, where disruption would idle ultra-low-temperature shipper production for European biologics distributors. Distribution runs through pharmaceutical logistics hubs in Frankfurt, Munich, and the Greater Boston corridor, with reverse logistics networks for reusable systems anchored in the Netherlands and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across validation tiers creates niche entry points as direct-to-patient pharmacy models splinter procurement authority away from consolidated hospital purchasing.
For Market Incumbents: Build certification moats through accelerated EU GDP and FDA 21 CFR 211 qualification pipelines that emerging Asian competitors cannot replicate. Incumbents should deepen backward integration into PCM formulation chemistry to offset polyurethane feedstock volatility, while securing exclusive contracts with German pharmaceutical logistics hubs to lock out reusable system rivals. For New Entrants and Emerging Players: Pursue white-space capture in Indian vaccine distribution under tightening CDSCO guidelines, where domestic qualified thermal packaging capacity lags manufacturing expansion. Target the cosmetics direct-to-consumer channel with two-to-eight Celsius solutions for premium skincare active ingredients, leveraging shorter validation cycles than pharmaceutical equivalents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reusable system providers with established reverse logistics infrastructure. Long-term viability over the next decade hinges on carbon accounting monetization under EU CSRD reporting requirements. Watch for inflection in PCM-IoT integration adoption rates as predictive intervention capability becomes table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| PCM-IoT Integration Development | Embedded temperature loggers with phase-change formulations enable real-time payload stability monitoring for pharmaceutical distributors. |
| Natural Refrigerant Qualification | EU F-Gas Regulation compliance positions equipment manufacturers ahead of hydrofluorocarbon phase-down deadlines in Germany and France. |
| Reverse Logistics Network Expansion | Reusable shipper economics improve with dedicated return infrastructure in the Netherlands and Germany. |
| Indian Manufacturing Partnership | CDSCO guideline alignment addresses domestic capacity gaps in qualified vaccine distribution packaging. |
| Carbon Accounting Certification | Lifecycle emissions documentation supports premium positioning under EU CSRD reporting requirements for hospital procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with pharmaceutical logistics directors, cold chain procurement managers at hospital group purchasing organizations, thermal packaging R&D leads, and specialty pharmacy network operators. Secondary validation drew from FDA 21 CFR 211 guidance documents, EU GDP guideline updates, CDSCO cold chain circulars, ISTA thermal test protocols, and customs trade data for polyurethane and polystyrene foam imports. Bottom-up shipment volume estimates were triangulated against top-down pharmaceutical cold chain expenditure benchmarks.
Calibration against historical capacity additions and regulatory implementation timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include material type, application corridor, distribution channel structure, and end-user procurement archetype. CAGRs were derived from elasticity-adjusted demand projections for biologics distribution and e-commerce pharmacy expansion, with specific inputs from monoclonal antibody pipeline volumes and direct-to-patient pharmacy model adoption curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing or air freight dimensional weight tariff structures would shift the trajectory for polyurethane versus polystyrene substitution. Quarterly review of CDSCO enforcement actions, EU F-Gas Regulation amendment proposals, and PCM patent expiration calendars is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market