
 Interactive Packaging Market | 2026-2036
Interactive Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Packaging Market Outlook
Retail shelf-to-phone engagement channels are reshaping how consumer goods firms allocate packaging budgets. Sealed Air leverages embedded sensor expertise to target cold-chain pharmaceutical applications. Smurfit Kappa anchors European corrugated smart-box production with integrated printed electronics. Amcor competes on flexible film platforms that accommodate NFC inlay lamination at high throughput.
Interactive packaging denotes systems that enable two-way communication between a product container and an end user through integrated digital identifiers, conductive substrates, or optically readable layers, typically incorporating antenna structures, adhesive interposers, or printed conductive inks to facilitate data exchange. Its primary commercial purpose is to transform passive containers into dynamic touchpoints for authentication, supply-chain visibility, and post-purchase consumer engagement. Near Field Communication technology leads current deployment volumes due to smartphone ubiquity and tap-to-read simplicity, while IoT Solutions represents the fastest-expanding segment as cloud-connected sensor arrays penetrate perishable logistics. RFID maintains stable demand in high-value electronics and pharmaceutical track-and-trace programs where read-range requirements exceed NFC capabilities.
The FDA enforces pharmaceutical serialization mandates that directly expand demand for tamper-evident interactive labels across drug distribution networks. REACH and RoHS frameworks in Europe restrict hazardous substances in printed electronics, shaping material selection for conductive inks and antenna substrates. Stakeholders must monitor evolving EPR schemes and smartphone OS privacy updates that could alter consumer opt-in rates for packaging-triggered data collection.
Market Dynamics
Smartphone-native consumers now expect instant product provenance verification, forcing FMCG brands to embed NFC and sensor layers directly into primary packaging substrates rather than applying secondary labels.
Growth Catalysts
- EU Green Deal packaging waste rules:The directive mandates recyclable substrates, accelerating development of fiber-based smart containers with printed conductive antennas that replace plastic inlay carriers.
- Pharmaceutical cold-chain integrity:Temperature-sensitive biologics require real-time monitoring, expanding demand for embedded sensor arrays in vial and syringe packaging across distribution networks.
- German FMCG pilot scale:Industrial-scale NFC-enabled bottle programs in beverage and personal care categories demonstrate unit economics viable for mid-volume SKUs.
Market Restraints
- Conductive ink cost volatility:Silver flake and copper nanoparticle formulations face raw material price swings that compress converter margins on short-run smart label contracts.
- Antenna substrate concentration:PET and PEN film supply for inlay lamination concentrates among Asian specialty chemical producers, creating geographic single-source exposure.
- NFC read-range ceiling:The four-centimeter functional limit prevents adoption in warehouse automation use cases where RFID maintains technical superiority.
Strategic Opportunities
- Indian packaged food traceability:FSSAI digitization mandates for edible oils and dairy create first-mover openings for NFC-enabled tamper-evident closures in a market with limited incumbent smart packaging infrastructure.
- Blockchain-NFC convergence:Immutable ledger integration with tap-to-verify packaging enables premium authentication services for luxury cosmetics and spirits categories.
- Extended Producer Responsibility incentives:French and Italian EPR schemes award packaging recyclability credits for mono-material smart containers, rewarding fiber-based sensor integration.
Industry Challenges
- Printed electronics skill scarcity:Converters lack process engineers trained in roll-to-roll conductive ink deposition and antenna impedance matching at production speeds.
- Smartphone OS privacy fragmentation:Apple and Google permission frameworks for NFC background reading vary by release, forcing packaging designers to maintain multiple consumer journey workflows.
- Legacy line integration:High-speed filling and capping equipment requires mechanical retrofitting to accommodate thicker smart label substrates without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Packaging Market |
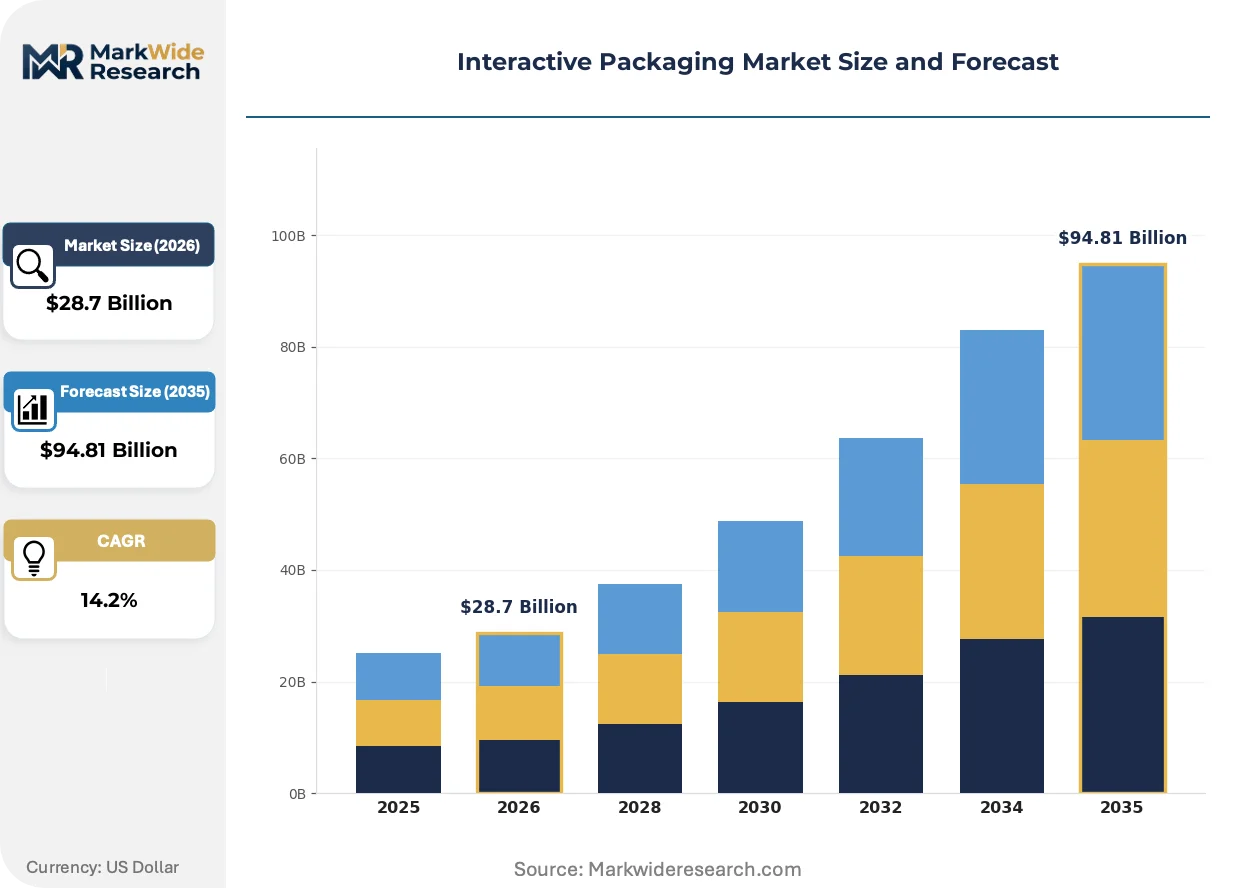
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Labels, QR Codes, NFC Tags, Augmented Reality Technology: Near Field Communication, RFID, IoT Solutions, Embedded Sensors End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Box, Bottle, Blister Pack, Flexible Packaging |
| Companies Covered | Sealed Air, Smurfit Kappa, Amcor, Constantia Flexibles, CCL Industries, Mondi Group, Tetra Pak, Huhtamaki, WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Packaging Market Strategic Shifts
Digital identifier technologies are migrating from standalone applications toward fused systems that combine multiple authentication and engagement modalities within single packaging constructions.
Printed sensor networks is hybridizing temperature, humidity, and shock detection into unified flexible substrates. Pharmaceutical 3PL providers in Benelux and Nordics are deploying these multi-parameter arrays for high-value gene therapy shipments. The convergence compresses what previously required three separate label components into one laminated structure, reducing application complexity and failure points.
REACH substance restrictions on heavy metals in electronics are forcing reformulation of traditional conductive inks across European converter operations. ECHA authorization requirements for cadmium and lead compounds have accelerated silver nanowire and carbon-based alternatives through qualification pipelines. German and French label printers are completing material transitions ahead of 2026 sunset dates for legacy formulations.
Direct-to-consumer engagement via packaging-triggered content is displacing traditional coupon and loyalty card programs in food and beverage categories. Younger demographics in urban UK and Spanish markets demonstrate higher repeat purchase rates when brands offer recipe content or sustainability stories through tap interactions. CPG marketing budgets are reallocating from print inserts toward cloud-hosted experiential platforms accessed through container-level identifiers.
Interactive Packaging Market Segmentation
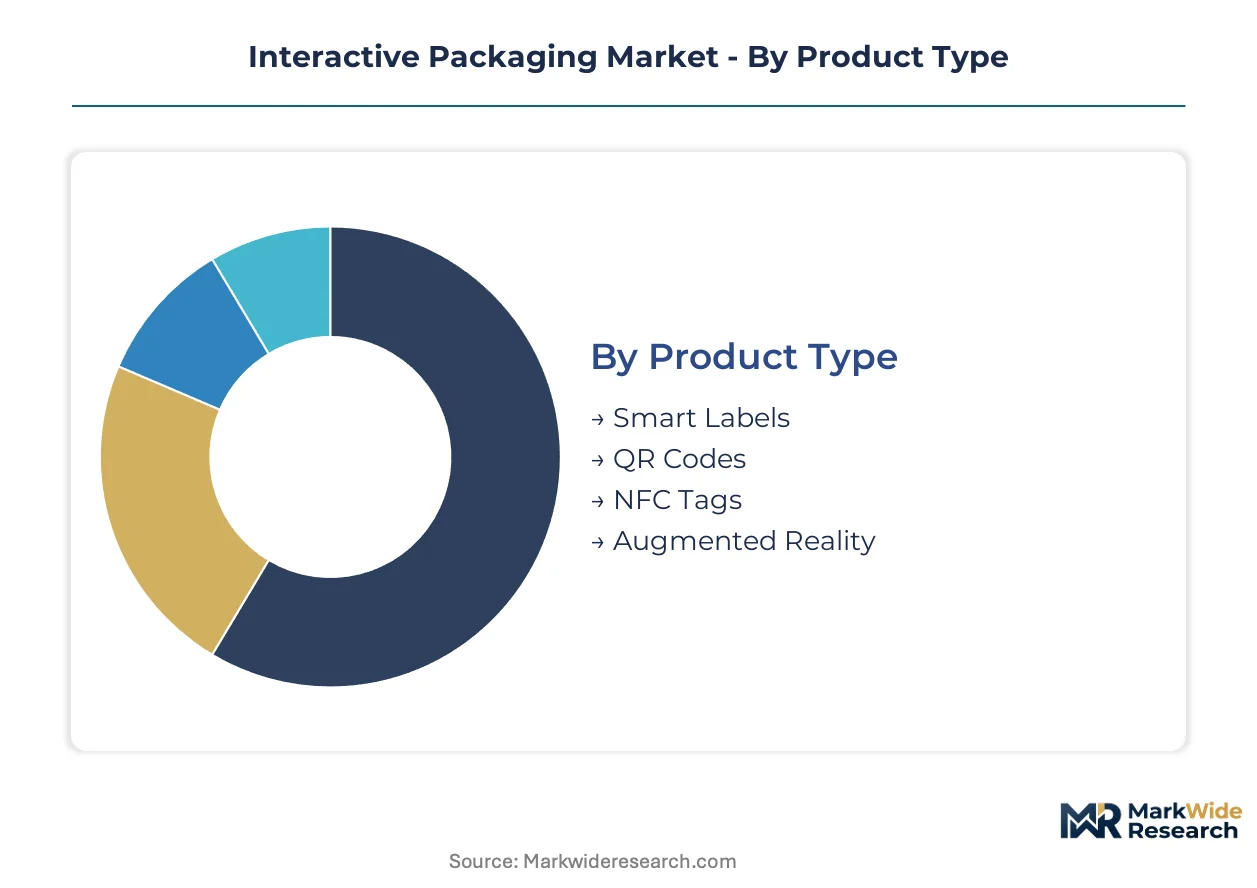
Interactive packaging architectures vary sharply by integration depth and substrate compatibility. Converter selection hinges on whether the application demands simple optical readability or complex two-way data exchange with cloud infrastructure.
Product Type:
Mature optical identifiers coexist alongside emerging sensor-embedded formats as brands balance cost against engagement depth.
- Smart Labels:These constructions integrate printed conductive traces, antenna structures, and adhesive interposers onto film or paper carriers. Pharmaceutical serialization mandates in the US and EU are concentrating procurement among cold-chain drug manufacturers requiring tamper-evident track-and-trace layers.
- NFC Tags:Inlay-based assemblies with etched aluminum or copper antennas laminated between PET substrates. German beverage and personal care pilots demonstrate industrial-scale viability for mid-volume SKUs seeking shelf-to-phone consumer engagement.
- QR Codes:Static optical matrices requiring no conductive materials; lowest unit cost enables mass deployment in emerging market food traceability programs.
- Augmented Reality:Marker-based or markerless visual recognition triggering digital overlays; cosmetics brands leverage these for virtual try-on experiences tied to primary packaging.
NFC Tags retain volume leadership; Augmented Reality holds the steepest expansion curve.
Technology:
Cost tiers separate established radio-frequency protocols from emerging cloud-connected sensor networks.
- Near Field Communication:Operating at 13.56 MHz with smartphone-native compatibility; tap-to-read simplicity drives FMCG adoption where consumer friction must approach zero.
- IoT Solutions:Cloud-connected sensor arrays penetrating perishable logistics. Benelux pharmaceutical 3PL providers deploy multi-parameter temperature-humidity-shock substrates for gene therapy distribution, compressing three legacy label components into unified flexible constructions.
- RFID:Ultra-high frequency systems enabling multi-meter read ranges; stable demand persists in high-value electronics and pharmaceutical warehouse automation where NFC range ceilings prove insufficient.
- Embedded Sensors:Discrete temperature, shock, or humidity detectors integrated directly into primary packaging walls; REACH substance restrictions on heavy metals are forcing silver nanowire and carbon-based conductive ink transitions across European converter operations.
Near Field Communication dominates current deployment volumes; IoT Solutions are climbing the fastest.
End User:
Application requirements dictate substrate durability, regulatory compliance burden, and engagement frequency.
- Food & Beverage:FSSAI digitization mandates for edible oils and dairy in India create first-mover openings for NFC-enabled tamper-evident closures; UK and Spanish urban demographics demonstrate higher repeat purchase rates when brands offer recipe content through tap interactions.
- Pharmaceuticals:FDA serialization mandates directly expand demand for tamper-evident interactive labels; temperature-sensitive biologics require real-time cold-chain monitoring through embedded sensor arrays.
- Cosmetics:Premium authentication services via blockchain-NFC convergence serve luxury spirits and skincare categories where counterfeit risk erodes brand equity.
- Electronics:High-value device track-and-trace programs leverage RFID for warehouse automation and NFC for consumer warranty activation.
Food & Beverage captures the broadest SKU penetration; Pharmaceuticals commands the highest unit value premium.
Packaging Type:
Structural geometry determines antenna placement constraints and conductive ink deposition feasibility.
- Flexible Packaging:Amcor and competitors engineer film platforms accommodating NFC inlay lamination at high throughput; French and Italian EPR schemes award recyclability credits for mono-material smart containers.
- Box:Smurfit Kappa anchors European corrugated smart-box production with integrated printed electronics; fiber-based substrates with printed conductive antennas replace plastic inlay carriers under EU Green Deal packaging waste rules.
- Bottle:High-speed filling and capping equipment requires mechanical retrofitting to accommodate thicker smart label substrates without throughput degradation.
- Blister Pack:Thermoformed cavities with lidding foil integration; pharmaceutical unit-dose compliance monitoring drives sensor placement on push-through backing layers.
Flexible Packaging leads substrate flexibility for converter innovation; Box formats gain share fastest under fiber-based sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing premiums for NFC-enabled bottle programs that Indian suppliers cannot yet match. This asymmetry reflects industrial maturity gaps rather than raw material costs. Regulatory divergence between EU Green Deal mandates and emerging economy digitization timelines amplifies the spread.
United States
FDA pharmaceutical serialization mandates drive tamper-evident interactive label demand across cold-chain drug distribution networks. The agency enforces track-and-trace requirements that expand procurement among vaccine and biologics manufacturers. Boston and New Jersey pharmaceutical clusters deploy embedded sensor arrays for gene therapy shipments requiring real-time integrity monitoring.
Germany
REACH and RoHS frameworks restrict hazardous substances in printed electronics, forcing silver nanowire transitions ahead of 2026 sunset dates. KBA and federal environmental regulators monitor compliance across converter operations. The Rhine-Ruhr industrial corridor anchors industrial-scale NFC bottle pilots for beverage and personal care mid-volume SKUs.
India
FSSAI digitization mandates for edible oils and dairy create first-mover openings for NFC-enabled tamper-evident closures in packaged food traceability. The regulator's phased implementation timeline lags EU counterparts by approximately 36 months. Maharashtra and Gujarat processing hubs lack incumbent smart packaging infrastructure, lowering competitive barriers for technology entrants.
United Kingdom
Urban demographics demonstrate higher repeat purchase rates when brands offer recipe content through tap interactions, reallocating CPG marketing budgets from print inserts. The Competition and Markets Authority monitors data collection practices alongside Information Commissioner's Office privacy frameworks. London and Southeast England concentrate AR-enabled cosmetics packaging development for virtual try-on experiences.
France
Extended Producer Responsibility schemes award packaging recyclability credits for mono-material smart containers, rewarding fiber-based sensor integration over plastic inlay carriers. ANSM pharmaceutical regulations align with EMA serialization standards. The Île-de-France region hosts luxury spirits authentication programs leveraging blockchain-NFC convergence for premium brand protection.
Interactive Packaging Market Competitive Environment
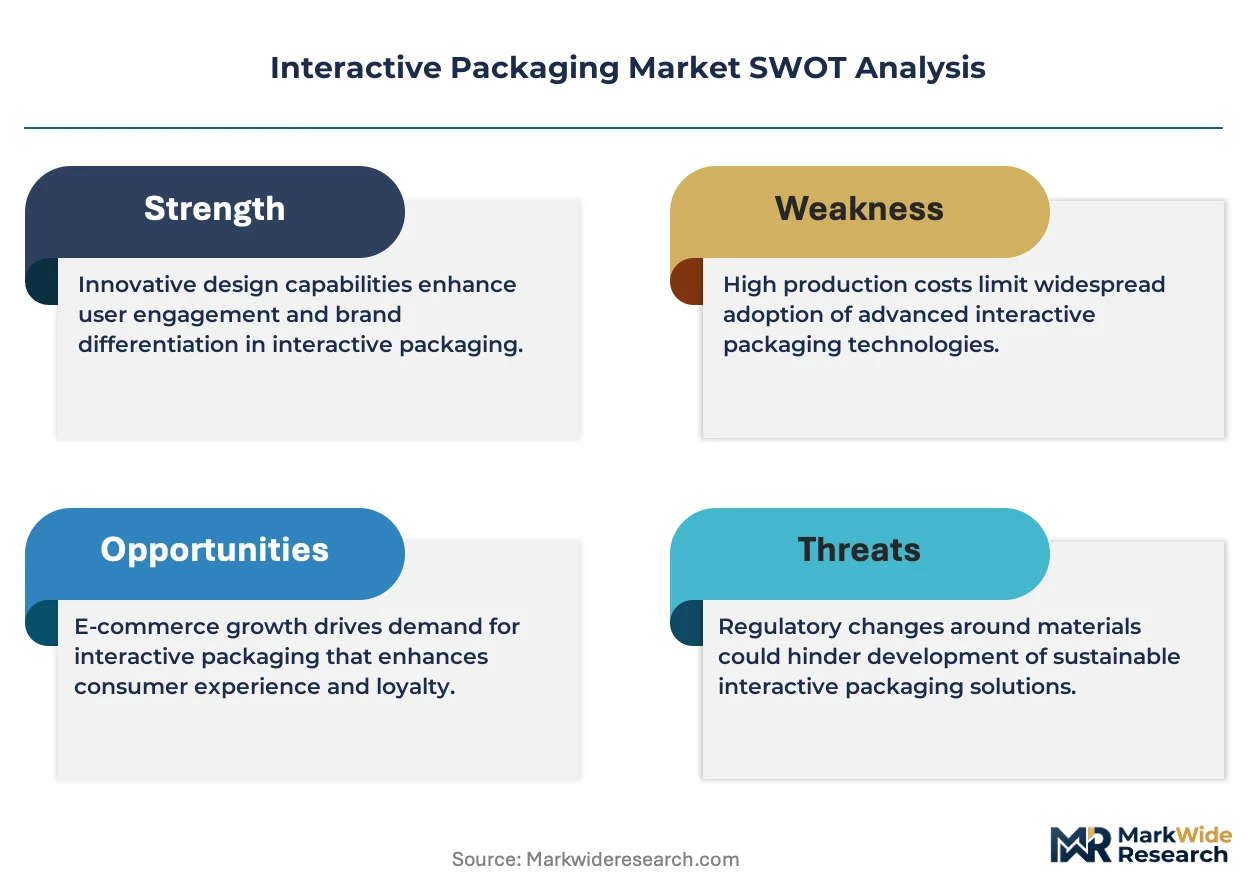
Specialized packaging converters and diversified materials conglomerates split the market along integration-depth lines. The vendor base concentrates among European and North American firms with printed electronics capabilities, while Asian competitors dominate substrate supply tiers. Three archetypes predominate: substrate-integrated specialists, flexible film platform engineers, and corrugated smart-box producers. Competitive dynamics center on M&A for conductive ink deposition expertise and strategic partnerships bridging converter gaps with cloud infrastructure providers.
Within the substrate-integrated specialist tier, Sealed Air and Smurfit Kappa exemplify divergent strategic positions. Sealed Air occupies a position emphasizing embedded sensor expertise for temperature-sensitive logistics applications. Smurfit Kappa anchors European corrugated production with integrated printed electronics capabilities. Amcor sits within the flexible film platform segment, representing high-throughput NFC inlay lamination approaches. These three firms collectively illustrate how geographic origin and corporate structure shape competitive archetype selection across the value chain.
| Leading Market Players |
|---|
| Sealed Air |
| Smurfit Kappa |
| Amcor |
| Constantia Flexibles |
| CCL Industries |
| Mondi Group |
| Tetra Pak |
| Huhtamaki |
| WestRock |
| Others |
Value Chain & Pricing Dynamics
Rhine-Ruhr industrial corridor capacity for NFC-enabled bottle production shapes downstream pricing power for European converters serving FMCG brands. German suppliers command premiums against Asian competitors due to REACH-compliant conductive ink qualification and embedded sensor integration expertise.
Pricing Analysis
The customization-premium spread between configured-to-order smart label contracts and standard NFC inlay pricing runs wide in this market. Project-based pricing dominates for pharmaceutical serialization mandates requiring tamper-evident track-and-trace layers, while per-unit transactional models prevail in beverage mid-volume SKUs. Price differentiation hinges on certification level (FDA serialization tier vs. standard NFC) and volume scale, with cold-chain biologics manufacturers showing least price sensitivity due to regulatory compliance imperatives. Cost compression in silver nanowire conductive ink formulations is intensifying because ECHA sunset deadlines for legacy heavy metal compounds force material transitions ahead of qualification timelines.
Supply Chain Analysis
Export-control regimes on printed electronics manufacturing equipment limit technology transfer to emerging converter operations in India and Southeast Asia. Geographic supply concentrates in Germany, Japan, and South Korea for precision antenna etching equipment and silver nanoparticle ink formulations. Raw material dependencies rest on PET and PEN film substrates from Asian specialty chemical producers, copper and aluminum antenna feedstocks, and cloud infrastructure for IoT sensor data routing. Single-source vulnerability in conductive substrate supply creates exposure for European label printers. Distribution runs through converter-to-brand-direct relationships for pharmaceutical applications, with FMCG procurement increasingly favoring integrated packaging-technology partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. FDA and EMA serialization mandates impose switching costs that lock pharmaceutical manufacturers into qualified supplier relationships.
For Market Incumbents: Harden defensive positioning through backward integration into silver nanowire conductive ink production and captive antenna substrate manufacturing. Capacity addition in Benelux pharmaceutical 3PL corridors captures gene therapy cold-chain monitoring demand. Certification investment in FDA serialization tiers creates barriers against emerging Asian converters.
For New Entrants and Emerging Players: Indian packaged food traceability under FSSAI digitization mandates represents the most penetrable entry point for NFC-enabled tamper-evident closures. Maharashtra and Gujarat processing hubs lack incumbent smart packaging infrastructure, lowering competitive barriers. Blockchain-NFC convergence for luxury spirits authentication offers a premium go-to-market angle with higher margin tolerance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors substrate-integrated specialists with printed electronics capabilities over pure-play label converters. Long-term viability across the projection horizon hinges on regulatory compliance moats rather than commodity NFC inlay production. Acquisition target archetype: European converters with REACH-qualified conductive ink processes and pharmaceutical customer relationships. The signal to watch is EPR scheme expansion awarding recyclability credits for fiber-based smart containers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Ink | ECHA sunset deadlines for cadmium compounds force captive silver nanowire production to protect margin structure. |
| Pharmaceutical Serialization Certification | FDA track-and-trace mandates create qualified supplier status that locks in multi-year cold-chain drug contracts. |
| Fiber-Based Smart Container Development | French and Italian EPR recyclability credits reward mono-material corrugated boxes with printed antenna integration. |
| Blockchain-NFC Convergence Platform | Luxury spirits and cosmetics brands pay premium authentication fees for immutable provenance verification. |
| Indian Market Entry Partnership | FSSAI digitization timelines for edible oils create first-mover advantage in packaged food traceability infrastructure. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA drug serialization guidance, ECHA authorization databases, and EU Green Deal packaging waste directives. Primary interviews engaged packaging converters, pharmaceutical supply chain directors, FMCG brand managers, and conductive ink formulation specialists. Secondary validation drew from SEC filings of diversified materials conglomerates, customs records for NFC inlay trade flows, and patent filings for printed antenna deposition methods. Bottom-up unit economics for German beverage pilot programs triangulate against top-down market sizing from pharmaceutical serialization mandate volumes.
Forecast inputs include technology adoption curves for smartphone-native NFC reading, regulatory implementation timelines for FSSAI digitization, and cold-chain biologics distribution growth. Segmentation dimensions span product type (smart labels, NFC tags, sensor-embedded formats), technology protocol (NFC, RFID, IoT sensor arrays), end-use vertical (pharmaceuticals, food and beverage, cosmetics), and packaging substrate (flexible film, corrugated fiber, rigid containers). CAGRs derive from installed base projections for connected packaging equipment and per-SKU cost erosion curves across the analysis window.
Practitioners should monitor REACH substance restriction enforcement, smartphone OS privacy permission frameworks, and EPR scheme credit valuations for early signals of forecast deviation. Material shifts in EU Green Deal packaging recyclability mandates or FDA serialization scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Isothermal Packaging Market