
 Highly Visible Packaging Market | 2026-2036
Highly Visible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Highly Visible Packaging Market Outlook
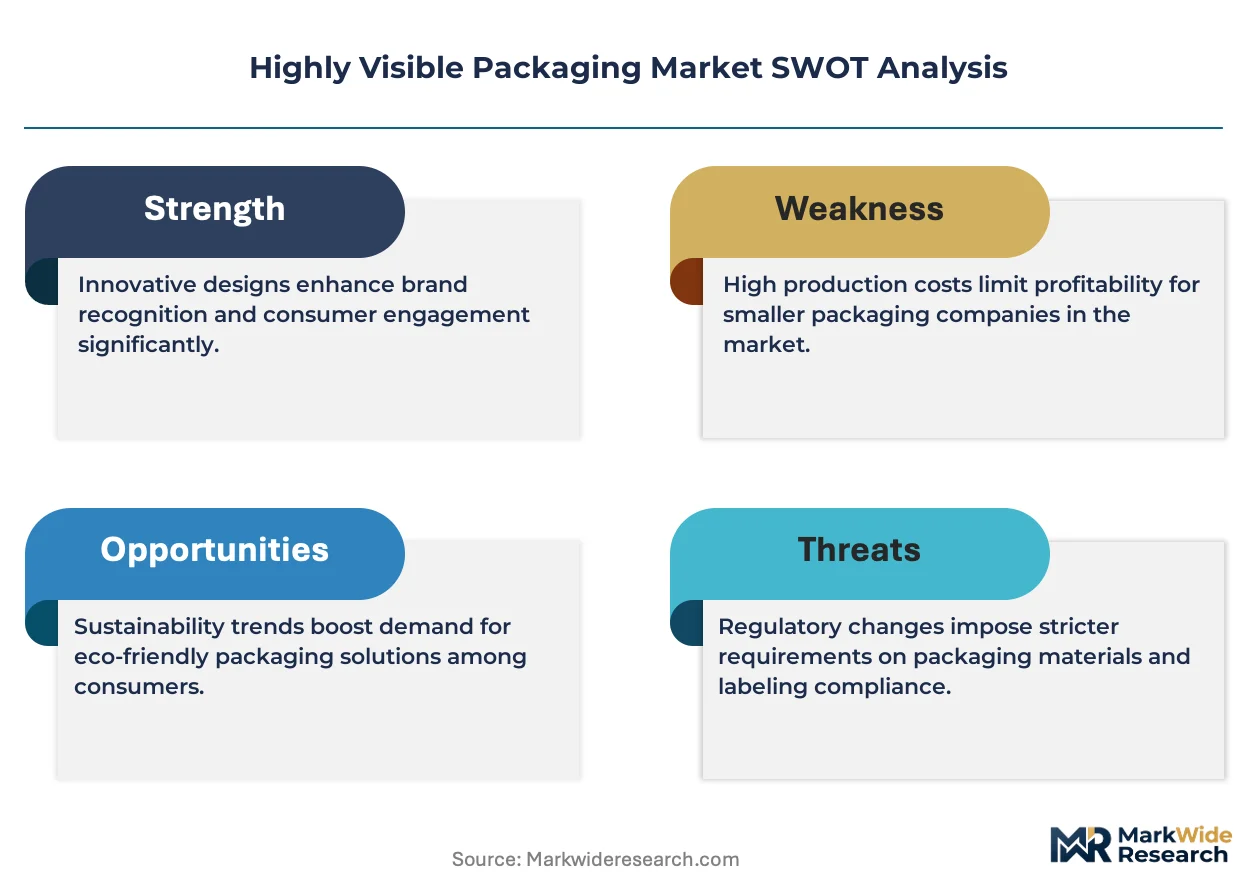
Multi-source procurement for printed packaging components is broadening as brand owners reduce dependency on single converters. Sealed Air Corporation leverages its integrated film-to-bag manufacturing to control substrate quality for high-visibility food pouches. Mondi Plc anchors European demand through kraft-based solutions that combine print clarity with fiber sustainability credentials. Smurfit Kappa competes via corrugated display packaging that maximizes shelf impact for retail-ready applications.
Highly visible packaging encompasses engineered containers, films, and closures designed for immediate consumer recognition through enhanced optical properties, surface gloss, and color saturation exceeding standard commercial print specifications. These systems employ multi-layer coextrusion, metallized substrates, or UV-cured inks to achieve luminance values and contrast ratios that accelerate purchase decisions in cluttered retail environments. Labels and pouches command disproportionate margin pools due to their direct interface with product identity and regulatory disclosure requirements. Boxes sustain volume leadership across e-commerce and retail shelf applications where structural billboard space drives brand communication. Material segmentation shows plastic films retaining dominance in flexible formats despite fiber-based alternatives gaining traction in premium personal care and food segments.
The US FDA enforces strict label legibility standards for over-the-counter pharmaceuticals and nutritional supplements, directly shaping substrate selection and print resolution requirements. ECHA's REACH restrictions on certain pigment chemistries and the EU Packaging and Packaging Waste Regulation compel reformulation of high-visibility inks and coatings toward compliant alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical disclosure mandates that will determine which material-print combinations retain market access across major economies.
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are forcing converters to reengineer label architectures for track-and-trace compliance, compressing lead times and elevating substrate specifications across European supply chains.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization requirements for pharmaceutical packaging are accelerating investment in high-contrast, machine-readable labels across Germany, France, and Italy.
- UV-cured ink systems:These chemistries deliver the luminance values required for instant shelf recognition in cluttered retail environments, particularly for nutritional supplements.
- Düsseldorf industrial cluster:Contract packaging services in this German hub integrate high-visibility designs for export-bound electronics and pharmaceutical clients.
Market Restraints
- Pigment chemistry restrictions:ECHA's REACH limitations on certain high-visibility pigment classes are forcing costly reformulation cycles for ink suppliers.
- Metallized substrate concentration:Supply of aluminum-deposited films concentrates among a limited set of European converters, creating input vulnerability.
- Multi-layer coextrusion complexity:Technical barriers in achieving consistent optical properties across production runs limit smaller converters' market entry.
Strategic Opportunities
- Extended producer responsibility frameworks:The EU Packaging and Packaging Waste Regulation creates first-mover advantage for fiber-based solutions with print clarity credentials.
- India pharmaceutical export packaging:CDSCO serialization alignment with EU standards opens demand for high-visibility track-and-trace labels in this underpenetrated market.
- E-commerce corrugated display integration:Structural billboard space in retail-ready boxes converges with digital unboxing experience requirements.
Industry Challenges
- Print resolution certification timelines:FDA label legibility audits for over-the-counter pharmaceuticals impose extended validation cycles on substrate-print combinations.
- Legacy flexographic asset integration:Converters face friction retrofitting established lines for UV-cured ink compatibility without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Highly Visible Packaging Market |
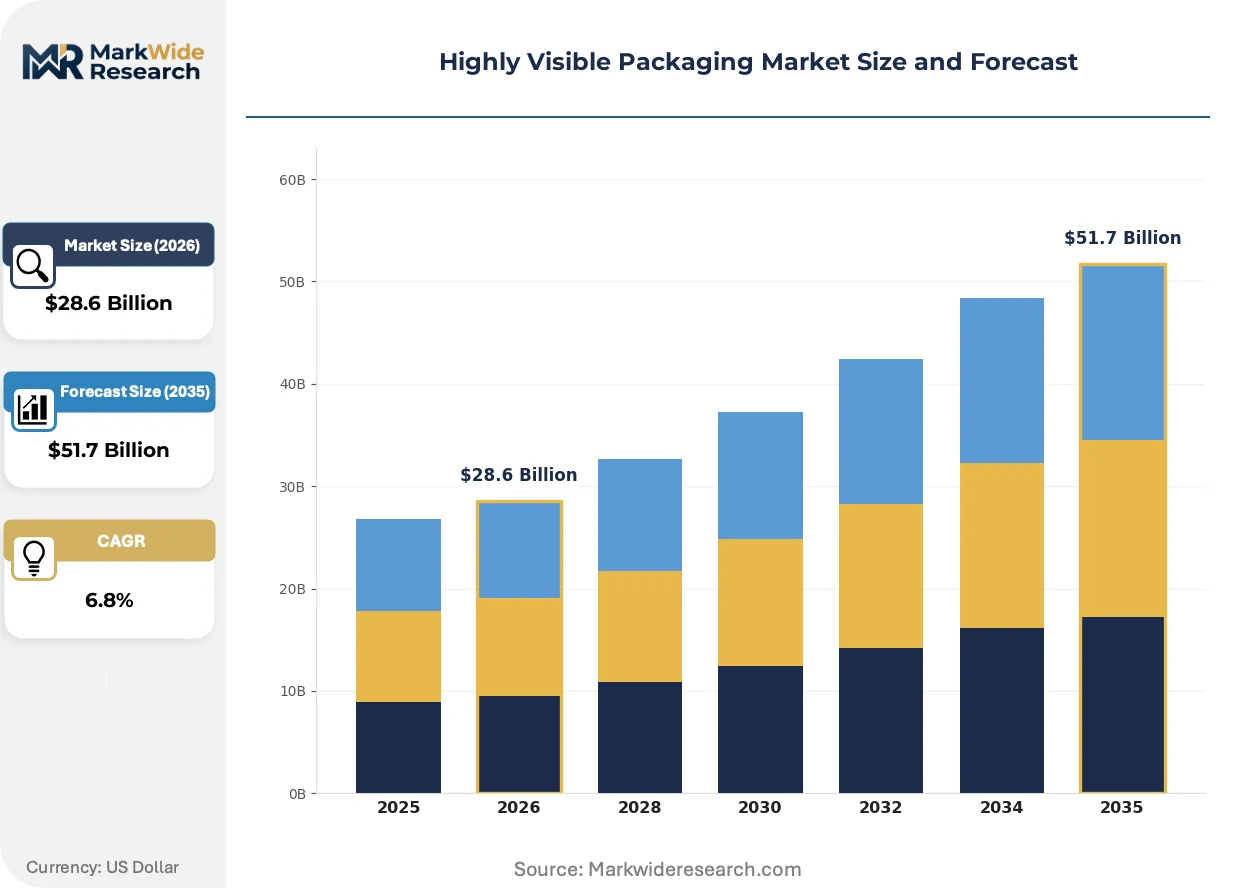
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Boxes, Pouches, Tapes Material: Plastic, Paper, Glass, Metal End User: Food & Beverage, Personal Care, Pharmaceuticals, Consumer Electronics Design Features: Color Coding, Graphics, Transparency, Texture |
| Companies Covered | Sealed Air Corporation, Smurfit Kappa, Amcor Plc, Berry Global, WestRock, Mondi Plc, Pactiv Evergreen Inc., International Paper, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Highly Visible Packaging Market Strategic Shifts
Digital printing architectures are compressing minimum order quantities and enabling versioned packaging runs, while regulatory chemical disclosure mandates are rewriting material selection protocols across pharmaceutical and food contact applications.
Water-based UV-curable inkjet systems are overtaking solvent-based flexography for short-run pharmaceutical labels. Brand owners in the nutritional supplement segment are adopting these platforms for regional language versioning. This shift is overtaking conventional converter economics by collapsing plate costs and enabling just-in-time production for export markets.
REACH restrictions on specific pigment chemistries are compelling ink formulators toward compliant high-luminance alternatives. The industrial consequence involves accelerated R&D cycles and supplier qualification protocols. Pharmaceutical label converters in Germany and France are responding by locking in multi-year supply agreements with certified pigment houses.
Brand owner procurement of printed packaging components is fragmenting across multiple converters to reduce single-source dependency. Food and personal care multinationals are displacing sole-source relationships with regional converter panels. This pattern is most visible in North American and Western European markets where supply chain resilience audits have become standard vendor selection criteria.
Highly Visible Packaging Market Segmentation
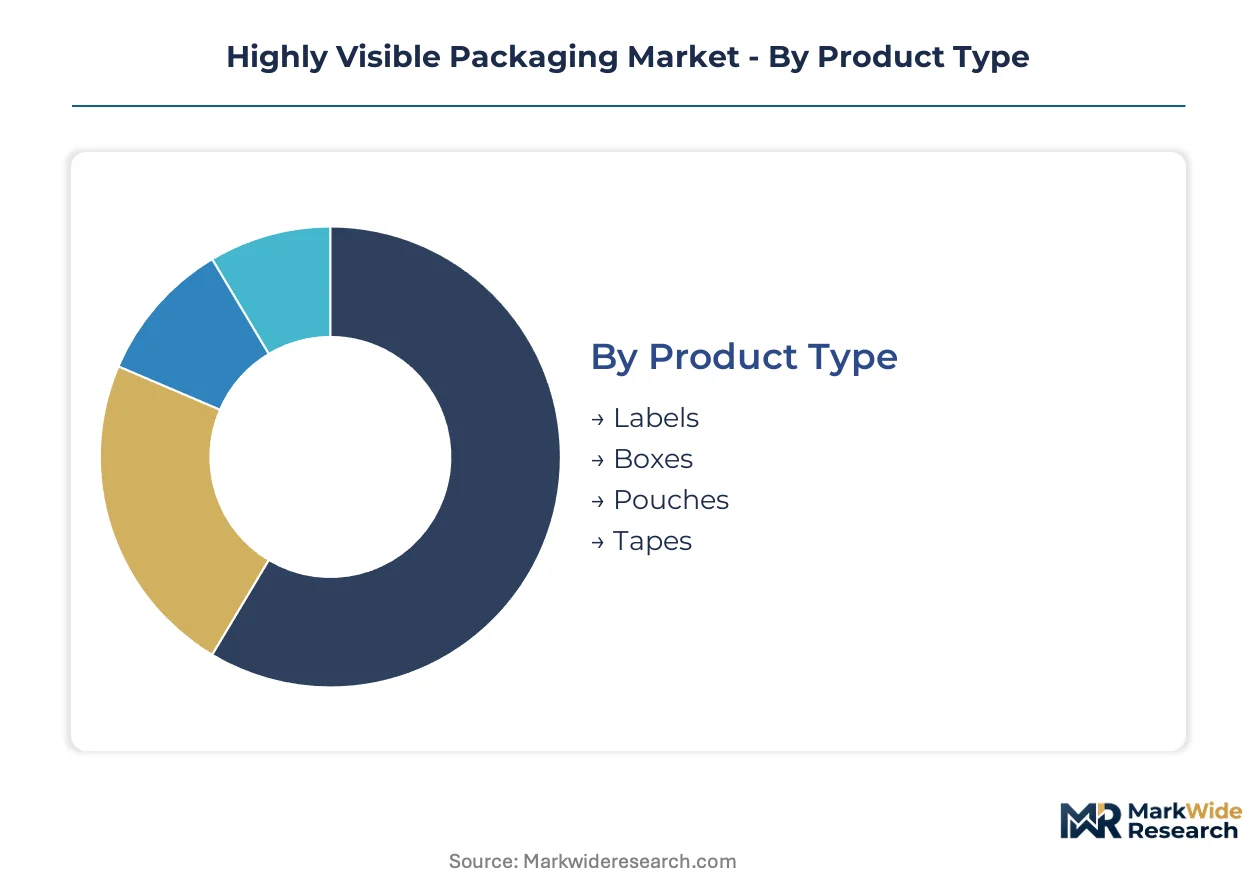
Segmentation in highly visible packaging reveals how optical performance requirements diverge across product formats, material substrates, and end-use regulatory environments. Each axis shapes procurement priorities, converter capabilities, and margin structures differently.
Product Type:
Structural hierarchy determines billboard space allocation and print resolution tolerances across retail, e-commerce, and industrial channels.
- Labels:Multi-layer constructions with UV-cured ink systems deliver the luminance values and machine-readability demanded by pharmaceutical serialization mandates. Demand concentrates in Germany's Düsseldorf industrial cluster where contract packagers serve export-bound pharmaceutical and electronics clients facing EU Falsified Medicines Directive compliance deadlines.
- Boxes:Corrugated display architectures maximize structural billboard space for retail shelf impact and e-commerce unboxing experiences. Volume leadership sustains across North American and Western European markets where retail-ready packaging specifications dominate procurement tenders.
- Pouches:Flexible formats employ coextruded films with metallized substrates for instant recognition in cluttered nutritional supplement aisles.
- Tapes:Adhesive-backed solutions secure secondary branding and tamper-evidence functions across logistics and promotional applications.
Boxes lead on scale; labels lead on momentum.
Material:
Substrate selection balances optical performance against chemical compliance and extended producer responsibility frameworks.
- Plastic:Multi-layer coextrusion and metallized films retain format dominance despite ECHA REACH restrictions on certain pigment chemistries forcing ink reformulation cycles. Optical consistency requirements limit viable converter supply to established European players with calibrated deposition equipment.
- Paper:Kraft-based solutions from Mondi Plc and competitors combine print clarity with fiber sustainability credentials aligned to EU Packaging and Packaging Waste Regulation requirements. Premium personal care and food segments drive fastest share expansion as brand owners seek compliant alternatives to plastic formats.
- Glass:Rigid containers serve high-value spirits and pharmaceutical applications where surface gloss and chemical inertness justify unit cost premiums.
- Metal:Aluminum and tinplate substrates deliver barrier properties and decorative embossing for aerosol and specialty food packaging.
Plastic dominates current volume; paper climbs the fastest.
End User:
Regulatory intensity and shelf competition pressure vary sharply across consumption categories, reshaping converter qualification requirements.
- Food & Beverage:UV-cured ink systems and high-contrast graphics accelerate purchase decisions in crowded retail environments where nutritional supplement brands compete for attention.
- Pharmaceuticals:FDA label legibility standards and EU Falsified Medicines Directive serialization mandates compress lead times and elevate substrate specifications across German, French, and Italian supply chains.
- Personal Care:Premium positioning drives demand for metallized substrates and tactile surface treatments in North American and Western European markets.
- Consumer Electronics:Unboxing experience requirements and anti-counterfeiting features concentrate demand in Düsseldorf contract packaging services for export-bound Asian manufacturing.
Pharmaceuticals lead on specification intensity; food and beverage leads on absolute volume.
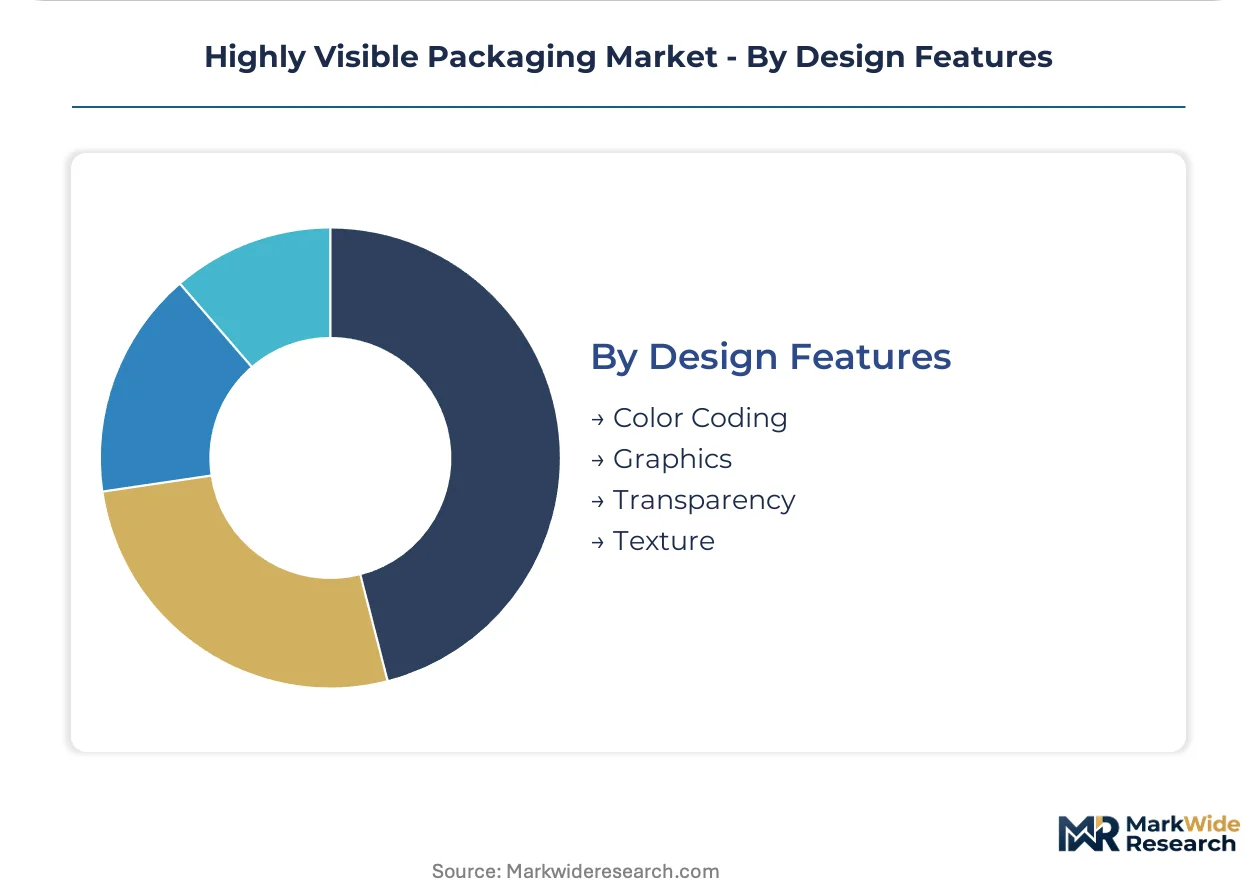
Design Features:
Visual differentiation mechanisms align with production technology capabilities and regulatory disclosure requirements.
- Color Coding:High-luminance pigment systems achieve contrast ratios exceeding standard commercial print specifications for instant shelf recognition.
- Graphics:Digital printing architectures enable versioned runs and regional language adaptation collapsing traditional plate economics.
- Transparency:Clear windows and film constructions satisfy consumer verification needs in fresh food and personal care segments.
- Texture:Embossing and tactile coatings differentiate premium tiers in spirits and cosmetic packaging applications.
Color coding leads on ubiquity; graphics leads on technology disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as converters relocate to jurisdictions with narrower compliance cost differentials. Manufacturers in lower-cost environments face escalating pigment chemistry disclosure requirements that erode historical labor advantages. Capital is flowing toward integrated clusters where substrate production, printing, and serialization capabilities co-locate.
Germany
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive dominate converter investment priorities. ECHA REACH restrictions on specific pigment classes force ink reformulation cycles across North Rhine-Westphalia printing facilities. The Düsseldorf industrial cluster anchors contract packaging services for export-bound electronics and pharmaceutical clients facing compressed compliance deadlines.
United States
FDA label legibility standards for over-the-counter pharmaceuticals and nutritional supplements elevate substrate specifications and print resolution requirements. Extended producer responsibility frameworks at the state level, particularly in California and New York, reshape procurement toward fiber-based alternatives. The Midwest printing corridor concentrates multi-layer coextrusion capacity serving CPG brand owners with regional versioning needs.
China
Domestic pharmaceutical regulators align serialization standards with EU Falsified Medicines Directive protocols, opening export packaging demand for high-visibility track-and-trace labels. NMPA chemical disclosure mandates for food contact materials accelerate substrate qualification timelines. The Yangtze River Delta manufacturing belt hosts metallized film deposition capacity serving both domestic nutritional supplement brands and contract exporters.
India
CDSCO serialization alignment with EU standards creates demand for high-contrast, machine-readable labels in pharmaceutical export packaging. FSSAI chemical disclosure requirements for food contact applications narrow viable ink formulation options. Gujarat and Maharashtra industrial corridors concentrate flexible packaging converters serving both domestic FMCG and export pharmaceutical clients.
France
ANSM pharmaceutical packaging regulations enforce stringent track-and-trace compliance that elevates converter qualification barriers. EU Packaging and Packaging Waste Regulation implementation accelerates fiber-based solution adoption in premium personal care segments. The Île-de-France region concentrates brand owner procurement functions that drive specification standards across continental supply chains.
Highly Visible Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital printing and sustainable substrate niches to bypass legacy asset constraints. The vendor base stratifies across integrated multinationals with captive film production, regional converters with specialized metallization capabilities, and technology-focused entrants leveraging inkjet platforms for short-run pharmaceutical versioning. Three archetypes dominate: substrate-integrated players controlling optical consistency through backward integration, specialist converters with certified pigment house relationships, and digital-native platforms collapsing minimum order quantities. Competitive intensity centers on M&A activity to secure metallized film capacity and strategic partnerships locking in multi-year supply agreements with certified ink formulators.
Among substrate-integrated multinationals, Sealed Air Corporation and Mondi Plc exemplify archetypes where captive film or fiber production controls quality specifications for high-visibility applications. Smurfit Kappa occupies a position representing corrugated display specialists maximizing structural billboard space for retail impact. These three entities anchor distinct competitive vectors: film-to-bag integration, kraft-based sustainability credentials, and retail-ready structural design.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Smurfit Kappa |
| Amcor Plc |
| Berry Global |
| WestRock |
| Mondi Plc |
| Pactiv Evergreen Inc. |
| International Paper |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation compliance gates both qualified substrate supply and premium-tier pricing access for converters serving pharmaceutical and personal care brand owners. REACH pigment chemistry restrictions compress the qualified supplier pool while extending producer responsibility frameworks reward fiber-based alternatives with sustainability credentials.
Pricing Analysis
Input-cost pass-through from metallized film substrates and certified pigment houses shapes converter margin structures across European supply chains. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical grades from general commercial print specifications. Price differentiation hinges on serialization compliance certification and UV-cured ink luminance performance. Pricing pressure stems from REACH reformulation cycles forcing ink supplier qualification investments. Nutritional supplement brand owners exhibit highest price sensitivity; pharmaceutical exporters show lowest due to regulatory non-negotiability.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical serialization returns and label revalidation create secondary demand channels for certified converters in Germany and France. Supply concentrates in Germany's Düsseldorf cluster, China's Yangtze River Delta, and India's Gujarat corridor. Raw material dependencies center on aluminum-deposited films, high-luminance pigment systems, and kraft pulp for fiber alternatives. Single-source vulnerability in metallized substrate deposition equipment creates chokepoint risk. Distribution runs through contract packaging services for pharmaceutical exporters and direct procurement by multinational brand owners for retail-ready formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory cost differentials between EU REACH compliance zones and emerging pharmaceutical export markets create geographic-arbitrage opportunities for substrate-integrated players. ECHA pigment restrictions impose heavier conversion costs on European facilities than on Indian or Chinese competitors serving aligned serialization standards.
For Market Incumbents: Anticipate digital printing platform disruption by locking multi-year supply agreements with certified pigment houses before REACH reformulation cycles accelerate. Defend market position through backward integration into metallized film deposition capacity. Prioritize certification investment for EU Falsified Medicines Directive compliance deadlines compressing lead times. For New Entrants and Emerging Players: Begin with short-run pharmaceutical versioning for export markets where serialization alignment creates demand without legacy flexographic asset friction. Target India's CDSCO-compliant pharmaceutical export packaging as the most penetrable geography. Pursue water-based UV-curable inkjet platforms as the go-to-market angle collapsing plate economics. For Investors and Strategic Acquirers: Roll-up economics work for metallized film specialists because supply concentration among limited European converters creates scarcity value for qualified capacity. Five-to-ten year viability favors substrate-integrated platforms with captive pigment house relationships. Target acquisition archetype: regional converters with certified serialization capabilities. Monitor ECHA chemical disclosure mandate expansion as the inflection signal for compliant alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Film Production | Captive aluminum deposition capacity insulates Sealed Air and Mondi from pigment chemistry supply shocks. |
| Digital Printing Platform Deployment | Inkjet architectures enable Smurfit Kappa to collapse minimum order quantities for pharmaceutical versioning. |
| REACH-Compliant Pigment House Partnership | Multi-year supply agreements lock in qualified ink formulations ahead of ECHA restriction expansion. |
| Fiber-Based Substrate Capacity Expansion | Kraft solutions from Mondi align with EU Packaging and Packaging Waste Regulation extended producer responsibility. |
| Serialization Validation Infrastructure Investment | FDA label legibility certification compresses competitor entry timelines for over-the-counter pharmaceutical grades. |
Study Parameters
Multiple input streams — primary interviews with packaging procurement directors, regulatory affairs leads at pharmaceutical multinationals, and contract packaging operations managers; secondary validation through ECHA REACH substance databases, FDA label guidance documents, and EU Falsified Medicines Directive implementation reports; plus customs trade data for metallized film substrates — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation applied across product type, material substrate, end-use regulatory intensity, and geographic compliance cluster dimensions over the projection horizon. CAGRs derived from segment-level volume build-ups validated against macro converter capacity expansion announcements. Forecast inputs incorporated pharmaceutical serialization mandate phase-in schedules and ECHA pigment restriction timelines.
Several conditions sit outside the modeled scope, including speculative regulatory acceleration beyond published ECHA restriction roadmaps and breakthrough substrate technologies displacing multi-layer coextrusion. Forecasts reflect documented assumptions about compliance cost pass-through rates and qualified supplier pool stability. Practitioners should monitor CDSCO-EU serialization alignment progress and NMPA chemical disclosure expansion for early demand shift signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market