
 Track and Trace Packaging Market | 2026-2036
Track and Trace Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Track and Trace Packaging Market Analytics
European serialization equipment providers is rebalancing capacity toward cloud-connected verification systems. Optel Group leverages its pharmaceutical inspection heritage to anchor high-margin validation services. Zebra Technologies sustains hardware dominance through ruggedized print-and-apply stations deployed at contract packaging sites. Siemens AG competes on edge-computing integration, embedding track and trace modules directly into packaging line PLCs.
Track and trace packaging encompasses labels, tags, barcodes, and RFID devices engineered with machine-readable data carriers and tamper-evident substrates to record product origin, handling history, and chain-of-custody across supply networks. Digital watermarking and 2D codes carry encrypted authentication data readable by standard smartphone cameras, reducing dedicated scanner dependency. RFID-enabled tags command premium positioning in cold-chain pharmaceuticals where real-time location and temperature logging justify higher unit costs. QR codes occupy volume-driven cosmetics and food segments where consumer engagement and regulatory minimums converge.
The US FDA enforces DSCSA unit-level traceability mandates that compel pharmaceutical distributors to upgrade aggregation and verification infrastructure. The EU EMA coordinates FMD compliance through national medicine verification systems, while REACH governs adhesive and substrate chemical composition in European label production. Stakeholders must weigh interoperability investments against evolving national serialization databases and emerging blockchain-based provenance protocols.
Market Dynamics
Regulatory mandates for unit-level pharmaceutical traceability are forcing packaging converters to absorb serialization infrastructure costs while margin compression intensifies across label and tag supply chains.
Growth Catalysts
- DSCSA Enforcement:The US FDA mandates unit-level traceability for pharmaceutical distributors, compelling wholesale buyers to install verification systems that cascade demand upstream to packaging suppliers.
- RFID Cold-Chain Expansion:Temperature-sensitive biologics shipments require real-time location and thermal logging, driving premium tag adoption in pharmaceutical logistics networks.
- India CDSCO Serialization:Domestic pharmaceutical exports to regulated markets require track and trace compliance, stimulating local label and authentication substrate manufacturing capacity.
Market Restraints
- Silicon Shortage Volatility:RFID inlay production depends on semiconductor wafer supply concentrated in Taiwan and South Korea, creating input cost instability for smart tag manufacturers.
- European REACH Compliance:Adhesive and substrate chemical composition restrictions add formulation complexity and testing overhead for European label converters.
- Optical Scanning Substitution:Machine vision systems for direct package marking threaten demand for physical labels in high-volume beverage and food segments.
Strategic Opportunities
- Brazil ANVISA Mandates:Pending pharmaceutical serialization regulations create first-mover advantage for equipment and substrate suppliers establishing local validation partnerships.
- Blockchain Provenance Convergence:Integration of immutable ledger protocols with existing verification databases opens new service revenue streams for data architecture providers.
- Cosmetics Digital Engagement:QR code deployment for consumer loyalty programs in prestige beauty brands expands addressable market beyond regulatory minimums.
Industry Challenges
- Validation Engineering Scarcity:Pharmaceutical packaging lines require IQ/OQ/PQ documentation expertise that outpaces current technical training pipeline output.
- Legacy MES Integration:Brownfield manufacturing sites struggle to connect new serialization stations to existing manufacturing execution systems without custom middleware development.
- Multi-National Database Interoperability:Stakeholders must maintain simultaneous compliance with EU EMVS, US EPCIS, and emerging national verification systems without protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Track and Trace Packaging Market |
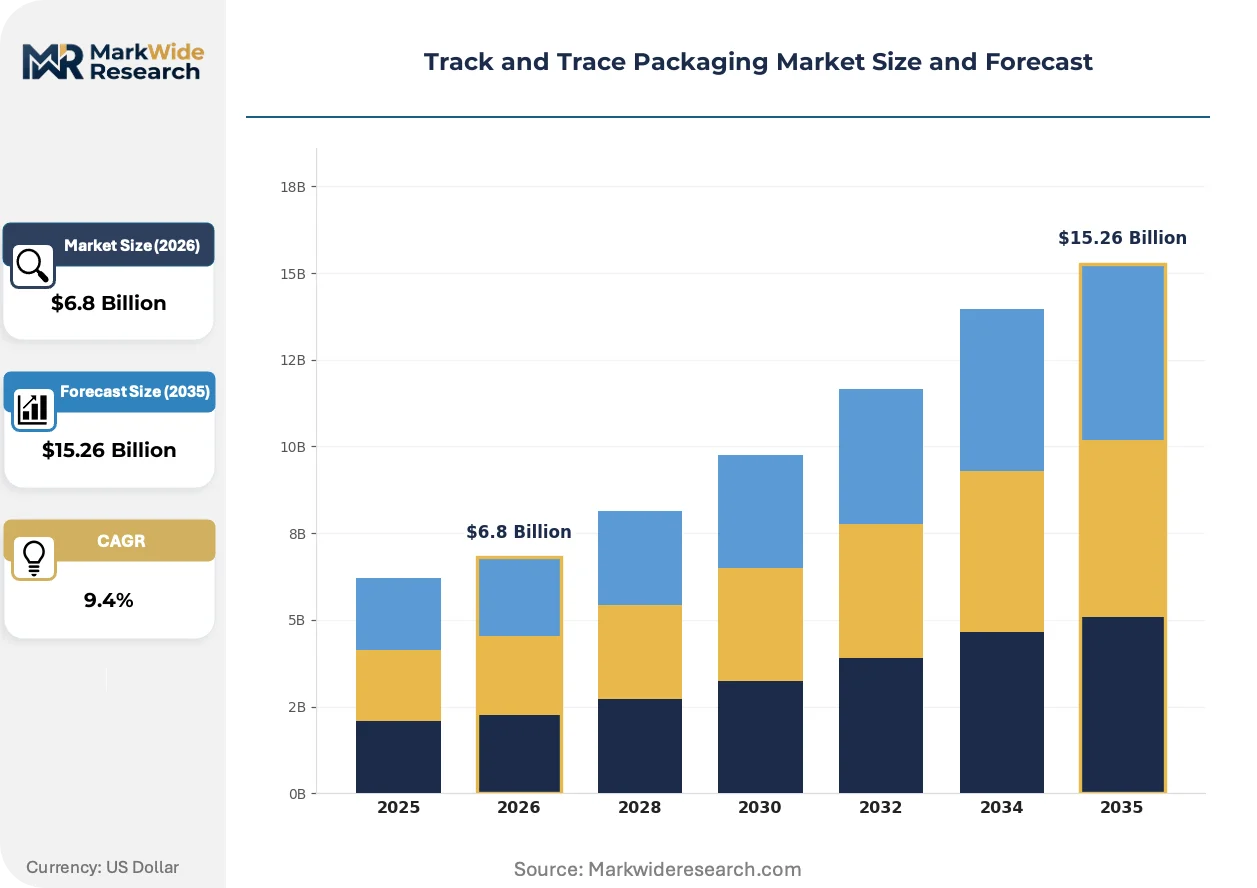
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Tags, Barcodes, RFID Technology: Digital Watermarking, 2D Codes, QR Codes, NFC End User: Pharmaceuticals, Cosmetics, Food & Beverage, Electronics Distribution Channel: Retail, E-commerce, Direct Sales, Distributors |
| Companies Covered | Optel Group, Antares Vision, Zebra Technologies, Systech International, TraceLink, Siemens AG, Avery Dennison, Uhlmann Group, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Track and Trace Packaging Market Evolving Landscape
Cloud-native verification architectures are displacing on-premise aggregation systems, while substrate innovations embed authentication directly into packaging materials rather than applied labels.
Digital watermarking technology embeds encrypted data within printed graphics visible to standard smartphone cameras. Pharmaceutical manufacturers in Switzerland and Singapore pilot this for consumer verification without dedicated scanner hardware. The technology is integrating directly into folding carton printing workflows, compressing equipment footprint and eliminating separate label application stations.
REACH amendments tighten adhesive substance restrictions for European label production. Converters reformulate hot-melt and pressure-sensitive chemistries to maintain bond performance under new substance thresholds. German packaging sites face the steepest compliance timeline, accelerating supplier qualification cycles for compliant raw material sources.
Contract packaging organizations consolidate procurement authority for serialization equipment across multi-site networks. Large pharmaceutical sponsors now mandate unified data formats and vendor certification tiers, displacing site-level purchasing autonomy. This concentration is most visible in North American and Western European markets where sponsor-contractor relationships dominate pharmaceutical manufacturing.
Track and Trace Packaging Market Segmentation
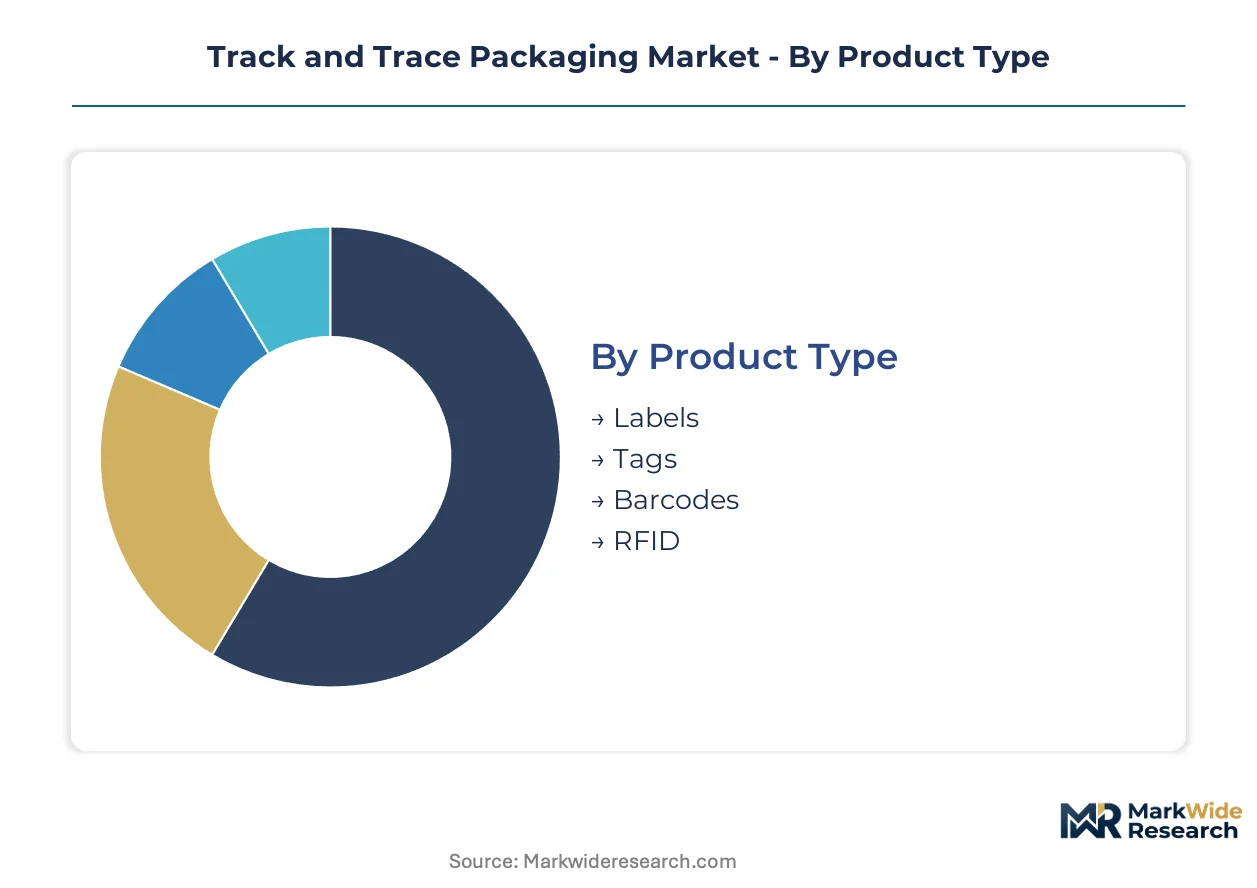
Track and trace packaging procurement hinges on regulatory tier, environmental exposure, and data carrier sophistication. Buyers segment by authentication intensity rather than commodity specifications, with pharmaceutical mandates commanding premium substrate investments and food retailers optimizing for consumer engagement at minimal unit cost.
Product Type:
Cost tier drives material selection, with adhesive substrate chemistry and data carrier integration determining per-unit economics across regulated versus non-regulated supply chains.
- Labels:Pressure-sensitive and shrink-sleeve constructions dominate pharmaceutical primary packaging, with tamper-evident substrates meeting FDA DSCSA and EU FMD verification requirements. Demand concentrates in German and US contract packaging sites where serialization line retrofits require validated label applicator integration.
- Tags:Hang tags and looped constructions serve apparel and electronics logistics, with synthetic substrates surviving extended supply chain handling. Indian pharmaceutical exporters deploy specialized tags for pallet-level aggregation under CDSCO export compliance protocols.
- Barcodes:Linear and stacked symbologies persist in food retail distribution, constrained by legacy scanner infrastructure at US grocery chains.
- RFID:UHF and HF inlays command cold-chain pharmaceutical applications where real-time temperature logging justifies semiconductor costs.
Volume sits with Labels; growth tilts toward RFID.
Technology:
Application environment dictates authentication method, with direct marking versus applied carrier trade-offs governed by line speed, substrate material, and verification infrastructure maturity.
- Digital Watermarking:Encrypted data embeds within printed graphics visible to standard smartphone cameras, eliminating dedicated scanner hardware. Swiss pharmaceutical manufacturers pilot this for consumer-facing verification, while Singapore packaging converters integrate watermarks directly into folding carton workflows to compress equipment footprint.
- 2D Codes:Data Matrix and GS1-128 symbols carry dense serialization data for pharmaceutical unit-level traceability, mandated by US FDA DSCSA and EU EMA verification systems. German packaging lines represent the densest installed base of 2D verification stations.
- QR Codes:Open-standard readability drives cosmetics and food adoption where consumer engagement supplements regulatory minimums.
- NFC:Near-field communication enables tap-to-verify authentication for prestige beauty brands and high-value electronics.
2D Codes anchor current pharmaceutical compliance; Digital Watermarking expands most quickly as carton converters seek equipment consolidation.
End User:
Customer type determines authentication intensity, with life-science regulatory exposure creating tiered demand for validation documentation and substrate traceability.
- Pharmaceuticals:Unit-level serialization mandates under US DSCSA and EU FMD drive the highest authentication investment per package. US wholesale distributors and European national verification systems cascade compliance requirements upstream to packaging converters.
- Cosmetics:QR code deployment for loyalty programs and anti-counterfeiting expands addressable market beyond regulatory floors, with prestige beauty brands in France and Italy leading consumer engagement integration.
- Food & Beverage:GS1 standards and retailer traceability initiatives govern adoption, with US grocery chains and European retail consortiums driving batch-level coding requirements.
- Electronics:High-value device authentication and grey-market diversion prevention motivate serialization, concentrated in East Asian manufacturing clusters and US distribution hubs.
Pharmaceuticals command premium pricing; Cosmetics gains share fastest through voluntary brand protection investment.
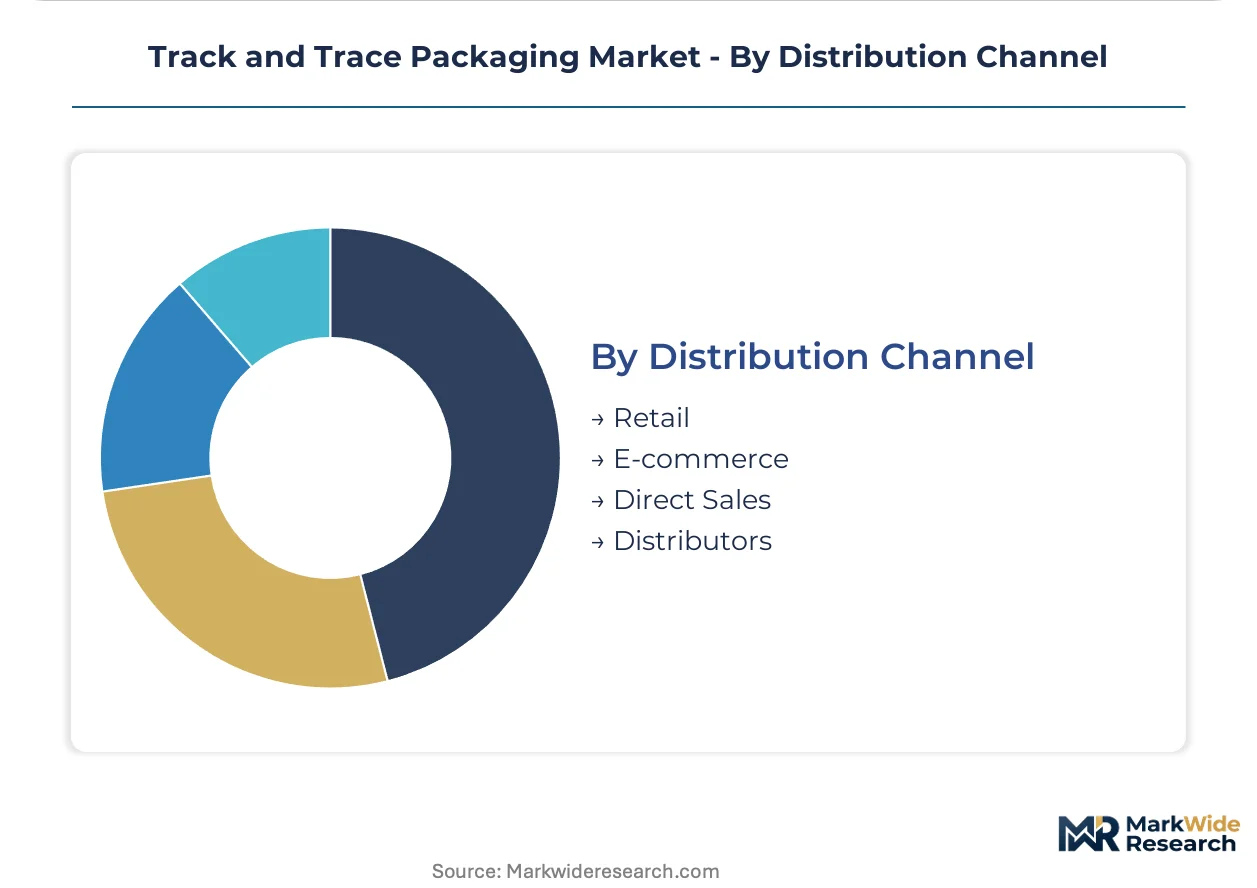
Distribution Channel:
Supply concentration shapes procurement authority, with channel structure determining whether serialization specifications flow from brand owners, contract manufacturers, or retail consolidators.
- Retail:Grocery and pharmacy chains impose supplier traceability standards, with US and German retail networks mandating GS1-compliant labeling for inbound logistics.
- E-commerce:Platform authentication requirements and return-fraud prevention drive packaging investment, concentrated in US and Chinese marketplace fulfillment networks.
- Direct Sales:Manufacturer-controlled channels enable customized serialization protocols for high-value pharmaceuticals and medical devices.
- Distributors:Pharmaceutical wholesale intermediaries under US DSCSA and EU FMD verification obligations drive aggregation infrastructure demand.
Retail channels dominate label volume; E-commerce climbs the fastest as marketplace authentication requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adhesive substrate manufacturing clusters in Germany's Rhineland and Switzerland's Basel region supply tamper-evident label stock to pharmaceutical serialization programs across Western Europe and North America.
United States
Pharmaceutical wholesale distributors under FDA DSCSA mandates drive aggregation infrastructure investment at contract packaging sites in New Jersey and Pennsylvania. The Drug Supply Chain Security Act requires unit-level verification systems by November 2024, accelerating demand for validated print-and-apply stations. Indianapolis hosts dense concentrations of pharmaceutical manufacturing where serialization line retrofits consume premium label substrates.
Germany
EMA-coordinated FMD compliance through Germany's national medicine verification system compels packaging converters in Bavaria and North Rhine-Westphalia to reformulate adhesives under REACH amendments. German label producers face accelerated substance restriction timelines, forcing supplier qualification cycles for compliant raw materials. Stuttgart's industrial automation corridor supplies edge-computing modules embedded directly into packaging line PLCs.
India
CDSCO serialization requirements for pharmaceutical exports to regulated markets stimulate label and authentication substrate manufacturing capacity in Gujarat and Maharashtra. Domestic contract packaging organizations in Hyderabad and Mumbai upgrade verification infrastructure to meet EU and US import standards. Indian label converters absorb semiconductor cost volatility from Taiwan-sourced RFID inlay supply chains.
Switzerland
Swiss pharmaceutical manufacturers pilot digital watermarking for consumer-facing verification without dedicated scanner hardware, leveraging Basel's packaging innovation cluster. Swissmedic oversight of serialization validation creates demand for high-margin documentation services. Zurich-area converters integrate watermarking directly into folding carton workflows, compressing equipment footprint at pharmaceutical packaging sites.
Brazil
Pending ANVISA pharmaceutical serialization regulations create first-mover positioning for equipment suppliers establishing validation partnerships in São Paulo state. Brazilian contract packaging organizations anticipate compliance deadlines modeled on EU FMD architecture. Campinas and São Paulo city pharmaceutical manufacturing clusters represent primary infrastructure investment targets for track and trace system providers.
Track and Trace Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native verification architectures and blockchain provenance integration. The vendor base stratifies across three maturity tiers: industrial automation conglomerates with embedded packaging line integration, specialized pharmaceutical inspection heritage firms, and hardware-dominant ruggedized equipment suppliers. Strategic differentiation concentrates on validation service margins, edge-computing module deployment, and multi-national database interoperability protocols. Competitive moves center on M&A for serialization software assets and capacity expansion in India and Brazil to capture regulatory compliance cycles.
Within the pharmaceutical inspection heritage tier, Optel Group and Antares Vision exemplify validation-service-centric positioning. Zebra Technologies anchors the hardware-dominant archetype through ruggedized print-and-apply station deployment. Among industrial automation conglomerates, Siemens AG occupies a position emphasizing edge-computing integration into packaging line control systems. These three archetypes represent distinct competitive vectors: software-heavy validation documentation, durable hardware for contract packaging environments, and embedded automation modules reducing line footprint.
| Leading Market Players |
|---|
| Optel Group |
| Antares Vision |
| Zebra Technologies |
| Systech International |
| TraceLink |
| Siemens AG |
| Avery Dennison |
| Uhlmann Group |
| Syntegon Technology |
| Others |
Value Network & Pricing Analysis
Pharmaceutical contract packaging organizations concentrate procurement authority across multi-site networks, compressing supplier pricing power into long-term validation service contracts with embedded hardware refresh cycles. This buyer consolidation forces equipment vendors to unbundle software subscriptions from hardware capital expenditure, shifting revenue toward recurring validation documentation fees.
Pricing Analysis
Validation service bundling separates premium-tier offerings from commodity hardware transactions, with IQ/OQ/PQ documentation packages commanding margins that bare equipment sales cannot match. Price differentiation rests on FDA certification tier and edge-computing integration depth, not unit specifications alone. Pricing pressure stems from semiconductor cost volatility in Taiwan-sourced RFID inlays, squeezing smart tag manufacturers. Contract packaging organizations show highest price sensitivity for line-retrofit equipment, while innovator pharmaceutical sponsors absorb premium pricing for cloud-native verification architectures.
Supply Chain Analysis
India's domestic-content mandates for pharmaceutical export compliance are reshaping label and substrate sourcing toward Gujarat and Maharashtra manufacturing clusters. Semiconductor wafer supply concentrates in Taiwan and South Korea, while adhesive substrate manufacturing anchors in Germany's Rhineland and Switzerland's Basel region. Raw material dependencies span silicon wafers, tamper-evident film stocks, and REACH-compliant adhesive chemistries. Single-source vulnerability in Taiwan semiconductor supply creates systemic risk for RFID inlay production. Distribution runs through pharmaceutical contract packaging networks and national verification system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native verification architectures are displacing legacy on-premise aggregation systems, with digital watermarking technology replacing dedicated scanner hardware in pharmaceutical packaging workflows.
For Market Incumbents: Anchor market position through backward integration into validation documentation services and captive cloud infrastructure development. Threat substitution from machine vision direct-marketing systems demands defensive investment in carton-integrated watermarking partnerships. Capacity addition in India and Brazil captures regulatory compliance cycles before ANVISA and CDSCO deadlines harden. For New Entrants and Emerging Players: Contract packaging organizations represent the most penetrable channel partner type for cloud-native serialization software plays. White-space targets include cosmetics digital engagement programs in France and Italy, plus Brazilian pharmaceutical validation partnerships ahead of ANVISA mandates. Go-to-market leverage rests on SaaS-tiered pricing that unbundles validation from capital equipment. For Investors and Strategic Acquirers: The window for entry favors software-heavy validation specialists with pharmaceutical inspection heritage over hardware-dominant equipment suppliers. Long-term viability centers on multi-national database interoperability capabilities spanning EU EMVS, US EPCIS, and emerging national verification systems. Acquisition target archetype: cloud-native verification platforms with embedded edge-computing modules. Signal to watch: blockchain provenance protocol integration announcements from major pharmaceutical sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Verification Platform Launch | Displaces on-premise aggregation systems at US contract packaging sites. |
| Validation Service Capacity Expansion | Captures IQ/OQ/PQ documentation scarcity premium in German pharmaceutical clusters. |
| Digital Watermarking Technology Partnership | Integrates encrypted authentication into Swiss folding carton workflows. |
| RFID Inlay Supply Agreement | Secures semiconductor allocation from Taiwan for cold-chain pharmaceutical tags. |
| Blockchain Provenance Protocol Integration | Opens service revenue streams from immutable ledger data architecture. |
Research Methodology
Independent corroboration across packaging line engineers, pharmaceutical quality assurance directors, and contract manufacturing procurement leads underwrites the qualitative findings. Secondary validation draws from FDA DSCSA guidance documents, EMA FMD implementation reports, CDSCO export compliance circulars, and EU REACH substance restriction amendments. Bottom-up equipment shipment analysis triangulates against top-down pharmaceutical serialization mandate compliance timelines.
Rate-of-change decomposition separates hardware unit growth from validation service revenue expansion across the projection horizon. Segmentation dimensions span product type, data carrier technology, end-use regulatory tier, and regional compliance cluster. CAGRs derive from pharmaceutical mandate enforcement calendars, RFID cold-chain adoption curves, and cosmetics digital engagement penetration. Forecast inputs incorporate semiconductor supply volatility indices and national verification system deployment schedules.
Caveats apply where Taiwan semiconductor supply disruptions, REACH adhesive reformulation delays, or ANVISA regulatory timeline revisions could materially shift the outlook. Forecasts reflect assumptions about interoperability protocol standardization and cloud migration willingness among brownfield pharmaceutical sites. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market