
 Gel Packs Market | 2026-2036
Gel Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Packs Market Foresight
The divergence between premium and commodity tiers is hardening as pharmaceutical-grade gel packs with validated temperature assurance command sustained price premiums over basic cold shipping commodities. Cardinal Health leverages its hospital distribution network to sustain dominant positioning in clinical cold chain logistics. Cryopak differentiates through specialized phase-change formulations that target precise thermal ranges for biologics transport. Nordic Ice competes aggressively on reusable product lines that reduce per-shipment waste costs for high-volume e-commerce food brands.
Gel packs are sealed, flexible containers filled with hydrophilic polymer gels, saline solutions, or phase-change materials that absorb, retain, and release thermal energy across defined temperature ranges, typically manufactured through vacuum-sealing or injection-molding processes to ensure leak-proof performance during transit. Their primary commercial purpose centers on passive temperature control for temperature-sensitive goods where active refrigeration is impractical or cost-prohibitive. Reusable gel packs lead the product type category due to sustainability mandates from corporate procurement departments, while cold gel packs represent the fastest-growing application segment as mRNA vaccine distribution requirements expand validated packaging demand. Plastic pouches remain the dominant packaging format though vacuum-sealed packs capture margin pools in premium pharmaceutical segments where contamination risk carries severe liability exposure.
FDA validation requirements for pharmaceutical cold chain packaging, EPA regulations on disposable plastic waste streams, and REACH compliance for polymer gel compositions collectively shape product development priorities and market access conditions across major demand centers. These frameworks force manufacturers to maintain dual certification portfolios that increase fixed compliance costs but simultaneously erect barriers against low-cost commodity entrants. Stakeholders must monitor evolving phase-change material classifications under chemical safety regimes and assess whether reusable format investments align with tightening extended producer responsibility obligations in key jurisdictions.
Market Dynamics
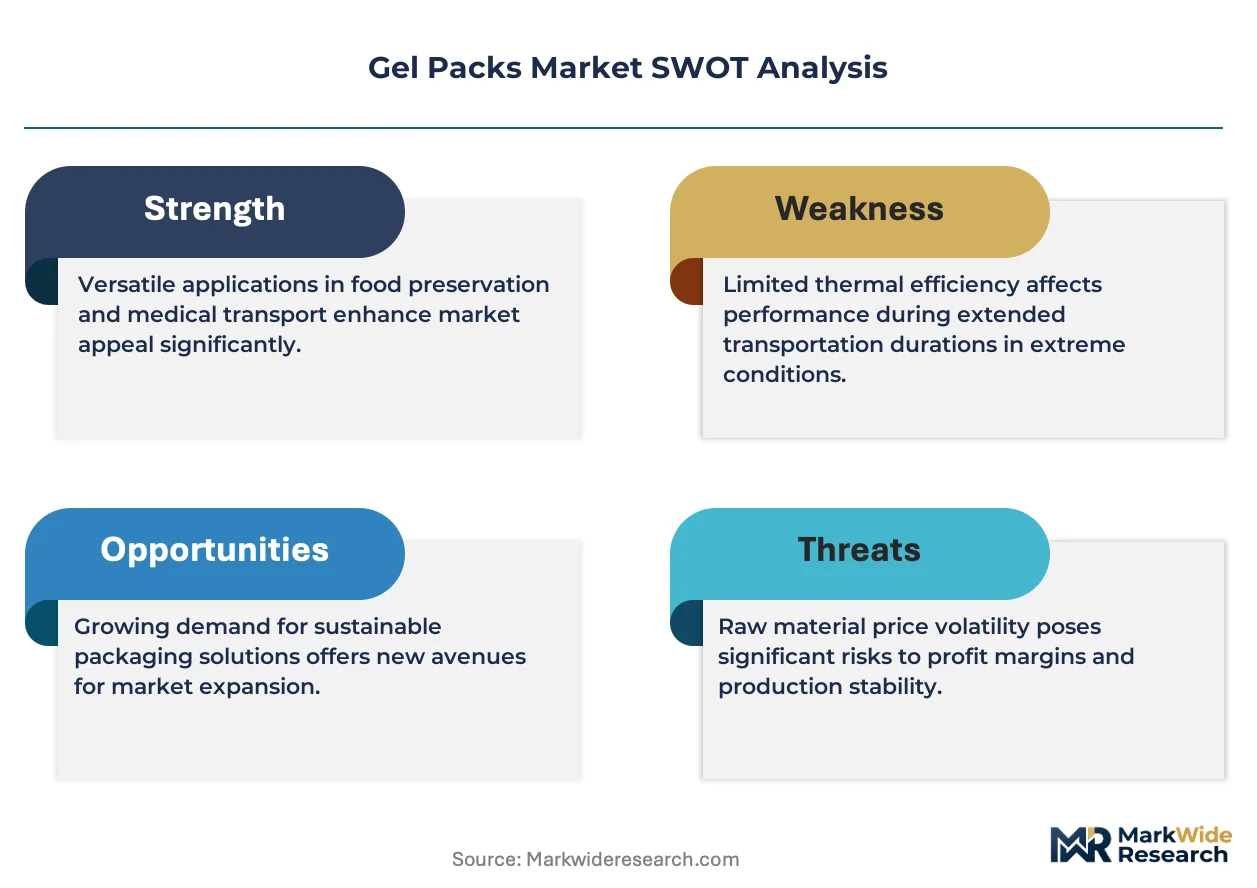
The pharmaceutical cold chain is hardening its validation requirements, forcing gel pack manufacturers to absorb fixed compliance costs that commodity producers cannot shoulder. This regulatory compression is bifurcating the competitive landscape between certified suppliers and undifferentiated volume players.
Growth Catalysts
- mRNA Vaccine Distribution:Biologics manufacturers require validated passive thermal packaging for ultra-cold transport chains. Gel packs with precise phase-change formulations address gaps where active refrigeration fails.
- Extended Producer Responsibility Mandates:The EU Green Deal and parallel state-level laws in California and New York penalize single-use packaging. Reusable gel pack formats capture procurement preference from corporate sustainability officers.
- REACH Compliance Barriers:Polymer gel composition standards under ECHA classifications exclude uncertified Asian imports. European manufacturers leverage this regulatory moat to defend margin pools in pharmaceutical segments.
Market Restraints
- Petrochemical Input Volatility:Hydrophilic polymer gels depend on acrylic acid derivatives whose pricing tracks crude oil futures. Manufacturers lack pricing power to pass through raw material swings to locked pharmaceutical contracts.
- Concentrated Cold Chain Infrastructure:Validated gel pack demand clusters in Germany, the United States, and Japan where biopharmaceutical distribution networks are mature. Peripheral markets lack the testing facilities to qualify new suppliers.
- Active Refrigeration Substitution:Compressor-based portable cold boxes from medical device specialists encroach on gel pack territory in high-value shipments where temperature excursion liability exceeds equipment capital cost.
Strategic Opportunities
- Cell and Gene Therapy Logistics:Cryogenic and controlled-rate freezing applications for CAR-T therapies require specialized phase-change materials below minus 80 degrees Celsius. Few gel pack suppliers currently certify for this thermal range.
- Indian Pharmaceutical Export Growth:CDSCO-aligned cold chain investments by Indian generic manufacturers create qualification demand for FDA-validated gel pack suppliers willing to establish local technical partnerships.
- Reusable Format Leasing Models:Third-party logistics operators in the Netherlands and Denmark pilot gel pack pooling systems that shift capital burden from shippers to packaging service providers.
Industry Challenges
- Dual Certification Timelines:Simultaneous FDA validation and REACH polymer dossier preparation extends product launch cycles by 18-24 months. Smaller manufacturers exhaust working capital during qualification delays.
- Phase-Change Material IP Fragmentation:Patent thickets around eutectic salt formulations and bio-based gels force licensing negotiations with multiple holders. Royalty stacking erodes margins on premium pharmaceutical grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Packs Market |
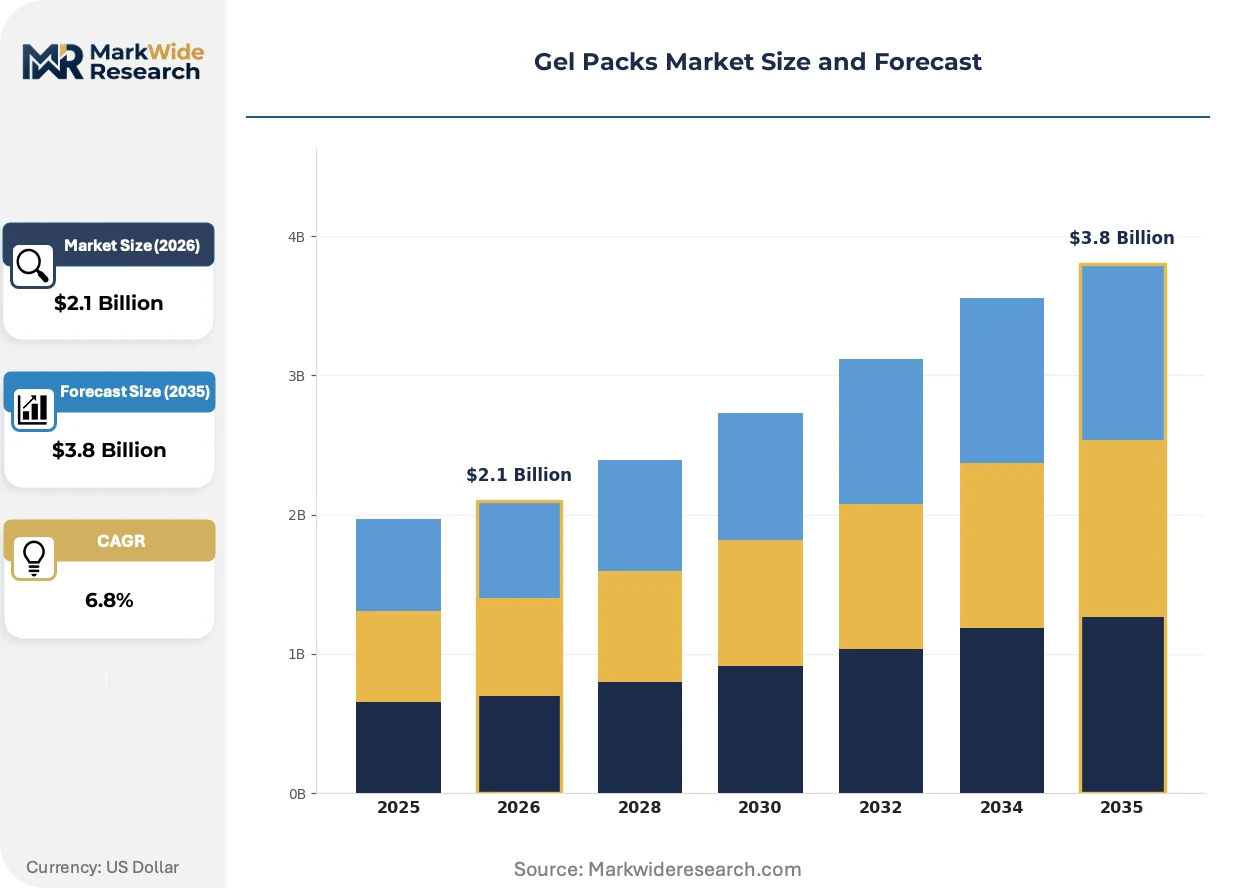
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Gel Packs, Hot Gel Packs, Reusable Gel Packs, Instant Gel Packs, Therapeutic Gel Packs Application: Medical Treatment, Food Preservation, Sports Therapy, Shipping & Logistics, Cosmetic Packaging End User: Hospitals, Pharmaceutical Companies, Sports Clinics, Food & Beverage Manufacturers, Beauty Salons Packaging Type: Plastic Pouches, Aluminum Foil Bags, Vacuum-Sealed Packs, Thermal Wrappings, Non-Woven Bags |
| Companies Covered | Polar Tech Industries, Cardinal Health, Cold Chain Technologies, Ice-Brix, Nordic Ice, Cryopak, 3M, Lifoam Industries, ThermoSafe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Packs Market Shifts & Advancements
Biodegradable polymer research and smart temperature monitoring integration are reshaping product development priorities. Manufacturers now compete on environmental credentials and data transparency rather than unit cost alone.
Phase-change materials engineered from plant-derived fatty acids and bio-based polyols are expanding into pharmaceutical cold chain applications. European logistics operators adopt these formats to preempt EFSA scrutiny of petroleum-derived gel compositions. The structural consequence is a compression of conventional polymer margins as sustainability premiums capture procurement preference.
EPA regulations on hydrofluorocarbon refrigerants under the AIM Act are accelerating passive cooling adoption in domestic pharmaceutical distribution. Active refrigeration systems face retrofit costs and supply constraints that gel packs circumvent. Specialty pharmacy networks in the United States are responding by mandating validated passive packaging for last-mile delivery.
Hospital procurement departments now bundle gel pack specification into enterprise cold chain contracts rather than treating packaging as a commodity input. Group purchasing organizations negotiate multi-year reusable format agreements that displace spot-market purchasing. This consolidation is most visible in German hospital networks where centralized pharmacy operations dominate biologics handling.
Gel Packs Market Segmentation
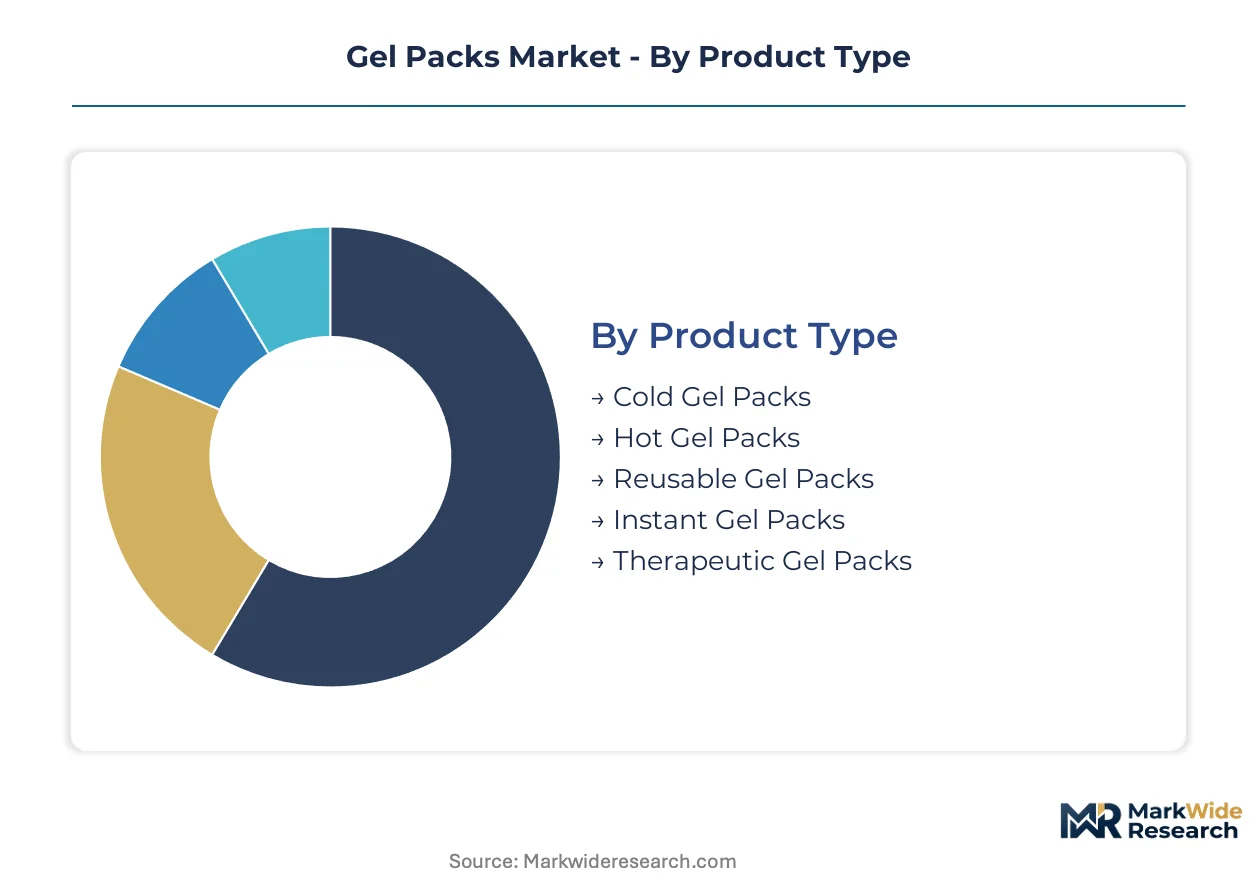
Segmentation in the gel packs market reveals how divergent buyer requirements create distinct margin pools. Pharmaceutical cold chain operators prioritize validated thermal performance, while food logistics buyers optimize for unit economics and waste reduction.
Product Type:
Buyers in this category differentiate primarily by sustainability mandates versus single-use convenience requirements.
- Reusable Gel Packs:Constructed from durable polymer shells with phase-change gel cores engineered for 500+ freeze-thaw cycles. Corporate procurement departments at pharmaceutical distributors in Germany and the United States now mandate reusable formats under extended producer responsibility compliance programs.
- Cold Gel Packs:Contain saline or hydrophilic polymer gels with engineered freezing points between minus 20 and plus 8 degrees Celsius. mRNA vaccine distribution networks in Japan and the United States absorb premium pricing for validated cold chain performance where temperature excursion liability exceeds packaging cost.
- Hot Gel Packs:Sodium acetate or supersaturated salt solutions activated by metal disc triggers deliver instant heat for therapeutic applications. Sports medicine clinics represent concentrated demand.
- Instant Gel Packs:Single-use chemical reaction packs combining ammonium nitrate and water for immediate cold without refrigeration. Emergency medical services and athletic trainers purchase in volume.
- Therapeutic Gel Packs:Microwaveable or freezable formats with fabric covers for patient comfort. Home healthcare and physical therapy practices drive replenishment cycles.
Reusable gel packs lead volumes today; cold gel packs are gaining share fastest.
Application:
Application segmentation tracks temperature sensitivity severity and regulatory oversight intensity across end-use sectors.
- Shipping & Logistics:Passive thermal packaging for biologics transport demands FDA-validated qualification protocols. Third-party cold chain operators in the United States and Germany specify gel packs with documented thermal profiles for regulatory audit trails.
- Medical Treatment:Post-operative cold therapy and chemotherapy port cooling require sterile, non-toxic gel compositions. Hospital group purchasing organizations in Japan consolidate procurement around certified suppliers.
- Food Preservation:E-commerce meal kit distributors specify food-grade gel packs with leak-proof seals for last-mile delivery. Sustainability pressures favor reusable pooling systems.
- Sports Therapy:Athletic trainers prioritize instant activation and portability over thermal duration. Professional sports franchises drive premium product adoption.
- Cosmetic Packaging:Temperature-sensitive skincare brands use gel packs to preserve active ingredient stability during direct-to-consumer shipment. Niche volume relative to medical applications.
Medical treatment anchors revenue per unit; shipping and logistics is expanding most quickly.
End User:
End user segmentation reflects procurement sophistication variance from enterprise contract negotiation to spot purchasing.
- Pharmaceutical Companies:Biologics manufacturers require gel packs with validated temperature assurance documentation for regulatory submissions. Supply agreements span multi-year horizons with technical qualification requirements.
- Hospitals:Centralized pharmacy operations at German hospital networks bundle gel pack procurement into enterprise cold chain contracts. Group purchasing organizations displace fragmented department-level buying.
- Food & Beverage Manufacturers:Processed food exporters to the United States and Japan specify gel packs for cold chain integrity across extended transit routes. Cost sensitivity limits premium format penetration.
- Sports Clinics:Outpatient rehabilitation facilities purchase therapeutic gel packs for patient home use. Retail margin structures differ from institutional procurement.
- Beauty Salons:Aesthetic clinics use gel packs for post-treatment cooling. Fragmented demand with limited volume concentration.
Pharmaceutical companies command the steepest pricing tier; hospitals are consolidating procurement fastest.
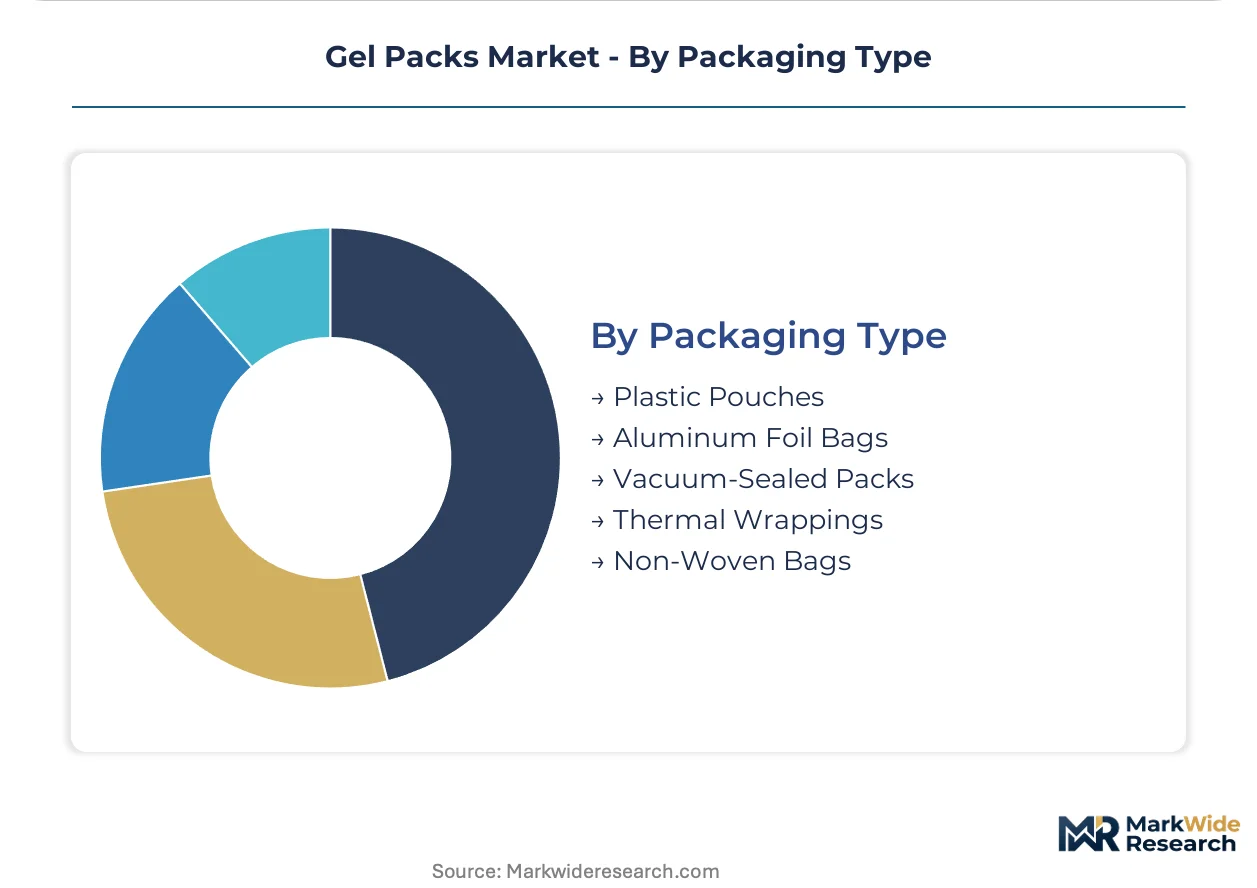
Packaging Type:
Packaging format selection correlates with contamination risk tolerance and premium positioning requirements.
- Vacuum-Sealed Packs:Multi-layer barrier films with evacuated airspace eliminate oxidation and microbial ingress. Pharmaceutical cold chain applications in Switzerland and the United States absorb 40-60% cost premiums for contamination risk mitigation.
- Plastic Pouches:Polyethylene or polypropylene single-layer construction dominates commodity food logistics. EPA regulations on disposable plastic waste streams in California and New York pressure format transition.
- Aluminum Foil Bags:Metalized barrier layers reflect radiant heat for extended thermal protection. High-value pharmaceutical shipments specify this format.
- Thermal Wrappings:Insulating sleeves or jackets surrounding gel pack cores. Used in conjunction with other formats rather than standalone.
- Non-Woven Bags:Fabric exteriors for patient-facing therapeutic applications. Comfort and reusability drive selection.
Plastic pouches dominate shipment volumes today; vacuum-sealed packs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold chain engineers and polymer chemists cluster in pharmaceutical manufacturing hubs where FDA, EMA, and PMDA validation requirements create specialized workforce demand.
United States
mRNA vaccine distribution networks and specialty pharmacy expansion drive validated gel pack procurement. EPA regulations under the AIM Act restrict hydrofluorocarbon refrigerants, accelerating passive cooling adoption. Boston-Cambridge biotech corridor manufacturers specify FDA-qualified thermal packaging for clinical trial logistics.
Germany
Hospital group purchasing organizations consolidate procurement around reusable formats under EU Green Deal extended producer responsibility mandates. REACH compliance dossiers for polymer gel compositions exclude uncertified imports. Bavarian pharmaceutical distribution hubs pilot gel pack pooling systems with Dutch logistics operators.
Japan
PMDA validation requirements for biologics cold chain packaging sustain premium pricing for qualified suppliers. METI guidelines on sustainable packaging procurement favor reusable phase-change formats. Osaka-Kobe pharmaceutical manufacturing belt concentrates demand for ultra-cold chain gel packs.
India
CDSCO-aligned cold chain investments by generic pharmaceutical exporters create qualification demand for FDA-validated packaging. Government PLI scheme incentives for active pharmaceutical ingredient manufacturing extend to cold chain infrastructure. Hyderabad and Ahmedabad pharmaceutical clusters seek technical partnerships with certified gel pack suppliers.
Switzerland
Swissmedic oversight of biologics transport sustains demand for vacuum-sealed barrier formats with contamination risk mitigation. Basel pharmaceutical headquarters operations mandate multi-year supplier qualification protocols. Alpine logistics corridors require validated passive thermal protection for temperature-sensitive shipments.
Gel Packs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where certified pharmaceutical-grade suppliers command sustained price premiums over commodity volume players. The competitive landscape separates into three strategic archetypes: diversified healthcare conglomerates with hospital distribution networks, specialized phase-change material formulators, and reusable format innovators targeting sustainability mandates. Dominant competitive moves include backward integration into polymer gel production and strategic partnerships with third-party logistics operators for pooling system deployment.
Within the diversified healthcare tier, Cardinal Health leverages integrated hospital distribution infrastructure. Cryopak and Nordic Ice exemplify specialized and sustainability-focused archetypes respectively, occupying distinct positioning vectors in the competitive matrix.
| Leading Market Players |
|---|
| Polar Tech Industries |
| Cardinal Health |
| Cold Chain Technologies |
| Ice-Brix |
| Nordic Ice |
| Cryopak |
| 3M |
| Lifoam Industries |
| ThermoSafe |
| Others |
Supply & Pricing Matrix
Backward integration into polymer gel production anchors supply security for certified pharmaceutical-grade manufacturers while simultaneously defending margin pools against commodity competitors. This upstream control over hydrophilic polymer feedstocks allows validated suppliers to absorb acrylic acid derivative volatility that undifferentiated volume players cannot shoulder.
Pricing Analysis
The bundled-versus-unbundled service split separates contract-based thermal validation packages from spot-market commodity transactions. Pharmaceutical distributors absorb premium-mid-economy pricing differentiation driven by FDA certification tiers and volume scale commitments. Cost compression in commodity food logistics segments is intensifying because petrochemical input volatility outpaces contract renegotiation cycles. Food and beverage manufacturers exhibit acute price sensitivity, while biologics manufacturers prioritize temperature assurance documentation over unit economics.
Supply Chain Analysis
Reverse-logistics networks for reusable gel pack refurbishment concentrate operational complexity in Germany, the United States, and the Netherlands where pooling system pilots are active. Manufacturing draws from acrylic acid derivatives, multi-layer barrier films, and phase-change salt formulations. Single-source vulnerability in eutectic salt formulations creates qualification bottlenecks for ultra-cold chain applications. Distribution runs through third-party cold chain operators and hospital group purchasing organizations with consolidated procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exclude uncertified Asian imports, creating margin sanctuary for qualified regional producers.
For Market Incumbents: Cement qualification moats through simultaneous FDA and ECHA dossier investments that exhaust smaller competitor working capital. Expand captive polymer gel production in Germany to preempt petrochemical input volatility. Active refrigeration substitution from portable compressor systems threatens passive packaging share in high-value shipments.
For New Entrants and Emerging Players: Enter via CDSCO-aligned technical partnerships with Indian generic pharmaceutical exporters seeking FDA-validated cold chain infrastructure. Target cell and gene therapy logistics where cryogenic phase-change material certification remains sparse. Pursue licensing arrangements with eutectic salt patent holders to circumvent IP fragmentation barriers.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap phase-change material formulators because dual certification timelines and fixed compliance costs prevent organic entry by new competitors. The five-to-ten year viability window favors suppliers with established REACH dossiers and FDA qualification protocols. Monitor EPA refrigerant regulations under the AIM Act for inflection signals accelerating passive cooling substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Gel Production | Captive acrylic acid derivative supply insulates margins from crude oil futures volatility. |
| Dual Certification Investment | Simultaneous FDA and REACH dossier preparation erects barriers against commodity entrants. |
| Reusable Format Leasing Models | Third-party logistics pooling systems shift capital burden from shippers to packaging service providers. |
| Cell and Gene Therapy Qualification | Cryogenic phase-change material certification below minus 80 degrees Celsius addresses unmet CAR-T logistics demand. |
| Biodegradable Polymer Transition | Plant-derived fatty acid formulations preempt EFSA scrutiny of petroleum-derived gel compositions. |
Research Methodology
Bottom-up pharmaceutical distributor modeling reconciled against top-down polymer gel production tracking forms the analytical core of this study. Primary interviews with cold chain logistics directors, regulatory affairs specialists, hospital procurement managers, and phase-change material R&D chemists were validated against secondary sources including FDA 510(k) filings, ECHA REACH registration databases, EPA AIM Act regulatory dockets, and EU Green Deal extended producer responsibility directives.
Input-output matrix framing connects hydrophilic polymer feedstock availability to finished gel pack qualification timelines across the projection horizon. Segmentation dimensions span product type, application severity, end-user procurement sophistication, and packaging format contamination risk tolerance. CAGRs were derived from elasticity-adjusted demand curves incorporating mRNA vaccine distribution requirements and reusable format adoption rates.
Inputs from ECHA polymer dossier registries and FDA qualification databases were available through the study window; gaps in proprietary phase-change material formulation specifications introduce uncertainty bands around thermal performance claims. Practitioners should monitor EPA refrigerant rulemakings and EU extended producer responsibility enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market