
 ASEAN and Gulf Countries MAP and VSP Packaging Market | 2026-2036
ASEAN and Gulf Countries MAP and VSP Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN and Gulf Countries MAP and VSP Packaging Market Outlook
REACH compliance is expanding the cost-of-entry calculus for MAP and VSP film suppliers exporting into European-bound supply chains from ASEAN and Gulf production bases. Amcor Plc leverages its integrated resin-to-film operations across Thailand and Malaysia to sustain margin stability under tightening chemical disclosure rules. Sealed Air Corporation anchors its Gulf presence through Jeddah-based technical service centers that specialize in halal-certified vacuum skin packaging for red meat exports.
Modified Atmosphere Packaging (MAP) and Vacuum Skin Packaging (VSP) are gas-flush and vacuum-sealing technologies that employ multi-layer coextruded films with oxygen transmission rates below 1 cc/m²/day to extend perishable shelf life. These systems serve commercial processors requiring precise atmospheric control—typically residual oxygen levels of 0.1-0.5% for fresh proteins—to maintain color stability and suppress microbial growth. Flexible packaging dominates volume flows in ASEAN fruit and vegetable export corridors where lightweight barrier bags reduce air freight costs. Sustainable packaging registers the fastest structural ascent as Saudi Arabia's SABIC-certified circular polymers and Indonesia's emerging bio-PE mandates reshape material procurement specifications across the Gulf-Thailand trade lane.
EMA chemical safety standards and Saudi SFDA food-contact material rules jointly determine which film formulations gain market access across the dual-region trade architecture. BIS-equivalent Gulf standardization bodies in the UAE and Thailand's Industrial Standards Institute enforce divergent migration limit testing protocols that fragment certification costs for pan-regional suppliers. Stakeholders must monitor whether ASEAN-Gulf mutual recognition agreements on polymer safety testing emerge before regional capacity investments lock in non-interoperable compliance systems.
Market Dynamics
EU Green Deal extraterritorial carbon border pressures are restructuring material procurement across Gulf-to-Europe export corridors, forcing certified recyclable film adoption ahead of domestic mandate timelines.
Growth Catalysts
- High-barrier vacuum skin technology:Fresh meat processors in Thailand and Vietnam accelerate equipment purchases to capture premium export shelf-life requirements.
- Saudi cold-chain infrastructure density:Riyadh-Jeddah corridor investments concentrate demand for temperature-validated MAP systems.
- REACH chemical disclosure rules:European-bound supply chains from ASEAN production bases expand compliant film formulation demand.
Market Restraints
- Ethylene-vinyl alcohol resin price volatility:Gulf-based converters face margin compression from petrochemical feedstock swings.
- Multi-layer film recycling technical limitation:Current mechanical separation cannot recover barrier polymers at commercial scale.
- Divergent migration testing protocols:UAE and Thai standardization bodies enforce non-interoperable certification requirements.
Strategic Opportunities
- Halal-certified VSP white space:Jeddah technical service capacity remains underdeveloped relative to red meat export volume.
- Bio-PE regulatory tailwind:Indonesia's emerging mandates reshape material specifications across Gulf-Thailand trade lanes.
- SABIC circular polymer certification:Saudi Arabia's polymer safety framework creates first-mover positioning for compliant suppliers.
Industry Challenges
- Coextrusion die engineering skill scarcity:Five-layer barrier film production requires specialized technicians concentrated in Malaysia and Germany.
- Legacy gas-flush system integration friction:Retrofitting vacuum skin capability onto existing MAP lines demands custom mechanical redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN and Gulf Countries MAP and VSP Packaging Market |
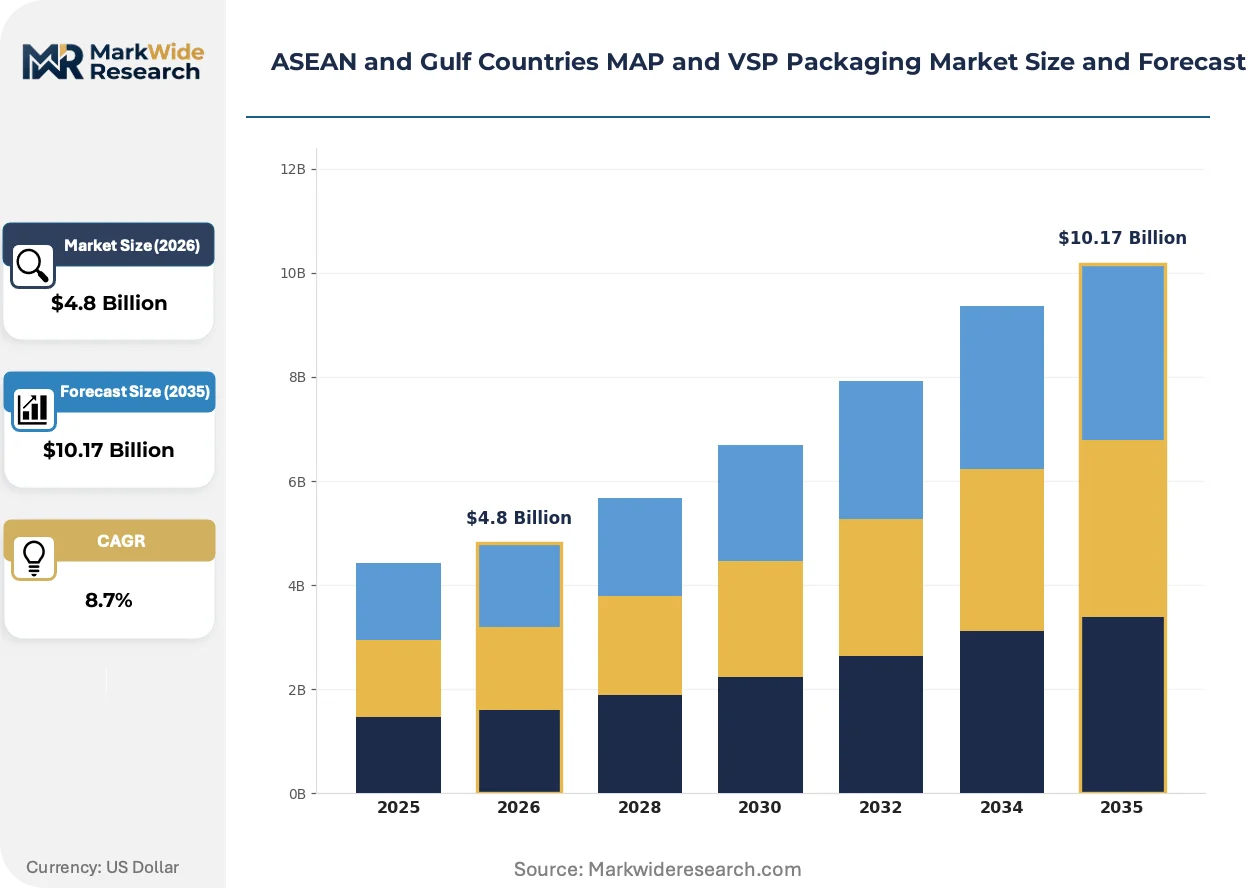
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Sustainable Packaging Material: Plastic, Paper, Glass, Metal End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Amcor Plc, Sealed Air Corporation, Berry Global Inc, Winpak Ltd, Napco National, Vishakha Polyfab Pvt Ltd, Linpac Packaging, MULTIVAC, Schur Flexibles, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN and Gulf Countries MAP and VSP Packaging Market Strategic Shifts
Active barrier technologies and circular material flows are compressing traditional film procurement cycles across ASEAN-Gulf protein export corridors.
Mono-material polyethylene barrier films with plasma-deposited silicon oxide coatings are consolidating technical roadmaps for recyclability compliance. Thai fruit exporters and Vietnamese seafood processors adopt these structures at pilot scale. The technology is consolidating supplier R&D budgets away from conventional multi-layer coextrusion platforms.
EU Green Deal carbon border adjustment mechanisms impose embedded emissions reporting on Gulf-based polymer exports. Saudi and UAE converters must document Scope 3 upstream footprints to maintain European market access. Red meat VSP shipments to Rotterdam and Hamburg face the most immediate documentation requirements.
Processor procurement teams now specify certified circular content percentages in annual film supply agreements. Traditional spot purchasing through distributor networks loses share to direct mill relationships with audit rights. This pattern concentrates contract volume with Thai and Malaysian resin-to-film integrated producers serving Riyadh and Jeddah meatpacking clusters.
ASEAN and Gulf Countries MAP and VSP Packaging Market Segmentation
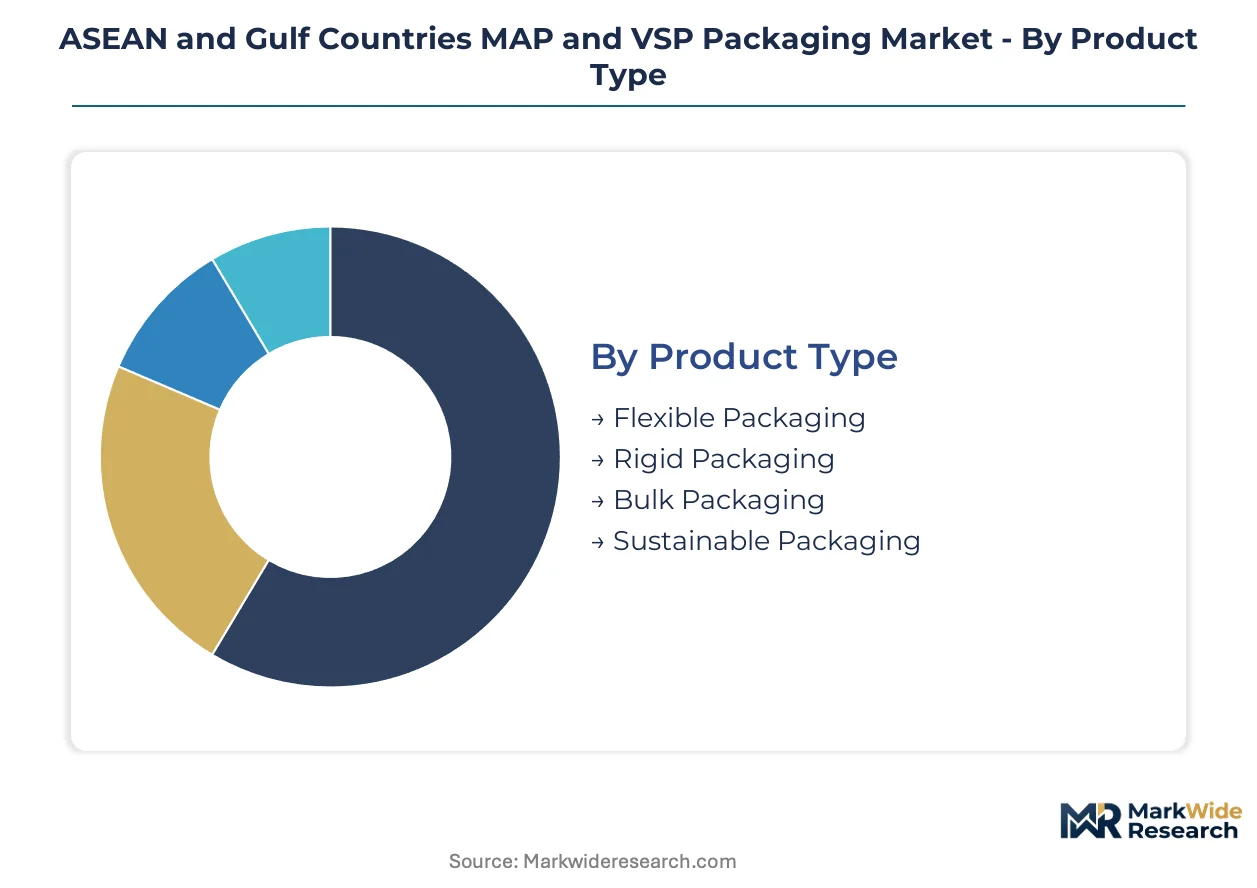
Segmentation in the ASEAN and Gulf Countries MAP and VSP Packaging Market reveals how capital deployment, material specifications, and channel access create divergent margin profiles across the Riyadh-Jeddah corridor and Thai export zones.
Product Type:
Capital intensity varies sharply: vacuum skin packaging lines demand precision coextrusion dies and gas-flush calibration systems that flexible packaging extruders avoid entirely.
- Flexible Packaging:Multi-layer coextruded barrier bags with oxygen transmission rates below 1 cc/m²/day dominate Thai fruit and Vietnamese seafood export volumes. Lightweight structures reduce air freight costs for Bangkok and Ho Chi Minh City processors serving European retail chains.
- Sustainable Packaging:Mono-material polyethylene films with plasma-deposited silicon oxide coatings are consolidating R&D budgets as SABIC-certified circular polymers and Indonesia's emerging bio-PE mandates reshape procurement specifications. Thai fruit exporters adopt these at pilot scale ahead of EU Green Deal carbon border documentation requirements.
- Rigid Packaging:Thermoformed barrier trays for red meat VSP applications require matched tooling investments that Gulf-based converters prioritize for halal-certified export lines.
- Bulk Packaging:Modified atmosphere bulk bins for Saudi dairy and poultry distribution concentrate in Riyadh cold-chain hubs where temperature validation protocols are strictest.
Flexible packaging absorbs the bulk of installed capacity; sustainable packaging is expanding most quickly.
Material:
Feedstock access and migration testing compliance determine which material classes gain market entry across the dual-region trade architecture.
- Plastic:Ethylene-vinyl alcohol copolymers and polyamide barrier layers remain indispensable for oxygen scavenging in fresh protein applications. Gulf-based converters face margin compression from petrochemical feedstock price swings.
- Paper:Fiber-based barrier structures with water-based coatings are gaining traction in Indonesian personal care and select food segments where plastic reduction targets apply.
- Glass:Pharmaceutical ampoules and vials for Saudi SFDA-regulated drug distribution require specialized annealing and barrier coating capabilities concentrated in UAE free zones.
- Metal:Tinplate and aluminum containers for heat-processed seafood retort applications serve niche export specifications to Middle Eastern markets.
Plastic commands the dominant share of film and tray tonnage; paper-based alternatives are climbing the fastest on regulatory tailwinds.
End User:
Atmospheric control precision requirements and shelf-life extension value create tiered pricing power across customer verticals.
- Food & Beverage:Fresh meat processors in Thailand and Vietnam accelerate high-barrier VSP equipment purchases to capture premium export shelf-life requirements. Red meat VSP shipments to Rotterdam and Hamburg face immediate EU Green Deal embedded emissions documentation requirements.
- Pharmaceuticals:Saudi SFDA and UAE MOHAP enforce divergent food-contact and drug-contact material rules that fragment certification costs for pan-regional suppliers.
- Personal Care:Halal-certified barrier films for cosmetic and hygiene products concentrate in Jeddah technical service corridors.
- Electronics:Moisture barrier bags with desiccant integration serve semiconductor and component shipping through Singapore and Dubai logistics hubs.
Food and beverage claims the largest share of MAP and VSP volume; pharmaceuticals is gaining share fastest on regulatory compliance premiums.
Distribution Channel:
Channel selection determines whether film suppliers engage direct mill relationships or distributor networks with audit rights.
- Supermarkets:Centralized procurement by Saudi and Thai retail chains drives specification of certified circular content percentages in annual film supply agreements.
- Wholesalers:Traditional spot purchasing through distributor networks loses share to direct relationships as processor procurement teams demand upstream Scope 3 footprint documentation.
- Online Retail:E-commerce fulfillment requirements for ambient-stable meal kits and portion-controlled proteins are emerging in Bangkok and Riyadh urban corridors.
- Convenience Stores:Small-format retail in Vietnamese and Indonesian cities drives demand for single-serve MAP portions with abbreviated shelf-life requirements.
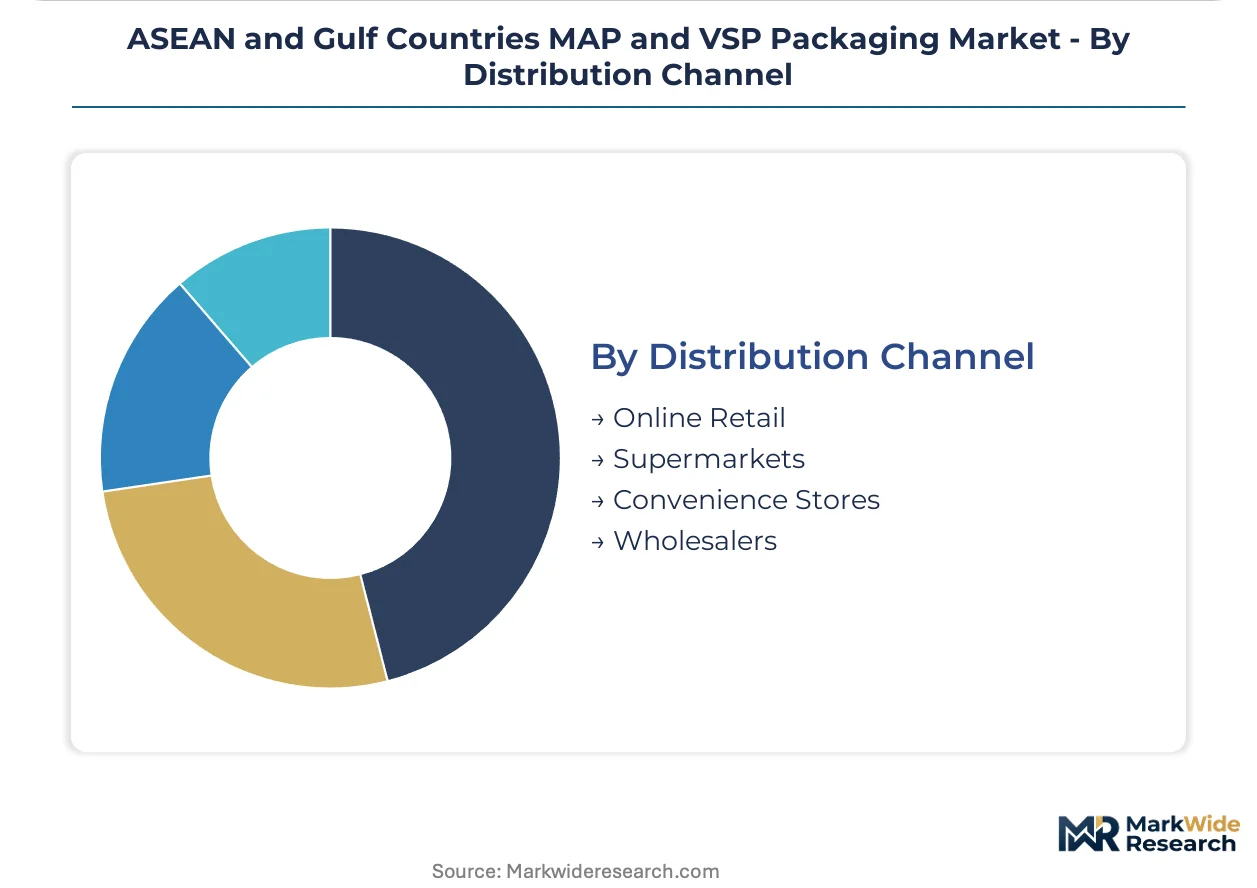
Supermarkets anchor the highest contract values; online retail is expanding most quickly on fulfillment infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along the Riyadh-Jeddah corridor and Thai export zones where cold-chain infrastructure investments are densest. Saudi Arabia and Thailand anchor procurement volumes for high-barrier vacuum skin packaging systems.
Saudi Arabia
Red meat processors in Riyadh and Jeddah drive VSP equipment deployment for halal-certified export lines. SFDA food-contact material rules enforce migration limit testing that filters non-compliant film suppliers. The Riyadh-Jeddah corridor hosts the densest cold-chain infrastructure investments in the Gulf, concentrating temperature-validated MAP system demand.
Thailand
Bangkok-based fruit exporters and seafood processors accelerate purchases of high-barrier vacuum skin packs for European retail chains. BIS-equivalent testing protocols from Thailand's Industrial Standards Institute create certification friction for pan-regional suppliers. The Eastern Economic Corridor clusters polymer-to-film integrated operations serving ASEAN protein export corridors.
Vietnam
Ho Chi Minh City seafood processors adopt gas-flush calibration systems to capture premium shelf-life requirements for EU-bound shipments. Emerging bio-PE regulatory discussions reshape material procurement specifications for Vietnamese converters. The Mekong Delta region concentrates shrimp and pangasius processing capacity driving barrier film demand.
United Arab Emirates
Dubai logistics hubs and Abu Dhabi polymer distribution centers anchor Gulf-to-Europe export corridor documentation requirements. MOHAP drug-contact material rules fragment certification costs for pharmaceutical barrier film suppliers. Jebel Ali free zones concentrate specialized annealing capabilities for SFDA-regulated pharmaceutical packaging.
Indonesia
Jakarta and Surabaya processors face emerging bio-PE mandates that reshape material specifications across Gulf-Thailand trade lanes. National plastic reduction targets in personal care segments drive fiber-based barrier structure adoption. The Java-Bali corridor concentrates domestic poultry and dairy distribution requiring modified atmosphere bulk bins.
ASEAN and Gulf Countries MAP and VSP Packaging Market Competitive Environment
Thai and Malaysian producers anchor one tier; Gulf-based specialists hold technical service positions closer to red meat export clusters. The vendor base separates between resin-to-film integrated operators and equipment-anchored service providers. Three archetypes dominate: integrated polymer producers with captive film extrusion, regional converters with halal certification capabilities, and European equipment licensors with localized technical centers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for SABIC circular polymer certification requirements.
Among integrated packaging multinationals, Amcor Plc and Sealed Air Corporation exemplify contrasting geographic anchoring strategies. Amcor's Thailand and Malaysia resin-to-film operations represent backward integration into polymer supply. Sealed Air's Jeddah-based technical service presence occupies a position within halal-certified vacuum skin packaging for red meat exports. Berry Global Inc completes the tier-one grouping as a scale-driven multinational with regional converting capabilities.
| Leading Market Players |
|---|
| Amcor Plc |
| Sealed Air Corporation |
| Berry Global Inc |
| Winpak Ltd |
| Napco National |
| Vishakha Polyfab Pvt Ltd |
| Linpac Packaging |
| MULTIVAC |
| Schur Flexibles |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between SABIC-certified circular polymers and conventional multi-layer barrier films splits pricing power across the ASEAN-Gulf corridor, with premium formulations commanding direct mill relationships while commodity grades flow through distributor spot markets. This bifurcation concentrates margin capture among Thai and Malaysian resin-integrated producers while Gulf-based converters absorb ethylene-vinyl alcohol resin volatility.
Pricing Analysis
Volume-mass flexible packaging for Thai fruit exports operates on thin contract margins, while precision VSP systems for Saudi halal-certified red meat capture premium pricing. Price differentiation rests on REACH compliance tiers and SABIC circular polymer certification status. Cost compression in standard-grade barrier films is intensifying because EVOH resin feedstock swings transmit directly to converter margins. Supermarket procurement teams exhibit lowest price sensitivity due to mandated circular content specifications, whereas Vietnamese seafood processors remain most sensitive to per-unit film costs.
Supply Chain Analysis
Regional distribution centers in Jeddah and Bangkok anchor hub-and-spoke patterns for temperature-validated MAP systems serving Riyadh meatpacking clusters and Ho Chi Minh City seafood processors. Geographic supply concentration centers on Thailand, Malaysia, and Saudi Arabia for polymer-to-film integrated operations. Raw material dependencies draw from ethylene-vinyl alcohol copolymers, polyamide barrier layers, and emerging bio-PE feedstocks. Single-source vulnerability in five-layer coextrusion die engineering—concentrated among Malaysian and German technician pools—poses structural supply chain risk. Distribution runs through direct mill relationships with audit rights replacing traditional spot purchasing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN and Gulf MAP and VSP packaging sector sits in a technology-transition phase as mono-material polyethylene films with plasma-deposited silicon oxide coatings displace legacy multi-layer coextrusion platforms. This substitution wave reconfigures competitive positioning across the Riyadh-Jeddah corridor and Thai export zones.
For Market Incumbents: Acquire specialized coextrusion die engineering capabilities to secure five-layer barrier film production talent concentrated in Malaysia and Germany. Consolidate backward integration into SABIC-certified circular polymer supply chains before Indonesia's bio-PE mandates reshape procurement specifications. Defend against margin compression from EVOH resin volatility by locking long-term offtake agreements with Saudi petrochemical suppliers. For New Entrants and Emerging Players: Digital-channel direct procurement platforms offer the most penetrable route for Vietnamese seafood processors seeking bypass distributor markups on high-barrier VSP films. Target halal-certified vacuum skin packaging white space in Jeddah technical service corridors where Sealed Air's localized presence remains underdeveloped relative to red meat export volume. Anchor go-to-market strategy through equipment-anchored service partnerships rather than commodity film distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated packaging multinationals seeking ASEAN resin-to-film backward integration. Long-term viability across the projection horizon favors producers with captive polymer supply and REACH-compliant formulation libraries. Monitor EU Green Deal carbon border documentation requirements as the signal to watch for inflection in Gulf-based converter competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Circular Polymer Supply | Captive SABIC-certified feedstock secures margin stability under tightening EU carbon border rules. |
| Halal-Certified VSP Technical Service Expansion | Jeddah-based service centers capture premium positioning in Saudi red meat export corridors. |
| Mono-Material Barrier Film R&D Scale-Up | Plasma-deposited silicon oxide coatings unlock recyclability compliance ahead of mechanical separation limits. |
| Direct Mill Relationship Development | Audit-rights contracts displace distributor spot purchasing for supermarket circular content mandates. |
| Five-Layer Coextrusion Die Engineering Acquisition | Specialized technician pools in Malaysia and Germany represent scarce production capability. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across film extrusion plant managers, Saudi and Thai supermarket procurement leads, halal certification technical directors, and cold-chain logistics operators. Secondary validation drew from SFDA food-contact material registrations, Thailand Industrial Standards Institute migration test protocols, EU ECHA REACH disclosure databases, and ASEAN customs trade statistics. Bottom-up capacity modeling and top-down demand estimation were triangulated against import-export flow data.
Granularity-level modeling deployed product type, material class, end-use vertical, and distribution channel dimensions at country-level resolution across Saudi Arabia, Thailand, Vietnam, UAE, and Indonesia. CAGRs were derived from segment-level volume and value build-ups applied across the projection horizon. Industry-specific forecast inputs included cold-chain infrastructure investment pipelines from Riyadh-Jeddah corridor development authorities and EU Green Deal carbon border implementation timelines affecting Gulf-to-Europe export documentation requirements.
The model holds under stable petrochemical feedstock pricing and continued ASEAN-Gulf trade lane openness; deviation in EVOH resin volatility spikes or bilateral polymer safety testing mutual recognition failures would shift competitive positioning. Forecasts reflect stated assumptions around SABIC circular polymer certification adoption rates and Indonesian bio-PE mandate implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Next Generation Packaging Market