
 Middle East and Africa Active and Intelligent Packaging Market | 2026-2036
Middle East and Africa Active and Intelligent Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Active and Intelligent Packaging Market Foresight
REACH-equivalent chemical safety frameworks under development across Gulf Cooperation Council member states is broadening compliance costs for imported active packaging substrates. BASF SE leverages its polymer additive portfolio to sustain formulation leadership across humidity-scavenging film applications. Honeywell International Inc anchors regional sensor integration through its barcode and RFID infrastructure deployed in Dubai's logistics corridors. Nampak Ltd competes in metal-based intelligent can formats for beverage applications across Southern Africa.
Active and intelligent packaging encompasses systems that interact with contained products or external environments through oxygen scavengers, moisture regulators, time-temperature indicators, or electronic tracking substrates to extend shelf life, authenticate provenance, or monitor condition integrity. Modified atmosphere packaging dominates food export applications from Morocco and Egypt into European retail channels, while RFID technology leads pharmaceutical serialization mandates across Saudi Arabia and the UAE. Smart labels occupy the fastest-expanding margin pool as Gulf retailers adopt NFC-enabled consumer engagement layers on premium cosmetics and electronics packaging.
Saudi Arabia's SFDA serialization requirements and South Africa's NRCS compulsory standards for food-contact materials are tightening product registration timelines across the region. The UAE's MOHAP pharmaceutical traceability directives and Egypt's emerging consumer protection labeling rules are reshaping specification sheets for imported intelligent packaging systems. Stakeholders must monitor divergent national implementation calendars for harmonized Gulf standards versus country-specific technical regulations to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
Pharmaceutical cold-chain logistics across the Gulf Cooperation Council corridor is accelerating uptake of sensor-enabled packaging, while South Africa's pending extended producer responsibility regulations are reshaping material compliance obligations across the value chain.
Growth Catalysts
- SFDA serialization requirements:Saudi Arabia's pharmaceutical traceability mandates are forcing packagers to deploy RFID-enabled labels for unit-level authentication.
- Humidity-scavenging films:Modified atmosphere packaging dominates food export applications from Morocco and Egypt into European retail channels.
- Dubai-Jebel Ali pharmaceutical free trade zone:Temperature-sensitive biologics transit through multimodal hubs, concentrating demand for time-temperature indicators.
Market Restraints
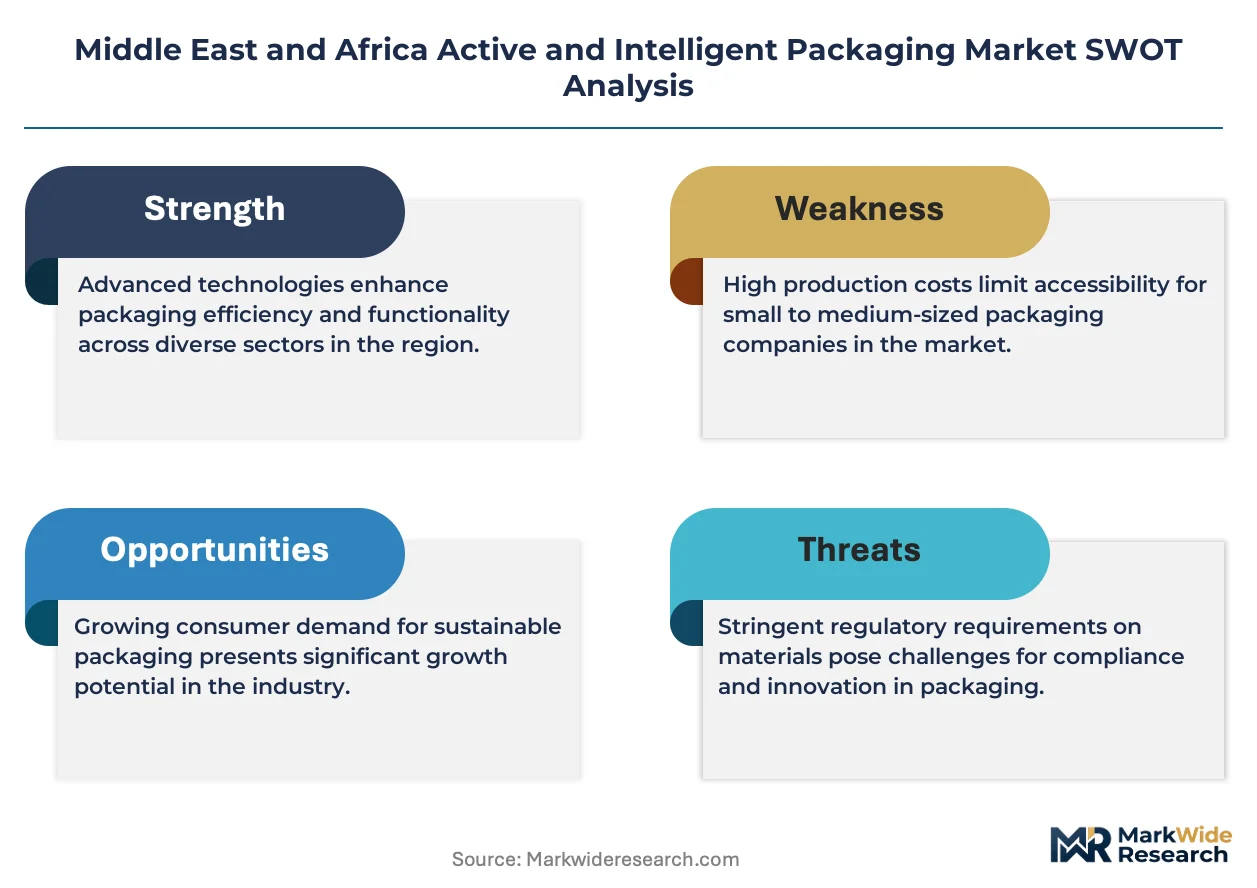
- REACH-equivalent chemical safety frameworks:Gulf Cooperation Council member states are broadening compliance costs for imported active packaging substrates.
- Polymer additive supply concentration:Formulation leadership for humidity-scavenging applications rests with a narrow supplier base in Western Europe.
- Metal can format limitations:Nampak's intelligent beverage cans face technical constraints in integrating flexible electronics at volume scale.
Strategic Opportunities
- Egypt's emerging consumer protection labeling rules:New specification requirements for imported intelligent packaging systems create first-mover advantage for compliant suppliers.
- NFC-enabled consumer engagement layers:Gulf retailers are adopting smart labels on premium cosmetics and electronics packaging.
- Biologics distribution expansion:The UAE's MOHAP pharmaceutical traceability directives are extending sensor integration into secondary and tertiary packaging tiers.
Industry Challenges
- RFID infrastructure integration:Honeywell's barcode and RFID systems in Dubai's logistics corridors require specialized technical talent scarce across the region.
- Divergent national implementation calendars:Harmonized Gulf standards versus country-specific technical regulations risk stranded inventory in cross-border distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Active and Intelligent Packaging Market |
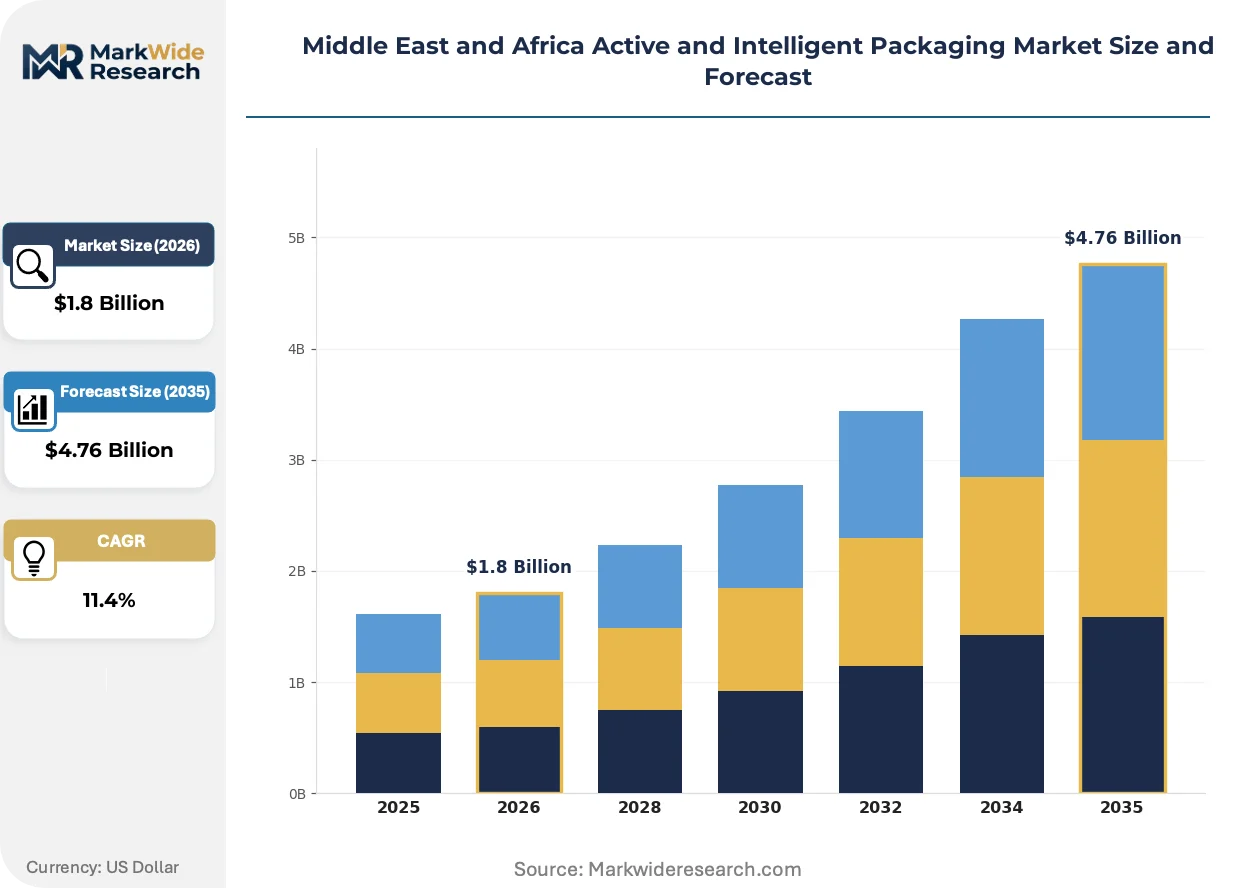
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Intelligent Packaging, Smart Labels, Modified Atmosphere Packaging Material: Plastic, Paper, Glass, Metal Application: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: RFID, NFC, Sensors, E-Film |
| Companies Covered | Amcor Ltd, Honeywell International Inc, Landec Corporation, BASF SE, Crown Holdings Inc, Hotpack Global, Nampak Ltd, Takween Advanced Industries Co, Sappi Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Active and Intelligent Packaging Market Shifts & Advancements
Active and intelligent packaging systems are evolving from passive containment toward interactive product stewardship, with sensor miniaturization and substrate flexibility enabling new form factors across pharmaceutical and food verticals.
Printed electronics on flexible substrates is integrating temperature logging and authentication functions directly into primary packaging films. Pharmaceutical exporters in the UAE are adopting these substrates at pilot scale for high-value biologics. This convergence is integrating sensing capabilities into packaging geometries previously incompatible with rigid electronics.
MOHAP pharmaceutical traceability directives in the UAE are tightening data retention and interoperability standards for serialization systems. Packagers must now demonstrate end-to-end chain-of-custody documentation from manufacturing through last-mile delivery. Cold-chain operators are responding by upgrading to cloud-connected sensor networks with real-time alert protocols.
Buyer procurement patterns for intelligent packaging are consolidating around integrated service contracts bundling hardware, software, and compliance support. Large Gulf retailers are displacing transactional component purchasing with multi-year vendor partnerships. This shift is most visible in Dubai's premium cosmetics sector, where NFC-enabled packaging now carries mandatory consumer engagement functionality.
Middle East and Africa Active and Intelligent Packaging Market Segmentation
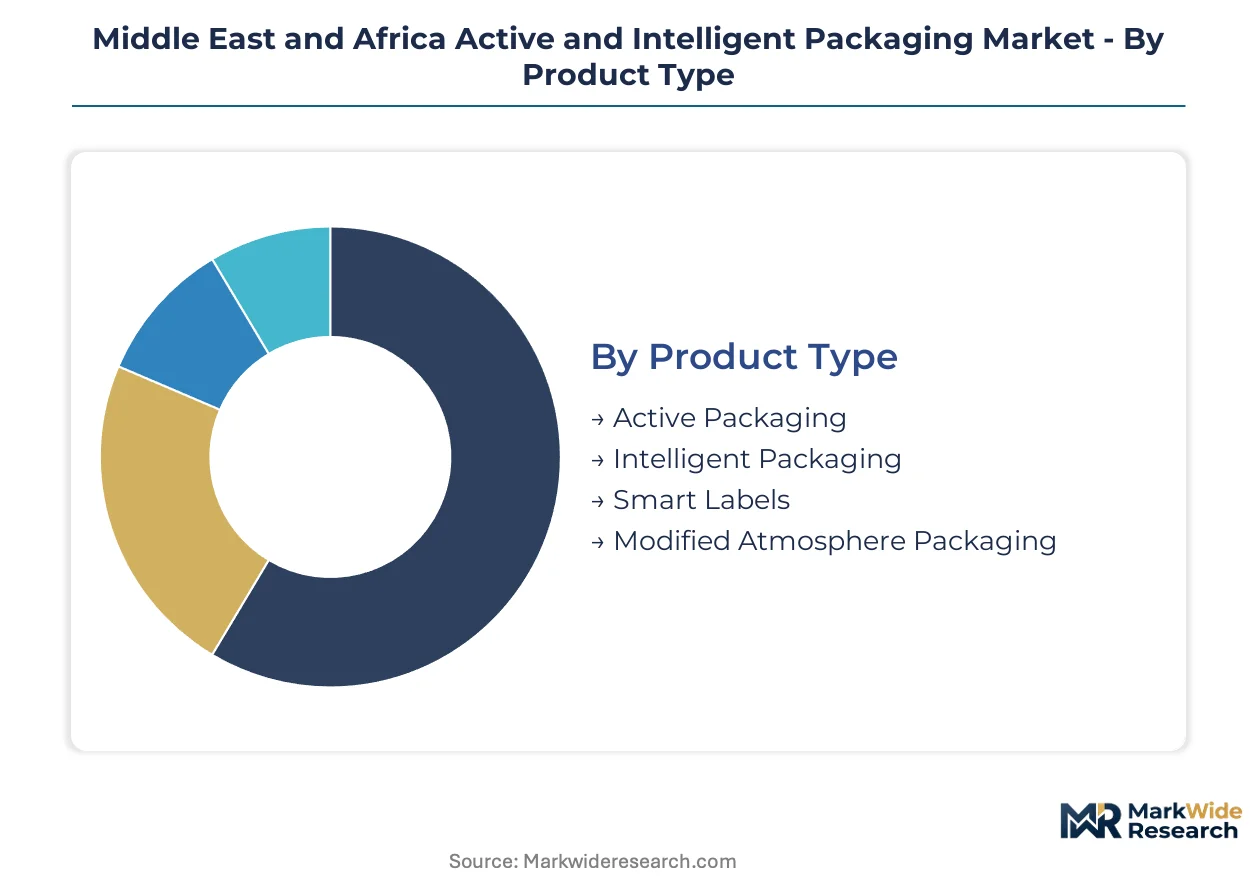
Active and intelligent packaging architectures diverge sharply across the Middle East and Africa corridor based on regulatory maturity, cold-chain infrastructure density, and export channel requirements. Upgrade cycles in pharmaceutical serialization and food export compliance are reshaping procurement specifications across each segment category.
Product Type:
Replacement cycles accelerate where Gulf regulatory mandates force wholesale substrate upgrades rather than incremental retrofits.
- Active Packaging:Oxygen scavengers and moisture regulators embedded in polymer films protect perishable exports from Morocco and Egypt entering European retail channels. Humidity-scavenging formulations from BASF SE dominate Gulf food packaging specifications as REACH-equivalent frameworks raise compliance barriers for alternative chemistries.
- Intelligent Packaging:Sensor-integrated substrates with real-time condition monitoring command premium positioning in Dubai-Jebel Ali pharmaceutical free trade zone operations. Temperature-sensitive biologics transiting multimodal hubs drive integration of time-temperature indicators into secondary packaging tiers.
- Smart Labels:NFC-enabled consumer engagement layers on premium cosmetics and electronics packaging are expanding fastest among Gulf retailers seeking differentiation.
- Modified Atmosphere Packaging:Gas-flush barrier systems dominate fresh produce export applications from North African agricultural zones.
Modified Atmosphere Packaging sits at the top of the volume ranking, with Smart Labels climbing the fastest.
Material:
Cost tiers separate commodity substrates from performance-engineered alternatives where regulatory compliance adds specification premiums.
- Plastic:Multi-layer barrier films with scavenging additives anchor food export packaging across the region, though polymer additive supply concentration in Western Europe creates procurement vulnerability.
- Paper:Fiber-based intelligent substrates with printed electronics integration are gaining traction in UAE pharmaceutical pilot programs for high-value biologics, offering sustainability positioning against plastic alternatives.
- Glass:Pharmaceutical vial and ampoule applications with embedded RFID authentication tags serve Saudi SFDA serialization mandates.
- Metal:Intelligent beverage can formats face technical constraints in integrating flexible electronics at volume scale, limiting penetration beyond Nampak's Southern Africa operations.
Plastic commands the highest installed base, while Paper gains share fastest on sustainability tailwinds.
Application:
Customer type stratification separates institutional pharmaceutical procurement from retail-driven food and cosmetics demand.
- Food & Beverage:Modified atmosphere and active moisture control systems dominate export-oriented operations from Morocco, Egypt, and South Africa into European markets, where shelf-life extension directly determines market access.
- Pharmaceuticals:Cold-chain serialization requirements from Saudi Arabia's SFDA and UAE's MOHAP are mandating RFID and sensor integration across unit, case, and pallet levels, creating the highest technology intensity segment.
- Cosmetics:NFC-enabled authentication and consumer engagement functionality is becoming mandatory for premium positioning in Dubai's retail corridor.
- Electronics:Humidity indicators and tamper-evident intelligent packaging protect high-value device shipments through Gulf logistics hubs.
Food & Beverage holds the largest volume position, with Pharmaceuticals expanding most quickly on regulatory compulsion.
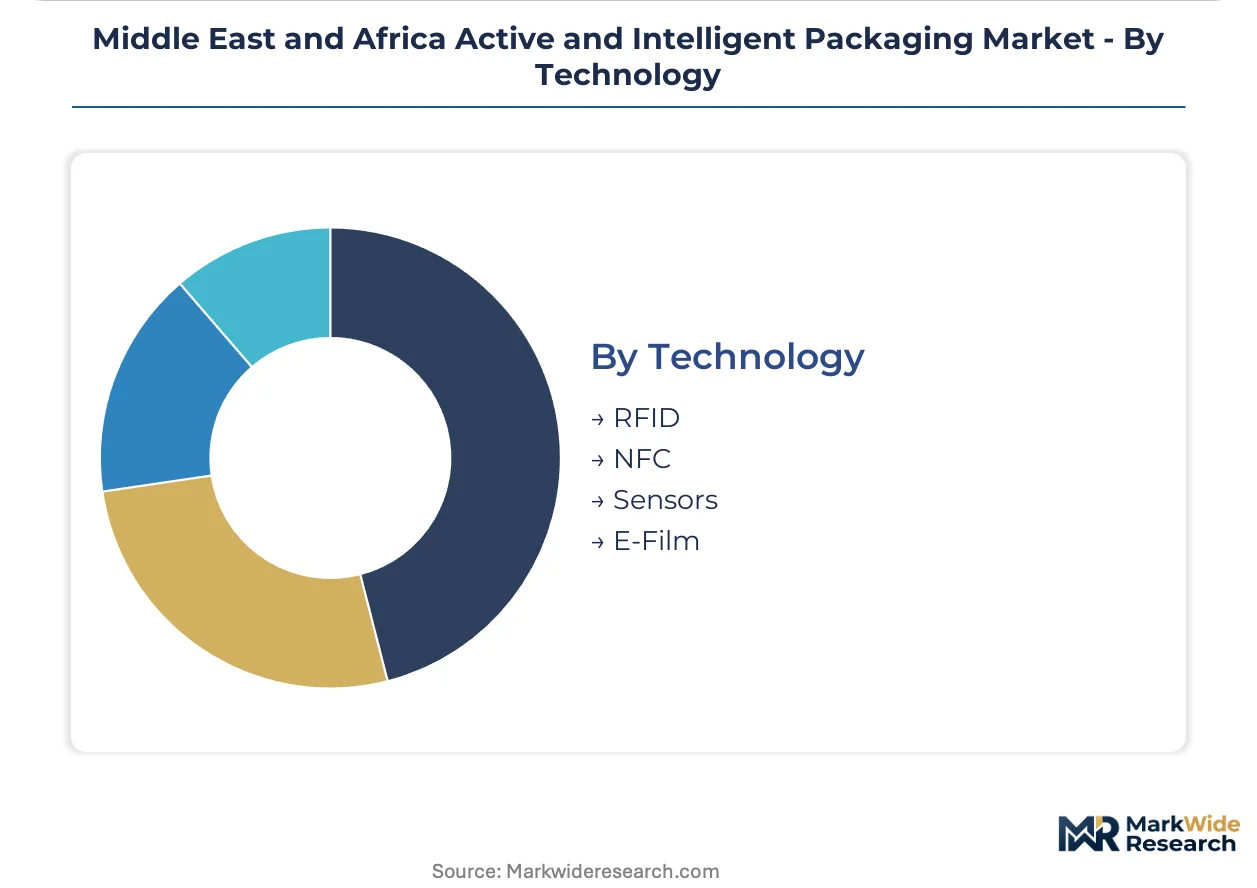
Technology:
Supply concentration in hardware and software integration capabilities favors vendors with established Gulf logistics corridor deployments.
- RFID:Unit-level pharmaceutical authentication systems anchor Saudi SFDA and UAE MOHAP compliance frameworks, with Honeywell's barcode and RFID infrastructure in Dubai providing regional integration leverage.
- NFC:Consumer-facing engagement layers on cosmetics and electronics packaging are displacing static labels in premium retail segments across the UAE and Saudi Arabia.
- Sensors:Miniaturized temperature and humidity logging devices are integrating into printed electronics on flexible substrates for biologics distribution.
- E-Film:Printed electronic films with embedded authentication and condition monitoring functions are piloting in UAE pharmaceutical exports.
RFID maintains volume leadership, with Sensors gaining traction fastest on cold-chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent clusters in Dubai's logistics corridor and Riyadh's pharmaceutical manufacturing zones anchor regional packaging innovation capacity.
United Arab Emirates
Dubai-Jebel Ali pharmaceutical free trade zone concentrates demand for time-temperature indicators as temperature-sensitive biologics transit through multimodal hubs. MOHAP pharmaceutical traceability directives tighten data retention standards for serialization systems. Cold-chain operators in the emirate upgrade to cloud-connected sensor networks with real-time alert protocols.
Saudi Arabia
SFDA serialization requirements force packagers to deploy RFID-enabled labels for unit-level authentication across pharmaceutical distribution. The national regulator mandates end-to-end chain-of-custody documentation from manufacturing through last-mile delivery. Riyadh anchors domestic pharmaceutical packaging upgrade cycles as compliance deadlines approach.
South Africa
Extended producer responsibility regulations reshape material compliance obligations across the value chain for metal and plastic packaging substrates. The country's national environmental regulator finalizes implementation timelines for post-consumer collection mandates. Johannesburg-Pretoria industrial corridor houses Nampak's intelligent beverage can operations facing technical constraints in flexible electronics integration.
Egypt
Modified atmosphere packaging dominates food export applications from North African agricultural zones into European retail channels. Emerging consumer protection labeling rules create specification requirements for imported intelligent packaging systems. Cairo-Alexandria logistics corridor channels perishable exports through humidity-scavenging film applications.
Morocco
Active moisture control systems protect perishable exports entering European markets where shelf-life extension determines market access. The country's national food safety regulator aligns domestic standards with EU import requirements. Casablanca-Rabat industrial zone concentrates agri-export packaging operations serving premium European retail channels.
Middle East and Africa Active and Intelligent Packaging Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with polymer additive portfolios and specialized sensor integrators with Gulf logistics corridor deployments. Market participation splits between formulation leaders sustaining humidity-scavenging film specifications and hardware-software bundlers capturing multi-year retail service contracts. Two strategic archetypes dominate: substrate specialists with REACH-equivalent compliance capabilities and integrated solution providers with regional RFID infrastructure. Competitive moves concentrate on strategic partnerships for regulatory navigation and portfolio diversification into printed electronics substrates.
Among diversified chemical conglomerates, BASF SE and Honeywell International Inc exemplify contrasting archetype positioning. BASF SE anchors formulation leadership through polymer additive portfolios serving humidity-scavenging applications across Gulf food packaging specifications. Honeywell International Inc occupies the integrated systems tier, leveraging barcode and RFID infrastructure deployed in Dubai's logistics corridors to capture pharmaceutical serialization mandates. Crown Holdings Inc represents the metal packaging specialist archetype competing in intelligent can formats, while Nampak Ltd sits within the regional fabricator tier focused on Southern Africa beverage applications.
| Leading Market Players |
|---|
| Amcor Ltd |
| Honeywell International Inc |
| Landec Corporation |
| BASF SE |
| Crown Holdings Inc |
| Hotpack Global |
| Nampak Ltd |
| Takween Advanced Industries Co |
| Sappi Ltd |
| Others |
Supply & Pricing Matrix
Printed electronics miniaturization is compressing unit economics for sensor-integrated substrates while simultaneously concentrating procurement leverage among Gulf-based cold-chain operators with volume scale. This production-method transition rewards packagers bundling hardware, software, and compliance support under multi-year contracts rather than transactional component sourcing.
Pricing Analysis
Service bundling versus component-only procurement now defines the pricing architecture across Dubai-Jebel Ali pharmaceutical corridors. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected sensor networks with real-time alerts from basic time-temperature indicators and passive RFID tags. Price differentiation hinges on certification grade for SFDA and MOHAP compliance plus after-sales technical support intensity. Cost compression in standard-tier humidity-scavenging films is intensifying because REACH-equivalent regulatory barriers limit qualified supplier pools. Food export packagers in Morocco and Egypt exhibit highest price sensitivity due to thin agricultural margins, while pharmaceutical cold-chain operators in the UAE show lowest sensitivity given biologics value-at-risk.
Supply Chain Analysis
Freight cost volatility on Europe-Gulf routes is amplifying working capital requirements for humidity-scavenging film substrates manufactured in Germany and the Netherlands. Active packaging formulation leadership draws from polymer additive concentration in Western Europe, with sensor hardware sourcing anchored in China and South Korea, and regional fabrication clustering in South Africa for Nampak's metal can operations. Single-source vulnerability in specialized scavenger chemistries creates supply chain risk given limited qualified alternatives under emerging Gulf chemical safety frameworks. Distribution runs through Dubai-Jebel Ali multimodal hubs for pharmaceutical serialization systems, while food export packaging channels through Casablanca-Rabat and Cairo-Alexandria corridors into European retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Active and Intelligent Packaging Market functions as a stable compounder, with pharmaceutical regulatory compulsion across Saudi Arabia and the UAE generating predictable upgrade cycles regardless of macroeconomic fluctuation.
For Market Incumbents: Deploy cloud-connected sensor network platforms to capture multi-year integrated service contracts displacing transactional component purchasing. BASF SE and Honeywell International Inc should deepen backward integration into printed electronics substrates to defend formulation leadership against emerging flexible sensor specialists. Channel control through Dubai-Jebel Ali logistics corridor dominance remains critical as MOHAP tightens data retention standards. For New Entrants and Emerging Players: The premium-to-economy tier gap in NFC-enabled consumer engagement layers offers entry opportunity for mid-market cosmetics packagers lacking Gulf retailer relationships. Egypt's emerging consumer protection labeling rules present the most penetrable regulatory entry point, with Cairo-Alexandria logistics corridor serving as launch geography. A compliance-first go-to-market angle targeting stranded inventory risk from divergent national implementation calendars differentiates against established hardware vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with metal can format capabilities but lacking flexible electronics integration expertise. Long-term viability over the projection horizon favors substrate specialists with REACH-equivalent compliance capabilities and established Gulf logistics corridor deployments. The signal to watch is Saudi SFDA enforcement action against non-compliant serialization systems, which would accelerate consolidation toward integrated solution providers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Certification | SFDA and MOHAP serialization mandates force packagers to deploy authenticated RFID infrastructure. |
| Printed Electronics Integration | Flexible substrate miniaturization enables sensor embedding in primary packaging films for biologics. |
| Multi-Year Service Contracting | Gulf retailers displace transactional purchasing with bundled hardware-software-compliance partnerships. |
| Backward Integration into Additives | Humidity-scavenging formulation leadership rests on captive polymer chemistry capabilities. |
| Geographic Expansion into Egypt | Emerging consumer protection labeling rules create first-mover advantage for compliant intelligent packaging suppliers. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement managers, cold-chain logistics operators, and regulatory affairs directors, alongside secondary validation through customs trade data, SEC filings of listed packaging conglomerates, and Gulf standards body documentation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured operational constraints in Dubai-Jebel Ali pharmaceutical free trade zone operations and Cairo-Alexandria food export corridors. Secondary sources included SFDA and MOHAP regulatory filings, ECHA REACH-equivalent framework drafts, and industry association reports from Gulf packaging federations.
Data-stream reconciliation across product type, material substrate, application vertical, and technology platform enabled granular volume and value estimation throughout the forecast period. Segmentation dimensions modeled encompassed active versus intelligent packaging architectures, plastic-paper-glass-metal material tiers, food-pharmaceutical-cosmetics-electronics end-use applications, and RFID-NFC-sensor-e-film technology categories. CAGRs were derived from installed base replacement cycles, regulatory deadline calendars, and cold-chain infrastructure expansion trajectories specific to GCC pharmaceutical distribution and North African food export channels.
Caveats apply where delays in harmonized Gulf standards implementation or abrupt shifts in EU import requirements for Moroccan and Egyptian agricultural exports could materially shift the outlook. Forecasts reflect assumptions regarding sensor cost curves, polymer additive supply availability, and regional technical talent development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
ASEAN and Gulf Countries MAP and VSP Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
United Arab Emirates Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
High-End Performance Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market