
 Global Acrylic Foam Tapes Market | 2026-2036
Global Acrylic Foam Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Foam Tapes Market Intelligence
Acrylic foam is expanding its share against mechanical fasteners in automotive body-in-white and exterior trim applications, driven by weight-reduction mandates and corrosion-resistance requirements. 3M leverages its multi-layer foam core patents to sustain premium positioning in North American OEM supply chains. Henkel anchors European demand through solvent-free formulations that meet industrial emissions protocols. Nitto Denko dominates Asia-Pacific electronics bonding with ultra-thin transfer tape geometries.
Acrylic foam tapes consist of viscoelastic polyacrylate adhesive layers laminated to closed-cell foam substrates, typically ranging from 0.25 mm to 3.0 mm thickness, engineered to absorb dynamic stress while maintaining peel adhesion above 15 N/cm on painted metals and engineering plastics. Their primary purpose is semi-structural bonding of dissimilar materials where thermal expansion mismatch, vibration damping, or sealed joints are required. Double-sided configurations command the largest volume share in automotive and construction applications where permanent lamination replaces rivets and welds. UV-cured technology segments are gaining fastest in electronics assembly, as manufacturers seek instant handling strength without solvent flash-off delays. Water-based formulations retain cost-sensitive share in furniture manufacturing and signage mounting, though performance gaps persist in extreme-temperature marine bonding.
FDA indirect food-contact regulations, EPA National Emission Standards for Hazardous Air Pollutants, and REACH Annex XVII restrictions on solvent content collectively shape formulation chemistry and manufacturing site location decisions for tape producers. CE marking under the Construction Products Regulation governs structural bonding claims in European building applications, creating compliance barriers for non-certified imports. OEMs and adhesive suppliers must monitor evolving automotive OEM material specifications and building code adoptions of structural glazing standards to anticipate specification shifts before contract renewals.
Market Dynamics
Automotive lightweighting mandates are compressing specification cycles for bonding materials, forcing tape producers to validate formulations against OEM crash-test protocols before contract awards rather than after.
Growth Catalysts
- EU REACH Annex XVII solvent restrictions:Manufacturers reformulating toward water-based and UV-cured chemistries capture specification share in German and French automotive assembly plants.
- China's NEV corridor concentration:Battery pack bonding demand in Shenzhen and Shanghai manufacturing zones pulls high-shear acrylic formulations for thermal management module assembly.
- Closed-cell foam core engineering:Multi-density substrate lamination improves peel strength on powder-coated aluminum, enabling rivet replacement in commercial vehicle sidewall construction.
Market Restraints
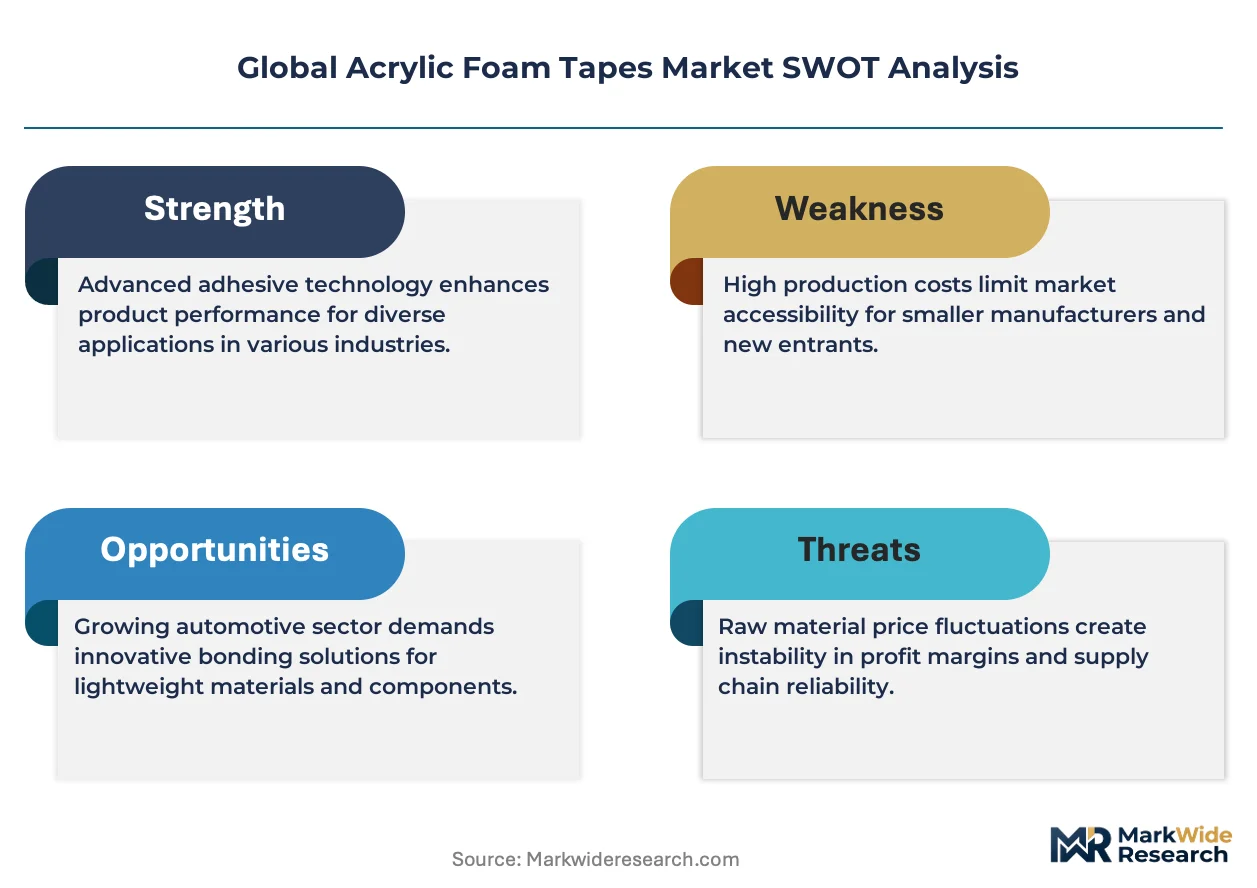
- Petrochemical feedstock volatility:Acrylate monomer and polyol costs tied to propylene derivatives create margin compression for non-integrated tape converters.
- Regional supply concentration:Asia-Pacific foam substrate capacity clusters in South Korea and Japan, exposing European and North American converters to freight cost spikes and currency fluctuation.
- Structural glazing certification lag:CE marking under Construction Products Regulation requires 18-24 month testing cycles, freezing non-certified imports out of European building retrofit tenders.
Strategic Opportunities
- Mexico automotive export zones:Queretaro and Aguascalientes component plants seek localized tape slitting and die-cutting to meet USMCA content rules and reduce cross-border inventory.
- Wind turbine blade bonding:Leading-edge erosion shields and vortex generator attachment present unmet demand for UV-stable, cyclical-load-resistant outdoor tapes.
- US Inflation Reduction Act domestic content:Clean vehicle tax credit assembly location requirements incentivize tape producers to qualify Mexican and US-based coating lines for EV supply chains.
Industry Challenges
- Formulation chemist scarcity:Expertise in viscoelastic polymer rheology and foam-cell nucleation concentrates at a handful of technical institutes, constraining R&D scaling for mid-tier producers.
- OEM specification lock-in:Automotive platform approvals require 3-5 year validation cycles, creating switching costs that entrench incumbent suppliers even when technical performance gaps emerge.
- Cross-border customs classification:Harmonized System code disputes between pressure-sensitive adhesive rolls and finished tape articles trigger duty rate uncertainty for distributors serving multiple manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Foam Tapes Market |
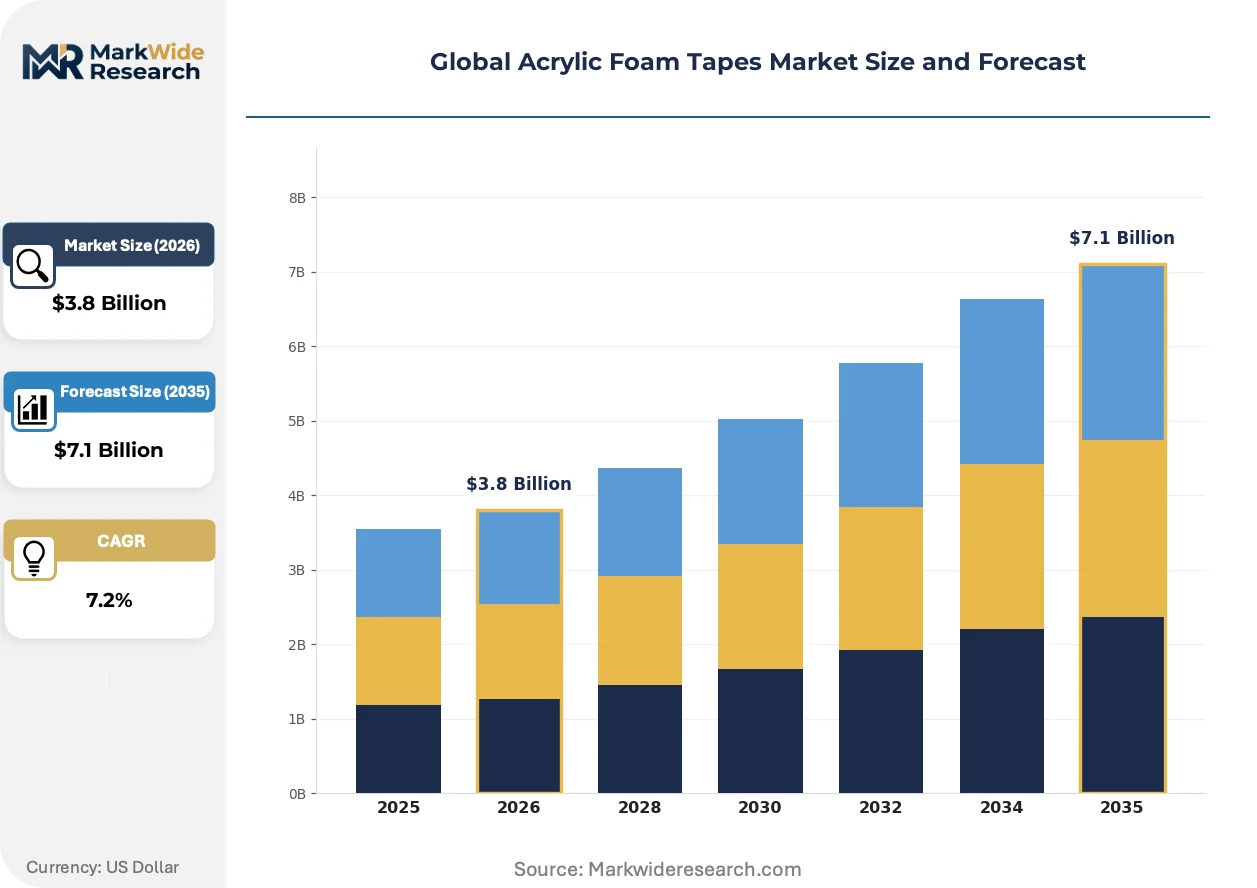
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.1 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Single-Sided, Transfer Tapes, High-Performance, Specialty, Custom Technology: Water-Based, Solvent-Based, Hot Melt, Radiation-Cured, UV-Cured, Foam Core Application: Construction, Electronics Assembly, Automotive Components, Signage Mounting, Marine Bonding, Furniture Manufacturing End User: OEMs, Aftermarket Suppliers, Electronic Device Manufacturers, Shipbuilders, Cabinet Makers, Packaging Companies |
| Companies Covered | 3M, Henkel, Avery Dennison, Tesa SE, Nitto Denko, Saint-Gobain, Intertape Polymer Group, Sika AG, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Foam Tapes Market Strategic Shifts & Innovations
Formulation chemistry and application engineering are converging to address thermal cycling demands in electrified transportation and renewable energy hardware, compressing development timelines and collapsing traditional supplier-buyer boundaries.
Multi-layer foam core architectures with graded density profiles are unifying vibration damping and structural load transfer in single tape constructions. Tier 1 automotive suppliers in Germany and Japan specify these for battery tray-to-chassis bonding. The technology is unifying what previously required separate gasket and adhesive steps, reducing assembly line footprint and work-in-process inventory.
REACH authorization requirements for diisocyanates and residual solvent content are forcing tape producers to relocate coating operations to sites with integrated solvent recovery or shift entirely to hot-melt and UV-curable platforms. German chemical parks with shared waste treatment infrastructure now attract disproportionate investment from adhesive formulators seeking regulatory cost containment.
Just-in-sequence delivery contracts are displacing traditional distributor stocking models in automotive supply chains. Tape converters near OEM assembly plants in Stuttgart, Detroit, and Toyota City hold consignment inventory and perform last-minute die-cutting to match hourly production schedules. This pattern is most pronounced in electric vehicle programs where platform variants proliferate and bond-line specifications change between model years.
Global Acrylic Foam Tapes Market Segmentation
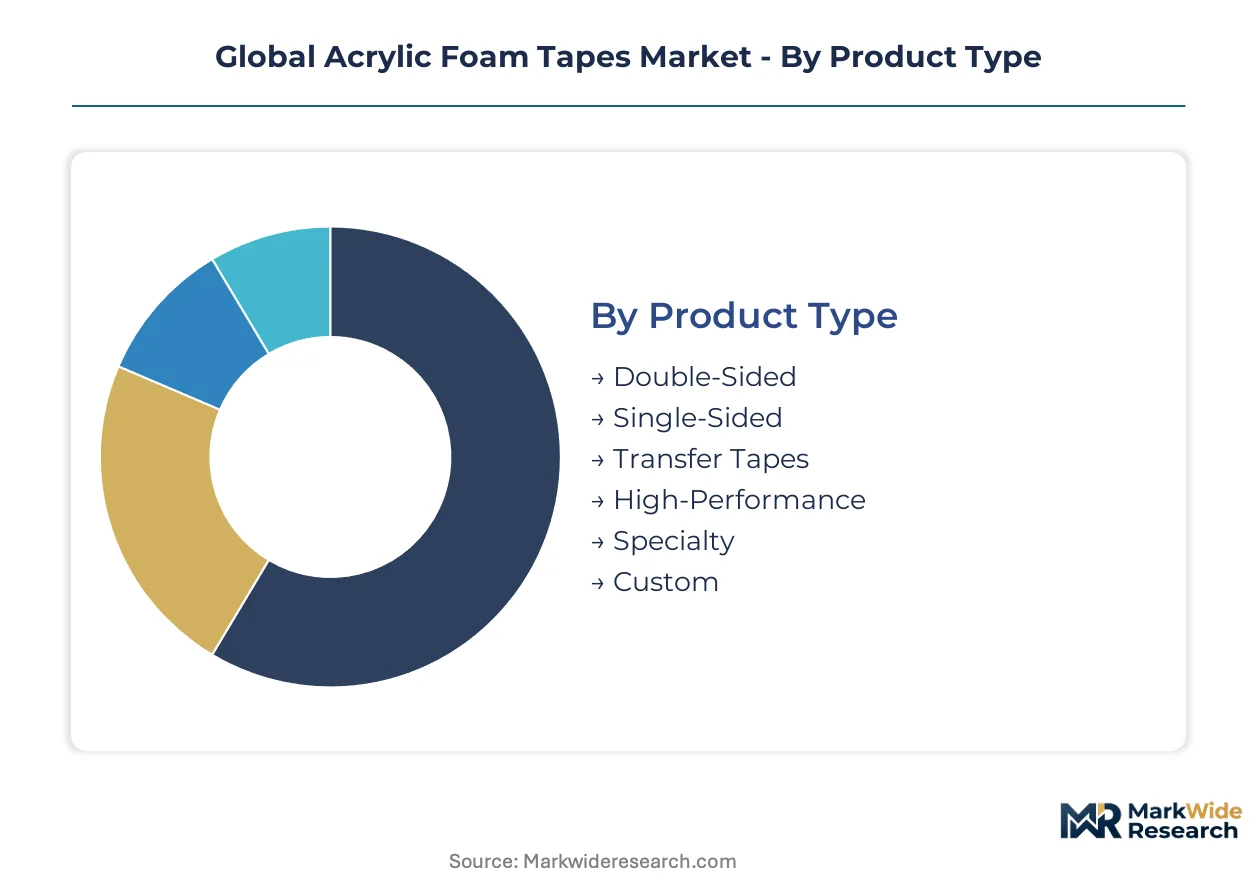
Segmentation in acrylic foam tapes reveals how certification requirements, application stresses, and supply chain proximity dictate formulation choices and manufacturing location decisions across automotive, electronics, and construction verticals.
Product Type:
CE marking under the Construction Products Regulation governs structural bonding claims for European building applications, while automotive OEM crash-test protocols dominate specification requirements for vehicle assembly tapes.
- Double-Sided:Viscoelastic adhesive layers on both faces of closed-cell foam substrates, typically 0.5 mm to 2.0 mm thickness, enable permanent lamination of dissimilar materials. German and Japanese automotive OEMs specify these for body-in-white assemblies where thermal expansion mismatch between aluminum and steel demands stress-absorbing bonds.
- Transfer Tapes:Adhesive films without foam carriers, ranging down to 0.05 mm thickness, deliver ultra-thin bonding profiles for electronics miniaturization. Shenzhen and Shanghai battery pack manufacturers pull high-shear formulations for thermal management module attachment where space constraints exclude foam-core alternatives.
- Single-Sided:Foam substrate with single adhesive face serves gasketing and sealing functions in HVAC ductwork and appliance manufacturing.
- High-Performance:Graded-density foam cores engineered for cyclical load resistance in wind turbine leading-edge applications.
- Specialty:Formulations meeting FDA indirect food-contact regulations for appliance interior bonding.
- Custom:Die-cut geometries produced under just-in-sequence contracts for automotive platform variants.
Leading the category by volume: Double-Sided. Growing fastest: Transfer Tapes.
Technology:
Cost stratification separates commodity converters from integrated formulators, with solvent recovery infrastructure and UV curing capacity determining margin capture.
- Water-Based:Acrylic emulsions with zero volatile organic compound emissions meet EPA National Emission Standards for Hazardous Air Pollutants. Furniture manufacturers in cost-sensitive markets specify these for indoor air quality compliance, though performance gaps persist in extreme-temperature marine environments.
- UV-Cured:Photoinitiator-triggered polymerization delivers instant handling strength without solvent flash-off delays. Electronics assemblers in South Korea and Japan favor these for high-throughput surface-mount device bonding where work-in-process inventory reduction drives capital efficiency.
- Solvent-Based:Traditional formulations retain share where open time and wet-out on porous substrates remain critical.
- Hot Melt:Thermoplastic adhesives applied molten, suited to high-speed converting operations with limited heat exposure requirements.
- Radiation-Cured:Electron-beam processing enables thick-film curing without photoinitiator constraints.
- Foam Core:Multi-density substrate lamination technology unifying vibration damping and structural load transfer.
Water-Based commands the largest production volume. UV-Cured climbs the fastest as electronics cycle times compress.
Application:
Geographic clustering of end-use demand pulls coating capacity toward manufacturing corridors in China, Mexico, and Germany.
- Automotive Components:Battery tray-to-chassis bonding and exterior trim attachment dominate specification volumes. Queretaro and Aguascalientes component plants seek localized slitting operations to meet USMCA content rules.
- Electronics Assembly:Thermal management module bonding and display lamination concentrate in Shenzhen and Shanghai manufacturing zones.
- Construction:Structural glazing and facade bonding require CE marking compliance.
- Signage Mounting:Exterior durability requirements drive UV-stable formulation selection.
- Marine Bonding:Salt spray and cyclical humidity resistance specifications favor solvent-based systems.
- Furniture Manufacturing:Indoor air quality regulations push water-based adoption.
Automotive Components generates the highest revenue concentration. Electronics Assembly shows the steepest expansion trajectory.
End User:
Procurement authority separates specification gatekeepers from price-taking distributors, with OEM direct contracts commanding formulation development resources.
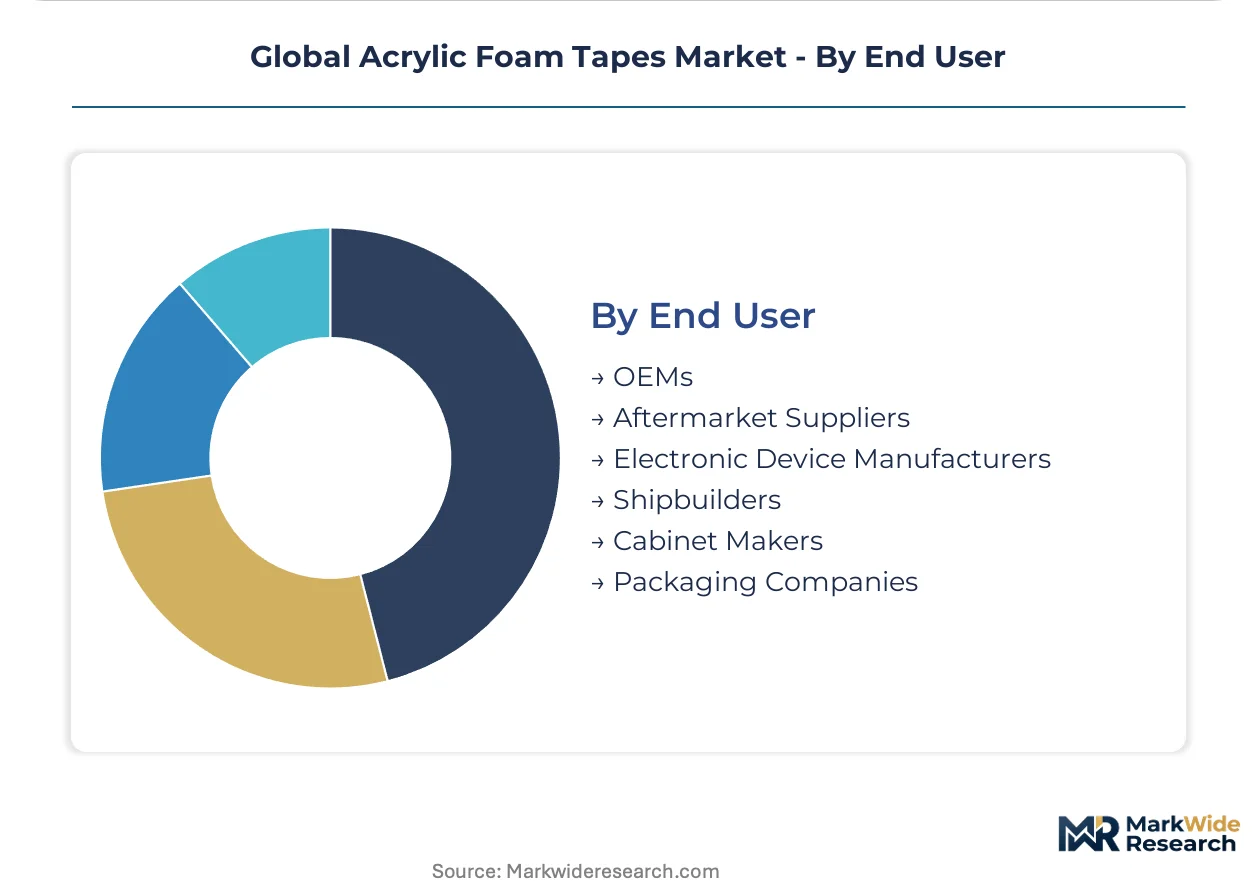
- OEMs:Automotive and appliance manufacturers hold 3-5 year validation cycles that entrench incumbent suppliers. Stuttgart, Detroit, and Toyota City assembly plants specify tapes through platform-level approvals rather than commodity procurement.
- Electronic Device Manufacturers:Contract assemblers and original design manufacturers in Asia-Pacific specify ultra-thin transfer tapes through quarterly supplier reviews.
- Aftermarket Suppliers:Distributors serving collision repair and maintenance channels.
- Shipbuilders:Korean and Japanese yards specify marine-grade formulations.
- Cabinet Makers:Regional furniture clusters driving water-based volume.
- Packaging Companies:High-speed converting operations favoring hot-melt systems.
OEMs anchor the category by contract value. Electronic Device Manufacturers expand most quickly as NEV production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for acrylic foam tapes clusters in automotive manufacturing corridors where electric vehicle assembly and lightweighting mandates concentrate purchasing authority. Battery pack bonding specifications in Shenzhen and Stuttgart drive formulation requirements. Queretaro component plants reshape North American supply chain geography.
China
Shenzhen and Shanghai manufacturing zones pull high-shear acrylic formulations for thermal management module assembly in NEV production. The Ministry of Ecology and Environment enforces dual carbon goals that push tape producers toward water-based and UV-cured chemistries. BYD and CATL supplier parks in Guangdong province specify closed-cell foam substrates for battery tray bonding at scale.
Germany
Stuttgart and Munich OEM assembly plants validate tapes against crash-test protocols before platform awards. ECHA REACH Annex XVII restrictions on residual solvent content force coating operations toward German chemical parks with shared waste treatment infrastructure. Bavarian automotive suppliers specify multi-density foam cores for aluminum-to-steel body-in-white bonding.
United States
Detroit-area OEMs and Tesla's Austin operations drive specification volumes for exterior trim and battery enclosure bonding. EPA National Emission Standards for Hazardous Air Pollutants tighten volatile organic compound thresholds for adhesive formulations. Michigan and Ohio-based Tier 1 suppliers hold consignment inventory for just-in-sequence delivery contracts.
Japan
Toyota City and Nagoya manufacturing clusters anchor demand for ultra-thin transfer tapes in electronics miniaturization. METI industrial emissions protocols favor solvent-free formulations in automotive assembly. Nitto Denko's supplier network in Osaka-Kobe corridor dominates Asia-Pacific electronics bonding specifications.
Mexico
Queretaro and Aguascalientes automotive component plants seek localized tape slitting to meet USMCA content rules for clean vehicle tax credits. PROFEPA environmental enforcement aligns with EPA cross-border standards for coating operations. Northern border states attract die-cutting investments to reduce cross-border inventory exposure.
Global Acrylic Foam Tapes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with formulation-integrated players commanding premium positioning in automotive OEM supply chains. The vendor base concentrates around multi-layer foam core patents and solvent-free platforms that satisfy REACH and EPA protocols. Three archetypes dominate: integrated chemical formulators with captive monomer supply, regional converters with die-cutting and slitting capabilities, and electronics-focused specialists in ultra-thin transfer geometries. Competitive moves center on coating capacity relocation to chemical parks with shared waste treatment and just-in-sequence inventory contracts near OEM assembly plants.
Among integrated formulators, 3M and Henkel occupy positions that exemplify premium-tier positioning through multi-layer foam core patents and solvent-free platforms respectively. Nitto Denko anchors the electronics-specialist archetype with ultra-thin transfer tape capabilities. These three represent the structural segmentation between automotive structural bonding, industrial emissions-compliant formulations, and miniaturized electronics attachment.
| Leading Market Players |
|---|
| 3M |
| Henkel |
| Avery Dennison |
| Tesa SE |
| Nitto Denko |
| Saint-Gobain |
| Intertape Polymer Group |
| Sika AG |
| Berry Global |
| Others |
Cost & Logistics Intelligence
Acrylate monomer and polyol costs tied to propylene derivatives cascade through three distinct pricing tiers, with integrated formulators capturing margin buffers that non-integrated converters in Europe and North America cannot match against Asian supply clusters.
Pricing Analysis
Volume concentrates in water-based commodity grades serving furniture and signage channels, while margin pools in UV-cured and solvent-free formulations certified for automotive OEM supply chains. Price differentiation hinges on REACH Annex XVII compliance tier and crash-test validation status, with German OEM specifications commanding substantial premiums over aftermarket alternatives. Cost compression in standard double-sided foam tapes is intensifying as South Korean substrate producers expand coating capacity. Aftermarket distributors exhibit highest price sensitivity, whereas Stuttgart and Detroit OEM procurement teams prioritize specification adherence over unit cost.
Supply Chain Analysis
Reverse-logistics flows remain minimal given the permanent-bonding nature of acrylic foam applications, though automotive assembly plants in Queretaro and Aguascalientes are experimenting with consignment inventory returns for die-cut scrap. Supply concentrates in South Korea, Japan, and Germany for foam substrate engineering, with China dominating acrylate monomer production. Raw material dependencies center on propylene derivatives, photoinitiator chemicals, and closed-cell polyethylene foam. Single-source vulnerability persists in ultra-thin transfer tape geometries where Nitto Denko's Osaka-Kobe corridor anchors Asia-Pacific electronics specifications. Distribution runs through Tier 1 automotive suppliers holding just-in-sequence contracts rather than traditional distributor stocking models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH Annex XVII solvent restrictions function as a compliance moat, elevating capital requirements for coating operations and freezing out non-certified imports from European building retrofit tenders.
For Market Incumbents: Lock in platform-level approvals with Stuttgart and Detroit OEMs before specification cycles refresh, as 3-5 year validation windows entrench suppliers against emerging foam-core competitors. Prioritize coating capacity relocation to German chemical parks with shared waste treatment infrastructure to contain regulatory cost escalation. Defend margin pools by deepening captive supply of acrylate monomers or securing long-term offtake agreements with propylene derivative producers. For New Entrants and Emerging Players: US Inflation Reduction Act domestic content requirements open a window for Mexican coating operations serving Queretaro and Aguascalientes component plants seeking USMCA qualification. Wind turbine blade bonding presents the most penetrable white-space target, with leading-edge erosion shield specifications still unmet by incumbent tape portfolios. Pursue qualification partnerships with blade OEMs rather than direct automotive platform approval routes. For Investors and Strategic Acquirers: Just-in-sequence contract announcements from Detroit-area Tier 1 suppliers are the leading indicator that regional supply chain reconfiguration is accelerating. Over the medium-term horizon, vertically integrated formulators with captive monomer supply and solvent-free platforms represent the highest-viability acquisition archetype. Monitor EPA National Emission Standards enforcement actions as a signal for margin compression timing among non-compliant converters.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Capacity Relocation to Chemical Parks | Shared waste treatment infrastructure at German chemical parks reduces REACH compliance cost burden for solvent-based formulations. |
| Just-in-Sequence Inventory Contracts | Consignment arrangements near Stuttgart and Detroit assembly plants displace distributor stocking models in automotive supply chains. |
| Multi-Density Foam Core Patent Expansion | Graded-density substrate lamination unifies vibration damping and structural load transfer for battery tray-to-chassis bonding specifications. |
| UV-Cured Platform Scale-Up | Photoinitiator-triggered polymerization captures electronics assembly share where instant handling strength reduces work-in-process inventory. |
| Backward Integration into Acrylate Monomers | Captive propylene derivative supply insulates margin compression from petrochemical feedstock volatility affecting non-integrated converters. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews validating formulation trends and procurement patterns across the analysis window. Plant managers at coating operations, procurement leads at German and Japanese automotive OEMs, distribution channel partners serving aftermarket collision repair, and technical R&D directors at adhesive formulators provided operational context. ECHA REACH registration databases, EPA National Emission Standards compliance filings, USMCA rules-of-origin documentation, and vehicle production databases from IHS Markit supplied quantitative foundations. Bottom-up segment sizing triangulated against top-down demand aggregation from end-use industry consumption patterns.
Granularity-level modeling distinguished product type, technology platform, application vertical, and end-user procurement authority across the projection horizon. Segment-level CAGRs derived from elasticity-adjusted demand curves incorporating OEM platform lifecycle timing and regulatory phase-in schedules. Automotive content-per-vehicle trajectories for electric vehicle bonding applications and electronics miniaturization trends in Shenzhen and Shanghai manufacturing zones informed volume build-ups.
The model assumes a particular technology adoption path; alternative pathways for hot-melt and radiation-cured platforms would alter the outlook if electronics assemblers accelerate away from UV-cured systems. Forecasts reflect assumptions about REACH Annex XVII enforcement intensity, USMCA content rule interpretation, and propylene derivative pricing stability. Material deviation in OEM crash-test protocol adoption timelines or EPA National Emission Standards revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Paper Masking Tapes Market
Tapes
Tape Dispenser Market
Tapes
Foil Tapes Market
Tapes
Tape Unwinder Market
Tapes
Shipping Tapes Market
Tapes
Packaging Tape Printing Market
Tapes
Carton Sealing Tape Market
Tapes
Heat Activated Tear Tape Market
Tapes
Seam Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Edge Band Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Freezer Tape Market
Tapes
Mastic Tapes Market
Tapes
Painting Masking Tapes Market