
 Fine Line Striping Tape Market | 2026-2036
Fine Line Striping Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Line Striping Tape Market Foresight
Buyer concentration among municipal road maintenance departments is pivoting toward consolidated state-level procurement contracts. 3M leverages its retroreflective technology portfolio to sustain premium positioning in highway striping applications. Tesa SE anchors European supply through specialized adhesive formulations for cold-climate road marking. Avery Dennison Corporation competes on film durability in sports facility line marking across North American school districts.
Fine line striping tape comprises precision-calibrated polymeric films, typically vinyl or polyester substrates coated with pressure-sensitive adhesives, engineered to produce lane boundaries and hazard markings with edge tolerances below three millimeters. The material withstands abrasion from vehicle tires, UV degradation, and thermal cycling while maintaining chromatic contrast against asphalt or concrete surfaces. Vinyl formulations dominate current volume due to cost efficiency in temporary roadwork zones, whereas polyester substrates command higher margins in permanent highway installations where elongation resistance proves critical. Automated application technology is displacing manual methods in large-scale municipal contracts, though cold application systems retain share among contractor fleets serving parking lot and sports facility segments.
Federal Highway Administration (FHWA) Manual on Uniform Traffic Control Devices governs retroreflectivity minimums for pavement markings, compelling tape manufacturers to validate performance through third-party testing. ASTM D4956 classifies sheeting grades, creating tiered product qualification barriers that filter supplier participation in state Department of Transportation bids. Environmental Protection Agency (EPA) VOC restrictions on solvent-based adhesives are redirecting formulation investment toward waterborne and hot-melt chemistries. Stakeholders must monitor evolving state-level Buy America preferences and infrastructure spending prioritization to align capacity with procurement cycles.
Market Dynamics
Automated application systems are compressing contractor margins while elevating performance thresholds for tape adhesion and dimensional stability across state highway procurement cycles.
Growth Catalysts
- FHWA retroreflectivity mandates:Federal minimums for pavement marking visibility compel state DOTs to replace degraded lane markings on accelerated schedules, sustaining replacement demand for high-grade sheeting.
- Sun Belt infrastructure renewal:California, Texas, and Florida DOTs are consolidating multi-year striping contracts, concentrating procurement volume among qualified tape suppliers with proven ASTM D4956 certification.
- Waterborne adhesive chemistry:EPA VOC restrictions on solvent-based formulations are redirecting R&D investment toward compliant hot-melt and emulsion systems that maintain peel strength in thermal cycling.
Market Restraints
- Petroleum-derived substrate costs:Vinyl and polyester resin prices track crude oil volatility, squeezing converter margins when asphalt paving seasons compress ordering windows.
- Concentrated retroreflective bead supply:Domestic sourcing of high-index glass microspheres depends on a limited supplier base in the Ohio River Valley, creating single-source exposure for premium sheeting grades.
- Cold-climate performance trade-offs:Pressure-sensitive adhesives formulated for low-temperature application sacrifice tack at summer peak temperatures, fragmenting product lines by regional climate zone.
Strategic Opportunities
- Buy America compliance specialization:State-level domestic content preferences create qualification barriers that favor converters with vertically integrated film extrusion and adhesive coating capacity.
- Electric vehicle charging zone marking:Municipalities are specifying high-visibility striping for EV parking infrastructure, opening incremental volume outside traditional highway applications.
- Preformed thermoplastic convergence:Tape manufacturers integrating extruded thermoplastic capability can bid bundled contracts covering both temporary and permanent marking phases.
Industry Challenges
- ASTM D4956 certification timelines:Third-party sheeting grade validation requires 18-24 month testing cycles, delaying new product commercialization relative to procurement award schedules.
- Applicator workforce specialization:Automated striping equipment operation demands combined mechanical and software competencies that contractor training programs have not scaled to match fleet expansion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Line Striping Tape Market |
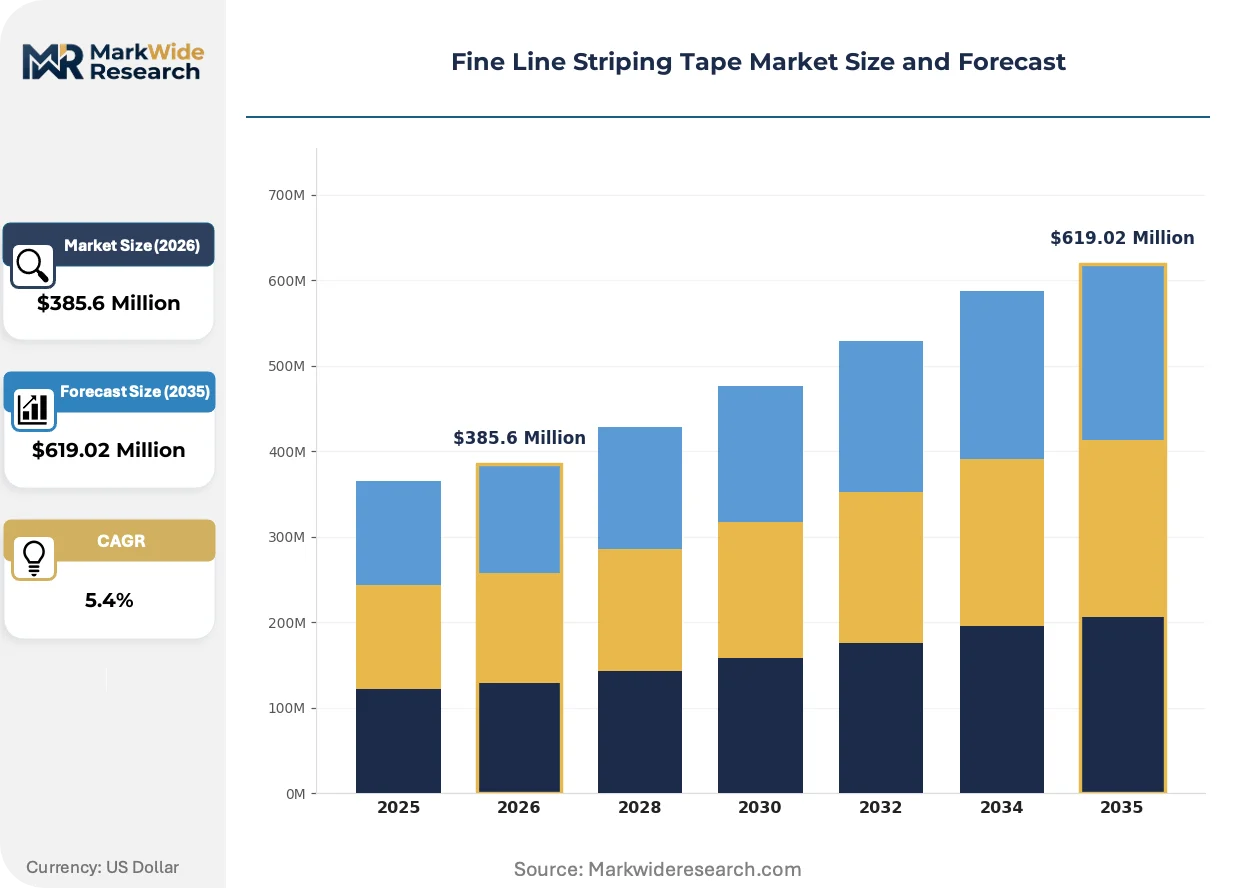
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Polyester, Polypropylene, PVC Application: Road Marking, Sports Facilities, Parking Lots, Floor Tape End User: Contractors, DIY Enthusiasts, Industrial Manufacturers, Municipalities Technology: Manual Application, Automated Application, Heat Transfer, Cold Application |
| Companies Covered | Intertape Polymer Group, Shurtape Technologies, 3M, PPM Industries SpA, Avery Dennison Corporation, Tesa SE, Nitto Denko Corporation, Scapa Group plc, Saint-Gobain Performance Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Line Striping Tape Market Shifts & Advancements
Material science advances and procurement digitization are compressing product development cycles while elevating performance verification standards across the striping value chain.
Embedded RFID tagging is integrating into preformed pavement marking tapes to enable automated inventory tracking and installation verification. State DOT asset management divisions in Michigan and Pennsylvania are piloting these smart markings for lifecycle monitoring. The technology is integrating with existing GIS platforms, reducing manual inspection labor while creating data service revenue streams for tape suppliers.
EPA VOC restrictions are tightening adhesive formulation standards, compelling manufacturers to validate waterborne chemistries through accelerated weathering protocols. California Air Resources Board thresholds now extend beyond manufacturing emissions to cover field application conditions. Contractors serving Los Angeles County and Bay Area municipalities are retrofitting application equipment for low-VOC systems ahead of mandate deadlines.
Consolidated state procurement portals are displacing fragmented municipal bidding processes, concentrating specification influence among DOT central procurement offices. Florida's State Term Contract system and Texas Department of Transportation consolidated awards now cover 60 percent of annual striping volume in those states. Contractor fleets are consolidating to meet bonding and equipment scale requirements, reducing the addressable customer base for mid-tier tape distributors.
Fine Line Striping Tape Market Segmentation
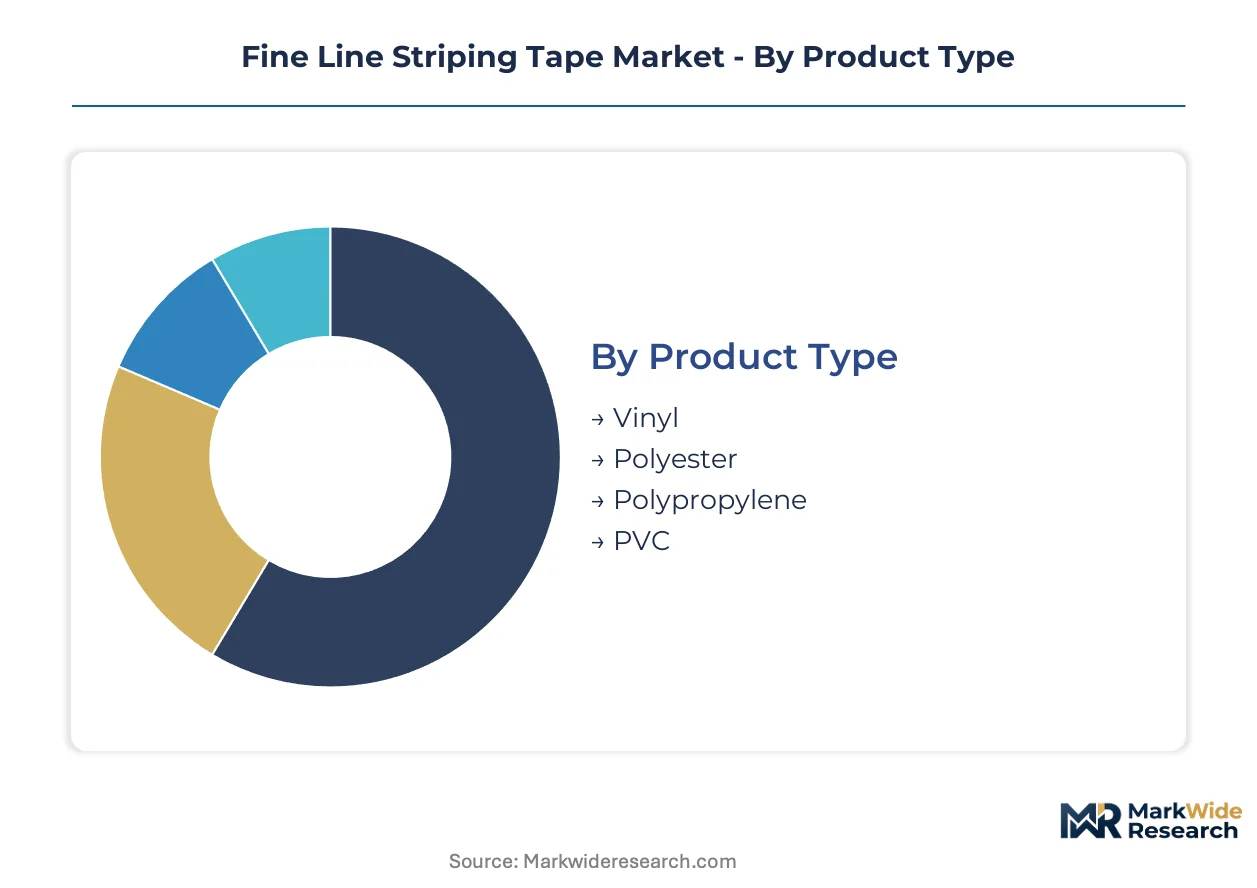
Fine line striping tape segmentation reveals how substrate chemistry, installation method, and end-user procurement scale interact to determine margin structures. Product differentiation across vinyl versus polyester formulations creates tiered qualification barriers for state highway contracts versus parking lot applications.
Product Type:
Integration depth varies sharply: vinyl and polyester dominate permanent highway installations as embedded systems within multi-layer pavement marking assemblies, while polypropylene and PVC serve standalone temporary applications where rapid deployment matters more than longevity.
- Vinyl:Cost-calibrated polymeric substrate coated with pressure-sensitive adhesives, formulated for temporary roadwork zones and seasonal lane restriping. Demand concentrates among California and Texas DOT maintenance divisions where procurement volumes favor economical replacement cycles over 18-24 month service life.
- Polyester:High-tenacity film engineered for elongation resistance below 2% under thermal cycling stress, qualifying for permanent highway installations under ASTM D4956 Type III and IV specifications. State DOTs in Florida and Arizona specify polyester for concrete bridge decks and high-shear zones where vinyl deformation risks retroreflectivity degradation.
- Polypropylene:Lightweight substrate suited to indoor floor marking and warehouse lane delineation where abrasion loads remain moderate.
- PVC:Rigid formulation serving sports facility line marking and parking lot boundary tape where dimensional stability at ambient temperatures suffices.
Volume placements concentrate in vinyl; the faster expansion belongs to polyester.
Application:
Cost tier stratification separates specification-intensive highway work from price-sensitive commercial segments, with procurement scale determining adhesive chemistry investment and certification burden.
- Road Marking:Federal Highway Administration retroreflectivity mandates govern lane boundary and hazard marking installations on asphalt and concrete surfaces. Caltrans and Florida DOT consolidated contracts drive specification convergence around ASTM D4956-certified sheeting grades.
- Sports Facilities:Synthetic turf and hardwood court line marking for school districts and municipal recreation departments. North American K-12 procurement cycles concentrate demand in July-August installation windows.
- Parking Lots:Commercial striping for retail and logistics properties where contractor bidding emphasizes unit cost over durability warranties.
- Floor Tape:Industrial warehouse lane marking and safety zone delineation, typically specified by facility managers rather than engineering departments.
Procurement scale peaks in road marking; margin compression is most severe in parking lots.
End User:
Customer type determines whether tape purchases flow through distributor networks or direct manufacturer relationships, with bonding capacity and equipment scale filtering market access.
- Contractors:State-qualified striping fleets serving DOT maintenance contracts and commercial parking projects. Florida's State Term Contract system and Texas DOT consolidated awards favor bonded contractors with automated application equipment.
- Municipalities:City and county road maintenance departments procuring through state cooperative purchasing agreements or independent bid processes.
- Industrial Manufacturers:Warehouse operators and logistics facilities specifying floor tape for internal traffic management and OSHA compliance marking.
- DIY Enthusiasts:Consumer segment purchasing pre-cut kits for residential driveway marking and small-scale sports court projects.
Revenue concentration sits with contractors; municipalities represent the steadiest replacement demand.
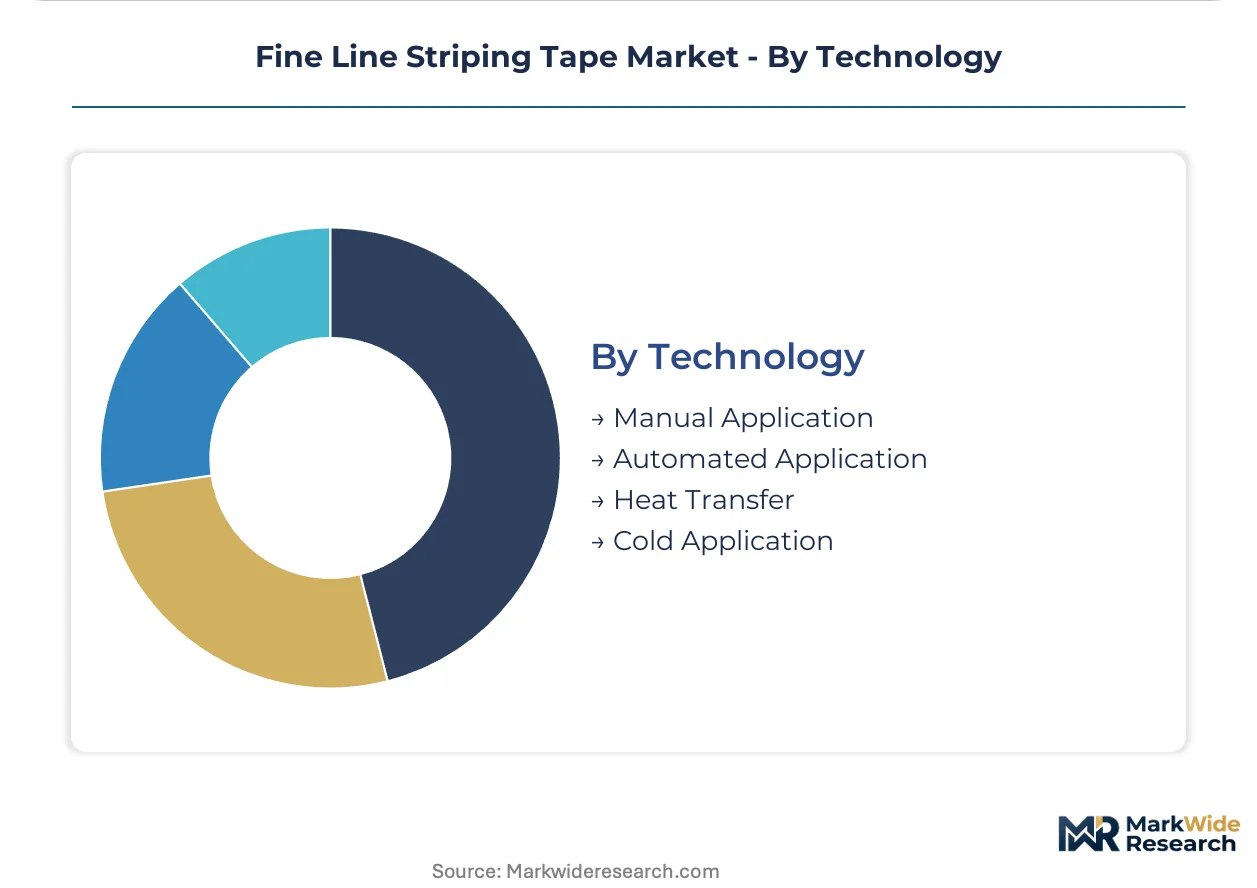
Technology:
Maturity gradients separate established manual methods from capital-intensive automated systems, with application scale determining equipment amortization feasibility.
- Automated Application:GPS-guided striping trucks with computer-controlled adhesive dispensing and bead embedding systems. State highway contractors in California and Texas deploy these for centerline and edge line renewal on interstate corridors.
- Cold Application:Pressure-sensitive tape systems requiring no heating equipment, retaining share among contractor fleets serving parking lot and sports facility segments where mobilization costs must stay minimal.
- Manual Application:Hand-guided dispensers and layout tools for small-scale projects and touch-up work.
- Heat Transfer:Preformed thermoplastic tape applied with propane-fired equipment, bridging temporary and permanent marking phases.
Equipment investment concentrates in automated application; cold application retains the broadest contractor base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level procurement consolidation in the United States concentrates demand among bonded contractors with automated equipment fleets. Caltrans specifications and Florida DOT contracts now govern specification standards that ripple through adjacent markets. Municipal maintenance budgets across Sun Belt states drive replacement cycles for retroreflective pavement markings.
United States
California DOT maintenance divisions and Texas highway contractors anchor North American demand through multi-year striping contracts. Federal Highway Administration retroreflectivity mandates compel state DOTs to replace degraded lane markings on accelerated schedules. The Los Angeles-San Diego corridor and Houston-Dallas corridor concentrate application equipment deployment and tape inventory positioning.
Germany
Autobahn maintenance programs and municipal road networks sustain demand for cold-climate adhesive formulations. ECHA REACH compliance requirements govern pressure-sensitive adhesive chemistry for European road marking applications. The Rhine-Ruhr industrial belt hosts converter operations serving Benelux and Scandinavian export markets.
China
National expressway expansion and provincial urban renewal programs drive procurement volume for pavement marking materials. MIIT standards for road traffic safety facilities establish sheeting grade requirements that filter supplier participation. The Yangtze River Delta manufacturing cluster supplies film substrates and retroreflective bead integration for domestic highway contractors.
Japan
Metropolitan expressway maintenance and prefectural road safety upgrades sustain precision striping material demand. METI technical standards for road marking materials specify durability testing protocols for polymer substrates. The Kanto region around Tokyo concentrates applicator fleet operations and tape distribution logistics.
Australia
State road authority maintenance contracts and mining haul road marking sustain demand for high-durability striping solutions. State-level procurement cooperatives in New South Wales and Victoria consolidate specification influence among qualified suppliers. The Sydney-Melbourne transport corridor concentrates contractor fleet capacity and tape inventory staging.
Fine Line Striping Tape Market Competitive Landscape
North American producers anchor one tier; European specialists hold adhesive formulation leadership in cold-climate applications. The vendor base stratifies across integrated film extruders, adhesive coaters, and regional converters serving state DOT qualification requirements. Three archetypes dominate: retroreflective technology licensors, adhesive chemistry specialists, and regional tape converters with state certification portfolios. Competitive moves concentrate on ASTM D4956 certification acquisition and automated application equipment partnerships.
Among diversified materials conglomerates, 3M and Avery Dennison Corporation exemplify the premium-tier positioning built on retroreflective technology portfolios and film durability expertise. Tesa SE represents the European specialist archetype with adhesive formulation capabilities for climate-differentiated road marking segments. Nitto Denko Corporation anchors Asian supply positioning through polymer substrate and pressure-sensitive adhesive integration.
| Leading Market Players |
|---|
| Intertape Polymer Group |
| Shurtape Technologies |
| 3M |
| PPM Industries SpA |
| Avery Dennison Corporation |
| Tesa SE |
| Nitto Denko Corporation |
| Scapa Group plc |
| Saint-Gobain Performance Plastics |
| Others |
Supply & Pricing Matrix
Automated striping equipment deployment across California and Texas DOT corridors is compressing contractor margins while elevating performance thresholds for tape adhesion and dimensional stability, simultaneously concentrating procurement volume among qualified suppliers with ASTM D4956 certification and squeezing mid-tier converters without in-house film extrusion capacity.
Pricing Analysis
Volume placements in vinyl formulations for temporary roadwork zones trade at compressed margins, while polyester substrates for permanent highway installations under ASTM D4956 Type III and IV specifications capture premium spreads. Price differentiation hinges on certification grade attainment and retroreflective bead integration quality. Pricing pressure intensifies in parking lot and sports facility segments where contractor bidding emphasizes unit cost over durability warranties. Municipal road maintenance departments exhibit highest price sensitivity; state DOT consolidated contracts show lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Applicator workforce shortages in the Ohio River Valley glass microsphere production cluster and the Yangtze River Delta film substrate manufacturing belt are constraining capacity expansion timelines. Raw material flows draw from petroleum-derived vinyl and polyester resins, high-index glass microspheres, and pressure-sensitive adhesive polymers. Single-source vulnerability concentrates in domestic high-index bead supply. Distribution runs through state-qualified contractor fleets and regional tape converters serving DOT certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
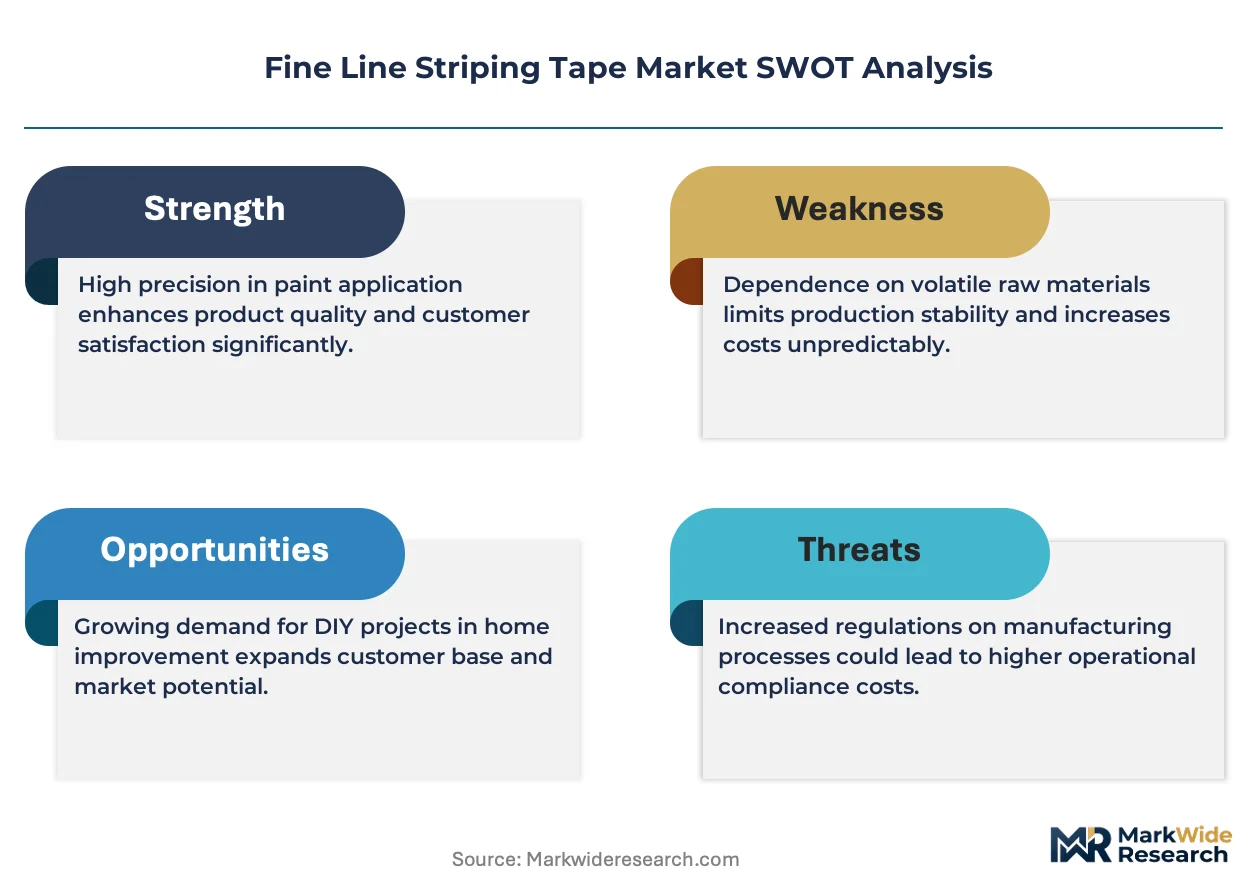
This market is consolidating around automated application capability and ASTM D4956 certification portfolios, with EPA VOC restrictions and state-level Buy America preferences forcing weaker players without vertical integration into exit or acquisition.
For Market Incumbents: Deploy backward integration into film extrusion and adhesive coating capacity to defend margin position against petroleum resin volatility and capture state-level domestic content preferences. Accelerate RFID-enabled smart marking pilot programs with Michigan and Pennsylvania DOT asset management divisions to create data service revenue streams. Counter preformed thermoplastic convergence threats by bundling temporary and permanent marking phase capabilities. For New Entrants and Emerging Players: Regional tape distributors with state certification portfolios represent the most penetrable channel partner type for wedge creation. Target EV charging zone marking specifications in Sun Belt municipalities as white-space volume outside traditional highway applications. Pursue waterborne adhesive chemistry validation through accelerated weathering protocols to meet California Air Resources Board thresholds ahead of mandate deadlines. For Investors and Strategic Acquirers: Re-rating potential sits with converters possessing vertically integrated film extrusion and adhesive coating capacity given state-level Buy America compliance specialization requirements. Long-term viability centers on 5-10 year infrastructure spending prioritization alignment. Monitor Florida State Term Contract and Texas DOT consolidated award schedules as inflection indicators for procurement concentration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D4956 Certification Investment | Third-party sheeting grade validation unlocks state DOT bid participation and multi-year contract eligibility. |
| Waterborne Adhesive Chemistry Transition | EPA VOC compliance redirects R&D toward hot-melt and emulsion systems maintaining peel strength in thermal cycling. |
| Automated Application Equipment Partnership | GPS-guided striping truck deployment secures bonding capacity for California and Texas DOT consolidated awards. |
| RFID-Enabled Smart Marking Integration | Embedded tagging pilots with Michigan and Pennsylvania DOTs create lifecycle monitoring data service revenue. |
| Preformed Thermoplastic Capability Addition | Extruded thermoplastic integration enables bundled bidding across temporary and permanent marking phases. |
Research Methodology
SEC 10-K filings, FHWA pavement marking databases, and state DOT procurement records formed the secondary backbone, supplemented by customs and trade data tracking vinyl and polyester resin flows. Primary interviews with road marking contractors, state DOT procurement officers, adhesive formulation chemists, and automated striping equipment operators grounded segmentation assumptions. Bottom-up tape volume estimates by substrate chemistry and application method triangulated against top-down infrastructure spending allocation analysis.
Historical trendline analysis of replacement cycle frequencies and retroreflectivity degradation curves informed projection frameworks across the analysis window. Segmentation modeling incorporated substrate type, installation technology, end-user procurement scale, and regional climate zone performance requirements. CAGRs derived from correlation between state DOT maintenance budget trajectories and sheeting grade specification tightening velocities, with cross-validation against petroleum resin price elasticity assumptions.
Caveats apply where FHWA retroreflectivity mandate enforcement intensity, EPA VOC restriction phase-in timelines, or concentrated glass microsphere supply disruptions could materially shift the outlook. Forecasts embed assumptions regarding state infrastructure spending prioritization continuity and automated application equipment fleet expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
PVC Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Thermoplastic Tape Market
Tapes
Paper Gummed Tape Market
Tapes
Cable Wrapping Tapes Market
Tapes
Nano Tapes Market
Tapes
Packaging Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
Holographic Tear Tape Market
Tapes
Filmic Tapes Market
Tapes
Foam Tape Market
Tapes
Umbilical Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Replica Tapes Market
Tapes
Acoustic Tape Market