
 Kitchen/ Toilet Roll Converting Machines Market | 2026-2036
Kitchen/ Toilet Roll Converting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen/ Toilet Roll Converting Machines Market Foresight
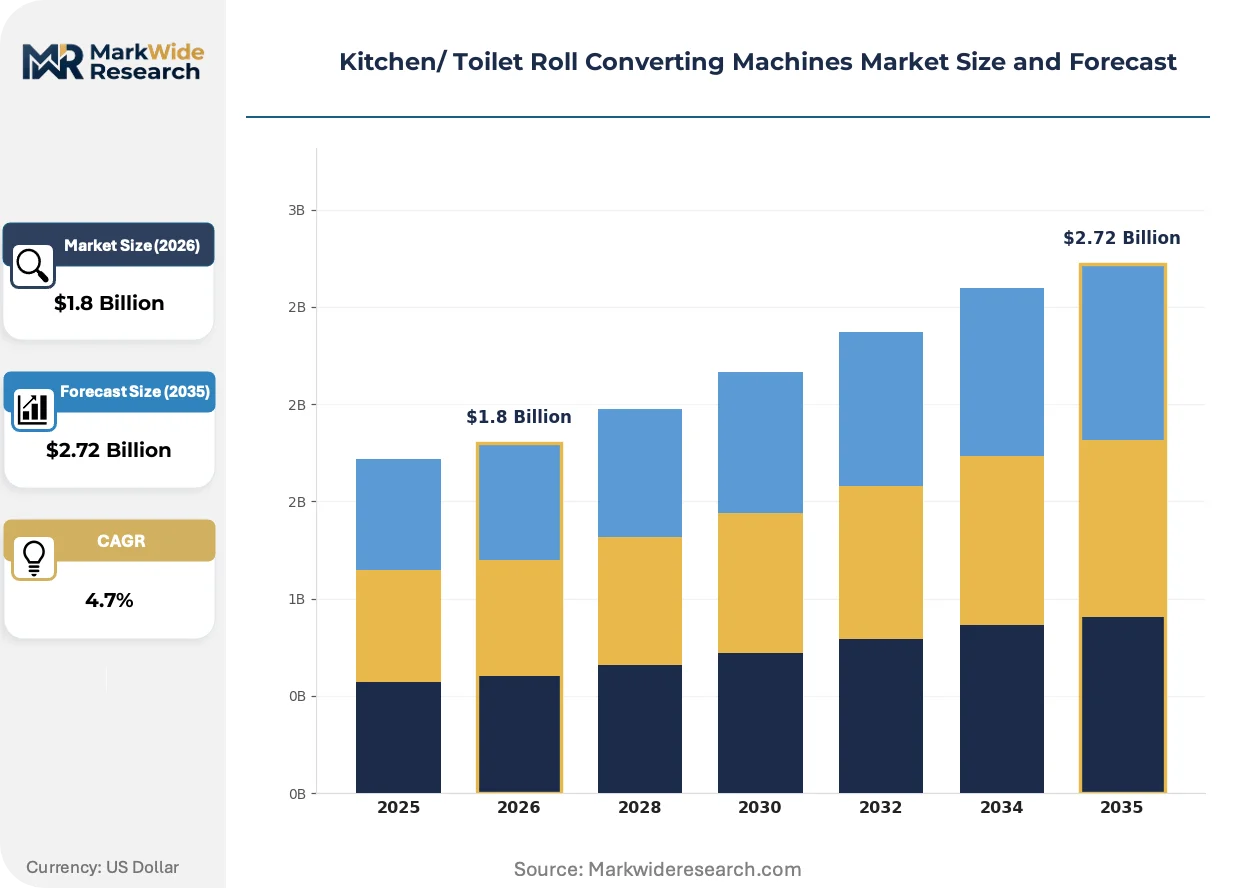
Buyer concentration among private-label tissue manufacturers is pivoting as discount retailers and regional consumer brands expand captive converting capacity. Körber Tissue AG leverages its integrated automation portfolio to anchor large-scale OEM relationships across Europe. Fabio Perini S.p.A. competes through deep specialization in high-speed embossing and perforation modules. Bretting Manufacturing Company, Inc. sustains its position via precision engineering for mid-tier North American converters seeking flexible line configurations.
Kitchen and toilet roll converting machines transform parent tissue jumbo reels into finished consumer rolls through unwinding, embossing, perforating, log cutting, and wrapping operations, with line speeds typically ranging from 200 to 600 meters per minute depending on automation grade. These systems serve commercial tissue producers requiring consistent ply adhesion, core insertion accuracy, and packaging integration to meet retail specification. Automatic lines dominate capital deployment among tier-one manufacturers due to throughput economics and labor cost arbitrage, while servo motor technology captures preference where quick changeovers between SKU formats reduce downtime. PLC controlled architectures retain share in retrofit markets where legacy mechanical systems require incremental automation without full line replacement.
CE marking and EU Ecodesign requirements shape machinery compliance costs for suppliers targeting European tissue converters, while FDA facility standards influence equipment sanitation specifications for North American producers serving foodservice towel segments. ISO 9001 quality management and ISO 14001 environmental management certifications increasingly gate supplier qualification with multinational tissue groups. Stakeholders must monitor how energy efficiency mandates and recycled fiber content targets alter machine design priorities and retrofit investment cycles.
Market Dynamics
Private-label tissue manufacturers are accelerating captive converting capacity builds across Southeast Asia, compressing third-party machinery demand while reshaping supplier-customer power dynamics toward turnkey automation partnerships.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandates for lower-GWP refrigerants in climate control systems are driving replacement cycles for aging converting lines across German and Italian tissue mills.
- Embossing pattern diversification:Consumer brands in Vietnam and Indonesia are specifying quick-change embossing modules to support rapid SKU rotation for private-label retail contracts.
- Parent reel width standardization:Harmonized jumbo reel specifications across ASEAN trade blocs are reducing changeover downtime and enabling cross-border spare parts pooling.
Market Restraints
- Specialized steel alloy supply:Precision-engineered unwind frames and log saw blades depend on niche alloy suppliers concentrated in Germany and Japan, creating input cost volatility.
- CE marking compliance burden:Small and mid-tier machinery builders face disproportionate certification costs for European market entry, favoring incumbent OEMs with dedicated compliance teams.
- Mechanical-to-servo retrofit complexity:Legacy pneumatic systems in North American converter plants resist incremental automation without full line replacement, freezing capital deployment.
Strategic Opportunities
- Recycled fiber content mandates:EU Ecodesign requirements for minimum recycled content in tissue products are creating demand for converting lines optimized for shorter, weaker fiber handling.
- Indonesia regional hub expansion:Underpenetrated outer island markets present whitespace for compact, lower-speed lines serving dispersed population centers outside Java.
- Cloud-based predictive maintenance:Convergence of PLC architectures with IoT sensor networks is enabling remote downtime prevention services as a recurring revenue layer for machinery OEMs.
Industry Challenges
- Servo control programming expertise:Tissue converters face acute shortages of automation engineers capable of optimizing multi-axis motion profiles for high-speed perforation accuracy.
- ISO 14001 certification timelines:Environmental management system audits for multinational tissue group supplier qualification are extending equipment approval cycles by four to six months.
- Legacy mechanical-pneumatic integration:Hybrid retrofits combining existing unwind sections with new servo-driven embossing modules create synchronization faults requiring specialized commissioning support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen/ Toilet Roll Converting Machines Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Manufacturers, Distributors, Retailers, Importers Technology: Servo Motor, PLC Controlled, Hydraulic, Mechanical Application: Bathroom Tissue, Paper Towel, Napkins, Industrial Wipes |
| Companies Covered | Körber Tissue AG, Fabio Perini S.p.A., Bretting Manufacturing Company, Inc., Valmet Oyj, BaoSuo Paper Machinery, Dechangyu Paper Machinery, Gambini S.p.A., Futura S.p.A., Omet S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen/ Toilet Roll Converting Machines Market Shifts & Advancements
Automation architectures and sustainability mandates are converging to redefine machinery specifications, with digitalization and energy efficiency emerging as the primary axes of competitive differentiation among converting equipment suppliers.
Servo motor technology is expanding into mid-tier converting lines previously dominated by mechanical cam systems. Regional consumer brands in Vietnam are specifying servo-driven embossing and perforation modules to enable sub-15-minute format changeovers. This capability compression is eroding the throughput advantage historically held by large-scale automatic lines, democratizing flexible manufacturing across smaller converter footprints.
The EU Ecodesign Directive's expanding scope now covers energy consumption metrics for tissue converting machinery operational efficiency. Equipment suppliers must document power draw per finished roll across standardized duty cycles to maintain CE marking eligibility. High-volume producers in Germany and Italy are responding by specifying regenerative drive systems and heat recovery modules as standard configuration elements.
After-sales service unbundling is accelerating as tissue converters seek to separate maintenance contracts from original equipment purchases. Discount retailers with captive converting operations are negotiating standalone technical support agreements with third-party automation specialists rather than incumbent OEMs. This procurement pattern shift is most visible in Indonesia, where regional private-label brands are building in-house maintenance capabilities to reduce lifetime machinery operating costs.
Kitchen/ Toilet Roll Converting Machines Market Segmentation
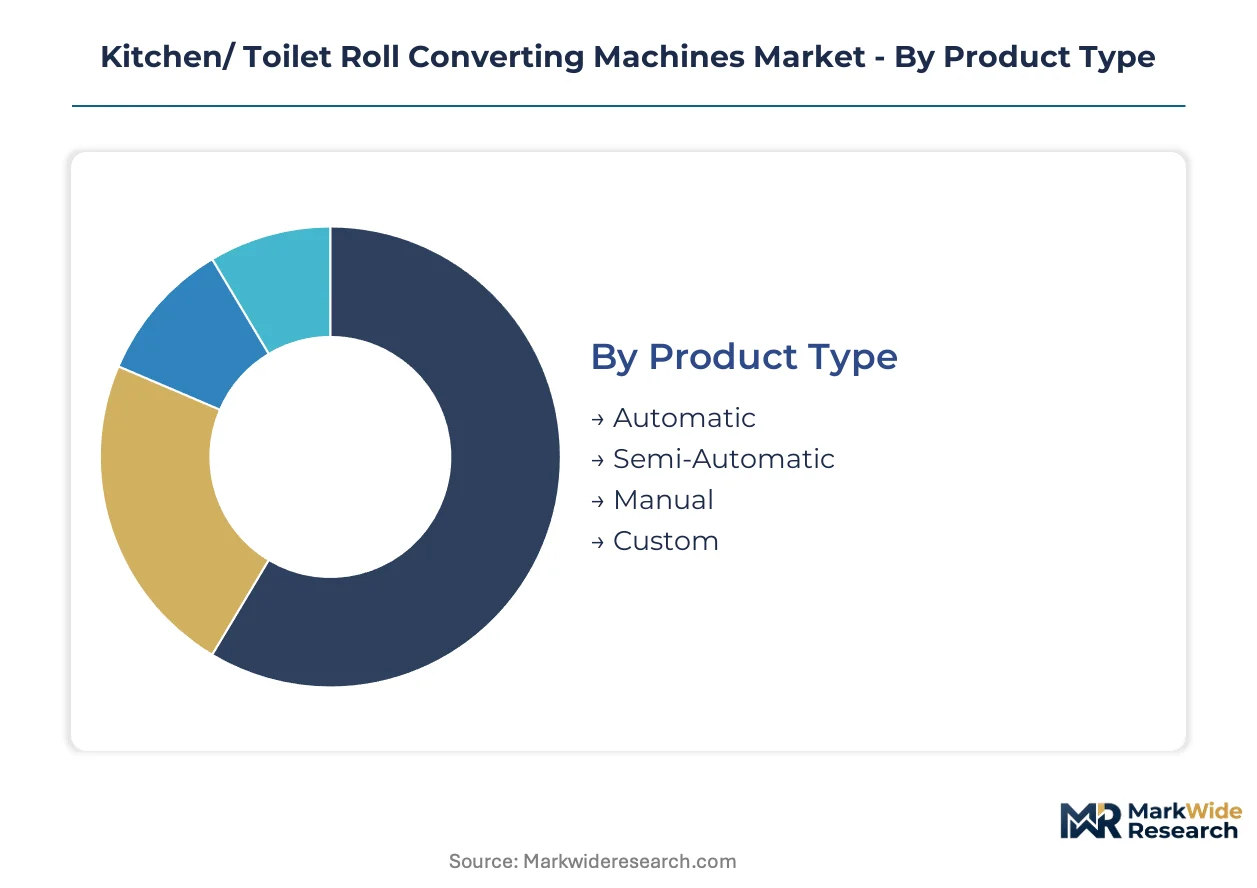
Segmentation in converting machinery reveals how automation grade, control architecture, and end-use specifications reshape procurement priorities across tissue supply chains. Manufacturers configure line investments around throughput economics, regulatory compliance, and SKU flexibility requirements.
Product Type:
Volume lines dominate capital deployment among tier-one tissue groups, while premium flexibility commands price premiums among regional brands.
- Automatic:Fully integrated lines achieve 400-600 meters per minute through continuous unwinding, embossing, and wrapping sequences. Demand concentrates in Germany and Italy where F-Gas Regulation replacement cycles favor complete line renewal over retrofit. Labor cost arbitrage and throughput economics anchor adoption among multinational tissue producers.
- Semi-Automatic:Hybrid configurations blend mechanical unwind sections with servo-driven finishing modules. Vietnam's expanding private-label manufacturers specify these lines to balance capital constraints against embossing pattern diversification needs for retail contract flexibility.
- Manual:Entry-level systems serve micro-converters and startup tissue operations with batch processing and operator-dependent changeovers.
- Custom:Engineered-to-order lines address non-standard parent reel widths or specialized ply bonding requirements for premium tissue grades.
Today's leader: Automatic. Tomorrow's challenger: Semi-Automatic.
End User:
Captive converting capacity builds are compressing traditional machinery demand patterns across buyer categories.
- Manufacturers:Integrated tissue mills with in-house converting operations specify high-speed automatic lines to capture margin from parent reel to finished roll. Indonesia's regional consumer brands are building captive footprints across outer island markets to reduce logistics costs.
- Distributors:Third-party converters serving multiple tissue brands prioritize quick-changeover semi-automatic lines to manage SKU proliferation.
- Retailers:Discount retail chains with private-label tissue programs are accelerating direct machinery procurement, bypassing traditional OEM service bundles in favor of standalone maintenance contracts.
- Importers:Trading houses supplying emerging market converters focus on refurbished automatic lines and legacy mechanical systems with lower capital barriers.
Procurement gravity is shifting from distributors toward retailers with captive operations.
Technology:
Control architecture selection determines changeover speed, energy efficiency compliance, and retrofit pathway viability.
- Servo Motor:Multi-axis motion control enables sub-15-minute format changeovers through programmable embossing and perforation profiles. Vietnam's consumer brands specify servo modules to support rapid SKU rotation for private-label contracts, compressing the throughput advantage historically held by large-scale automatic lines.
- PLC Controlled:Programmable logic architectures dominate retrofit markets where legacy mechanical systems require incremental automation without full line replacement. FDA facility standards for North American foodservice towel segments favor PLC-based sanitation monitoring integration.
- Hydraulic:Remains entrenched in high-tonnage log cutting applications where pneumatic alternatives lack force density for dense tissue grades.
- Mechanical:Cam-driven systems persist in mature North American converter plants where capital deployment freezes against full automation replacement costs.
Adoption is climbing fastest in servo motor technology as energy efficiency mandates tighten.
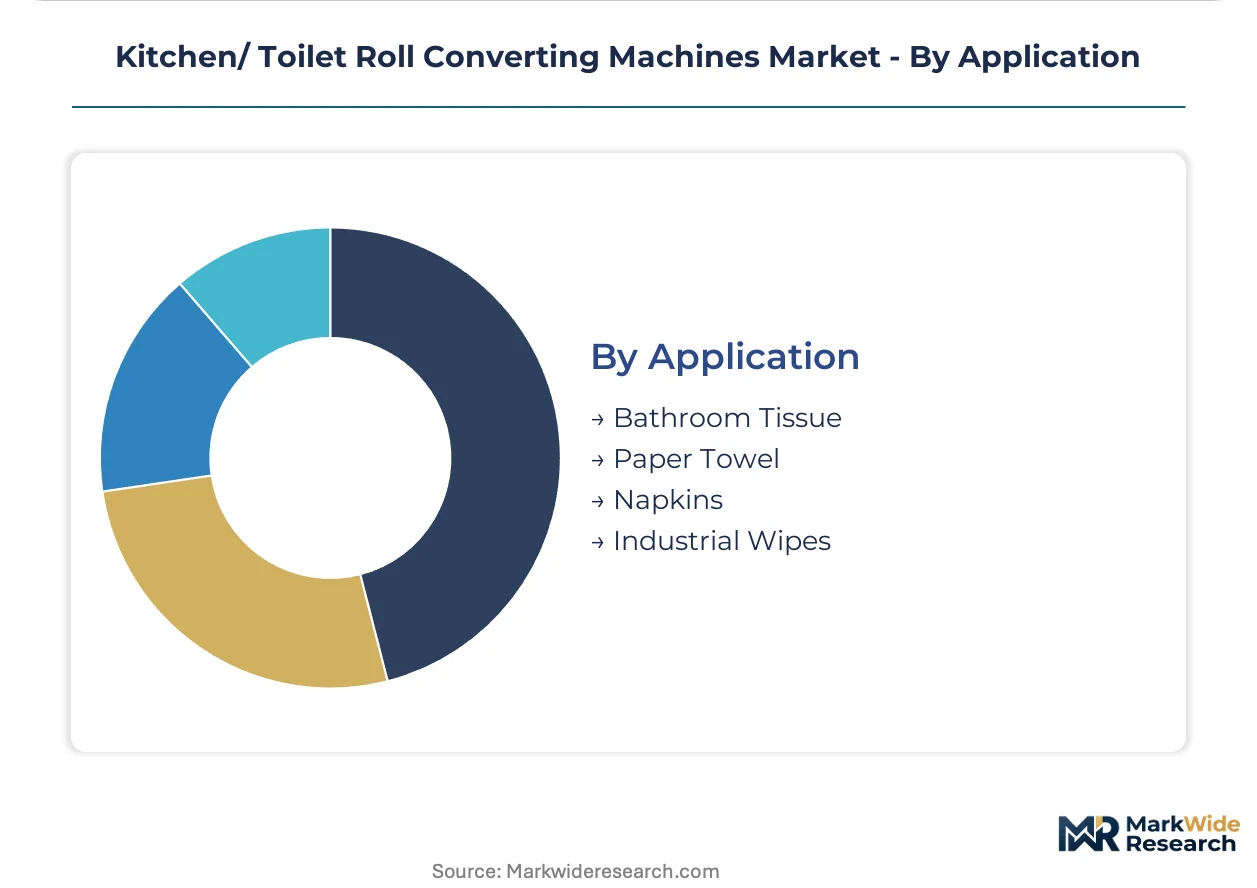
Application:
End-use specifications drive divergent requirements for ply adhesion, embossing depth, and packaging integration.
- Bathroom Tissue:Two-ply and three-ply converting lines require precise core insertion accuracy and controlled unwind tension to prevent ply separation. EU Ecodesign recycled fiber content mandates are creating demand for lines optimized for shorter, weaker fiber handling in German and Italian mills.
- Paper Towel:Foodservice and household segments demand high wet strength and specific absorbency profiles. FDA facility standards influence equipment sanitation specifications for North American producers.
- Napkins:Compact folding modules and specialized packaging integration distinguish napkin converting from roll-based systems.
- Industrial Wipes:Non-woven substrate handling and chemical treatment compatibility requirements diverge from standard tissue converting architectures.
Bathroom tissue maintains volume leadership. Industrial wipes present the steepest expansion trajectory as commercial hygiene protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains tighter machinery specification standards than Vietnam, yet both markets drive substantial equipment procurement as regional tissue brands expand captive converting capacity.
Germany
F-Gas Regulation phase-down mandates accelerate replacement cycles for aging converting lines in German tissue mills. EU Ecodesign requirements for energy consumption documentation now gate CE marking eligibility for machinery suppliers. The Lucciana industrial corridor hosts concentrated OEM engineering activity as Körber Tissue AG anchors large-scale automation partnerships.
Italy
High-speed embossing module demand from premium tissue brands shapes Italian converter investment priorities. REACH compliance obligations for chemical handling in climate control systems add certification layers to equipment procurement. Bologna-Modena manufacturing clusters specialize in precision perforation and log saw blade engineering for European export markets.
Vietnam
Private-label tissue manufacturers expand captive converting capacity across northern industrial zones near Hanoi and Hai Phong. Quick-change embossing specifications for rapid SKU rotation dominate machinery tenders from regional consumer brands. Binh Duong province attracts semi-automatic line deployments balancing capital constraints against retail contract flexibility requirements.
Indonesia
Outer island market underpenetration creates whitespace for compact lower-speed lines serving dispersed population centers outside Java. National standards for recycled fiber content in tissue products align with EU Ecodesign trajectories, influencing machine design priorities. Surabaya manufacturing hubs concentrate regional brand converting footprints to reduce logistics costs across the archipelago.
United States
Mid-tier North American converters seek flexible line configurations to manage SKU proliferation across private-label retail contracts. FDA facility standards for foodservice towel segments influence equipment sanitation specifications in converting plants. Wisconsin and Ohio industrial corridors sustain precision engineering demand from converters retrofitting legacy mechanical-pneumatic systems.
Kitchen/ Toilet Roll Converting Machines Market Competitive Landscape
German producers anchor the premium automation tier; Italian specialists hold entrenched positions in high-speed finishing modules. The vendor base separates into three functional layers: integrated automation portfolio suppliers, deep specialization players in embossing and perforation, and regional fabricators serving capital-constrained mid-tier converters. Two dominant competitive moves shape positioning: turnkey automation partnerships that bundle equipment with predictive maintenance services, and geographic expansion into Southeast Asian markets where private-label capacity builds concentrate.
Within the integrated automation tier, Körber Tissue AG and Valmet Oyj represent archetypal European engineering houses with multi-line portfolio breadth. Fabio Perini S.p.A. occupies a specialist position exemplifying deep module-level expertise in high-speed embossing architectures. Bretting Manufacturing Company, Inc. anchors the North American mid-tier segment, reflecting precision engineering capabilities calibrated to flexible configuration requirements.
| Leading Market Players |
|---|
| Körber Tissue AG |
| Fabio Perini S.p.A. |
| Bretting Manufacturing Company, Inc. |
| Valmet Oyj |
| BaoSuo Paper Machinery |
| Dechangyu Paper Machinery |
| Gambini S.p.A. |
| Futura S.p.A. |
| Omet S.r.l. |
| Others |
Supply & Pricing Matrix
Specialized steel alloy price indices from German and Japanese suppliers cascade through converting machinery manufacturing into three-tier pricing structures across premium, standard, and economy equipment tiers. CE marking compliance costs and servo motor component premiums concentrate pricing power among incumbent OEMs with dedicated certification teams, while Southeast Asian capacity builds compress margins for mid-tier builders.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for semi-automatic lines as regional private-label manufacturers negotiate volume discounts against quick-changeover specifications. Contract-based long-term offtake dominates procurement between multinational tissue groups and integrated automation suppliers, with price differentiation anchored in CE marking tier and after-sales service bundling. Cost compression in manual and entry-level segments intensifies because Chinese fabricators expand regional distribution networks. Discount retailers with captive converting operations exhibit highest price sensitivity through unbundled maintenance negotiations, while premium tissue brands in Italy demonstrate lowest sensitivity when specifying high-speed embossing module precision.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated tissue mills in Germany and Italy, while distributor networks serve capital-constrained converters across Southeast Asia. Manufacturing concentrates in Germany, Italy, and China, with precision-engineered unwind frames and log saw blades drawing from niche alloy suppliers in Germany and Japan. Raw material dependencies span specialized steel alloys, servo motor drives from Japanese automation houses, and PLC architectures from European controls specialists. Single-source vulnerability concentrates in high-tonnage hydraulic systems for dense tissue grades, where alternative suppliers lack force density certification. Distribution runs through machinery OEMs with regional service subsidiaries, third-party automation specialists, and refurbished equipment trading houses serving emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Kitchen/Toilet Roll Converting Machines Market functions as a stable compounder, with EU Ecodesign and F-Gas Regulation mandates driving steady replacement cycles across European tissue mills. Automation grade upgrades and sustainability compliance investments sustain equipment demand regardless of macroeconomic volatility.
For Market Incumbents: Deepen predictive maintenance service bundling to capture recurring revenue from discount retailers unbundling traditional OEM contracts. Anchor large-scale automation partnerships through integrated servo motor portfolios that compress changeover times below 15 minutes. Defend against Chinese fabricator encroachment by embedding CE marking compliance expertise into turnkey offerings that mid-tier builders cannot replicate without dedicated certification teams. For New Entrants and Emerging Players: The price-point gap between premium Italian embossing modules and economy Chinese fabricator lines creates entry space for mid-speed servo-driven systems targeting Indonesian outer island markets. Target compact line configurations for dispersed population centers outside Java where logistics costs disadvantage large-scale automatic deployments. Pursue standalone technical support agreements with regional private-label brands building in-house maintenance capabilities to bypass incumbent OEM service bundles. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 14001 certification timelines extend equipment approval cycles by four to six months, favoring acquirers with existing environmental management infrastructure. The market supports long-term viability framing around recurring service revenue streams and regulatory-driven replacement cycles rather than cyclical capital expenditure dependence. Target acquisition archetypes include regional automation specialists with embedded servo programming expertise and Southeast Asian distribution networks. Watch for inflection where EU recycled fiber content mandates accelerate demand for shorter-fiber-optimized converting lines.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Launch | Remote IoT-enabled downtime prevention creates recurring revenue layers beyond equipment sales. |
| Quick-Change Embossing Module Development | Sub-15-minute format changeovers capture private-label contract flexibility requirements in Vietnam. |
| CE Marking Compliance Infrastructure Investment | Dedicated certification teams gate European market entry against mid-tier machinery builders. |
| Southeast Asian Regional Hub Establishment | Local assembly and service presence reduce logistics costs across Indonesian archipelago markets. |
| Recycled Fiber Handling Line Optimization | EU Ecodesign mandates for minimum recycled content drive specialized equipment demand. |
Research Methodology
Multiple input streams — primary interviews with tissue mill engineering directors, OEM product managers, and aftermarket service heads; secondary validation through SEC machinery manufacturer filings, EU Ecodesign regulatory databases, and ASEAN trade bloc customs records; plus equipment procurement database analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured capital expenditure timelines, SKU flexibility requirements, and retrofit versus replacement decision criteria across German, Italian, Vietnamese, Indonesian, and North American converter operations.
Data-stream reconciliation anchored volume and value outputs across automation grade, control architecture, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from equipment shipment trajectories, parent reel width standardization trends, and replacement cycle analysis throughout the forecast period. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down schedules, recycled fiber content mandate trajectories, and servo motor adoption curves across mid-tier line configurations.
The model assumes a particular technology adoption path; alternative pathways for mechanical-to-servo retrofit penetration would alter the outlook if legacy pneumatic system integration complexity proves more tractable than base-case assumptions. Forecasts reflect documented assumptions around EU regulatory enforcement consistency, Southeast Asian logistics infrastructure development, and specialized steel alloy supply stability. Periodic stress-testing of base assumptions is recommended against tariff exposure in precision component trade and automation engineer labor market tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Global Blister Packaging Machinery Market