
 Oil Resistant Packaging Market | 2026-2036
Oil Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Resistant Packaging Market Analytics
Fluorochemical coatings is rebalancing toward bio-based and recyclable barrier systems as brands face extended producer responsibility mandates. Amcor leverages integrated film-to-package manufacturing across multiple continents. Mondi anchors European kraft paper operations with certified recyclable oil-barrier grades. Berry Global competes through blown film scale in North American food-service channels.
Oil resistant packaging denotes engineered materials and converted structures that prevent grease, fat, and hydrocarbon migration between contained products and external environments, typically achieving oil kit ratings of 8-12 or equivalent Cobb-Unger values below 20 g/m². Polyethylene and polypropylene films dominate flexible formats due to heat-seal reliability and moisture-oil dual barrier performance; paperboard represents the fastest-growing structural platform as fiber-based solutions displace multilayer plastics in quick-service restaurant applications. Pouches and roll stock capture disproportionate investment from food industry end users seeking portion-control and shelf-life extension, while rigid containers retain margin pools in premium cosmetics and pharmaceutical oil-based formulations.
FDA food-contact substance notifications and EPA per- and polyfluoroalkyl substance restrictions in the United States, alongside REACH Annex XVII limitations on persistent organic pollutants in Europe, compel reformulation of legacy oil-barrier chemistries toward mineral-oil-free and bio-wax alternatives. China's SAMR national food safety standards and GB migration limits add compliance layers for imported packaging substrates. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure dual-certified substrate supply before phased substance bans take effect.
Market Dynamics
Extended producer responsibility mandates are forcing reformulation of oil-barrier chemistries across food-contact packaging, shifting procurement criteria from performance-only to circularity-certified substrates. This regulatory pressure is compressing legacy fluorochemical coating volumes while accelerating mineral-oil-free and bio-wax alternative qualification timelines.
Growth Catalysts
- REACH Annex XVII limitations:Persistent organic pollutant restrictions in Europe compel substrate suppliers to certify mineral-oil-free barrier grades, creating first-mover premium capture for compliant converters.
- Quick-service restaurant fiber transition:Paperboard oil-barrier solutions displace multilayer plastics in burger and fried-food packaging as chains face single-use plastic bans in Germany, France, and California.
- Blown film heat-seal reliability:Polyethylene and polypropylene films retain dominance in flexible roll stock for portion-control pouches where moisture-oil dual barrier performance remains non-negotiable.
Market Restraints
- Fluorinated raw material concentration:Legacy PFAS-based barrier chemistry supply concentrates among limited specialty chemical producers, exposing converters to EPA substance restriction volatility and forced reformulation costs.
- Bio-wax performance ceiling:Plant-derived barrier coatings fail to match fluorochemical oil kit ratings above 10 in high-temperature fried-food applications, limiting complete material substitution.
- China GB standard divergence:SAMR migration limits for imported packaging substrates require dual certification testing, extending qualification timelines for European and North American exporters.
Strategic Opportunities
- Indian quick-service expansion:FSSAI food-contact compliance frameworks are maturing as Yum Brands and Domino's localize supply chains, creating virgin demand for certified oil-barrier paperboard.
- Pharmaceutical oil-based formulations:Rigid container demand for cosmetics and nutraceuticals with hydrocarbon active ingredients remains underpenetrated by fiber-based alternatives.
- Recyclable barrier certification:EU Green Deal packaging and packaging waste regulation incentives reward mono-material structures with extended producer responsibility fee reductions.
Industry Challenges
- Dual-certified substrate sourcing:Qualifying materials that satisfy both FDA food-contact substance notifications and REACH Annex XVII simultaneously demands specialized regulatory affairs staffing and extended laboratory testing cycles.
- Extrusion coating line reconfiguration:Shifting from fluorochemical to bio-wax barrier application requires capital-intensive drying system modifications and slower line speeds during qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Resistant Packaging Market |
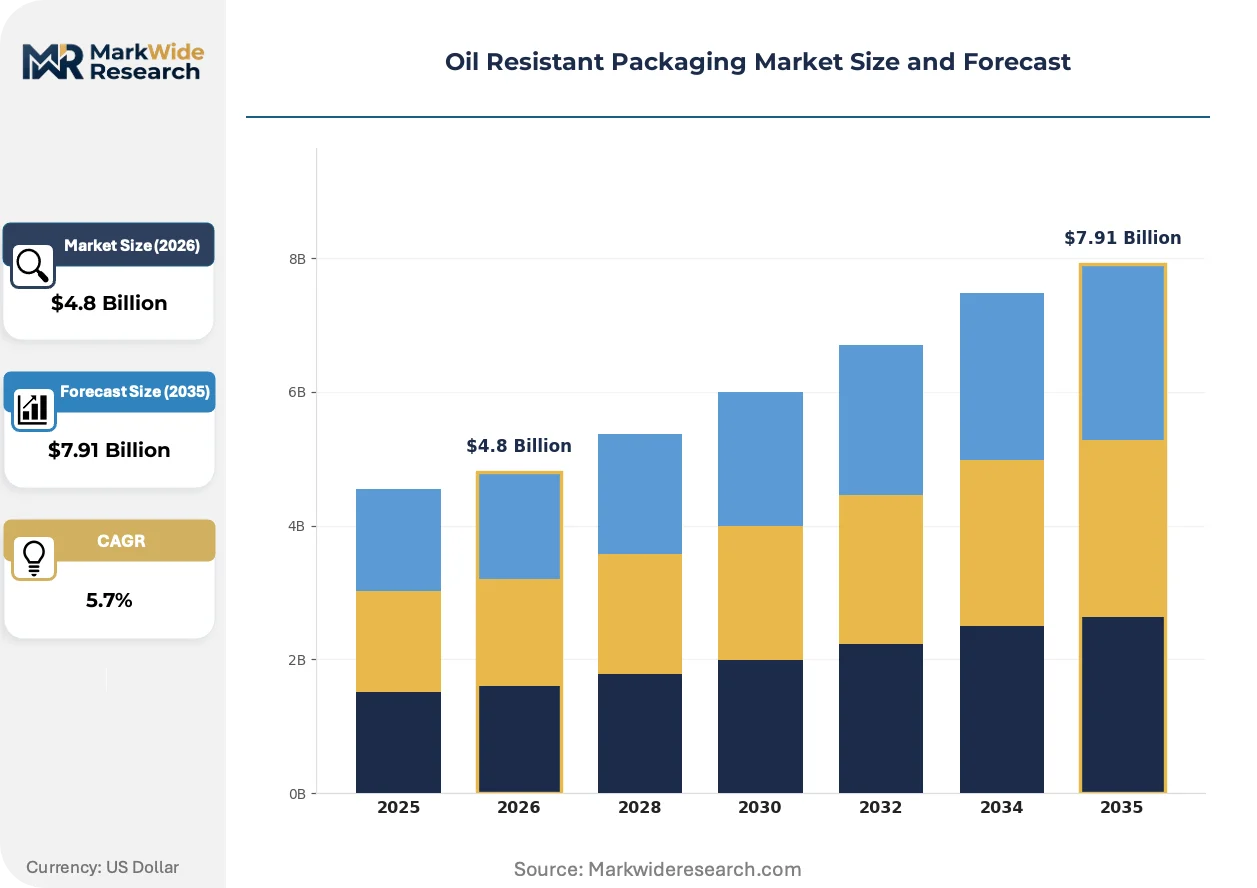
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Paperboard Packaging Type: Pouches, Roll Stock, Boxes, Containers End User: Food Industry, Pharmaceuticals, Cosmetics, Industrial Applications Material: Plastic, Metal, Glass, Composites |
| Companies Covered | Amcor, Mondi, Berry Global, Huhtamaki, Sonoco, Zanders GmbH, Archroma, DuPont, Michelman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Resistant Packaging Market Evolving Landscape
Barrier technology convergence with circular economy infrastructure is reshaping competitive positioning in oil-resistant packaging. Material scientists, regulatory consultants, and brand sustainability officers now co-develop specifications rather than sequential handoffs.
Water-based bio-wax emulsion coatings are decentralizing barrier manufacturing by enabling paper mills to integrate oil-resistance directly into base stock production rather than relying on downstream converter coating. Quick-service restaurant chains in Germany and the Netherlands are qualifying these integrated grades for burger wraps and french fry cartons. This vertical integration of barrier function into primary pulp and paper operations is compressing traditional converter margins and shortening supply chains.
EPA per- and polyfluoroalkyl substance restrictions are eliminating legacy C6 and C8 fluorochemical treatments from food-contact applications by 2027. The industrial consequence is a qualification rush for mineral-oil-free and silicone-based alternatives across North American flexible packaging. Pouch and roll stock converters serving frozen and fried-food segments face the steepest reformulation timelines and are consolidating supplier relationships to secure compliant substrate allocation.
Buyers are consolidating vendor panels around dual-certified substrate suppliers capable of serving both European and North American regulatory regimes simultaneously. Frozen food manufacturers in the United States are reducing qualified supplier lists from twelve to four partners to simplify compliance documentation. This concentration is most visible in the prepared meals segment, where private-label brands demand single-source accountability for oil-barrier performance and regulatory certification.
Oil Resistant Packaging Market Segmentation
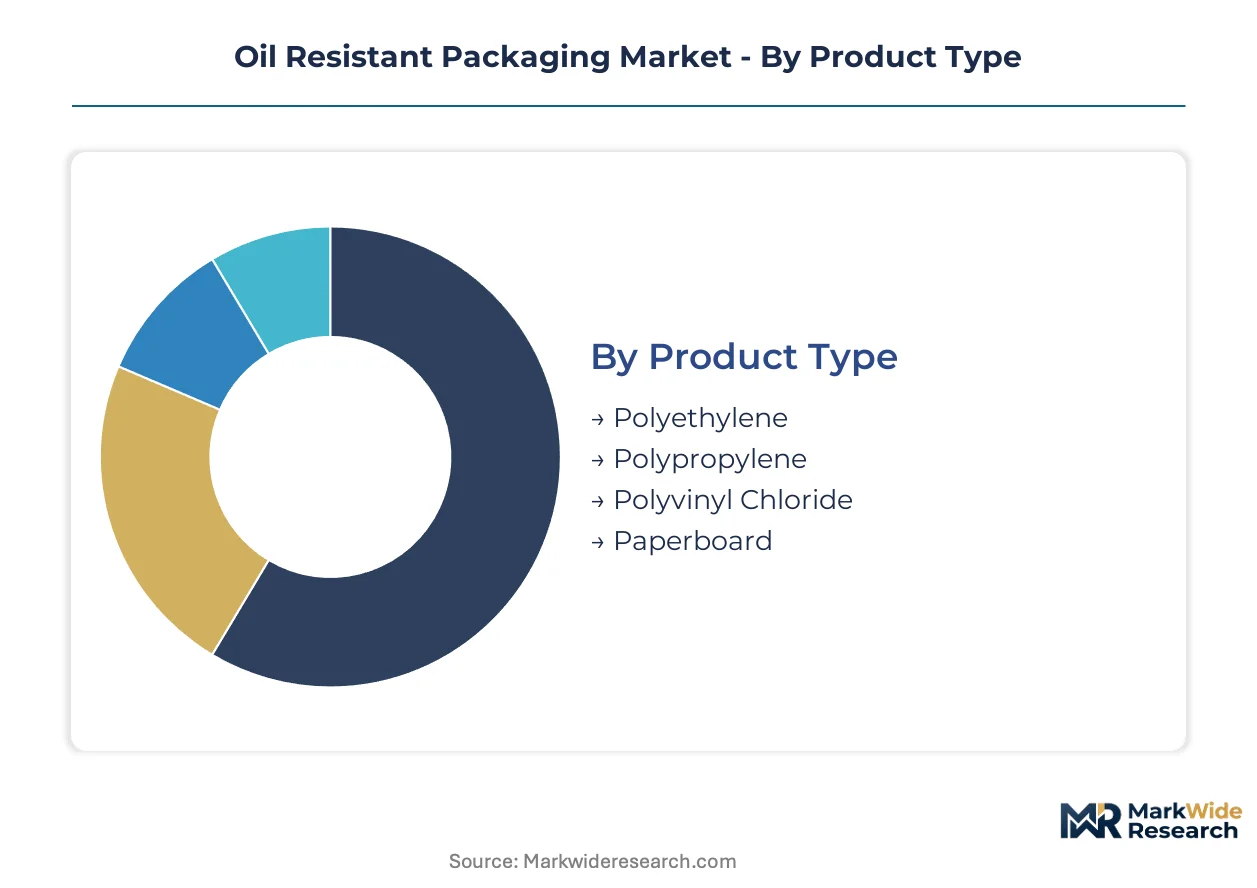
Segmentation in oil resistant packaging reveals how material science, regulatory compliance, and end-use performance requirements intersect to create distinct procurement clusters. Buyers prioritize either flexible barrier reliability or structural recyclability depending on their product format and geographic regulatory exposure.
Product Type:
Standardization dominates commodity polymer grades while specialty barrier formulations command premium qualification cycles and dedicated production lines.
- Polyethylene:Low-density and linear low-density variants provide heat-seal reliability and moisture-oil dual barrier performance in frozen and fried-food pouches. FDA food-contact substance notifications and EPA per- and polyfluoroalkyl substance restrictions are accelerating reformulation toward mineral-oil-free barrier additives in North American flexible packaging.
- Polypropylene:Oriented and cast films deliver higher temperature resistance for hot-fill and retort applications where oil migration resistance must survive thermal processing. Blown film converters serving quick-service restaurant supply chains in the United States concentrate procurement around biaxially oriented grades with certified oil kit ratings above 10.
- Polyvinyl Chloride:Rigid and semi-rigid formats retain niche positions in pharmaceutical blister packs and industrial chemical containment where clarity and hydrocarbon resistance coincide.
- Paperboard:Kraft and solid bleached sulfate grades with integrated bio-wax barriers displace multilayer plastics in burger wraps and french fry cartons under Germany's single-use plastic bans.
Leading the category by volume: Polyethylene. Expanding most quickly: Paperboard.
Packaging Type:
Format selection tracks directly to automation compatibility and shelf-life extension requirements across food manufacturing clusters.
- Pouches:Stand-up and flat pouch configurations capture disproportionate investment from frozen food manufacturers seeking portion control and extended shelf stability. REACH Annex XVII compliance mandates in Europe are pushing converters toward mono-material polyethylene structures that qualify for extended producer responsibility fee reductions.
- Roll Stock:Continuous web formats supply high-speed form-fill-seal operations in prepared meals and snack food production. Berry Global and Amcor compete through blown film scale and integrated film-to-package manufacturing across multiple continents.
- Boxes:Folding carton and corrugated formats with internal barrier coatings serve quick-service restaurant chains transitioning away from plastic clamshells in France and California.
- Containers:Rigid tubs and jars retain margin pools in premium cosmetics and pharmaceutical oil-based formulations where fiber-based alternatives remain technically underpenetrated.
Highest throughput: Roll stock. Steepest qualification investment: Pouches.
End User:
Regulatory stringency and extended producer responsibility timelines create divergent material specification pathways across customer verticals.
- Food Industry:Processed food manufacturers in Germany, China, and the United States drive volume demand for grease-proof solutions in frozen, fried, and ready-to-eat segments. FSSAI food-contact compliance frameworks in India are maturing as Yum Brands and Domino's localize supply chains, creating virgin demand for certified oil-barrier substrates.
- Pharmaceuticals:Rigid container demand for oil-based active ingredients and nutraceutical formulations requires hydrocarbon migration resistance combined with child-resistant and senior-friendly closure compatibility.
- Cosmetics:Premium skincare and haircare brands specify oil-resistant folding cartons and tubes for formulations with botanical oils and silicone bases.
- Industrial Applications:Lubricant, adhesive, and chemical manufacturers specify drum liners and intermediate bulk containers with hydrocarbon containment ratings for warehouse and transport safety.
Dominant procurement volume: Food Industry. Fastest certification timeline pressure: Pharmaceuticals.
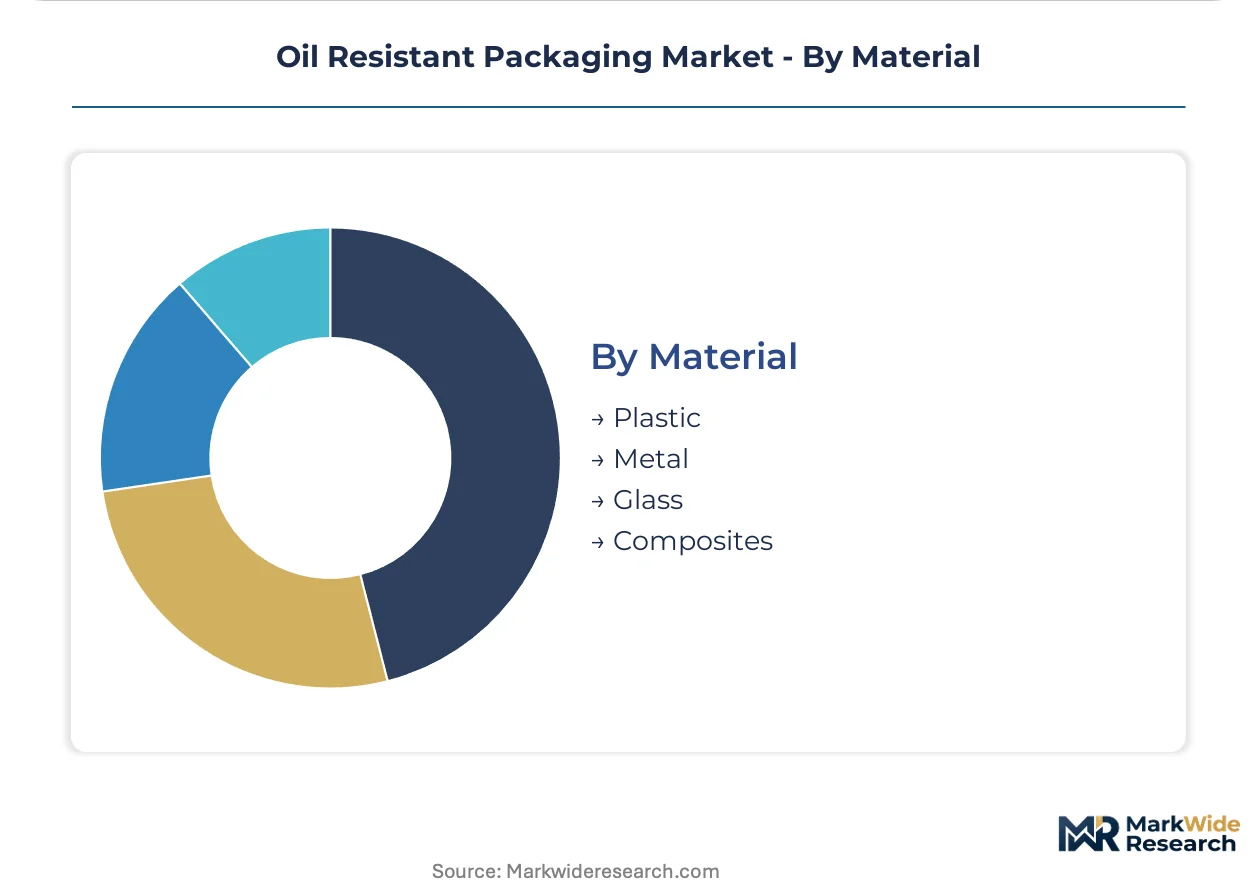
Material:
Substrate selection balances barrier performance, recyclability credentials, and regulatory compliance burden across regional regimes.
- Plastic:Polyethylene and polypropylene films dominate flexible formats due to established heat-seal reliability and reformulation flexibility as EPA restrictions eliminate legacy fluorochemical treatments.
- Metal:Aluminum laminates and cans provide absolute oil and oxygen barrier for premium edible oils and industrial lubricants where shelf life extension justifies material cost.
- Glass:Pharmaceutical and cosmetic oil-based formulations retain glass preference for inertness and premium positioning despite weight and fragility penalties.
- Composites:Multi-material structures combining plastic films with paperboard or aluminum face stranded inventory risk as EU Green Deal packaging and packaging waste regulation incentivizes mono-material alternatives.
Widest application coverage: Plastic. Steepest regulatory pressure: Composites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processed food manufacturing clusters in Germany, China, and the United States concentrate procurement of grease-proof packaging solutions at scale. Regulatory divergence between REACH Annex XVII in Europe and FDA food-contact rules in the United States shapes material qualification pathways. Extended producer responsibility mandates in multiple jurisdictions accelerate substrate reformulation timelines.
United States
Frozen and fried-food manufacturers in the Midwest and Southeast drive flexible pouch demand for portion-control applications. EPA per- and polyfluoroalkyl substance restrictions eliminate legacy C6 and C8 fluorochemical treatments from food-contact applications by 2027. Chicago and Atlanta processing clusters consolidate supplier relationships around blown film converters capable of dual-certification documentation.
Germany
Quick-service restaurant chains face single-use plastic bans that displace multilayer plastics with fiber-based oil-barrier solutions. EU Green Deal packaging and packaging waste regulation incentivizes mono-material structures with extended producer responsibility fee reductions. Hamburg and Munich quick-service supply chains qualify integrated bio-wax barrier grades for burger wraps and french fry cartons.
China
Processed food export manufacturers confront SAMR national food safety standards and GB migration limits that add compliance layers for imported packaging substrates. Yangtze River Delta and Pearl River Delta converters invest in mineral-oil-free barrier qualification to maintain European market access. Shanghai regulatory consultants specialize in dual-certified substrate documentation for cross-border food brands.
India
Yum Brands and Domino's localize supply chains as FSSAI food-contact compliance frameworks mature across quick-service expansion. Maharashtra and Karnataka food processing parks create virgin demand for certified oil-barrier paperboard. Mumbai converters partner with European substrate suppliers to accelerate qualification timelines for fried-food packaging formats.
France
Cosmetics and premium skincare brands specify oil-resistant folding cartons for formulations with botanical oils and silicone bases. REACH Annex XVII limitations on persistent organic pollutants compel reformulation of legacy barrier chemistries toward bio-wax alternatives. Lyon and Paris packaging design studios co-develop specifications with material scientists rather than sequential handoffs.
Oil Resistant Packaging Market Competitive Landscape
Strategic partnerships dominate the current landscape as converters secure compliant substrate allocation ahead of phased substance bans. The vendor base organizes around three tiers: integrated multinational film-to-package manufacturers, regional kraft paper specialists with certified recyclable grades, and blown film scale operators serving North American food-service channels. Two strategic archetypes have emerged—regulatory affairs specialists managing dual-certification complexity, and vertical integration players controlling barrier formulation through captive chemical supply. Competitive intensity concentrates on M&A activity targeting mineral-oil-free coating capabilities and capacity expansion in Indian quick-service supply chains.
Within the integrated multinational tier, Amcor leverages film-to-package manufacturing across multiple continents to anchor global supply relationships. Mondi exemplifies the European kraft paper specialist archetype through certified recyclable oil-barrier grades produced at scale. Berry Global occupies the North American blown film position competing through roll stock volume in food-service channels. These three represent distinct strategic postures rather than overlapping competitive territory—Amcor through geographic breadth, Mondi through fiber-based circularity credentials, and Berry Global through flexible format scale.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Berry Global |
| Huhtamaki |
| Sonoco |
| Zanders GmbH |
| Archroma |
| DuPont |
| Michelman |
| Others |
Value Network & Pricing Analysis
Quick-service restaurant chains consolidating vendor panels around dual-certified substrate suppliers are compressing converter margins while elevating pricing power for compliant material sources. This procurement concentration forces supply-side specialization and reshapes how barrier coatings are valued across regional regulatory regimes.
Pricing Analysis
High-volume polyethylene roll stock operates on thin margins while specialty bio-wax barrier grades capture premium spreads. Three-tier pricing structure separates REACH-certified premium substrates from standard FDA-compliant grades and economy mineral-oil-containing alternatives. Price differentiation hinges on dual-certification status and volume commitment scale. Cost compression in standard flexible formats is intensifying because blown film converters face forced reformulation timelines ahead of EPA substance restrictions.
Supply Chain Analysis
Specialized coating chemists in Germany, China, and the United States face tightening availability as qualification demand surges across converter operations. The supply chain draws from concentrated fluorochemical specialty producers, bio-wax agricultural feedstock suppliers, and integrated pulp-and-paper mills with captive barrier lines. Single-source vulnerability persists in legacy PFAS-based chemistry as EPA restrictions eliminate qualified suppliers. Distribution runs through regional converter hubs serving quick-service restaurant supply chains and frozen food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral-oil-free barrier coating capacity remains structurally constrained against surging qualification demand, propping pricing premiums for compliant substrate supply. This supply scarcity rewards early-mover investment in certified production lines.
For Market Incumbents: Acquire bio-wax formulation capabilities and dual-certified substrate production lines to anchor supplier relationships ahead of phased fluorochemical bans. Incumbents must defend against margin erosion from integrated paper mills by securing exclusive offtake agreements with quick-service restaurant chains. Capacity addition in India offers geographic diversification as FSSAI frameworks mature. For New Entrants and Emerging Players: The gap between premium dual-certified substrates and economy single-regulation grades creates entry space for mid-tier converters with targeted certification investment. New entrants should prioritize Indian quick-service supply chains where virgin demand outruns established supplier relationships. A white-label qualification service model serving smaller frozen food manufacturers offers accelerated revenue capture. For Investors and Strategic Acquirers: The window for entry favors mineral-oil-free coating specialists with existing laboratory validation infrastructure and regulatory affairs depth. Long-term viability rests on substrate suppliers capable of serving both European and North American compliance regimes without dual production lines. Watch for EPA enforcement acceleration against legacy fluorochemical treatments as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Wax Supply | Captures margin from agricultural feedstock through captive coating formulation for paperboard barriers. |
| Dual-Certification Capacity Expansion | Positions converters to serve REACH and FDA regimes simultaneously, reducing customer qualification burden. |
| Indian Quick-Service Supply Chain Localization | Aligns with Yum Brands and Domino's supply chain maturation under evolving FSSAI compliance frameworks. |
| Mineral-Oil-Free Formulation Acquisition | Accelerates barrier technology transition ahead of EPA per- and polyfluoroalkyl substance restrictions. |
| Mono-Material Structure Development | Qualifies for EU Green Deal extended producer responsibility fee reductions in European markets. |
Research Methodology
Document review covered regulatory filings from EPA and ECHA, trade association reports from FEFCO and FPA, and customs data on barrier-coated substrate imports, complemented by interviews with plant managers at blown film converters, procurement leads at quick-service restaurant supply chains, technical R&D directors at specialty chemical suppliers, and sustainability officers at frozen food manufacturers. Secondary validation drew from FDA food-contact substance notification databases, REACH Annex XVII restriction updates, and SAMR GB standard documentation. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Segment-level outputs across material type, packaging format, and end-use vertical were generated through the projection horizon using elasticity-adjusted demand curves. The analytical framework incorporated regulatory phase-in schedules, extended producer responsibility fee structures, and quick-service restaurant fiber-transition commitments as exogenous variables. CAGRs were derived from regression analysis against historical substitution patterns between fluorochemical and bio-wax barrier adoption.
Inputs from converter operations and regulatory consultants were available through the study window; gaps in real-time qualification timeline data from private-label frozen food manufacturers introduce uncertainty bands around near-term volume forecasts. Material deviation in EPA enforcement acceleration or REACH substance list expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Self-Adhesive Films Market