
 Painting Masking Tapes Market | 2026-2036
Painting Masking Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Painting Masking Tapes Market Analysis
Skilled adhesive-coating technicians is bifurcating the competitive landscape between precision manufacturers and commodity assemblers. 3M Company leverages its in-house resin synthesis capabilities to sustain premium positioning in automotive OEM channels. tesa SE anchors European supply through integrated film extrusion and slitting operations near Stuttgart.
Painting masking tapes are pressure-sensitive adhesive strips engineered with crepe-paper, vinyl, or PVC backings typically 50–150 micrometers thick, designed to mask surfaces during spray, brush, or powder-coating operations while releasing cleanly without adhesive transfer or substrate damage. Paper tape dominates home-improvement retail due to cost accessibility and biodegradability tailwinds, while specialty tape captures margin pools in aerospace and marine applications requiring temperature resistance above 120°C. Acrylic adhesive formulations are displacing rubber-based systems in industrial coatings as VOC regulations tighten across manufacturing geographies.
EPA rules on hazardous air pollutants from coating operations compel U.S. painters to specify low-VOC masking products, while REACH restrictions on phthalate plasticizers reshape PVC tape formulations across Europe. China's GB standards for indoor air quality in commercial buildings drive similar specification upgrades for interior painting contractors. Stakeholders must monitor adhesive chemistry transitions and regional certification divergence to align procurement and R&D portfolios.
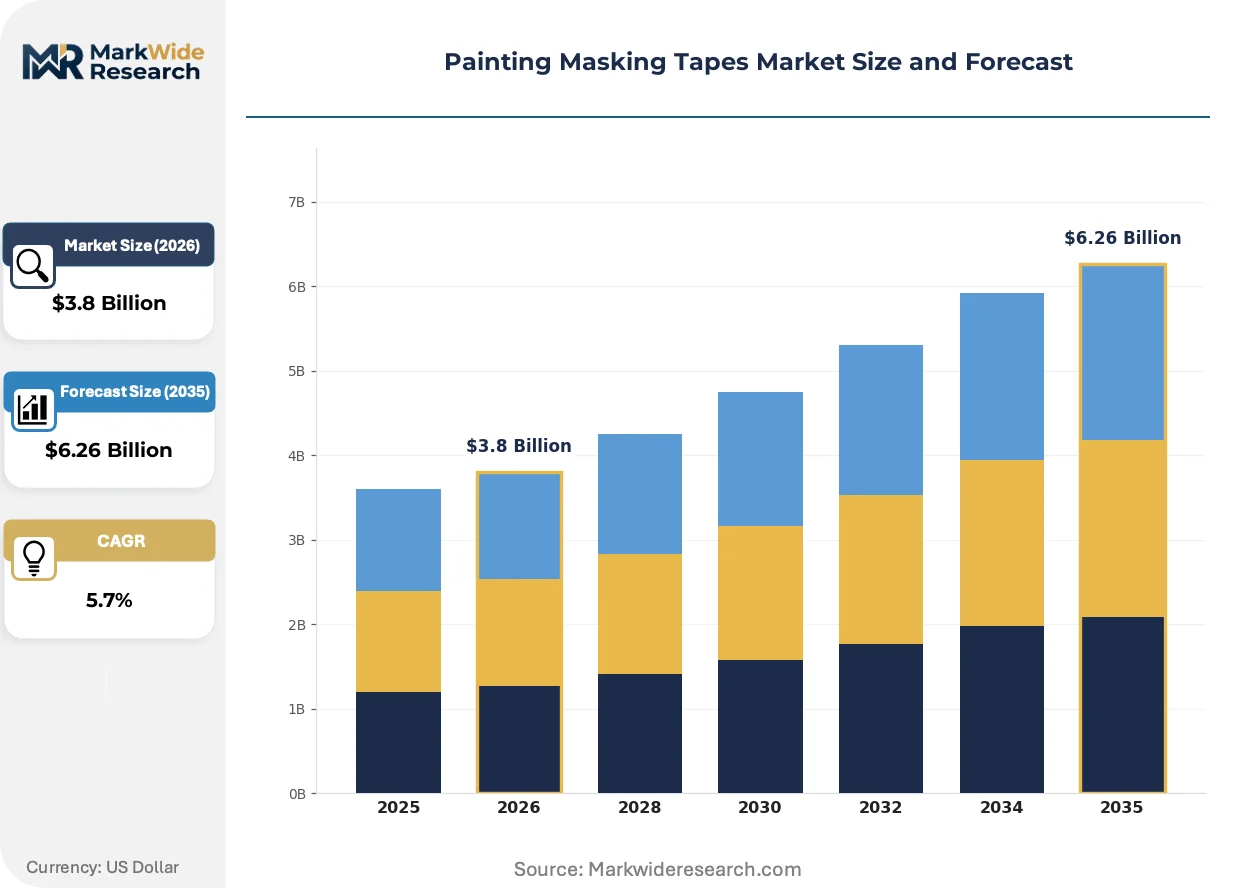
Market Dynamics
Acrylic adhesive chemistry is decomposing the established rubber-based tape hierarchy as VOC regulations harden across manufacturing geographies, forcing converters to rebuild coating lines around solvent-free platforms or exit industrial channels entirely.
Growth Catalysts
- REACH Phase-Down:ECHA restrictions on phthalate plasticizers in Europe are accelerating solvent-free acrylic tape qualification cycles among automotive OEM paint shops.
- EV Paint-Shop Investment:China's state-backed electric vehicle manufacturing subsidies are expanding precision masking tape consumption in robotic coating lines.
- OEM Color-Matching Standards:Tightening tolerances in automotive refinishing are elevating tape specification grades above commodity levels in North American collision repair networks.
Market Restraints
- Petrochemical Feedstock Volatility:PVC and polypropylene backing resin costs swing with naphtha cracking margins, compressing converter gross margins unpredictably.
- Adhesive Coater Concentration:Precision slot-die coating capability clusters in Germany, Japan, and the US Midwest, creating supply bottlenecks for qualified industrial-grade tape.
- Natural Rubber Substitution Ceiling:Acrylic formulations still fail at sub-zero release performance, limiting full displacement in cold-climate aerospace applications.
Strategic Opportunities
- India Infrastructure Build-Out:National highway and metro expansion projects are creating first-time specification demand for UV-resistant masking tapes in commercial painting contracts.
- Marine Coatings Specification:Salt-spray-resistant silicone-adhesive tapes for shipyard blasting operations remain underpenetrated relative to automotive and aerospace verticals.
- Biodegradable Paper Backing:EU Green Deal procurement mandates for construction materials are opening premium positioning for compostable crepe-paper formulations in renovation markets.
Industry Challenges
- Adhesive Formulation Chemist Scarcity:Solvent-free acrylic polymerization expertise concentrates among aging specialists in Stuttgart and Minneapolis coating clusters, constraining R&D velocity.
- Dual Certification Burden:Automotive OEMs now demand simultaneous AAMA 501.8 and OEM-specific clean-release testing, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Painting Masking Tapes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tape, Vinyl Tape, PVC Tape, Specialty Tape Application: Home Improvement, Automotive Refinishing, Industrial Coatings, Arts & Crafts Adhesive Type: Rubber Adhesive, Acrylic Adhesive, Hot Melt Adhesive, Others Thickness: Thin, Medium, Heavy Duty, Extra Thick |
| Companies Covered | Shurtape Technologies LLC, Berry Global Inc., 3M Company, Scapa Group PLC, tesa SE, Saint-Gobain Performance Plastics Corporation, Intertape Polymer Group Inc., Avery Dennison Corporation, Nitto Denko Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Painting Masking Tapes Market Emerging Trajectories
Coating automation and regulatory chemistry are converging to restructure tape value chains, with precision manufacturers capturing margin pools that commodity assemblers cannot access.
Waterborne acrylic emulsion adhesives are decomposing solvent-based rubber formulations in industrial masking applications. Automotive OEM paint shops in Stuttgart and Detroit are completing platform conversions. The technology is decomposing incumbent converter margins by 15-20 points while enabling premium pricing for qualified suppliers.
EPA National Emission Standards for Hazardous Air Pollutants are compelling US coating contractors to specify low-VOC masking products or face permit revocation. Industrial painters in Michigan and Ohio are now rejecting uncertified tape shipments. The rule is compressing distributor inventories toward pre-qualified SKUs.
Direct specification relationships between automotive OEM paint engineers and tape converters are displacing distributor-mediated procurement in North America. Tier-1 coating shops now contract adhesive coaters for custom width and release-force tuning. The shift concentrates purchasing power among Detroit, Wolfsburg, and Toyota City manufacturing clusters.
Painting Masking Tapes Market Segmentation
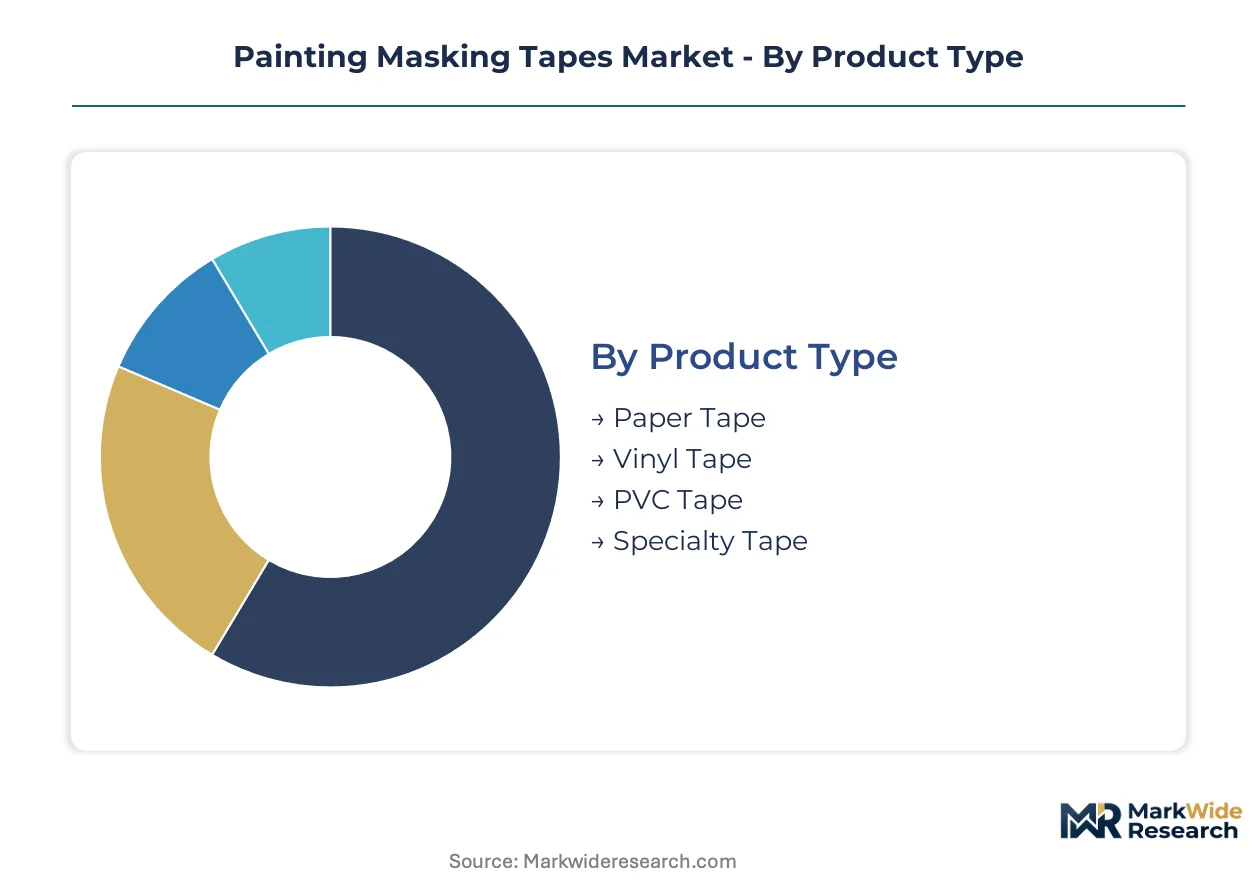
Segmentation in painting masking tapes reveals divergent margin structures across material platforms and end-use specifications. Understanding these fault lines exposes where converters capture value versus where price competition erodes returns.
Product Type:
Paper tape dominates domestic consumption in renovation-heavy economies, while vinyl and specialty grades concentrate in export-led industrial supply chains.
- Paper Tape:Crepe-paper backing with rubber or acrylic adhesive dominates home-improvement retail in the United States and Germany. Biodegradability tailwinds under EU Green Deal procurement rules are elevating specification grades in French and Dutch renovation contracts.
- Vinyl Tape:PVC-backed construction with solvent-based adhesive systems serves automotive refinishing shops requiring clean release on curved body panels. Stuttgart-area OEM paint shops specify vinyl grades for robotic tape-dispensing lines.
- PVC Tape:Thicker calendered PVC backings with plasticizer-stabilized adhesives face REACH phase-down pressure across European industrial channels.
- Specialty Tape:Silicone-adhesive and polyimide-backed systems for aerospace and marine applications command premium positioning in Japan and South Korea.
Paper tape holds the largest share; momentum sits with specialty grades as temperature resistance specifications tighten.
Application:
Volume concentrates in home improvement, but margin pools cluster in automotive and industrial coatings where certification barriers filter competition.
- Home Improvement:DIY renovation and contractor painting in the United States and Western Europe drives commodity-grade paper tape consumption through hardware retail channels. Price sensitivity limits converter margins to single digits.
- Automotive Refinishing:Collision repair networks in Michigan and Wolfsburg specify precision-cut tapes for color-matching tolerance compliance. OEM certification requirements extend qualification timelines to 18-24 months.
- Industrial Coatings:Powder-coating and spray operations in China's EV manufacturing hubs demand UV-resistant and high-temperature masking solutions.
- Arts & Crafts:Low-specification decorative masking serves hobbyist and educational markets with minimal adhesive performance requirements.
Home improvement generates the highest volume; automotive refinishing delivers the steepest expansion trajectory as OEM standards proliferate.
Adhesive Type:
Chemistry transitions are restructuring competitive positioning, with solvent-free platforms displacing legacy formulations in regulated geographies.
- Rubber Adhesive:Natural and synthetic rubber-based solvent systems retain cost advantage in cold-climate aerospace applications where sub-zero release performance remains critical.
- Acrylic Adhesive:Waterborne emulsion and solvent-free UV-cured acrylics are capturing industrial specification in Stuttgart, Detroit, and Shanghai as VOC regulations harden. Coating line conversion costs filter out commodity assemblers.
- Hot Melt Adhesive:Synthetic rubber and EVA-based hot melts serve high-speed automated taping equipment in automotive assembly plants.
- Others:Silicone and hybrid adhesive systems address niche temperature extremes above 150°C in aerospace engine masking.
Rubber adhesive retains volume leadership; acrylic formulations are gaining share fastest as regulatory chemistry transitions accelerate.
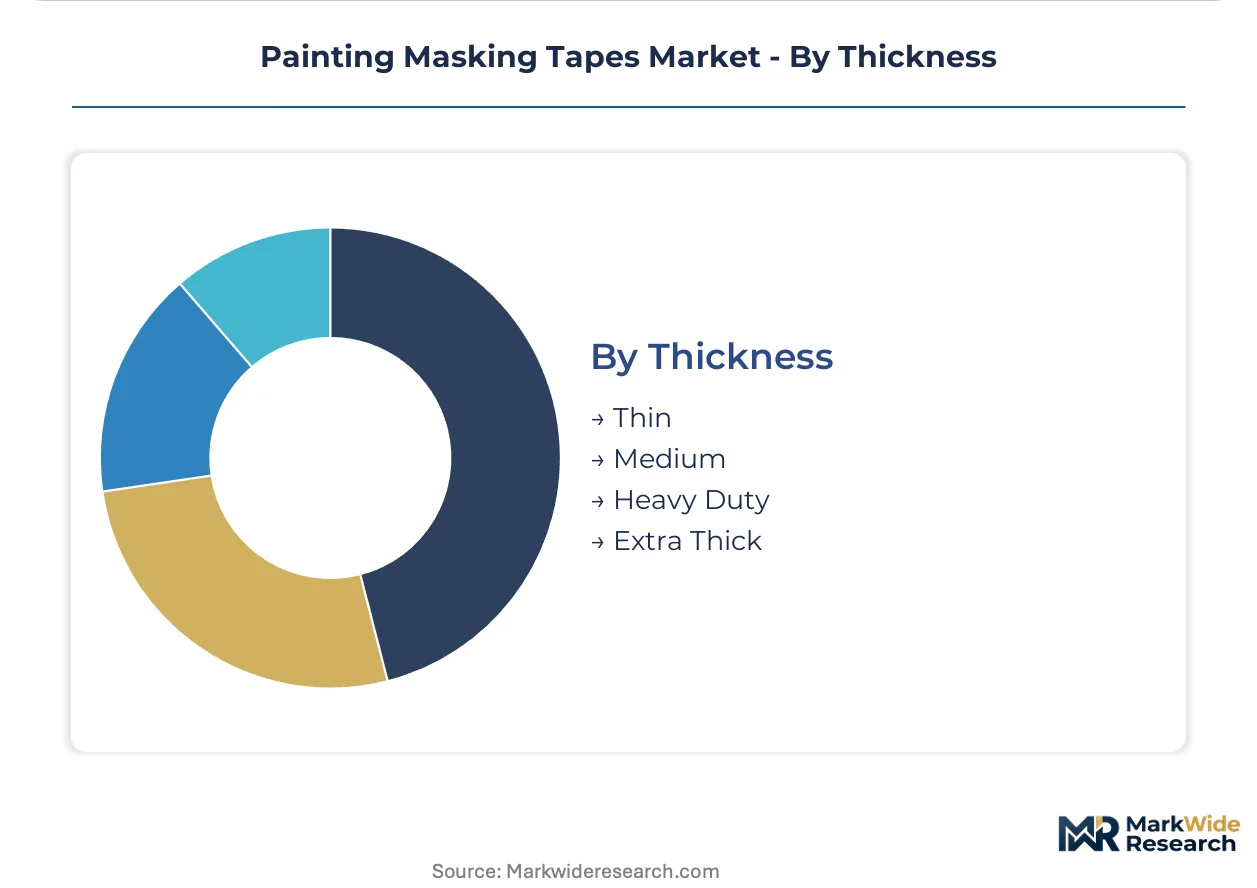
Thickness:
Specification grade correlates directly with end-use performance requirements and pricing tier.
- Thin:50-75 micrometer backings serve precision electronics masking and fine-line automotive detailing.
- Medium:75-100 micrometer constructions balance conformability and handling in general industrial painting.
- Heavy Duty:100-125 micrometer grades withstand aggressive blasting and high-build coating operations in shipyards.
- Extra Thick:125-150 micrometer specialty backings absorb severe mechanical stress in aerospace composite manufacturing.
Medium thickness dominates unit volume; extra thick commands the highest per-meter pricing as qualification barriers concentrate supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes painting masking tapes through EV paint-shop automation, while the United States and Germany drive specification-grade demand through collision repair networks and OEM certification programs.
China
State-backed electric vehicle manufacturing subsidies are expanding precision masking tape consumption in robotic coating lines across Shanghai and Guangzhou. GB standards for indoor air quality in commercial buildings drive specification upgrades for interior painting contractors. Yangtze River Delta manufacturing clusters anchor solvent-free acrylic adhesive platform adoption among domestic converters.
United States
EPA National Emission Standards for Hazardous Air Pollutants compel coating contractors to specify low-VOC masking products or face permit revocation. Collision repair networks in Michigan and Ohio now reject uncertified tape shipments. Detroit-area OEM paint engineers contract directly with adhesive coaters for custom width and release-force tuning.
Germany
ECHA restrictions on phthalate plasticizers accelerate solvent-free acrylic tape qualification cycles among automotive OEM paint shops. Stuttgart-area OEM paint shops specify vinyl grades for robotic tape-dispensing lines. Baden-Württemberg coating clusters concentrate precision slot-die coating capability that filters out commodity assemblers.
Japan
Silicone-adhesive and polyimide-backed systems for aerospace and marine applications command premium positioning in Nagoya and Osaka manufacturing basins. METI industrial standards shape adhesive chemistry transitions in precision electronics masking. Kanto region coating specialists serve temperature resistance specifications above 150°C for aerospace engine applications.
India
National highway and metro expansion projects create first-time specification demand for UV-resistant masking tapes in commercial painting contracts. BIS certification requirements for construction materials elevate procurement standards in infrastructure tenders. Maharashtra and Gujarat industrial corridors attract adhesive coater investments serving domestic automotive assembly plants.
Painting Masking Tapes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with tape converters stratifying between precision manufacturers with in-house resin synthesis and commodity assemblers sourcing adhesive from merchant suppliers. The competitive landscape separates players by coating line capability, with solvent-free acrylic qualification determining access to automotive OEM channels. Three archetypes dominate: integrated chemical-resin-to-tape manufacturers, regional converters with captive film extrusion, and distributor-assemblers without coating assets. Capacity expansion in solvent-free coating lines and strategic partnerships with automotive paint-shop equipment vendors represent the dominant competitive moves reshaping supply relationships.
Within the integrated leader tier, 3M Company and tesa SE exemplify the resin-synthesis-to-tape model that sustains premium positioning in automotive OEM channels. Among North American fabricators, Shurtape Technologies LLC and Intertape Polymer Group Inc. occupy positions serving contractor-grade demand through hardware retail distribution. Japanese specialists including Nitto Denko Corp anchor high-temperature aerospace and electronics masking applications where silicone-adhesive expertise creates qualification barriers.
| Leading Market Players |
|---|
| Shurtape Technologies LLC |
| Berry Global Inc. |
| 3M Company |
| Scapa Group PLC |
| tesa SE |
| Saint-Gobain Performance Plastics Corporation |
| Intertape Polymer Group Inc. |
| Avery Dennison Corporation |
| Nitto Denko Corp |
| Others |
Supply Flow & Price Mechanics
Acrylic adhesive chemistry replacing rubber-based formulations across automotive OEM channels simultaneously concentrates supply geography around Stuttgart, Detroit, and Shanghai coating clusters while compressing margins for converters lacking solvent-free platform qualification. Buyers now face bifurcated sourcing economics where certified precision manufacturers command premium positioning while commodity assemblers compete on resin cost arbitrage.
Pricing Analysis
Long-term offtake contracts dominate automotive OEM procurement, with Detroit and Wolfsburg paint shops locking in 18-24 month supply agreements for custom-width tape specifications. Price differentiation rests on REACH certification tier and in-house resin synthesis capability, with solvent-free acrylic platforms sustaining 15-20 point margin premiums over rubber-based alternatives. Cost compression in commodity paper tape is intensifying as Chinese converters expand capacity for home-improvement retail. DIY renovation contractors exhibit highest price sensitivity, while aerospace specification buyers prioritize temperature performance over unit cost.
Supply Chain Analysis
Inventory lead times for industrial-grade precision tape extend 12-16 weeks due to slot-die coating capacity concentration in Germany, Japan, and the US Midwest. Supply draws from naphtha-derived PVC and polypropylene resin feedstocks, acrylic monomer streams, and specialty silicone polymers for high-temperature grades. Single-source vulnerability concentrates in Stuttgart-area coating clusters where ECHA regulatory expertise and precision equipment co-locate. Distribution runs through direct converter-OEM relationships in automotive channels and hardware retail networks for home improvement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvent-free adhesive platform economics are restructuring procurement relationships around specification interoperability, as automotive OEMs demand simultaneous AAMA 501.8 and proprietary clean-release testing that only integrated resin-to-tape manufacturers can satisfy.
For Market Incumbents: Fortify solvent-free acrylic coating capacity in Baden-Württemberg and Michigan industrial corridors to defend against merchant adhesive suppliers entering automotive qualification channels. Prioritize backward integration into UV-cured polymerization to capture margin pools escaping commodity assemblers. Extend certification investment timelines to filter out capital-constrained competitors seeking fast-track OEM approval. For New Entrants and Emerging Players: Custom release-force tuning services for robotic tape-dispensing equipment represent an underserved layer where incumbent distributors lack technical depth. Marine coatings specification for salt-spray-resistant silicone tapes offers the most penetrable vertical given lower qualification barriers versus automotive. Pursue direct equipment partnership strategies with Yangtze River Delta EV paint-shop automation vendors to bypass established distribution. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with captive film extrusion and existing REACH certification rather than greenfield coating assets requiring 24-month qualification cycles. Five-to-ten year viability favors players with demonstrated OEM paint-engineer relationships over distributor-assemblers facing margin compression. Watch for ECHA expansion of phthalate restrictions to signal accelerated acrylic platform conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Line Conversion | REACH Phase-Down compliance unlocks automotive OEM procurement channels in Stuttgart and Wolfsburg. |
| Direct OEM Paint-Shop Contracting | Detroit-area manufacturers bypass distributor markups through custom specification relationships. |
| Biodegradable Paper Backing Development | EU Green Deal procurement mandates create premium positioning in French and Dutch renovation. |
| Marine Coatings Specification Push | Shipyard blasting operations in Nagoya and Osaka remain underpenetrated relative to automotive verticals. |
| India Infrastructure Supply Partnership | Maharashtra highway tenders create first-time UV-resistant tape specification demand. |
Methodological Framework
Desk research of ECHA regulatory filings, EPA National Emission Standards documentation, and automotive OEM paint-shop equipment specifications preceded structured interviews with adhesive coating line engineers, automotive procurement managers, and hardware retail category buyers. Secondary validation drew from customs trade data for PVC and acrylic monomer flows, SEC filings of integrated tape manufacturers, and BIS certification records for Indian construction materials. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across product type, adhesive chemistry, application vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Forecast inputs included EV paint-shop automation deployment rates, REACH compliance timeline scenarios, and naphtha cracking margin volatility patterns.
Underlying assumptions cover sustained ECHA regulatory enforcement, continued Chinese state-backed EV manufacturing subsidies, and stable naphtha feedstock availability, with deviation risk concentrated in phthalate restriction acceleration and cold-climate aerospace substitution ceilings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
India Reflective Tapes Market
Tapes
Raffia Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Shipping Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Security Tape Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Flocking Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Invisible Tapes Market