
 Heat Transfer Films Market | 2026-2036
Heat Transfer Films Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Transfer Films Market Outlook
The heat transfer films industry is pivoting between premium performance grades and commodity vinyl tiers as brand owners split procurement between certified automotive specifications and price-driven textile decoration. Avery Dennison Corporation leverages its materials science heritage to dominate durable automotive interior applications. Stahls' Inc. anchors the North American service provider channel with vertically integrated heat press equipment and consumable film systems. Siser SRL specializes in craft and mid-market textile segments, competing on color breadth and ease-of-weeding formulations.
Heat transfer films are polymer-based decorative substrates, typically 50-250 microns in thickness, engineered with release coatings and hot-melt or pressure-sensitive adhesive layers that bond to textiles, plastics, and metal surfaces under controlled temperature and pressure. Their primary commercial purpose is to enable durable graphic application without direct screen printing infrastructure, reducing setup waste and supporting short-run customization. Polyester films lead in electronics and automotive applications where dimensional stability under thermal cycling commands margin premiums, while vinyl formulations dominate textile decoration volumes through screen printing and heat press technologies. Digital printing transfer films represent the fastest-expanding technology segment as direct-to-garment workflows displace analog setups in on-demand fulfillment.
REACH restrictions on phthalate plasticizers and heavy metal pigments constrain European formulation choices, while EPA and state-level PFAS regulations in the United States pressure fluorinated release coatings. China's GB standards on volatile organic compound emissions from adhesive films shape export compliance requirements for converters in Zhejiang and Jiangsu provinces. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid stranded inventory in cross-border textile and automotive supply chains.
Market Dynamics
Digital-ready heat transfer films are compressing order minimums and turnaround times, forcing converters to retool coating lines for shorter runs while automotive specifications demand thicker, dimensionally stable polyester grades that resist thermal cycling.
Growth Catalysts
- REACH phthalate restrictions:ECHA's tightening limits on plasticizer migration are accelerating water-based adhesive adoption across European textile decoration supply chains.
- On-demand fulfillment infrastructure:Direct-to-garment workflows in North American e-commerce are pulling digital transfer film volumes beyond screen-print replacement rates.
- Guangdong converter density:China's Pearl River Delta clusters achieve 48-hour global shipping windows that lock in apparel brand procurement decisions.
Market Restraints
- Petrochemical input volatility:Polyester resin and vinyl chloride monomer prices swing with crude oil indices, compressing converter margins on fixed-price contracts.
- Fluorinated release coating dependency:EPA and state-level PFAS regulations threaten supply continuity for premium easy-weede formulations.
- Dimensional stability thresholds:Automotive interior specifications require sub-0.5% shrinkage under 150°C thermal cycling, disqualifying commodity vinyl grades.
Strategic Opportunities
- India apparel export manufacturing:Tirupur and Surat clusters lack captive transfer film coating capacity, creating import substitution openings for solvent-free chemistries.
- Recyclable mono-material constructions:Single-polyester-layer designs without adhesive interlayers align with EU Green Deal circular economy mandates.
- Equipment-film bundling:Heat press OEMs in Mexico and Vietnam seek captive consumable supply to replicate Stahls' North American service model.
Industry Challenges
- Color matching across substrate batches:Pigment dispersion consistency varies between water-based and solvent coating lines, forcing manual QC intervention.
- Dual certification timelines:Automotive IATF 16949 and textile OEKO-TEX Standard 100 audits require parallel documentation systems that strain mid-cap converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Transfer Films Market |
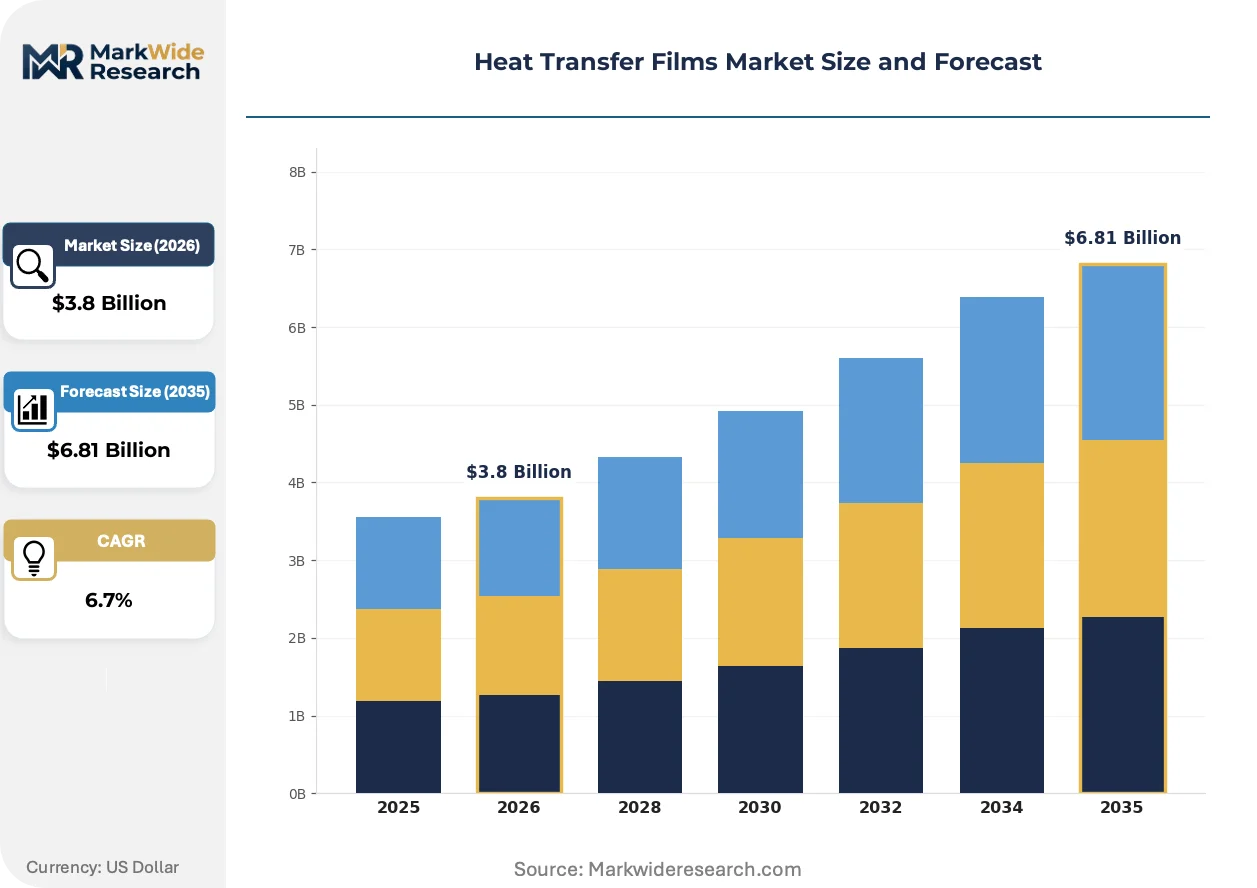
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, Vinyl, Others Application: Textiles, Packaging, Consumer Electronics, Automotive End User: Manufacturers, Retailers, Service Providers, Aftermarket Technology: Digital Printing, Screen Printing, Transfer Printing, Heat Press |
| Companies Covered | Avery Dennison Corporation, Stahls' Inc., Hexis S.A.S., Siser SRL, Chemica US Corp, 3M Company, Orafol Europe GmbH, MHM Holding GmbH, Specialty Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Transfer Films Market Strategic Shifts
Formulation chemistry and application hardware are advancing in lockstep, with coating developers racing to deliver films that print, cut, and transfer on equipment designed for narrower process windows than analog predecessors tolerated.
Laser-contour cutting systems are converging with printable heat transfer films to eliminate mechanical weeding entirely. Sportswear decorators in Germany and California are adopting these integrated workflows for single-piece fulfillment. This convergence is compressing labor content per order and enabling same-day production economics that screen printing cannot match.
EPA's proposed PFAS reporting rule under TSCA Section 8(a)(7) is forcing reformulation of fluorinated release liners. Coating houses in Ohio and South Carolina are testing silicone-based alternatives that sacrifice some weeding speed for regulatory certainty. Textile decoration segments with thinner margin structures face the steepest compliance cost absorption.
Brand procurement teams are unbundling film specification from equipment purchase decisions, reversing decade-old bundled supply contracts. Mid-market apparel decorators in Bangladesh and Turkey now source films from Chinese converters while leasing European heat press hardware. This fragmentation is visible most acutely in sportswear verticals where design turnover cycles have compressed from seasonal to weekly rhythms.
Heat Transfer Films Market Segmentation
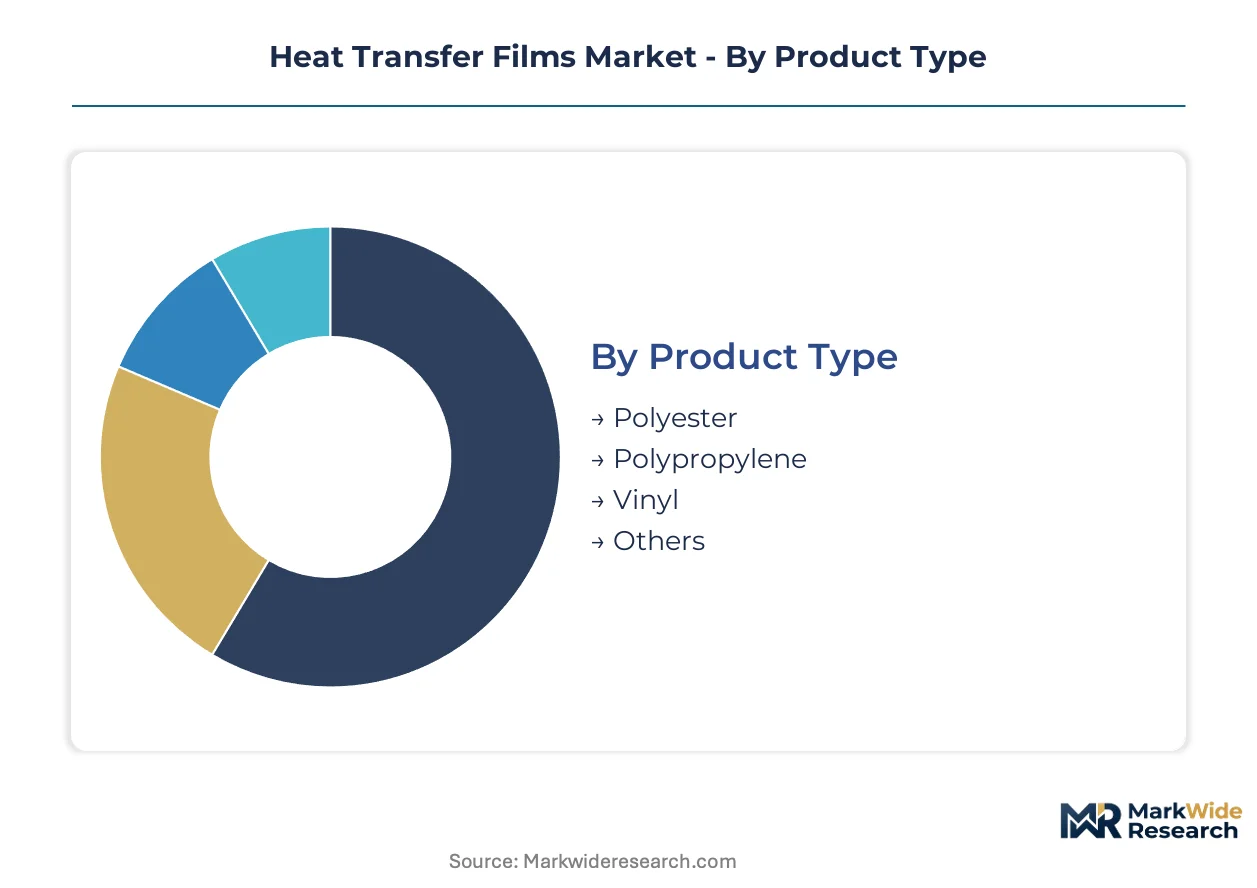
Heat transfer films serve divergent performance requirements across textile decoration, automotive interiors, and electronics assembly. Segmentation reveals how formulation chemistry and application hardware must align to capture margin premiums in certified specifications versus commodity volumes.
Product Type:
Upgrade cycles in automotive and electronics are displacing commodity vinyl with dimensionally stable engineered films that survive thermal cycling.
- Polyester:Thermoplastic polymer films deliver sub-0.5% shrinkage under 150°C thermal stress. Automotive interior specifications in Germany and Japan command premium pricing for heat-stabilized grades that resist dashboard thermal loading.
- Vinyl:Polyvinyl chloride formulations dominate textile decoration through cost-efficient calendering and broad color gamut compatibility. Bangladesh and Vietnam apparel decorators source commodity vinyl from Guangdong converters for price-driven sportswear runs.
- Polypropylene:Lower density olefin films serve packaging and disposable textile applications where heat resistance requirements remain modest.
- Others:Specialty fluoropolymer and polyurethane films address niche electronics shielding and medical textile applications with chemical resistance demands.
Volume placements concentrate in vinyl; the faster expansion belongs to polyester.
Application:
Cost tiers separate certified automotive specifications from price-sensitive textile decoration, with equipment bundling decisions following application margins.
- Textiles:Apparel decoration consumes the largest film volumes through direct-to-garment workflows and heat press transfer systems. Tirupur and Surat clusters in India drive import demand for solvent-free chemistries that meet EU brand compliance requirements.
- Automotive:Interior trim applications require IATF 16949 certification and thermal cycling validation that disqualifies commodity grades. Tier-1 suppliers in Michigan and Stuttgart specify polyester films with automotive-grade release liners.
- Consumer Electronics:Device branding and membrane switch overlays demand precise dimensional stability for automated assembly lines in Shenzhen and Seoul.
- Packaging:Promotional labeling and flexible packaging decoration utilize thinner films with lower adhesive coat weights for cost containment.
Textiles generate the highest absolute volumes; automotive specifications capture the steepest margin expansion trajectory.
End User:
Customer type determines procurement sophistication, from specification-driven OEMs to price-sensitive service bureaus.
- Manufacturers:Apparel and automotive OEMs specify films through approved vendor lists with locked formulation requirements. Vertical integration pressures are strongest at this tier.
- Service Providers:Independent decorators and fulfillment centers prioritize digital-ready films compatible with leased heat press equipment. California and North Rhine-Westphalia sportswear decorators compress turnaround times through on-demand workflows.
- Retailers:Corporate merchandise and private label programs source films through consolidated procurement platforms with sustainability scorecards.
- Aftermarket:Vehicle customization and repair segments tolerate wider specification variance for short-run graphic replacement.
Service providers drive volume velocity; manufacturers anchor premium pricing tiers.
Technology:
Application method maturity curves separate analog legacy infrastructure from digital displacement economics.
- Digital Printing:Inkjet-receptive films with specialized topcoats enable single-piece fulfillment without screen setup waste. E-commerce decorators in North America are pulling digital transfer film volumes beyond replacement rates for analog equipment.
- Screen Printing:Conventional mesh-based application dominates high-volume textile runs with established color matching protocols. Bangladesh and Turkey mid-market decorators maintain screen infrastructure for seasonal volume surges.
- Transfer Printing:Sublimation-compatible films serve polyester textile decoration with dye migration control requirements.
- Heat Press:Mechanical transfer systems bridge multiple film chemistries, with equipment OEMs in Mexico and Vietnam seeking captive consumable supply arrangements.
Screen printing retains volume dominance; digital printing climbs the fastest through on-demand infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province's Pearl River Delta anchors global heat transfer film production, with converter clusters in Dongguan and Shenzhen achieving 48-hour shipping windows to apparel supply chains worldwide.
United States
California and North Carolina sportswear decorators drive digital transfer film adoption through on-demand fulfillment workflows. EPA's proposed PFAS reporting rule under TSCA Section 8(a)(7) pressures reformulation of fluorinated release coatings. Ohio and South Carolina coating houses test silicone-based alternatives to maintain regulatory compliance.
Germany
Automotive interior specifications from Stuttgart-based Tier-1 suppliers command premium pricing for heat-stabilized polyester grades. REACH phthalate restrictions enforced by ECHA accelerate water-based adhesive adoption across textile decoration supply chains. Bavarian industrial zones host precision coating operations serving European OEM approved vendor lists.
China
Zhejiang and Jiangsu province converters shape export compliance requirements through GB standards on volatile organic compound emissions from adhesive films. Guangdong's dense converter clusters supply Bangladesh and Vietnam apparel decorators with commodity vinyl volumes. Shanghai and Beijing-based brand procurement offices increasingly unbundle film specification from equipment purchases.
India
Tirupur and Surat textile clusters lack captive transfer film coating capacity, creating import substitution openings for solvent-free chemistries. BIS standards on adhesive film emissions align with EU brand compliance requirements for export manufacturing. Maharashtra and Gujarat-based converters explore partnerships to replicate Chinese scale economics.
Vietnam
Ho Chi Minh City and Hanoi apparel export zones pull transfer film volumes as manufacturing shifts from China. Local heat press OEMs seek captive consumable supply arrangements to replicate North American service models. Da Nang and Hai Phong industrial parks attract coating line investments targeting ASEAN regional distribution.
Heat Transfer Films Market Competitive Environment
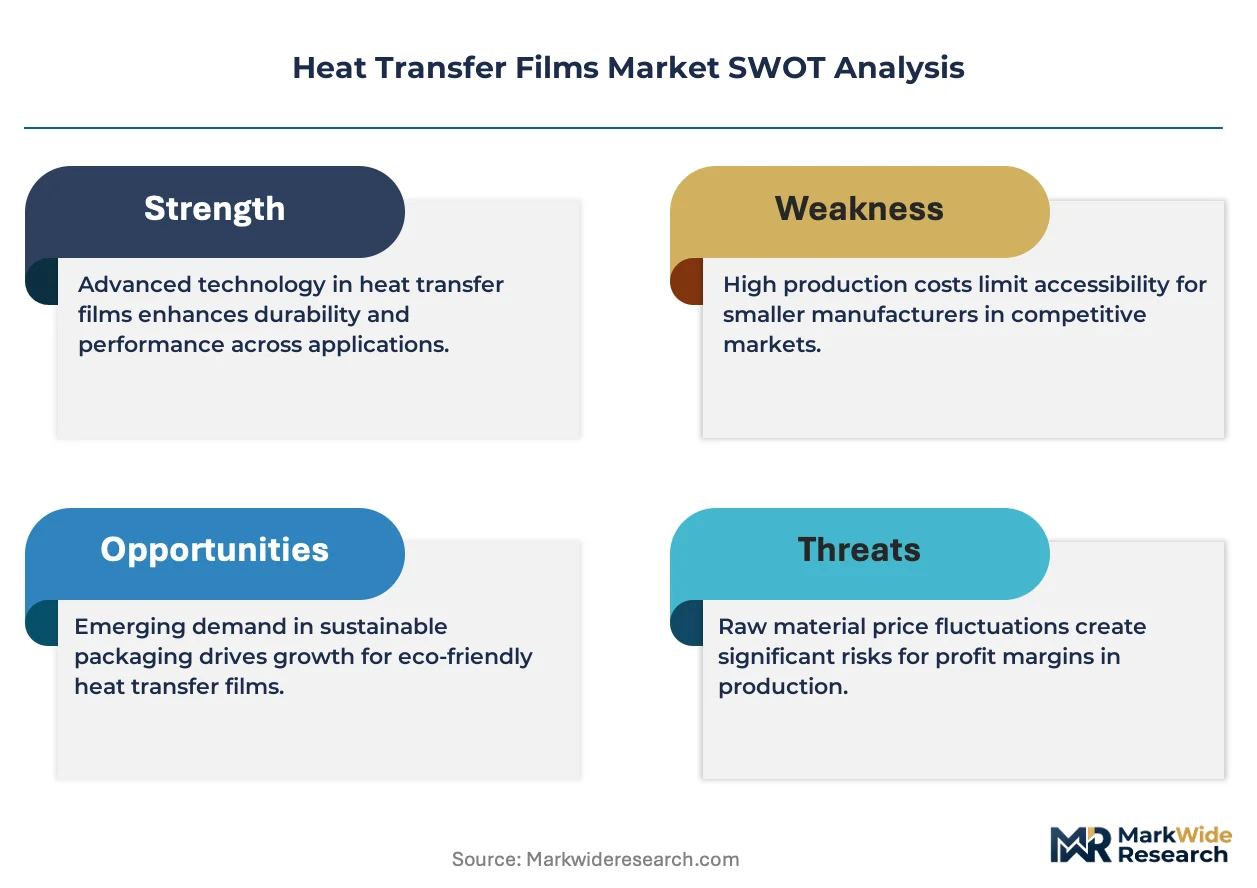
Premium-margin players sit above commodity-margin players across certification tiers, with automotive-grade polyester specifications capturing 3-4x the margin of textile decoration vinyl. The vendor base organizes into three strategic archetypes: materials science conglomerates with automotive heritage, vertically integrated equipment-film bundlers, and specialized craft-market formulators. Dominant competitive moves include geographic expansion into India and Vietnam manufacturing zones, plus backward integration into coating resin production to hedge petrochemical input volatility.
Within the materials science tier, Avery Dennison Corporation and 3M Company occupy positions anchored by automotive interior specifications and electronics assembly applications. Stahls' Inc. exemplifies the vertically integrated archetype, bundling heat press equipment with consumable film systems across North American service provider channels. Siser SRL represents specialized craft-market positioning, competing on color breadth and ease-of-weeding formulations for mid-market textile segments.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Stahls' Inc. |
| Hexis S.A.S. |
| Siser SRL |
| Chemica US Corp |
| 3M Company |
| Orafol Europe GmbH |
| MHM Holding GmbH |
| Specialty Materials |
| Others |
Value Chain & Pricing Dynamics
Coating line engineers clustered in Guangdong Province's Pearl River Delta generate labor-cost differentials that widen spreads between automotive-grade polyester specifications and commodity vinyl tiers. Textile decorators in Bangladesh and Vietnam absorb price premiums for REACH-compliant water-based formulations that European brand procurement mandates require.
Pricing Analysis
Throughput-based pricing anchors automotive interior specifications, where Tier-1 suppliers in Stuttgart and Michigan contract for heat-stabilized polyester grades validated to sub-0.5% shrinkage thresholds under thermal cycling. Three-tier pricing structure across IATF 16949-certified automotive, OEKO-TEX Standard 100 textile, and uncertified craft segments separates margin capture by certification burden. Cost compression in commodity vinyl runs through fixed-price contract exposure to vinyl chloride monomer volatility. Service providers leasing heat press equipment in California and North Rhine-Westphalia exhibit highest price sensitivity; automotive OEMs with locked approved vendor lists show lowest.
Supply Chain Analysis
India's domestic-content push under the PLI scheme for textiles reshapes sourcing patterns for Tirupur and Surat apparel clusters seeking captive coating capacity. Raw material flows draw from Saudi petrochemical complexes for polyester resin, Louisiana vinyl chloride monomer production, and Chinese adhesive polymer supply. Single-source vulnerability concentrates in fluorinated release coating formulations threatened by EPA TSCA Section 8(a)(7) reporting requirements. Distribution runs through Guangdong converter clusters achieving 48-hour global shipping windows to Bangladesh and Vietnam apparel supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating line capacity scarcity in India and Vietnam props pricing premiums for solvent-free chemistries that EU brand compliance requirements mandate. Qualified converter capacity expansion lags demand pull from on-demand fulfillment infrastructure buildout.
For Market Incumbents: To counter unbundling of film specification from equipment purchase decisions, Avery Dennison and 3M should deepen backward integration into heat-stabilized polyester resin production and lock in IATF 16949 certification renewal cycles with Stuttgart-based Tier-1 suppliers. Channel control through approved vendor list maintenance remains the priority lever against mid-market Chinese converter encroachment. For New Entrants and Emerging Players: Laser-contour cutting system compatibility offers the most penetrable technology wedge for German and California sportswear decorators seeking same-day production economics. White-space targets include solvent-free chemistry coating lines in Maharashtra and Gujarat to serve Tirupur export manufacturing, plus equipment-film bundling partnerships with Mexican and Vietnamese heat press OEMs replicating the Stahls' service model. Go-to-market positioning should emphasize digital-ready film formulations compatible with leased narrow-process-window equipment. For Investors and Strategic Acquirers: The window for entry favors coating specialists with GB standards compliance and EU REACH certification documentation already filed. Long-term viability over the next decade hinges on mono-material recyclable construction capabilities aligned with EU Green Deal circular economy mandates. Watch for silicone-based release coating formulation validation as the inflection signal for fluorinated chemistry replacement economics tipping toward regulatory certainty.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Resin | Insulates margin compression from vinyl chloride monomer price swings in Louisiana and Saudi supply. |
| Water-Based Adhesive Capacity Expansion | Captures ECHA-enforced formulation shifts across European textile decoration supply chains. |
| Laser-Contour Cutting System Partnership | Locks in digital decorator workflows in California and North Rhine-Westphalia sportswear verticals. |
| GB Standards Compliance Certification | Enables Zhejiang and Jiangsu province converters to maintain Bangladesh and Vietnam apparel export access. |
| Mono-Material Recyclable Construction R&D | Aligns single-polyester-layer designs with EU Green Deal circular economy procurement scorecards. |
Study Parameters
Independent corroboration across coating plant managers in Guangdong and Zhejiang provinces, procurement leads at Stuttgart automotive Tier-1 suppliers, and distribution channel partners serving Bangladesh apparel decorators underwrites the qualitative findings. Primary interviews with technical R&D directors at adhesive formulators, heat press equipment OEMs in Mexico, and EU brand sustainability officers combined with secondary validation from customs/trade data, SEC 10-K filings of materials science conglomerates, and ECHA REACH restriction updates. Bottom-up volume triangulation across converter clusters and top-down value estimation from automotive specification premiums anchored the market sizing.
Rate-of-change decomposition across the analysis window separated volume growth in digital-ready films from value expansion in automotive-grade polyester specifications. Segmentation dimensions modeled include product chemistry tier, end-use application margin structure, certification level, and regional production hub concentration. CAGRs derived from fitted growth curves applied to converter capacity expansion timelines and e-commerce fulfillment infrastructure buildout rates. Industry-specific forecast inputs incorporated GB standards enforcement trajectories in China and EPA PFAS regulatory pathway probabilities.
Several conditions sit outside the modeled scope, including sudden petrochemical input price shocks, accelerated PFAS ban implementations beyond proposed TSCA rules, and trade policy disruptions affecting Guangdong export channels. Forecasts reflect assumptions regarding coating line utilization rates and brand procurement unbundling velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market