
 Paper Slitting Machine Market | 2026-2036
Paper Slitting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Slitting Machine Market Analysis
Automated tension control and servo-driven knife positioning is reshaping how paper slitting systems deliver finished roll quality. Kampf Schneid- und Wickeltechnik GmbH & Co. KG anchors German engineering standards across European packaging lines. Parkinson Technologies, Inc. dominates North American installations through its specialized web handling expertise. ASHE Converting Equipment leverages modular designs to compete across mid-volume conversion operations.
A paper slitting machine cuts large parent rolls into narrower strips using rotary, shear, or band knife configurations, operating at web speeds up to 1,500 meters per minute with slit widths ranging from 20 millimeters to several meters for downstream packaging and printing processes. Rotary slitters occupy the largest installed base due to versatility across paper grades, while fully automatic systems capture expanding margin pools as labor costs rise in European and North American conversion facilities. High-speed technology leads capital investment intentions among corrugated box manufacturers seeking throughput gains.
OSHA machine guarding standards and EU machinery directives (CE marking) mandate interlocked safety systems and emergency stop architectures, pushing upgrade demand among aging North American and European installed bases. China's GB standards and SAMR enforcement on imported equipment create compliance thresholds for foreign suppliers. Stakeholders must monitor how dual carbon goals in China and EU Green Deal carbon border adjustments reshape equipment energy efficiency specifications and sourcing geography decisions.
Market Dynamics
EU F-Gas Regulation phase-down schedules and machinery safety directive updates are forcing synchronous replacement cycles across European installed bases, while North American e-commerce fulfillment expansion pulls automated slitting capacity into greenfield packaging converter facilities.
Growth Catalysts
- CE marking machinery directives:European safety standard upgrades mandate interlocked guarding and emergency stop architectures, accelerating equipment turnover in aging German and Italian conversion plants.
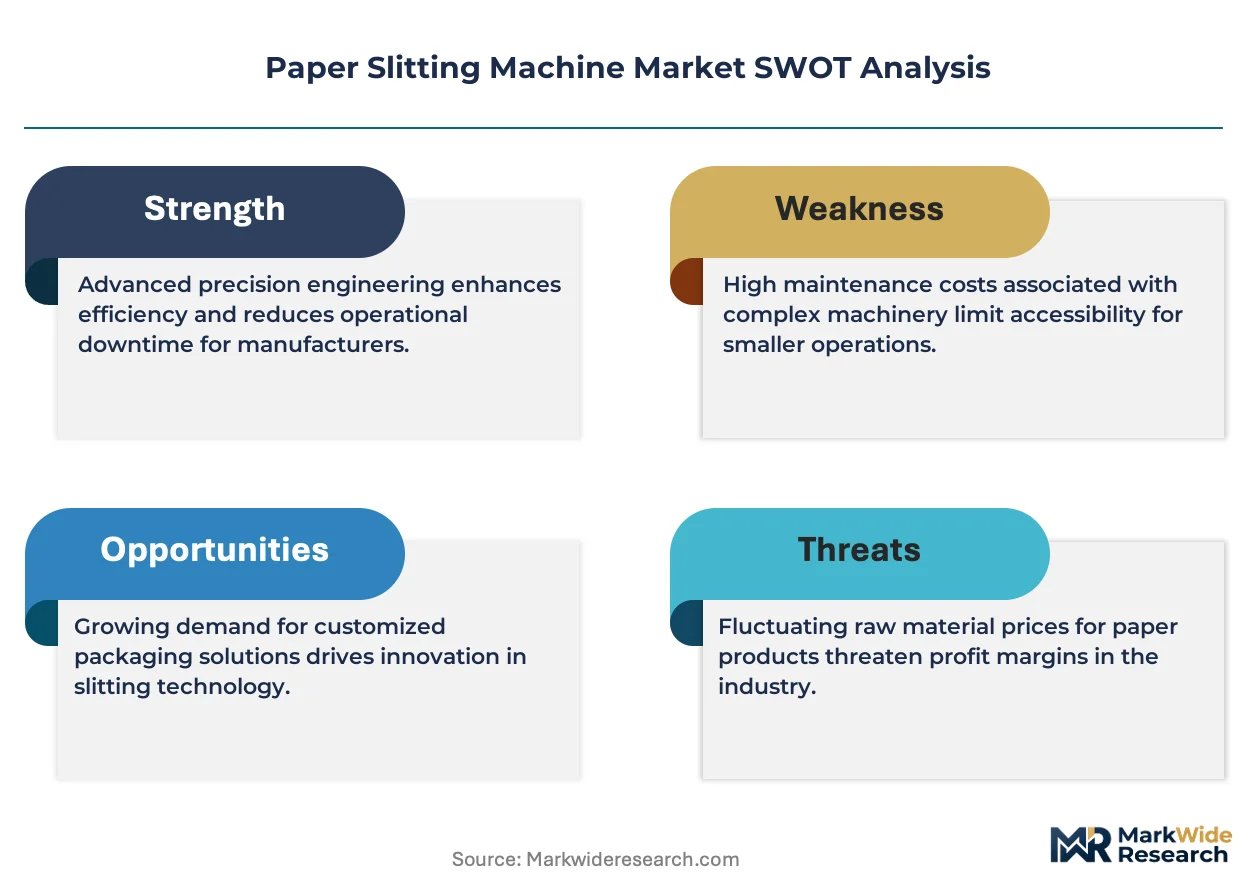
- E-commerce corrugated demand:North American box manufacturers are tripling automated slitting lines to match one-day delivery packaging throughput requirements.
- Shear knife servo positioning:Precision blade alignment technology reduces setup waste by half, justifying premium system upgrades in high-grade specialty paper operations.
Market Restraints
- Specialized steel alloy supply:Rotary slitter blade substrates concentrate among German and Japanese metallurgical suppliers, exposing buyers to input cost volatility and extended lead times.
- Technical speed-width tradeoffs:Band knife configurations cannot sustain web speeds above 400 meters per minute, capping their deployment in high-volume publication paper slitting.
- OSHA machine guarding retrofits:North American legacy installations face six-figure compliance costs per line, freezing capital allocation for smaller independent converters.
Strategic Opportunities
- India packaging corridor expansion:Maharashtra and Gujarat states are attracting integrated pulp-to-box investments requiring slitting systems for kraft linerboard production.
- Battery separator film slitting:Lithium-ion cell manufacturing is creating demand for contamination-controlled slitting environments using adapted paper handling architectures.
- EU Green Deal carbon border adjustments:Energy efficiency certification is becoming a procurement filter, favoring servo-driven systems with documented power consumption profiles.
Industry Challenges
- Mechatronics technician scarcity:Servo drive calibration and PLC programming skills are in short supply across Midwestern US manufacturing regions, extending commissioning timelines.
- Legacy tension control integration:Pneumatic brake systems from 1990s installations resist seamless retrofit with digital closed-loop architectures, forcing complete line replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Slitting Machine Market |
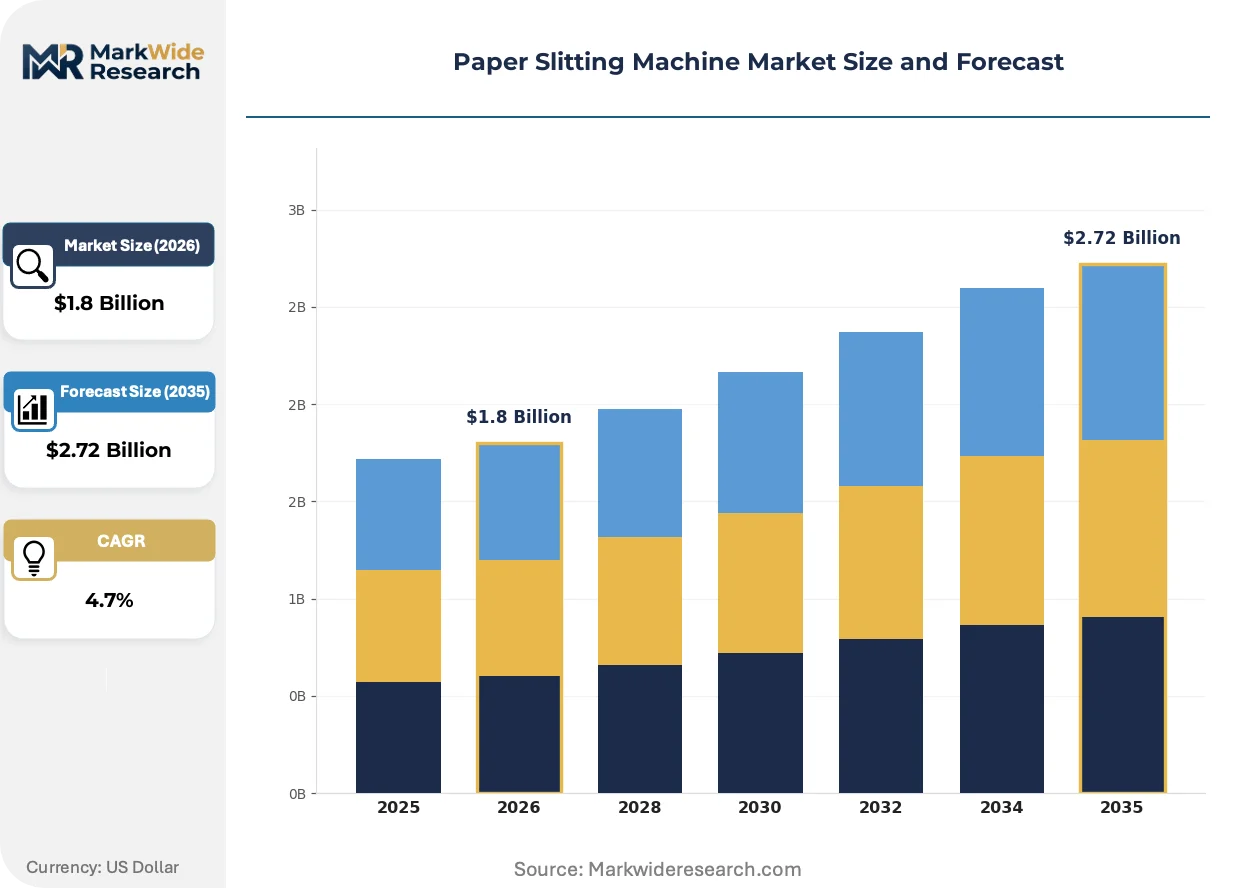
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Slitters, Shear Slitters, Band Slitters, Edge Slitters Application: Packaging, Labeling, Printing, Textiles End User: Paper Manufacturers, Conversion Companies, Print Shops, Corrugated Box Manufacturers Technology: Manual, Semi-Automatic, Fully Automatic, High-Speed |
| Companies Covered | ASHE Converting Equipment, Kampf Schneid- und Wickeltechnik GmbH & Co. KG, Parkinson Technologies, Inc., Universal Converting Equipment, Parkland Machines Ltd, ATLAS CONVERTING EQUIPMENT LT, GOEBEL Schneid und Wickelsysteme GmbH, Euromac S.r.l., SOMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Slitting Machine Market Emerging Trajectories
Digital web inspection and predictive maintenance algorithms are compressing the operational gap between premium European engineering and mid-tier Asian manufacturing, redistributing competitive advantage toward software-enabled service models.
Artificial vision surface defect detection integrated directly into slitting line control loops is rendering obsolete offline quality sampling protocols that required manual roll inspection and rewinding. Specialty paper converters in Scandinavia are adopting these systems at replacement cycle points. The technology is compressing quality assurance labor headcount and enabling single-pass finishing from parent roll to customer-ready narrow rolls.
The EU F-Gas Regulation bans hydrofluorocarbon refrigerants in pneumatic cooling systems from 2027, compelling compressor architecture redesigns in high-speed slitting operations. Equipment manufacturers are engineering closed-loop air circulation to eliminate external cooling dependencies. German precision engineering clusters are prototyping these configurations for export to markets anticipating similar thermal management restrictions.
Converter procurement departments are unbundling after-sales service contracts from initial equipment purchases, negotiating separate multi-year maintenance agreements with third-party specialists. This behavior is displacing OEM captive service revenue streams and forcing Kampf and Parkinson Technologies to restructure pricing architectures. The pattern is most visible among North American independent corrugated converters with in-house mechanical capabilities.
Paper Slitting Machine Market Segmentation
Equipment specification varies sharply across paper grades and throughput requirements. Slitting system selection directly determines finished roll quality, setup waste levels, and compliance with evolving safety mandates.
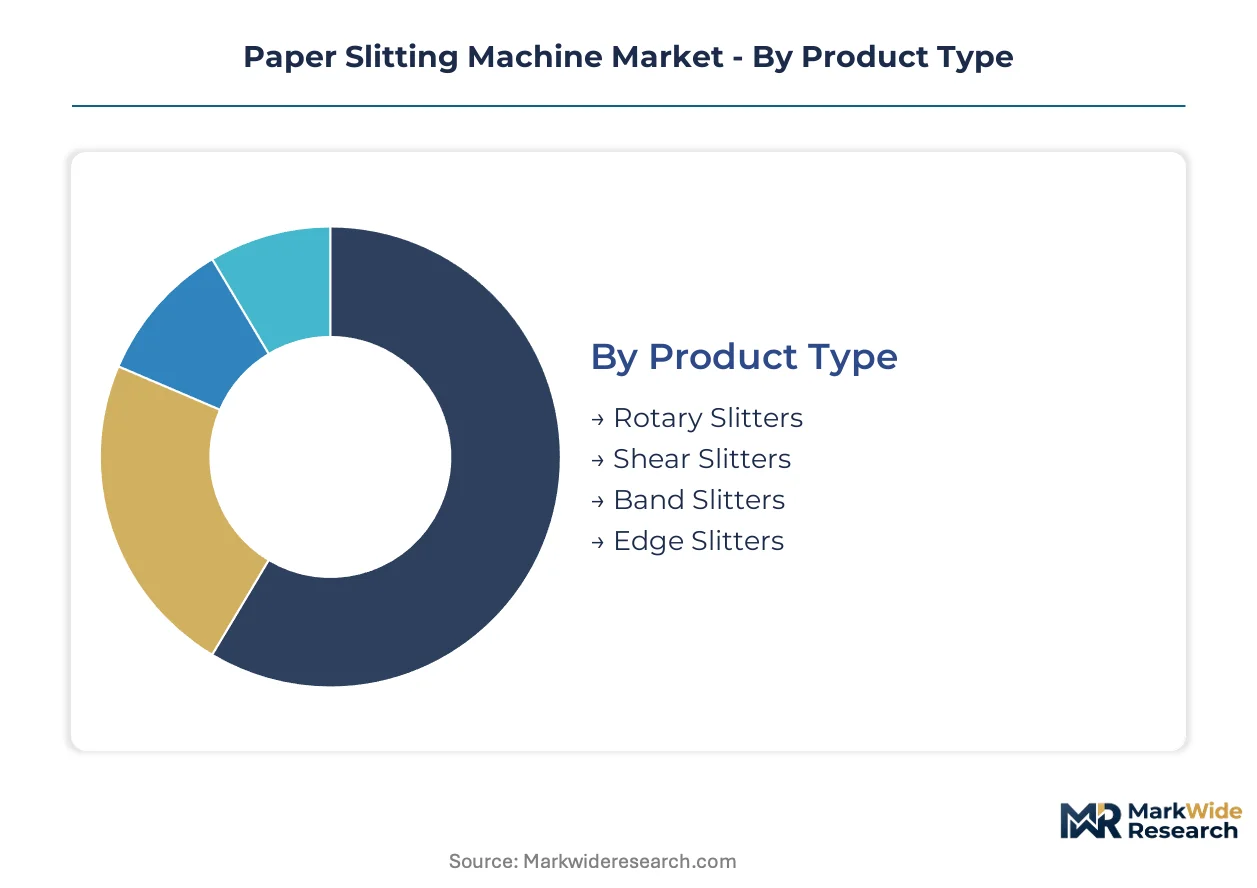
Product Type:
Cost tier differentiates these architectures through blade complexity, speed capability, and substrate versatility.
- Rotary Slitters:Circular blade assemblies score and separate web material without full thickness cutting, accommodating paper weights from tissue to heavy board. German precision engineering clusters dominate rotary system supply for European packaging converters seeking versatility across mixed-grade operations.
- Shear Slitters:Overlapping blade pairs generate clean cuts through scissor-like action, essential for coated papers and films where edge quality determines downstream printability. Shear configurations justify premium positioning in specialty labelstock operations where setup waste reduction delivers measurable margin recovery.
- Band Slitters:Continuous loop blades slice thick materials and non-wovens at moderate speeds.
- Edge Slitters:Trim removal systems process parent roll edges to finished width specifications.
Rotary slitters command the established base. The steepest expansion runs through shear configurations as specialty paper grades multiply.
Application:
Volume concentration and margin structure vary substantially across these end-use environments.
- Packaging:Corrugated linerboard and folding carton production demands high-speed rotary systems processing web widths exceeding two meters at speeds approaching 1,500 meters per minute. North American e-commerce fulfillment expansion is tripling automated slitting line installations among independent box manufacturers.
- Labeling:Pressure-sensitive and linerless label production requires precision shear slitting with width tolerances below 0.1 millimeters. European pharmaceutical and food labeling regulations are tightening traceability requirements that favor automated inspection-integrated slitting systems.
- Printing:Publication and commercial print operations prioritize quick changeover between job specifications.
- Textiles:Non-woven and technical fabric slitting adapts paper handling architectures for hygiene and filtration applications.
Packaging absorbs the dominant share of capital deployment. Labeling applications are climbing the fastest as pharmaceutical serialization mandates spread.
End User:
Customer type shapes procurement authority, technical sophistication, and service contract preferences.
- Paper Manufacturers:Integrated pulp and paper mills operate captive slitting capacity for internal conversion or merchant roll distribution. These facilities specify heavy-duty systems with decades-long depreciation horizons and comprehensive OEM service agreements.
- Conversion Companies:Independent converters serving multiple end markets prioritize modular systems with rapid reconfiguration capabilities. North American independent corrugated converters are increasingly unbundling after-sales contracts from initial equipment purchases.
- Print Shops:Commercial printers maintain narrow web slitters for in-house finishing of digitally printed rolls.
- Corrugated Box Manufacturers:Integrated box plants source slitting systems as components of complete corrugator lines.
Conversion companies drive the majority of replacement demand. Corrugated box manufacturers are gaining share fastest as greenfield capacity expands.
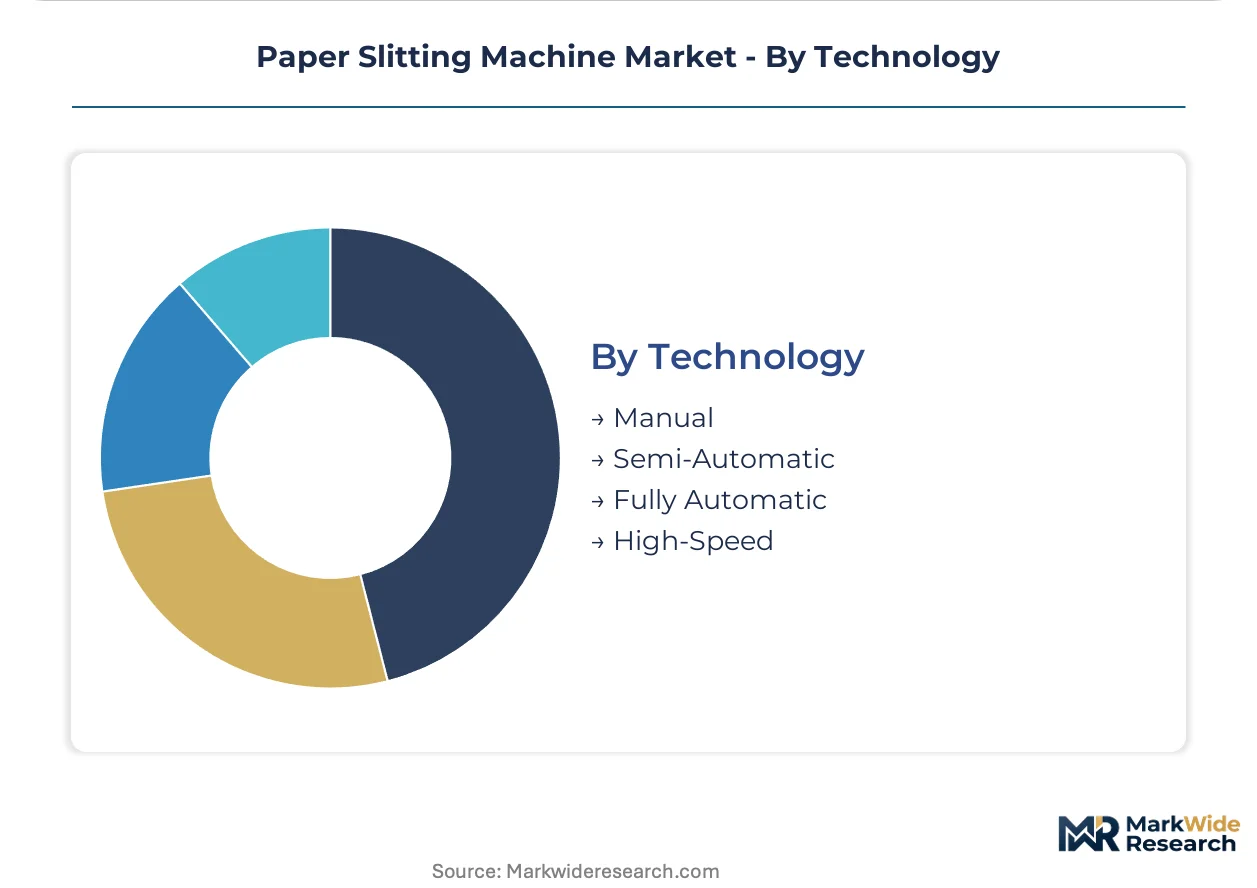
Technology:
Maturity and automation level determine labor content, safety compliance burden, and energy efficiency profile.
- Manual:Operator-positioned knives and mechanical tension brakes serve low-volume specialty operations with minimal capital budgets. These systems face accelerating obsolescence as OSHA machine guarding retrofits impose six-figure compliance costs per line.
- Fully Automatic:Servo-driven knife positioning, automated tension control, and integrated web inspection compress setup intervals and quality variance. EU machinery directives mandating interlocked guarding architectures are accelerating turnover toward fully automatic replacements in aging German and Italian plants.
- Semi-Automatic:Hybrid configurations retain manual loading with powered knife positioning.
- High-Speed:Optimized mechanical and control architectures sustain maximum web velocities for volume-focused producers.
Semi-automatic systems retain residual presence in emerging markets. Fully automatic technology is expanding most quickly as labor costs rise and safety mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated packaging converters and specialty paper manufacturers concentrate equipment procurement in industrial corridors with established precision engineering ecosystems. Regulatory mandates on safety and refrigerant phase-downs are synchronizing replacement cycles across mature markets.
Germany
Precision engineering clusters in North Rhine-Westphalia and Baden-Württemberg supply slitting systems across European packaging lines. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs from 2027, compelling compressor redesigns in high-speed operations. Kampf Schneid- und Wickeltechnik GmbH & Co. KG anchors engineering standards from its Wiehl headquarters.
United States
Corrugated box manufacturers in the Midwest and Southeast are tripling automated slitting capacity to match e-commerce fulfillment throughput. OSHA machine guarding standards impose six-figure retrofit costs on legacy installations, accelerating greenfield investments over upgrades. Parkinson Technologies, Inc. dominates installations through specialized web handling expertise.
China
Battery separator film production for lithium-ion cells is creating demand for contamination-controlled slitting environments. GB standards and SAMR enforcement on imported equipment establish compliance thresholds for foreign suppliers. Yangtze River Delta converters are adapting paper handling architectures for technical film applications.
India
Integrated pulp-to-box investments in Maharashtra and Gujarat states require slitting systems for kraft linerboard production. Bureau of Indian Standards certification and central electricity authority efficiency norms shape procurement specifications. Mundra and Hazira industrial corridors are attracting packaging infrastructure with captive slitting capacity.
Italy
Specialty labelstock and pharmaceutical packaging converters in Lombardy and Emilia-Romagna prioritize precision shear slitting with automated inspection integration. CE marking machinery directives mandate interlocked guarding architectures, forcing turnover in aging Bologna and Milan conversion plants. Euromac S.r.l. represents regional fabrication capabilities.
Paper Slitting Machine Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where precision engineering heritage commands premium positioning. The vendor base organizes around three strategic archetypes: German precision engineering clusters, North American web handling specialists, and modular Asian fabricators. Consolidation pressure operates through geographic expansion and technology licensing rather than horizontal mergers. Portfolio diversification into adjacent converting equipment and energy-efficient system architectures represents the dominant competitive moves.
Among German precision engineering clusters, Kampf Schneid- und Wickeltechnik GmbH & Co. KG and GOEBEL Schneid und Wickelsysteme GmbH occupy positions defined by decades of rotary and shear system refinement. Parkinson Technologies, Inc. anchors North American demand through specialized expertise in high-speed web handling architectures. ASHE Converting Equipment exemplifies the modular design approach competing across mid-volume conversion operations in multiple geographies.
| Leading Market Players |
|---|
| ASHE Converting Equipment |
| Kampf Schneid- und Wickeltechnik GmbH & Co. KG |
| Parkinson Technologies, Inc. |
| Universal Converting Equipment |
| Parkland Machines Ltd |
| ATLAS CONVERTING EQUIPMENT LT |
| GOEBEL Schneid und Wickelsysteme GmbH |
| Euromac S.r.l. |
| SOMA |
| Others |
Supply Flow & Price Mechanics
German and Japanese metallurgical suppliers concentrate rotary slitter blade substrate production, anchoring premium pricing power in precision-engineered shear configurations while forcing mid-tier buyers toward modular Asian alternatives with compressed margin structures.
Pricing Analysis
Cost-plus contracts with steel alloy indexation dominate procurement for high-performance blade assemblies. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified servo systems from pneumatic retrofits and manual configurations. Pricing pressure stems from unbundled after-sales service contracts among North American independent converters. Conversion companies exhibit highest price sensitivity; integrated paper manufacturers absorb premiums for comprehensive OEM service agreements.
Supply Chain Analysis
Tariff exposure between Germany and China disrupts component flows for servo drive systems and precision bearings. Manufacturing concentrates in Germany, China, and Italy for complete machine builds. Supply chains draw from specialized steel alloy foundries, servo motor producers, and PLC control module fabricators. Single-source vulnerability persists in high-grade blade substrates. Distribution runs through OEM direct sales for integrated mills and specialized converting equipment distributors for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper slitting machine market functions as a service-attach opportunity where multi-year maintenance agreements and predictive maintenance software subscriptions expand faster than hardware revenue as converter procurement departments unbundle after-sales contracts.
For Market Incumbents: Harden aftermarket revenue retention by embedding predictive maintenance algorithms directly into control architectures, resisting third-party service displacement. Kampf and Parkinson Technologies must restructure pricing architectures to capture recurring software revenue. Invest in mechatronics technician certification programs to address commissioning timeline bottlenecks in Midwestern US manufacturing regions. For New Entrants and Emerging Players: Build out contamination-controlled slitting environments for battery separator film applications, leveraging adapted paper handling architectures from Yangtze River Delta technical film operations. India's Maharashtra and Gujarat packaging corridors offer white-space entry with Bureau of Indian Standards certification as the procurement filter. Pursue joint development agreements with lithium-ion cell manufacturers to establish reference installations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering clusters in Germany's North Rhine-Westphalia region holding mature rotary slitter portfolios. Five-to-ten year viability hinges on energy efficiency certification compliance for EU Green Deal carbon border adjustments. Monitor servo drive system order backlogs as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Metallurgy | German OEMs securing captive supply of specialized steel alloys reduce input cost volatility from Japanese suppliers. |
| Predictive Maintenance Platform Launch | Software-enabled service models compress the operational gap between European engineering and Asian manufacturing. |
| CE Marking Pathway Acceleration | Interlocked guarding architectures unlock replacement demand in aging Italian and German conversion plants. |
| Joint Venture in India Packaging Corridor | Mundra and Hazira industrial clusters require slitting systems for integrated pulp-to-box investments. |
| Energy Efficiency Certification Program | Documented power consumption profiles become procurement filters under EU Green Deal carbon border adjustments. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads at packaging converters across Germany, the United States, China, and India; and secondary validation through customs/trade data, machinery safety directive filings, SEC 10-K disclosures from listed equipment manufacturers, and industry association production statistics. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure surveys from pulp and paper industry associations.
Forecast inputs span product type segmentation across rotary, shear, band, and edge configurations; application segmentation through packaging, labeling, printing, and textiles; technology tiers from manual through fully automatic and high-speed systems; and end-user archetypes including paper manufacturers, conversion companies, print shops, and corrugated box manufacturers. CAGRs derive from regression analysis against corrugated box production indices, e-commerce fulfillment center buildouts, and regulatory compliance deadline schedules. Model assumptions incorporate EU F-Gas Regulation phase-down timelines and OSHA machine guarding enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular Asian fabricators into premium servo-driven segments would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Food Powder Packaging Machine Market