
 Mastic Tapes Market | 2026-2036
Mastic Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Mastic Tapes Market Foresight
Butyl rubber compounds are hardening as the preferred substrate over traditional asphalt-based formulations in electrical insulation and moisture-sealing applications. 3M leverages its polymer science capabilities to supply reinforced mastic tapes for utility infrastructure across multiple continents. Denso anchors the automotive corrosion-protection segment with OEM-certified underbody coatings and seam-sealing products. Tesa SE specializes in precision-cut mastic solutions for electronics and transportation assembly lines.
Mastic tapes are self-fusing, non-curing adhesive strips composed of synthetic rubber or polymeric compounds loaded with tackifying resins and fillers, designed to form permanent watertight and airtight seals upon application pressure. Self-adhesive formulations dominate volume due to simplified field installation, while reinforced variants command premium positioning in high-stress construction and industrial environments. The electrical application segment is expanding fastest as utilities replace heat-shrink systems with cold-applied mastic wraps for medium-voltage cable joints. Contractors represent the most concentrated end-user channel, though OEM direct procurement is gaining share in automotive and HVAC equipment manufacturing.
OSHA workplace safety standards and NFPA electrical codes in the United States mandate flame-retardant and low-smoke emission properties for tapes deployed in commercial building systems. REACH chemical restrictions in Europe limit certain plasticizers and heavy-metal stabilizers, compelling reformulation toward compliant polymeric backings. EPA regulations on volatile organic compound emissions affect manufacturing processes and product labeling requirements for domestic producers. Stakeholders must monitor evolving material compliance thresholds and qualification timelines across jurisdictions to secure specification continuity in procurement pipelines.
Market Dynamics
Grid electrification and the phase-out of high-GWP chemical sealants are restructuring procurement specifications across utilities and automotive OEMs, compressing qualification timelines and elevating butyl-based formulations over legacy asphalt systems.
Growth Catalysts
- EU F-Gas Regulation:The phase-out of high-global-warming-potential sealants redirects specification toward butyl-based mastic compounds in HVAC and electrical sealing applications across member states.
- Electric vehicle battery assembly:German automotive OEMs specify vibration-damping tapes for battery pack module fixation, creating dedicated demand for reinforced mastic substrates with thermal cycling resistance.
- Cold-applied insulation systems:North American electrical utilities accelerate replacement of heat-shrink cable joint systems with self-amalgamating mastic wraps to reduce installation time and hot-work permitting.
Market Restraints
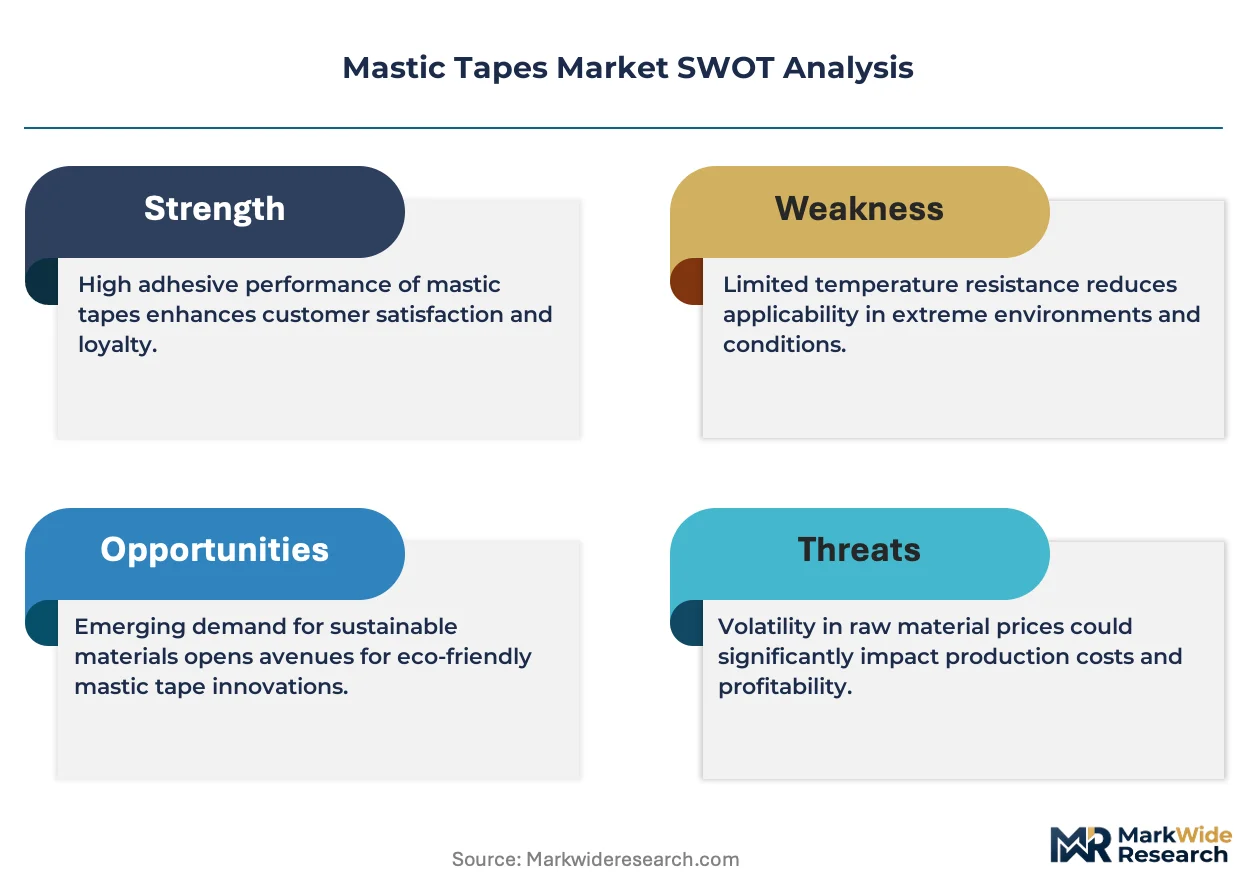
- Petrochemical feedstock volatility:Synthetic rubber and tackifying resin prices fluctuate with crude oil derivatives, compressing margin stability for compounders without backward integration into polymer production.
- REACH chemical restrictions:European limitations on phthalate plasticizers and heavy-metal stabilizers force reformulation cycles that extend product requalification timelines by 18-24 months.
- Acrylic pressure-sensitive adhesives:Lower-cost PSA tapes substitute for mastic in low-stress moisture-sealing applications where permanent fusion is not technically required.
Strategic Opportunities
- India transmission infrastructure:State electricity boards under the CEA mandate expand medium-voltage network upgrades, opening specification windows for imported cold-applied insulation systems.
- Offshore wind cable protection:Subsea array cable manufacturers seek mastic-based corrosion barriers that withstand saltwater immersion and cathodic disbondment over 25-year service lives.
- Direct OEM procurement channels:Automotive and HVAC equipment manufacturers bypass distributor networks to qualify tape suppliers directly, enabling volume commitments and co-development agreements.
Industry Challenges
- NFPA and OSHA compliance testing:Flame-retardant certification for commercial building applications requires third-party validation that adds 6-12 months to product launch timelines.
- Polymer compounding expertise:Shortage of formulators skilled in butyl-rheology modification and filler dispersion limits in-house R&D expansion for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mastic Tapes Market |
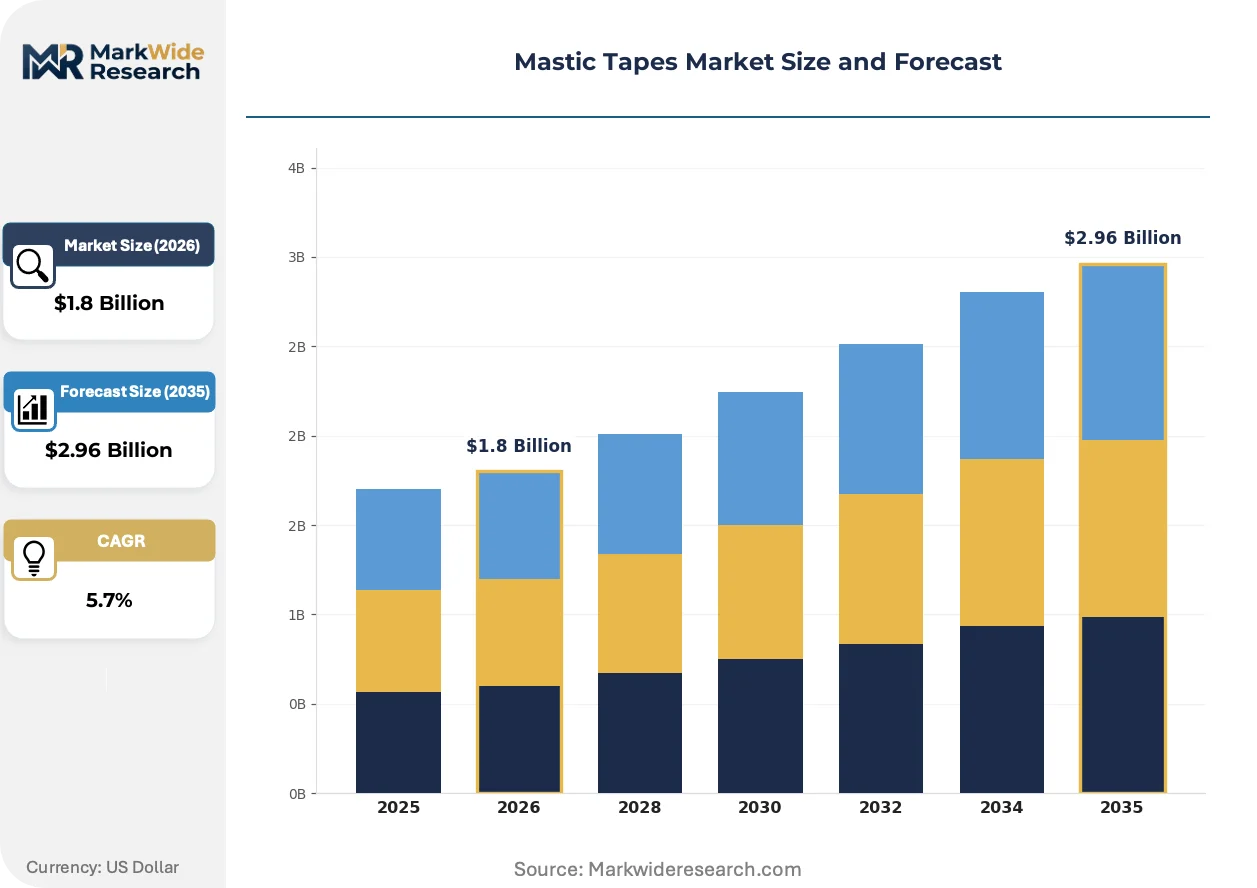
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Non-Adhesive, Reinforced, Liquid Application: Construction, Automotive, Electrical, HVAC End User: Contractors, OEMs, DIY Enthusiasts, Repair Shops Material: Polymeric, Rubber, Fabric, Foam |
| Companies Covered | 3M, Denso, Osaka Rubber, Omega Rubber Industries, Filoform, NSI Industries, McMaster-Carr, Tesa SE, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mastic Tapes Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are compressing product development cycles while unifying previously separate performance attributes into single-substrate solutions.
Self-fusing silicone-butyl hybrid tapes are unifying electrical insulation and extreme-temperature resistance in a single applied layer. Aerospace wire harness manufacturers in the United States adopt these substrates to reduce part count and assembly time. The convergence is compressing supplier bases as dual-capability formulations displace separate tape systems.
REACH authorization procedures for persistent organic pollutants are forcing substitution of chlorinated paraffin plasticizers in European electrical tape formulations. Compounders reformulate with bio-based tackifiers and precipitated calcium carbonate fillers to maintain adhesion profiles. German cable accessory manufacturers face the steepest requalification burden as they supply both domestic utilities and export markets.
Utility procurement departments consolidate vendor lists and demand application-engineering support rather than commodity supply. Regional electrical distributors lose share to direct manufacturer relationships as buyers seek cold-applied system training and joint specification development. This concentration is most visible across North American municipal utilities modernizing aging underground distribution networks.
Mastic Tapes Market Segmentation
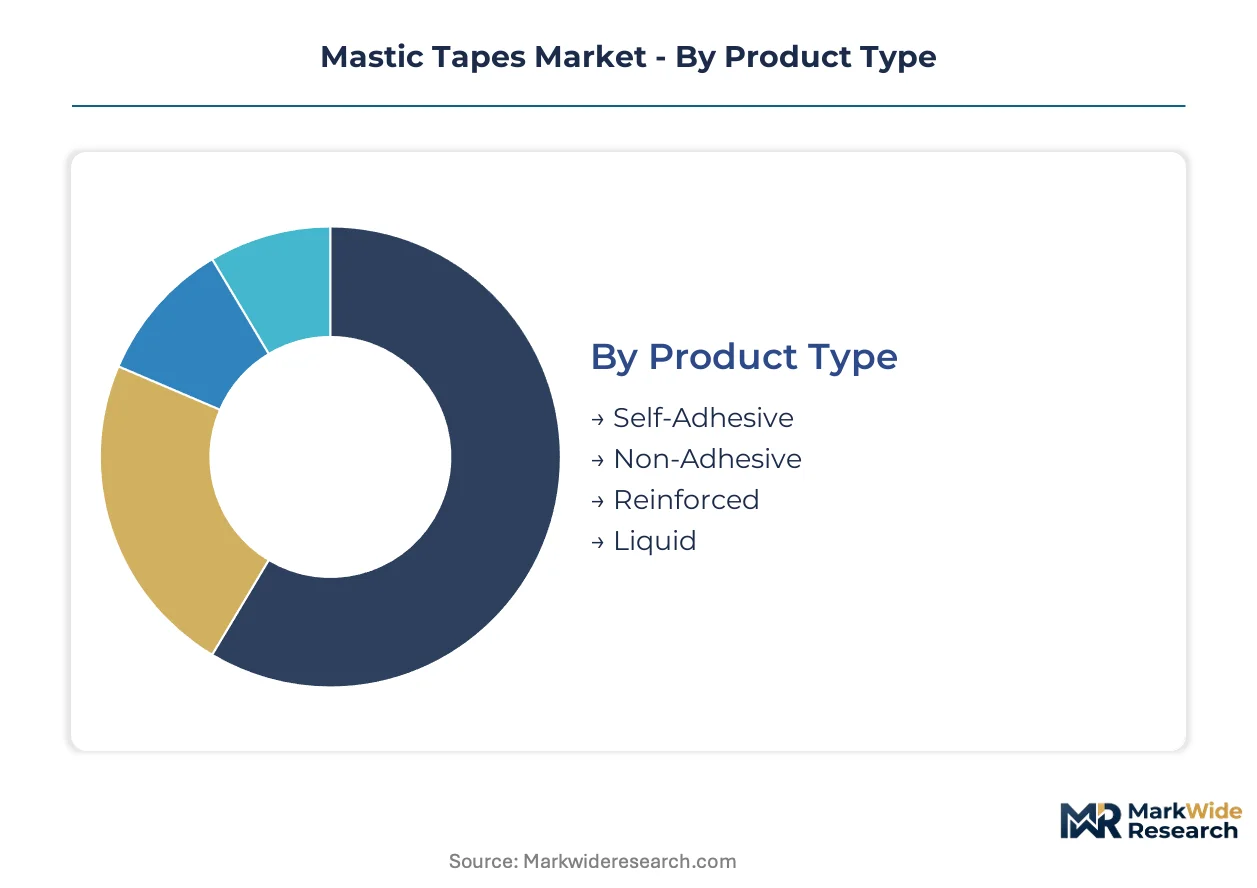
Mastic tapes serve divergent technical requirements across electrical infrastructure, automotive assembly, and building construction. Segmentation reveals how formulation chemistry and application method determine procurement channels and margin structures for compounders.
Product Type:
Installation labor costs and permanence requirements separate buyers into field-applied versus factory-integrated systems.
- Self-Adhesive:Pre-tackified synthetic rubber substrates enable immediate bonding without solvent activation. Electrical utilities in the United States specify these for live-line medium-voltage cable repairs where hot-work permits are prohibitively expensive.
- Reinforced:Scrim-embedded or mesh-backed variants withstand tensile stress in subsea cable protection and heavy-equipment vibration damping. German offshore wind array manufacturers drive qualification demand for 25-year saltwater immersion resistance.
- Non-Adhesive:Heat-activated or solvent-requiring formulations serve OEM factory lines where controlled application conditions replace field convenience.
- Liquid:Brush or spray-applied mastic compounds conform to irregular geometries in pipeline flange sealing and structural steel corrosion protection.
Self-adhesive tapes dominate procurement volumes today; reinforced substrates are gaining share fastest in high-stress industrial applications.
Application:
Regulatory compliance intensity and specification authority concentration shape segment profitability.
- Electrical:Cold-applied insulation wraps for medium-voltage cable joints displace heat-shrink systems under NFPA and OSHA flame-retardant mandates. North American utilities accelerate procurement as grid modernization funding flows through state electricity boards.
- Automotive:Vibration-damping and thermal-management tapes secure electric vehicle battery modules. German OEMs specify butyl-based substrates with thermal cycling resistance from -40°C to 150°C.
- Construction:Building envelope sealing and roofing membrane applications face EPA VOC emission constraints on installation chemistry.
- HVAC:Duct sealing and refrigeration line insulation pivot toward low-GWP compliant formulations under the EU F-Gas Regulation phase-out schedule.
Electrical applications anchor revenue today; automotive battery assembly is expanding most quickly.
End User:
Technical support requirements and volume predictability determine supplier relationship depth.
- OEMs:Direct procurement with co-development agreements and multi-year volume commitments. Automotive and HVAC equipment manufacturers bypass distribution to qualify tape suppliers against internal performance specifications.
- Contractors:Concentrated demand from electrical and mechanical installation firms who value application training and field engineering support over commodity pricing.
- Repair Shops:Fragmented aftermarket demand for automotive underbody sealing and electrical splice repair with limited specification authority.
- DIY Enthusiasts:Retail-channel moisture sealing and weatherstripping with minimal technical qualification requirements.
Contractor channels generate the highest volume throughput; OEM direct procurement is climbing the fastest.
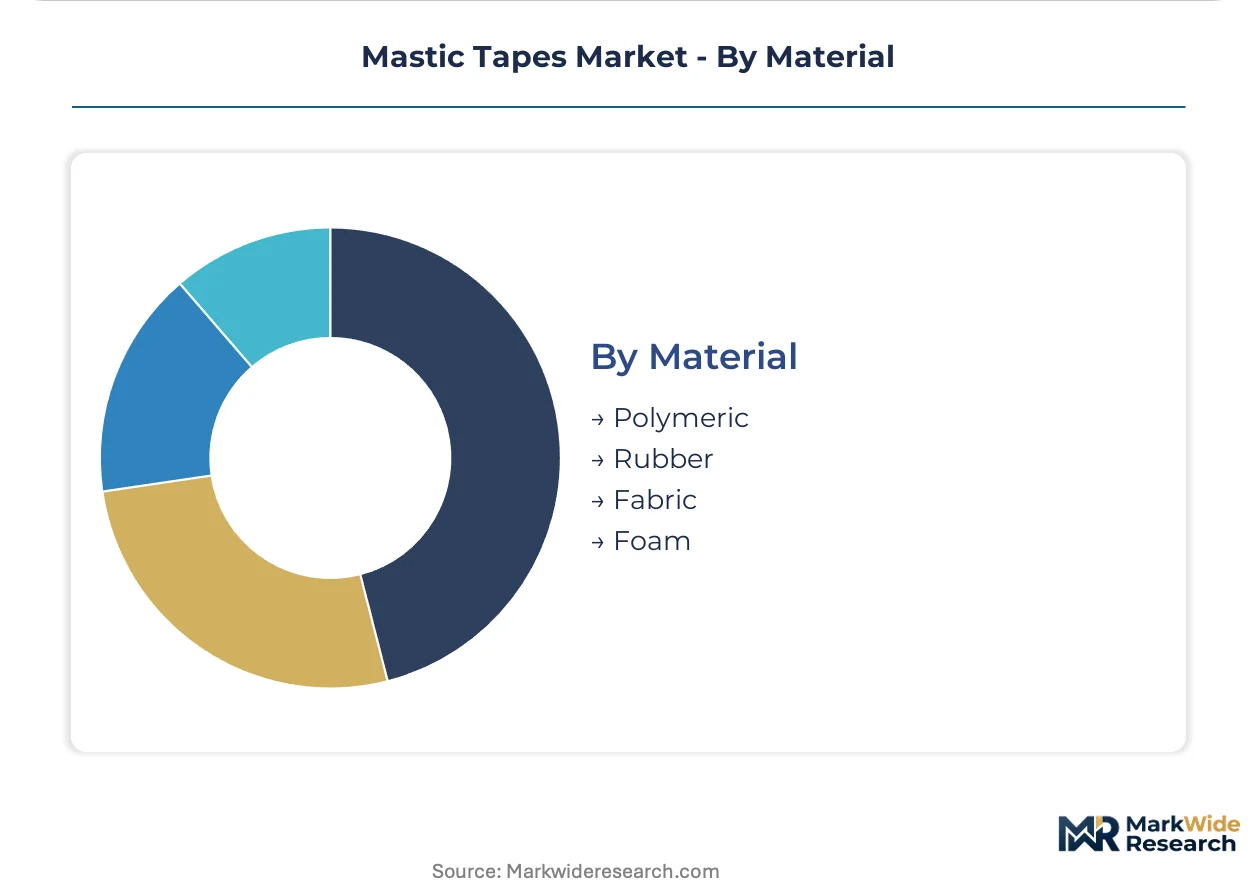
Material:
Feedstock chemistry and compounding complexity create tiered performance and pricing strata.
- Rubber:Butyl and EPDM compounds dominate electrical insulation and automotive damping. REACH restrictions on phthalate plasticizers force reformulation with precipitated calcium carbonate fillers and bio-based tackifiers.
- Polymeric:Synthetic elastomer blends enable precise rheology control for automated dispensing equipment in high-volume manufacturing lines.
- Fabric:Woven or non-woven carrier substrates reinforce mechanical strength in heavy-duty construction and industrial maintenance applications.
- Foam:Cellular structures provide compressible sealing and gap-filling in irregular joint geometries with lower material density.
Rubber formulations lead material consumption today; polymeric substrates show the steepest expansion trajectory in precision assembly applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs in Stuttgart and Munich are specifying butyl-based mastic tapes for electric vehicle battery assembly, creating concentrated demand for vibration-damping substrates with thermal cycling resistance.
United States
Electrical utilities across Texas and California are accelerating cold-applied insulation procurement for medium-voltage cable joint modernization. OSHA workplace safety standards and NFPA electrical codes mandate flame-retardant properties for commercial building tape applications. Municipal utilities in the Pacific Northwest are replacing heat-shrink systems with self-amalgamating mastic wraps to eliminate hot-work permitting costs.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify reinforced mastic substrates for battery pack module fixation in electric vehicle production lines. The EU F-Gas Regulation redirects HVAC and electrical sealing specifications toward low-GWP butyl compounds. Cable accessory manufacturers in North Rhine-Westphalia face extended requalification timelines as REACH restrictions force substitution of chlorinated paraffin plasticizers.
China
State Grid Corporation procurement departments are expanding medium-voltage network upgrades across eastern provinces. GB standards and MIIT industrial policy guide domestic specification for electrical insulation materials. Manufacturing clusters in Jiangsu and Zhejiang are scaling production of polymeric-backed mastic compounds for export markets.
India
Central Electricity Authority mandates are driving transmission infrastructure expansion across Maharashtra and Gujarat. State electricity boards under CEA procurement guidelines are opening specification windows for imported cold-applied insulation systems. Utility contractors in Tamil Nadu are qualifying self-adhesive mastic wraps for live-line cable repair applications.
Japan
Automotive wire harness manufacturers in Aichi Prefecture are adopting silicone-butyl hybrid tapes to reduce assembly part counts. METI industrial standards and JIS certification requirements shape product qualification timelines. Precision electronics assemblers in the Kanto region are specifying mastic solutions for automated dispensing equipment integration.
Mastic Tapes Market Competitive Landscape
Global majors compete with regional champions across polymer compounding capabilities and application-engineering support depth. The vendor base organizes into three tiers: integrated material science conglomerates with captive polymer production, specialized adhesive compounders serving single industries, and regional fabricators competing on price for commodity electrical insulation. Strategic archetypes include butyl-rheology specialists, reinforced-substrate innovators, and cold-applied system integrators. Dominant competitive moves involve backward integration into synthetic rubber production and direct OEM qualification partnerships that bypass distribution channels.
Within the integrated-materials tier, 3M leverages polymer science capabilities across multiple continents while Denso anchors automotive corrosion-protection segments with OEM-certified supply relationships. Tesa SE occupies a precision-positioning niche for electronics and transportation assembly lines. These three exemplify how scale-driven compounders, automotive specialists, and precision-cut solution providers respectively represent divergent paths to specification authority in electrical, automotive, and industrial end-use segments.
| Leading Market Players |
|---|
| 3M |
| Denso |
| Osaka Rubber |
| Omega Rubber Industries |
| Filoform |
| NSI Industries |
| McMaster-Carr |
| Tesa SE |
| Nitto Denko Corporation |
| Others |
Supply & Pricing Matrix
Cold-applied insulation system adoption across North American utilities is compressing supplier margins while concentrating procurement authority among compounders with captive butyl rubber production. This production-method transition simultaneously elevates material cost pass-through sensitivity and rewards backward-integrated manufacturers with pricing power over distributor-dependent competitors.
Pricing Analysis
Petrochemical feedstock pass-through mechanics dominate mastic tape pricing, with synthetic rubber and tackifying resin costs tracking crude oil derivative movements. Three-tier pricing structure across premium, standard, and economy levels separates reinforced substrates with 25-year saltwater certification from commodity electrical wraps. Cost compression in standard-grade butyl compounds is intensifying because REACH-mandated reformulation cycles extend requalification timelines. Electrical contractors exhibit highest price sensitivity due to project-based bidding, while German automotive OEMs accept premium positioning for thermal-cycling-validated battery assembly tapes.
Supply Chain Analysis
Reverse-logistics flows for off-specification mastic compounds remain underdeveloped, with most manufacturers relying on internal reprocessing rather than third-party refurbishment networks. Raw material supply concentrates in Germany, China, and the United States, with butyl rubber production anchored in German petrochemical complexes and polymeric backing extrusion scaling in Jiangsu manufacturing clusters. Formulation draws from precipitated calcium carbonate fillers, bio-based tackifiers, and synthetic elastomer feedstocks. Single-source vulnerability persists in specialized butyl-rheology modifiers. Distribution runs through direct OEM procurement channels and regional electrical distributors serving contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU F-Gas Regulation phase-out schedule redirecting specification toward low-GWP butyl formulations and compressing qualification timelines for non-compliant suppliers.
For Market Incumbents: Anticipate acrylic pressure-sensitive adhesive substitution in low-stress moisture-sealing applications by accelerating certification investment for flame-retardant NFPA compliance. Defend margin position through backward integration into synthetic rubber production and direct qualification partnerships with automotive OEMs that bypass distributor networks. Channel control over application-engineering support represents the critical retention lever against regional price competitors. For New Entrants and Emerging Players: Begin with India's transmission infrastructure expansion under CEA mandates, where state electricity boards are opening specification windows for imported cold-applied insulation systems with limited incumbent penetration. Target offshore wind cable protection applications in German North Sea arrays, where 25-year saltwater immersion resistance requirements create technical barriers that filter out commodity suppliers. Pursue co-development agreements with subsea cable manufacturers as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier compounders lacking captive polymer production but holding established contractor channel relationships. Long-term viability over the next decade hinges on REACH compliance completion and direct OEM qualification progress. Monitor German automotive OEM battery platform specification releases as the inflection indicator for vibration-damping tape demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber | Captive butyl production insulates margin stability from petrochemical feedstock volatility. |
| Direct OEM Qualification Partnerships | Bypassing distributor networks secures volume commitments from German automotive manufacturers. |
| REACH Compliance Reformulation | Substitution of chlorinated paraffin plasticizers maintains European market access under ECHA restrictions. |
| Cold-Applied System Training Programs | Application-engineering support differentiates suppliers as utilities consolidate vendor lists. |
| Subsea Cable Protection Certification | 25-year saltwater immersion validation opens specification windows in German offshore wind arrays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrical utility procurement officers, automotive OEM platform engineers, adhesive compounder R&D directors, and contractor field supervisors with secondary validation. Trade data from customs authorities, SEC filings from integrated material science conglomerates, ECHA REACH registration databases, and CEA infrastructure procurement notices anchored supply-side modeling. Bottom-up segment sizing and top-down macroeconomic cross-checks ensured triangulation integrity.
Historical reference periods spanning installed base analysis and recent procurement cycle data anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user channel, and material chemistry grade. CAGRs were derived from elasticity-adjusted demand curves and input-cost trajectory assumptions. Forecast inputs incorporated EU F-Gas Regulation phase-out schedules, State Grid Corporation capital expenditure plans, and German automotive battery production ramp timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to NFPA electrical codes, abrupt petrochemical feedstock price dislocations, and trade policy shifts affecting butyl rubber tariff structures. Forecasts reflect documented assumptions about qualification timeline stability and OEM specification continuity. Practitioners should monitor ECHA authorization list updates and German automotive platform battery chemistry shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Tape Banding Machine Market
Tapes
Foil Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Flatback Tapes Market
Tapes
Gaffers Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Heat Activated Tear Tape Market
Tapes
Wing Walk Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Carbon Tapes Market
Tapes
PVC Tapes Market