
 Polyester Straps Market | 2026-2036
Polyester Straps Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Straps Market Outlook
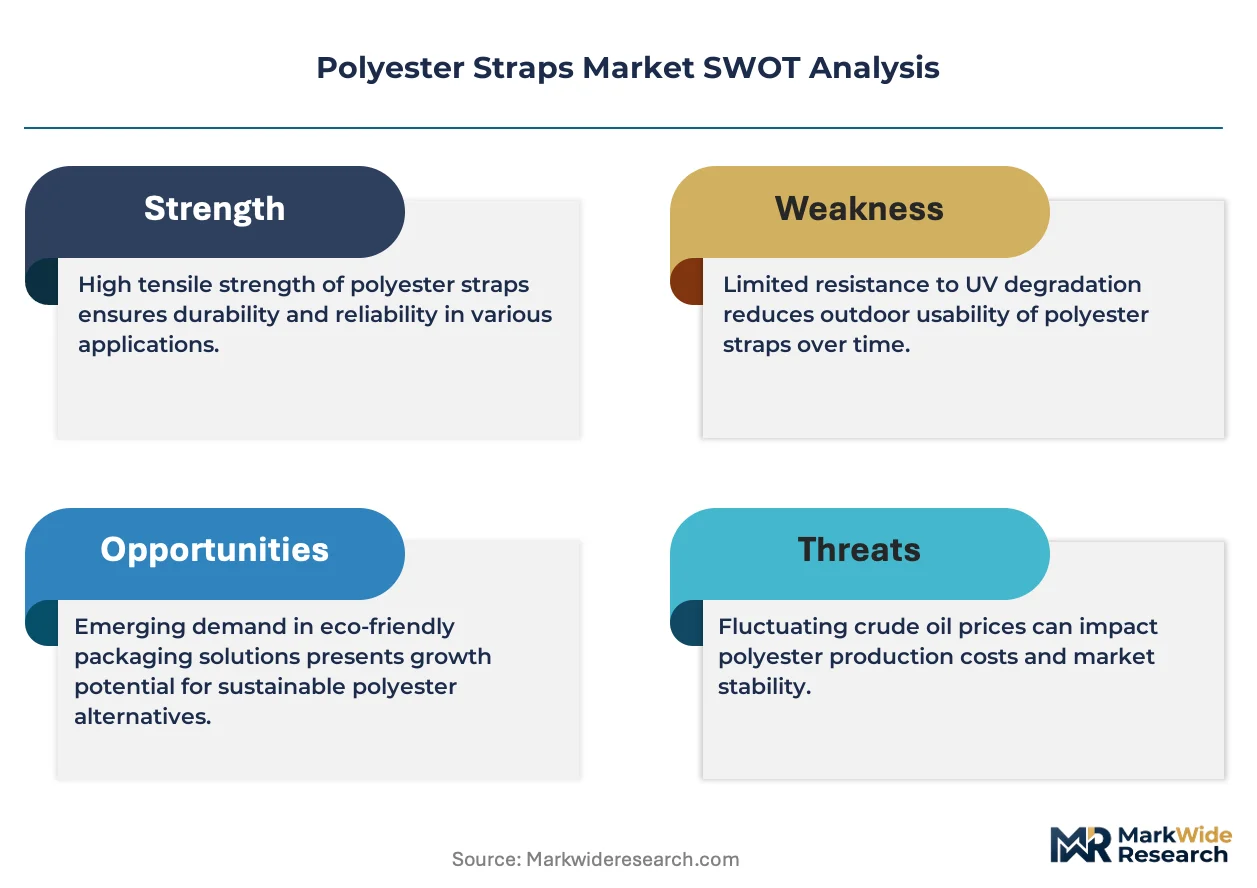
REACH compliance is expanding the cost-of-entry calculus for polyester strap exporters targeting European manufacturing clients. FROMM Packaging leverages captive extrusion capacity to sustain margin control across multiple continents. Samuel Strapping anchors North American supply through dedicated PET recycling streams. Teufelberger differentiates via high-tenacity fiber integration for heavy-load applications.
Polyester straps are woven or extruded polyethylene terephthalate (PET) bands, typically rated from 300 kg to 2,000 kg break strength, designed to secure palletized goods during transit and storage. Heavy-duty straps command premium positioning in construction and steel coil applications where elongation recovery prevents load relaxation. Flat straps dominate logistics volumes due to compatibility with automated tensioning equipment, while custom straps capture margin pools in specialized lifting operations where dimensional precision reduces slippage risk.
FDA food-contact rules and OSHA load-secure guidelines shape product certification requirements in the United States, while REACH and EU Green Deal packaging mandates drive reformulation timelines in Europe. Stakeholders must monitor how California's SB 54 extended producer responsibility framework and Germany's Packaging Act amendments alter recycled-content thresholds for strapping sold into retail supply chains.
Market Dynamics
Steel-to-PET substitution is accelerating as logistics operators confront freight damage costs and carbon accounting pressures. The EU Packaging and Packaging Waste Regulation is compressing reformulation timelines for converters serving retail supply chains.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable-content thresholds are pulling converters toward rPET formulations. European retailers now specify post-consumer recycled strapping in procurement contracts.
- E-commerce fulfillment density:Automated warehouse systems in China require high-tensile PET securing solutions. Pallet stability standards are tightening as order velocities rise.
- Steel coil handling:Heavy-load polyester straps with elongation recovery properties are displacing metal alternatives. Construction material distributors specify break-strength ratings above 1,500 kg.
Market Restraints
- Crude oil volatility:Purified terephthalic acid feedstock costs swing with naphtha pricing. Margins compress when PTA spot markets spike.
- Recycling infrastructure gaps:Post-industrial PET collection networks remain sparse outside Germany and Japan. Strap-to-strap closed-loop systems require capital-intensive sorting technology.
- Competing bio-based materials:Polylactic acid strapping gains trial placements in temperature-controlled logistics. PLA biodegradability appeals to food-contact applications.
Strategic Opportunities
- India warehousing expansion:Cold chain infrastructure buildout creates demand for moisture-resistant securing solutions. Third-party logistics providers specify UV-stabilized formulations for outdoor storage yards.
- Automated tensioning convergence:Battery-powered friction-weld tools are integrating with IoT load-monitoring systems. Real-time break-force telemetry enables predictive replacement scheduling.
- California SB 54 EPR framework:Extended producer responsibility rules create recycled-content pull-through for strapping sold into retail distribution. Brand owners face compliance cost exposure without certified supply chains.
Industry Challenges
- Extrusion technician scarcity:PET orientation line operation requires specialized polymer rheology expertise. Training programs lag equipment deployment timelines in Southeast Asia.
- REACH SVHC documentation:Substance-of-very-high-concern declarations consume compliance bandwidth. Importers face customs delays without complete safety data sheet packages.
- Legacy steel strapping integration:Mixed-material securing protocols complicate warehouse standardization. Operations managers resist dual-inventory SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Straps Market |
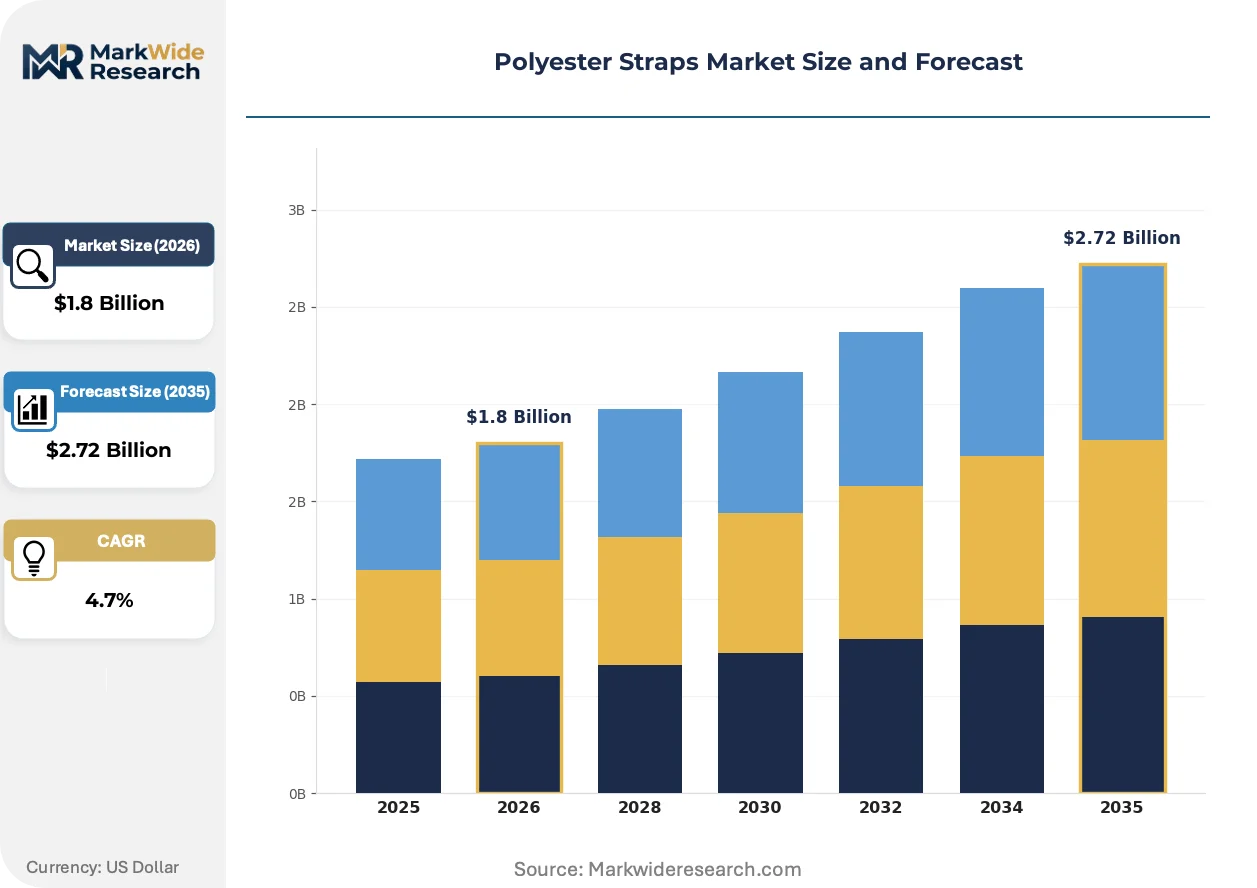
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Straps, Round Straps, Heavy-Duty Straps, Custom Straps Application: Packaging, Forming, Lifting, Securing End User: Construction, Retail, Logistics, Manufacturing Size: Small, Medium, Large, Extra Large |
| Companies Covered | FROMM Packaging, Signode, Teufelberger, Samuel Strapping, Mosca GmbH, Polychem Corporation, Crown, DuBose Strapping, GREENBRIDGE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Straps Market Strategic Shifts
Material science advances and regulatory precision are compressing product development cycles. Three forces are restructuring how polyester straps are specified, manufactured, and deployed across industrial supply chains.
High-tenacity fiber reinforcement is integrating into extruded PET formulations to achieve break strengths exceeding 2,000 kg without diameter expansion. Heavy machinery exporters in Germany and Japan are specifying these hybrid constructions for ocean container securing. The technology is integrating performance characteristics previously reserved for woven lifting slugs into commodity-priced logistics strapping.
REACH authorization requirements are forcing reformulation of antioxidant packages used in outdoor-grade strapping. ECHA scrutiny of hindered phenol stabilizers is pushing compounders toward phosphite alternatives with shorter regulatory approval histories. European construction material distributors are absorbing higher unit costs to maintain CE marking compliance for site-delivered steel products.
Consolidated buying by third-party logistics platforms is compressing supplier qualification timelines. Amazon and Shopify fulfillment networks now mandate ISO 9001 certification and 48-hour sample turnaround as baseline entry requirements. This concentration is most visible in the Yangtze River Delta, where e-commerce infrastructure investment has outpaced independent converter capacity expansion.
Polyester Straps Market Segmentation
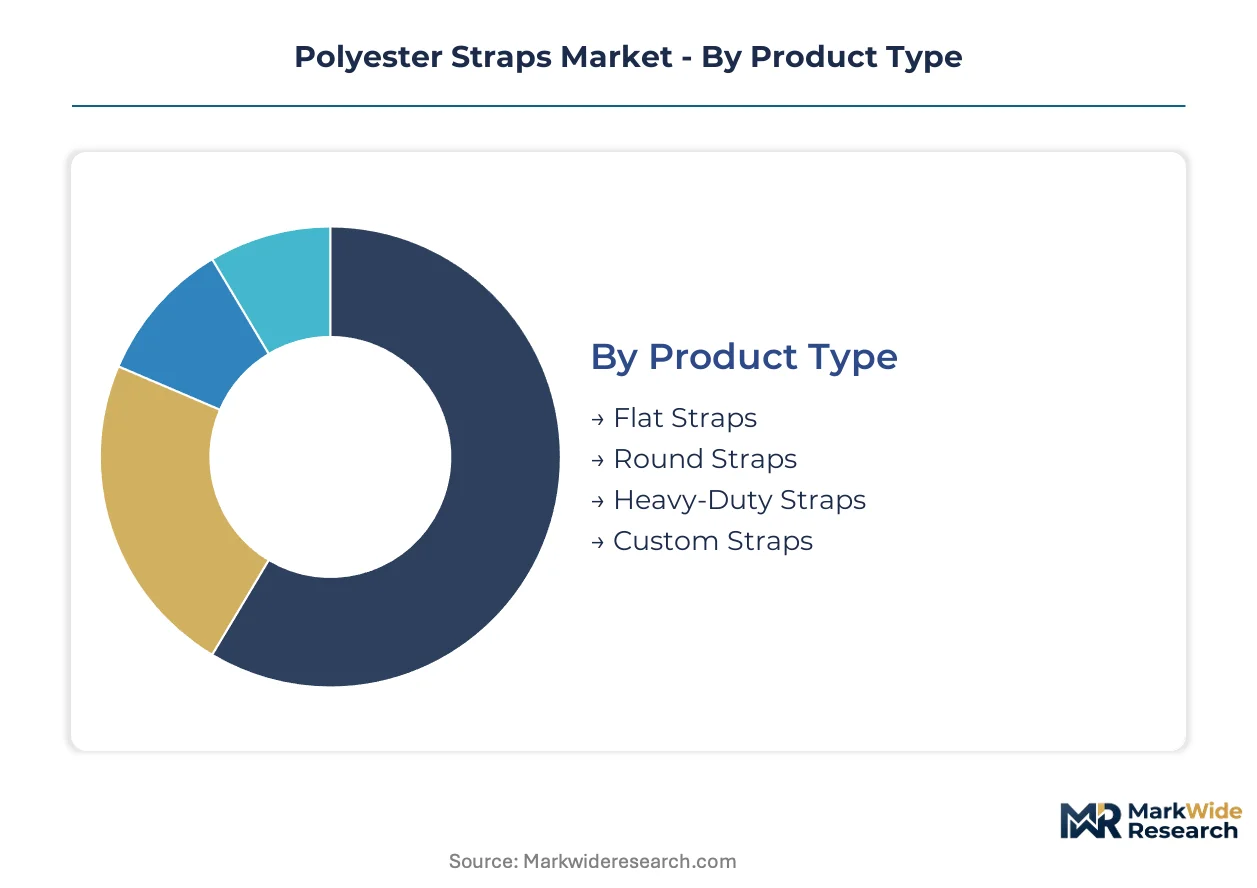
Polyester strap specification varies sharply across load requirements, equipment compatibility, and regulatory exposure. Procurement teams segment supply by performance tier first, then by integration complexity with existing warehouse automation.
Product Type:
Load-bearing capacity and equipment interface geometry drive product selection above all other variables.
- Flat Straps:Extruded PET bands with rectangular cross-sections optimize surface contact area for palletized goods. Automated tensioning systems in Chinese e-commerce fulfillment centers specify 12mm–19mm widths for compatibility with friction-weld tools. Demand concentrates where conveyor-fed strapping stations require consistent feed geometry.
- Heavy-Duty Straps:High-tenacity fiber-reinforced constructions achieve break strengths above 1,500 kg with controlled elongation recovery. German machinery exporters and Japanese steel coil distributors specify these for ocean container securing where load relaxation risks cargo shift. Premium positioning reflects material science integration previously limited to woven lifting slings.
- Round Straps:Circular cross-section extrusions suit manual tensioning applications and irregular load geometries. Construction sites in India deploy these for temporary securing where automated equipment access is limited.
- Custom Straps:Dimensional precision manufacturing serves specialized lifting operations with slippage-critical requirements. Dimensional tolerances below 0.5mm reduce failure modes in precision manufacturing supply chains.
Flat straps lead on scale; heavy-duty straps lead on momentum.
Application:
Functional deployment determines margin structure through labor intensity and equipment capital requirements.
- Securing:Transit stabilization of palletized goods represents volume concentration across logistics networks. Load containment specifications from OSHA and EU packaging directives drive certification requirements for cross-border freight.
- Packaging:Unitization and bundling operations in retail distribution centers specify break-strength ratings aligned with automated handling equipment. California SB 54 extended producer responsibility rules now shape recycled-content procurement for retail-facing supply chains.
- Lifting:Vertical load handling requires safety factor engineering beyond standard logistics ratings. Construction material distributors in Germany specify CE-marked constructions for site-delivered steel products under REACH authorization pressures.
- Forming:Shape retention during manufacturing processes serves metal fabrication and composite molding operations. Process heat exposure limits material selection to stabilized PET formulations.
Securing commands volume concentration; packaging faces the steepest compliance cost escalation.
End User:
Industry-specific load characteristics and regulatory exposure create distinct procurement patterns.
- Logistics:Third-party warehouse operators specify ISO 9001 certification and 48-hour sample turnaround as baseline entry requirements. Consolidated buying by Amazon and Shopify fulfillment networks compresses supplier qualification timelines in the Yangtze River Delta.
- Construction:Steel coil handling and heavy machinery securing demand break-strength ratings above 1,500 kg with elongation recovery properties. Site storage conditions in India require UV-stabilized formulations for outdoor exposure.
- Retail:E-commerce fulfillment density drives automated warehouse system investment. Pallet stability standards tighten as order velocities rise in Chinese distribution centers.
- Manufacturing:In-process material handling integrates strapping with production line timing. FDA food-contact rules in the United States shape product certification for packaging adjacent to consumable goods.
Logistics leads on procurement consolidation; construction shows the strongest specification escalation.
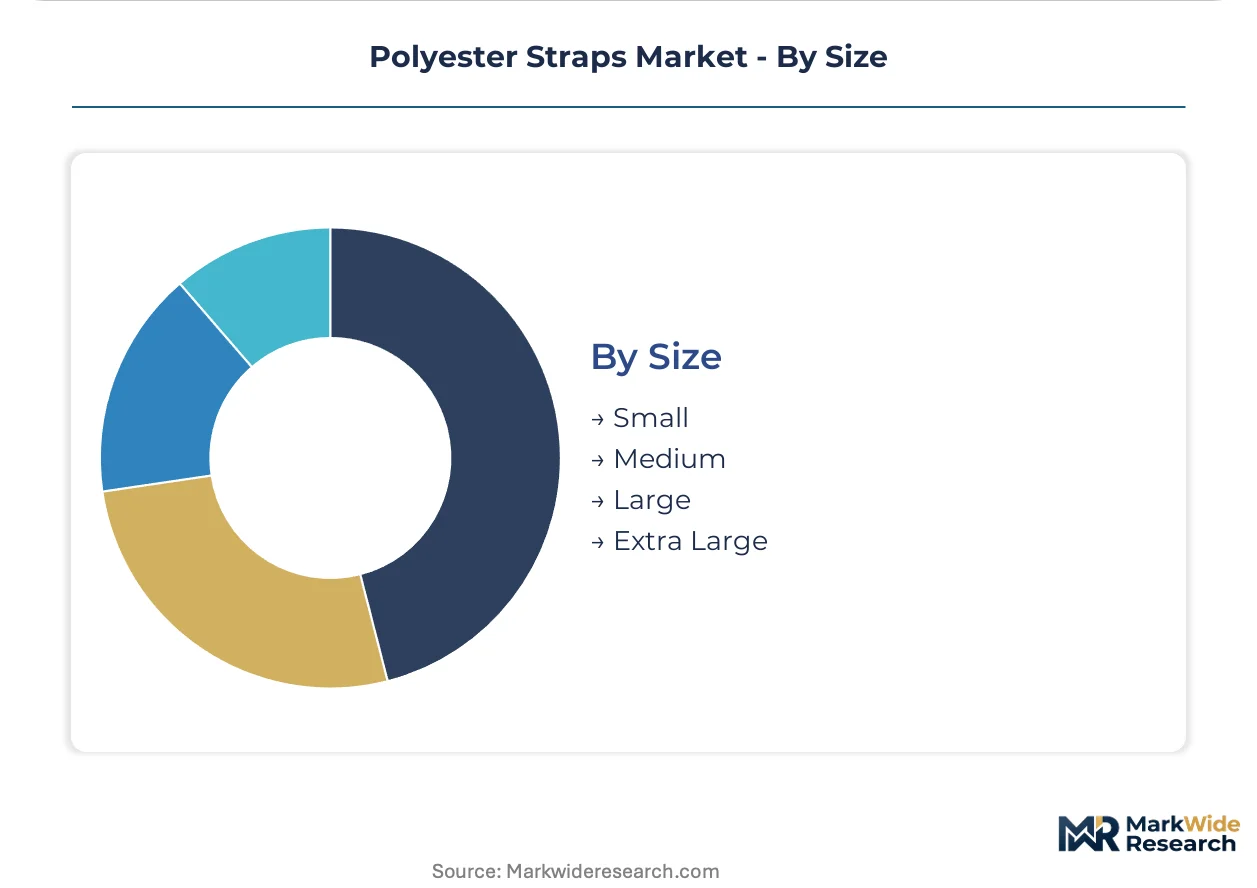
Size:
Width and thickness combinations determine equipment compatibility and unit economics at scale.
- Medium:16mm–19mm widths balance strength-to-weight ratios with automated equipment compatibility. This specification dominates European retail distribution where REACH compliance costs concentrate in mid-tier volume procurement.
- Large:25mm–32mm constructions serve heavy-load applications in steel and construction materials. German and Japanese industrial buyers specify these for export container securing.
- Small:9mm–13mm widths suit light bundling and consumer goods unitization. Manual tensioning applications in developing markets favor this specification for cost minimization.
- Extra Large:38mm+ widths address specialized heavy machinery and infrastructure component securing. Limited production runs reflect custom equipment requirements and premium pricing structures.
Medium sizes lead on procurement volume; large sizes capture the strongest specification premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer rheology technicians cluster in Germany, China, and the United States, anchoring extrusion capacity where automated warehouse investment concentrates. Regional demand patterns diverge sharply between mature logistics networks and emerging cold chain buildouts.
United States
Third-party logistics operators in the Inland Empire and Dallas-Fort Worth metroplex drive specification escalation for high-tensile securing solutions. OSHA load-secure guidelines and California SB 54 extended producer responsibility rules compress supplier qualification timelines. Amazon fulfillment networks in the Pacific Northwest now mandate ISO 9001 certification as baseline entry.
Germany
Steel coil distributors and heavy machinery exporters in the Ruhr industrial region specify break-strength ratings above 1,500 kg with elongation recovery properties. REACH authorization requirements for antioxidant packages force reformulation of outdoor-grade strapping toward phosphite stabilizers. Bavarian automotive logistics hubs absorb higher unit costs to maintain CE marking compliance.
China
E-commerce fulfillment density in the Yangtze River Delta and Pearl River Delta drives automated warehouse system investment at unprecedented scale. Dual carbon goals and national packaging waste regulations push converters toward rPET formulations. Pallet stability standards tighten as order velocities rise in Shanghai and Hangzhou distribution centers.
India
Cold chain infrastructure buildout in Maharashtra and Gujarat creates demand for moisture-resistant securing solutions with UV stabilization. The Bureau of Indian Standards tightens material certification for retail supply chain entry. Third-party logistics providers in the Delhi-Mumbai Industrial Corridor specify outdoor storage yard compatibility.
Japan
Precision manufacturing supply chains in the Chubu and Kansai regions demand dimensional tolerances below 0.5mm for slippage-critical applications. METI circular economy directives accelerate post-industrial PET collection network development. Osaka-based steel distributors specify hybrid fiber-reinforced constructions for export container securing.
Polyester Straps Market Competitive Environment
The competitive structure tilts toward vertically integrated packaging conglomerates with captive resin supply. Tier-one players control margin through backward integration into purified terephthalic acid procurement, while mid-scale specialists defend position through regional extrusion density. Three archetypes dominate: integrated multinational packaging systems, fiber-technology specialists leveraging textile heritage, and regional converters serving single-country logistics networks. Capacity expansion and strategic partnerships represent the dominant competitive moves, with extrusion line deployment timelines compressing in Southeast Asia.
Among integrated packaging systems, FROMM Packaging and Signode exemplify the scale-driven archetype with multi-continental manufacturing footprints. Teufelberger occupies a position within the fiber-technology specialist tier, drawing on rope and lifting sling heritage to serve heavy-load applications. Samuel Strapping anchors the North American regional converter category, representing supply security through dedicated recycling stream control.
| Leading Market Players |
|---|
| FROMM Packaging |
| Signode |
| Teufelberger |
| Samuel Strapping |
| Mosca GmbH |
| Polychem Corporation |
| Crown |
| DuBose Strapping |
| GREENBRIDGE |
| Others |
Value Chain & Pricing Dynamics
Consolidated procurement by Amazon and Shopify fulfillment networks concentrates buyer power across the Yangtze River Delta, compressing margins for converters while rewarding ISO 9001-certified suppliers with contract stability. This procurement concentration forces a bifurcated pricing model where automated-tensioning-compatible specifications command premiums over manual-application commodity grades.
Pricing Analysis
Bundled equipment-and-consumable contracts dominate automated warehouse deployments, while unbundled spot purchasing persists in construction and manual handling segments. Three-tier pricing structure across premium, standard, and economy levels separates fiber-reinforced heavy-duty straps from flat extrusion grades and basic round constructions. Cost compression in standard-grade flat straps is intensifying because PTA feedstock volatility transmits directly to converter margins. Third-party logistics platforms show least price sensitivity due to total-cost-of-ownership framing, whereas Indian construction distributors remain most sensitive, prioritizing per-meter cost over elongation recovery specifications.
Supply Chain Analysis
ISO 9001 and REACH SVHC documentation requirements gate supplier qualification, extending lead times for new market entrants. Extrusion capacity concentrates in China, Germany, and the United States, with specialized polymer rheology technicians anchoring production in these clusters. Raw material supply draws from purified terephthalic acid producers, recycled PET collection networks, and phosphite stabilizer compounders. Single-source vulnerability in hindered phenol antioxidant supply creates reformulation risk for outdoor-grade strapping. Distribution runs through packaging systems integrators, industrial distributors, and direct mill relationships to end-use facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyester straps market functions as a stable compounder, with steel-to-PET substitution in logistics networks providing durable volume expansion regardless of cyclical industrial fluctuations.
For Market Incumbents: Lock in rPET supply agreements ahead of EU Green Deal packaging mandate enforcement, securing feedstock advantage as recycled-content thresholds tighten. Deepen backward integration into post-industrial PET collection networks in Germany and Japan, where infrastructure gaps threaten competitor margin stability. Prioritize extrusion technician training programs in Southeast Asia, where equipment deployment outpaces qualified labor supply. For New Entrants and Emerging Players: California SB 54 in the United States opens a window for certified recycled-content suppliers to capture retail distribution chain contracts facing extended producer responsibility compliance exposure. Target cold chain infrastructure buildout in Maharashtra and Gujarat, where moisture-resistant UV-stabilized specifications face limited qualified domestic supply. Lead with battery-powered friction-weld tool integration services, bundling equipment expertise with consumable supply to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Packaging systems conglomerates are the most active acquirer in this space, seeking captive strapping supply to complement equipment portfolios. The five-to-ten-year viability window favors targets with demonstrated REACH documentation capability and established e-commerce logistics customer relationships. Monitor PTA spot market volatility as inflection indicator—sustained feedstock cost elevation accelerates consolidation toward vertically integrated players with captive resin supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Supply | Secures feedstock advantage as EU Green Deal mandates tighten recycled-content thresholds for retail supply chains. |
| Automated Tensioning Equipment Integration | Captures IoT load-monitoring convergence demand from Amazon and Shopify fulfillment networks in the Yangtze River Delta. |
| REACH-Compliant Antioxidant Reformulation | Maintains CE marking access for German steel coil distributors facing ECHA scrutiny of hindered phenol stabilizers. |
| Extrusion Capacity Expansion in Southeast Asia | Addresses technician scarcity while positioning for India warehousing expansion and third-party logistics growth. |
| Post-Industrial PET Collection Network Development | Closes loop for strap-to-strap recycling, responding to METI circular economy directives in Japanese precision manufacturing supply chains. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory and trade databases. Primary interviews engaged procurement directors at third-party logistics operators, plant managers at PET extrusion facilities, technical R&D leads at packaging systems integrators, and compliance officers navigating REACH and FDA certification pathways. Secondary sources included customs and trade flow data, SEC filings from listed packaging conglomerates, ECHA substance registration databases, and Bureau of Indian Standards certification records. Bottom-up demand modeling triangulated against top-down macroeconomic industrial production indices.
Granularity-level framing applied product type, application, end user, and size dimensions at the country level, with regional regulatory clusters modeled separately for REACH, FDA, and dual carbon goal compliance scenarios. CAGRs derived from weighted average of historical trend extrapolation and driver-based elasticity modeling across the projection horizon. Industry-specific forecast inputs incorporated e-commerce order velocity data from Chinese distribution centers and steel coil export volume projections from German machinery exporters.
Revisions become necessary when crude oil volatility disrupts PTA feedstock pricing, regulatory enforcement timelines shift for EU packaging mandates, or bio-based material substitution accelerates beyond trial placement thresholds. Forecasts reflect assumptions about recycling infrastructure development pace and automated warehouse investment continuity. A model refresh is warranted upon material change in consolidated buyer procurement concentration or REACH authorization substance lists.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Middle-East and Africa Aramid Fiber Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
High Temperature Fiber Market