
 Short Cut Polyester Fiber Market | 2026-2036
Short Cut Polyester Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Short Cut Polyester Fiber Market Insights
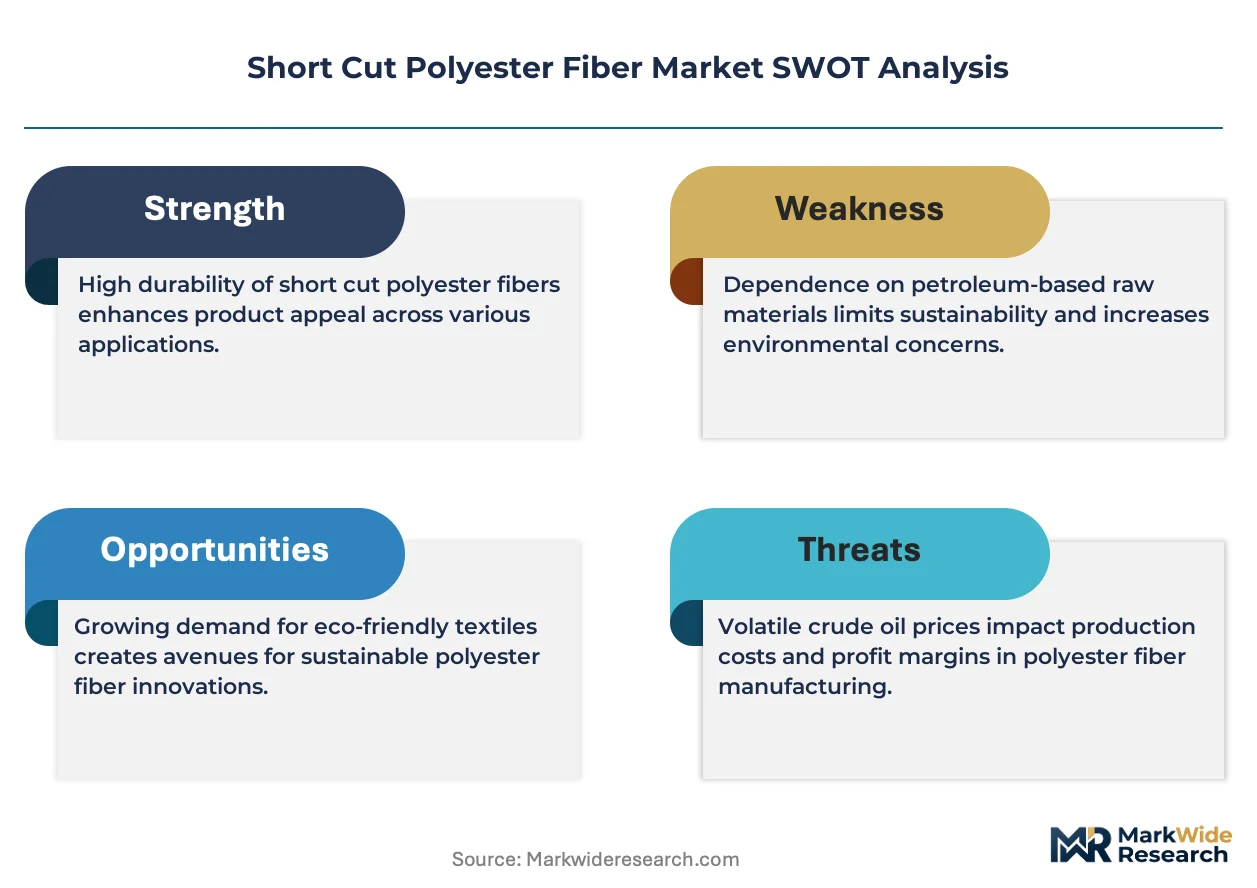
Recycled PET feedstock integration is rewriting the cost structure and carbon footprint of staple-grade production. Indorama Ventures leverages its bottle-to-fiber recycling infrastructure across Southeast Asian plants to secure lower-cost rPET flake supply. Toray Industries anchors its position through high-tenacity filament grades engineered for automotive airbag and tire cord applications. Reliance Industries dominates the South Asian supply base with backward integration into purified terephthalic acid and monoethylene glycol production.
Short cut polyester fiber denotes chopped synthetic filaments, typically 3-25 millimeters in length, manufactured through melt-spinning of polyethylene terephthalate followed by precision cutting; these fibers reinforce cementitious matrices, bond nonwoven webs, and impart dimensional stability to needle-punched geotextiles. Staple fiber commands the largest volume share across carpet backing and hygiene nonwoven end uses, while composite fiber configurations containing bicomponent sheath-core structures capture expanding margin pools in thermal-bonded automotive insulation. The filament segment leads industrial fabric penetration where high-modulus reinforcement replaces glass fiber in select gasket and friction material formulations.
REACH restrictions on microplastic shedding from textile washing cycles are pressuring European formulators to certify biodegradability claims through ECHA-recognized testing protocols. China's MEE enforcement of dual carbon goals is accelerating energy-efficiency audits at Yangtze River Delta chemical fiber complexes, effectively filtering out smaller melt-spinning operations unable to upgrade thermal oxidizer systems. In the United States, EPA effluent guidelines for synthetic fiber manufacturing are tightening discharge limits for antimony catalyst residues, raising compliance capital requirements for new extrusion capacity. Stakeholders must monitor how regional carbon border adjustments reshape the cost competitiveness of imported staple versus domestically recycled filament supply.
Market Dynamics
The short cut polyester fiber market is experiencing a fundamental restructuring as China's dual carbon goals force a migration from virgin polymer production toward recycled PET feedstock integration, compressing margins for conventional melt-spinning operations while rewarding vertically integrated recyclers with captive flake supply.
Growth Catalysts
- Automotive lightweighting mandates:OEM specifications for nonwoven interior components are expanding staple fiber reinforcement applications as manufacturers seek to reduce vehicle mass.
- REACH microplastic restrictions:European formulators are certifying biodegradable fiber grades through ECHA-recognized protocols, creating certified product premiums in textile and hygiene applications.
- Jiangsu province cluster concentration:Chemical fiber manufacturing agglomeration near Shanghai generates feedstock proximity advantages and shared thermal oxidizer infrastructure.
Market Restraints
- Antimony catalyst residue compliance:EPA effluent guidelines are tightening discharge limits for synthetic fiber manufacturing, raising capital requirements for new extrusion capacity in the United States.
- rPET flake supply volatility:Collection infrastructure gaps in Southeast Asia create feedstock price instability for producers dependent on bottle-to-fiber recycling streams.
- Glass fiber substitution persistence:High-modulus industrial applications in gaskets and friction materials retain incumbent mineral fiber specifications due to established performance benchmarks.
Strategic Opportunities
- Carbon border adjustment positioning:EU CBAM implementation creates cost advantages for European domestic recycled filament versus imported virgin staple from carbon-intensive production.
- Bicomponent thermal bonding:Sheath-core fiber configurations are capturing expanding margin pools in automotive insulation applications requiring controlled melt behavior.
- Geotextile infrastructure deployment:Needle-punched stabilization fabrics for civil engineering projects represent underpenetrated demand in India's national highway expansion program.
Industry Challenges
- Thermal oxidizer upgrade timelines:China's MEE enforcement of energy-efficiency audits is filtering smaller melt-spinning operations unable to meet compressed compliance deadlines.
- Cross-contamination control in rPET processing:Bottle sorting and flake washing protocols require capital-intensive automation to meet automotive-grade quality specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Cut Polyester Fiber Market |
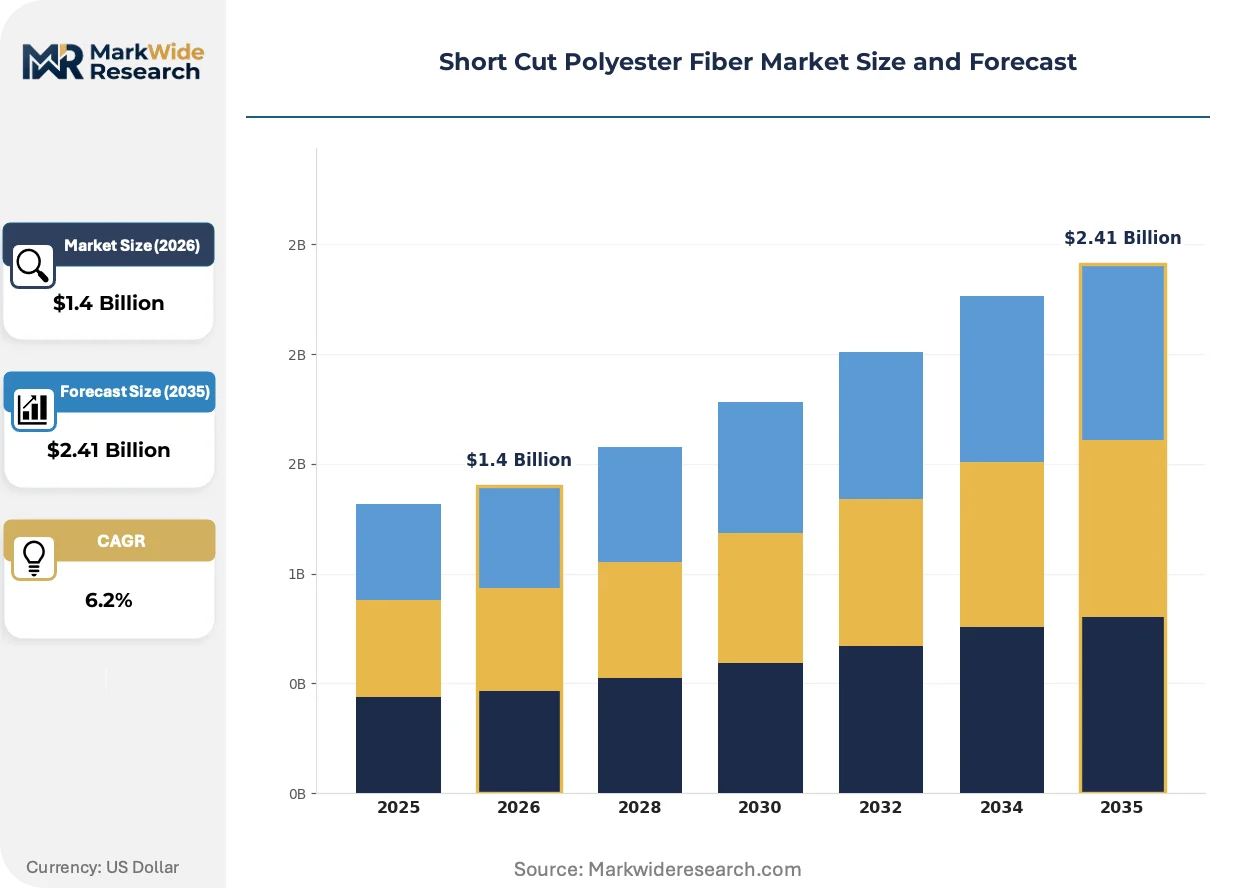
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament Fiber, Staple Fiber, Continuous Fiber, Composite Fiber End User: Textile Industry, Automotive Sector, Home Furnishings, Personal Care Application: Carpets, Upholstery, Apparel, Industrial Fabrics Form: Solid Fiber, Crimped Fiber, Dyed Fiber, Biodegradable Fiber |
| Companies Covered | Indorama Ventures Public Company Limited, Toray Industries, Inc., Reliance Industries Limited, Alpek S.A.B. de C.V., Sinopec Yizheng Chemical Fibre Company Limited, Hyosung Corporation, Nan Ya Plastics Corporation, Far Eastern New Century Corporation, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Cut Polyester Fiber Market Trends and Innovations
Digital process control and closed-loop recycling infrastructure are converging to transform quality assurance and feedstock traceability across staple and filament production lines. Three developments are reshaping competitive positioning.
Machine vision sorting is digitizing contamination detection in post-consumer PET flake streams. Automotive tier-one suppliers are mandating 99.97% purity certifications for airbag and tire cord applications. This technology is digitizing quality control workflows that previously required manual laboratory sampling, compressing batch release cycles from days to hours.
China's GB standards for chemical fiber energy intensity are tightening virgin polymer production allowances. The country's MEE enforcement mechanisms are accelerating facility consolidation across the Yangtze River Delta. Staple-grade producers with backward integration into PTA and MEG production face the steepest carbon audit exposure.
Buyer consolidation among hygiene nonwoven roll goods manufacturers is compressing supplier qualification timelines. Tier-one converters are unbundling technical service contracts from volume commitments, forcing fiber producers to demonstrate continuous melt index consistency through cloud-based batch data sharing. This behavioral shift is most visible in European diaper and feminine hygiene supply chains where sustainability scorecards now outweigh price in annual vendor reviews.
Short Cut Polyester Fiber Market Segmentation
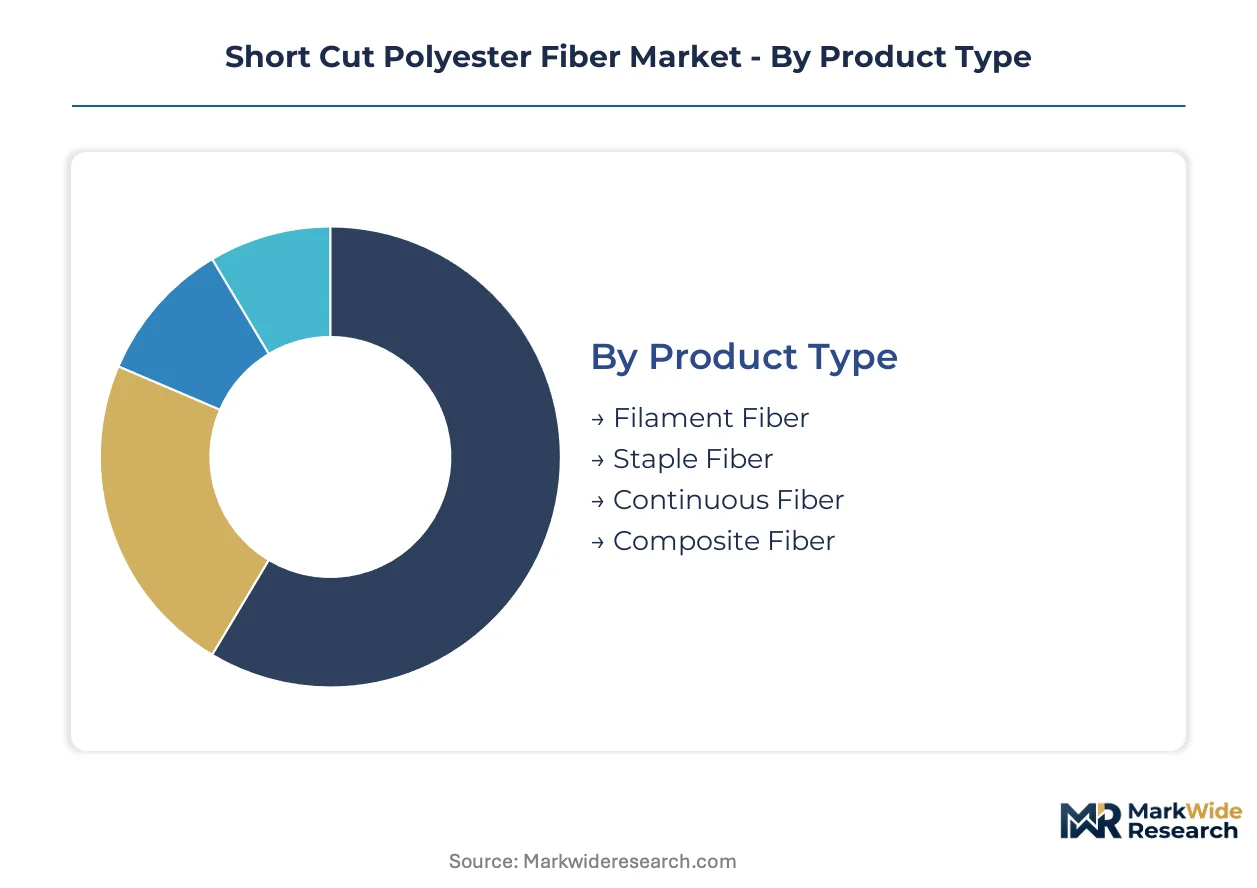
Segmentation in short cut polyester fiber markets reveals divergent margin structures and qualification timelines. Staple grades for hygiene nonwovens turn inventory weekly, while automotive filament contracts lock specifications for multi-year platform lifecycles.
Product Type:
Cycle times compress from filament precision runs to staple bulk production, with composite fibers occupying the middle ground for thermal-bonding trials.
- Filament Fiber:Continuous extrusion yields high-tenacity monofilaments engineered for tire cord and airbag fabric reinforcement. Demand concentrates in automotive supply chains where Toray Industries and Indorama Ventures qualify batches against OEM specifications spanning 18-36 month development cycles.
- Staple Fiber:Chopped filaments ranging 3-25 millimeters dominate carpet backing and hygiene nonwoven applications. Jiangsu province chemical fiber clusters supply roll goods manufacturers with 2-4 week order-to-delivery cycles, though rPET feedstock volatility is compressing margins for non-integrated producers.
- Continuous Fiber:Uncut filament tows serve industrial yarn spinning and direct roving applications.
- Composite Fiber:Bicomponent sheath-core structures enable controlled melt behavior in thermal-bonded automotive insulation.
Staple fiber anchors the volume base while composite fiber gains share at the steepest rate.
End User:
Cost tiers separate specification-grade automotive contracts from commodity textile procurement, with personal care occupying the premium sustainability tier.
- Textile Industry:Spinning mills consume staple fiber for blended yarn production serving apparel and home textile weavers. China's GB standards for chemical fiber energy intensity are forcing consolidation among smaller mills in the Yangtze River Delta.
- Automotive Sector:Tier-one suppliers mandate 99.97% purity certifications for safety-critical applications including airbag housings and tire reinforcement. Machine vision sorting infrastructure is digitizing contamination detection to compress batch release cycles.
- Home Furnishings:Carpet backing and upholstery filling applications prioritize bulk density and crimp retention over tensile performance.
- Personal Care:Diaper and feminine hygiene nonwoven manufacturers in Europe now weight sustainability scorecards above price in annual vendor reviews.
Automotive sector contracts command the highest margin tier while personal care applications are expanding most quickly on biodegradability certification premiums.
Application:
Volume concentration in carpet backing contrasts with specification intensity in industrial fabric penetration.
- Carpets:Primary and secondary backing layers consume bulk staple fiber with recycled PET integration rising on cost and carbon footprint advantages. Jiangsu province manufacturing clusters supply domestic Chinese carpet mills and export markets through Shanghai port infrastructure.
- Industrial Fabrics:High-modulus reinforcement replaces glass fiber in select gasket and friction material formulations where polyester offers processing advantages. REACH microplastic restrictions are pressuring European formulators to certify biodegradability claims through ECHA-recognized protocols.
- Upholstery:Furniture and automotive seating applications demand crimped fiber configurations for resilience and hand feel.
- Apparel:Blended yarn spinning for outerwear and technical clothing utilizes staple fiber with controlled shrinkage properties.
Carpet applications anchor the volume base while industrial fabrics climb the fastest on substitution dynamics.
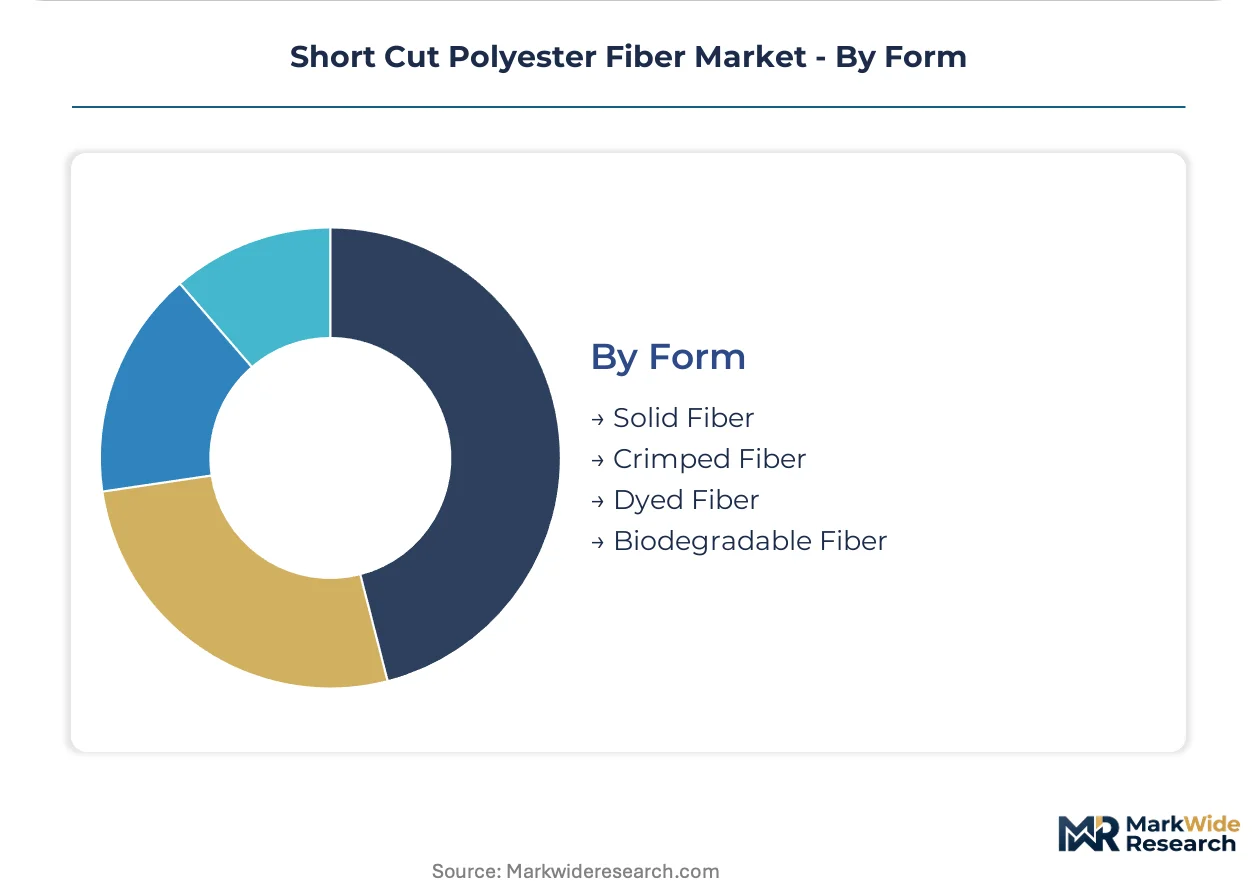
Form:
Supply concentration in solid fiber standard grades contrasts with emerging capacity investments in biodegradable variants.
- Solid Fiber:Uncrimped, undyed base material serves downstream processing including texturing, dyeing, and cutting operations. Yangtze River Delta chemical fiber complexes produce solid fiber at scale with shared thermal oxidizer infrastructure.
- Biodegradable Fiber:Modified PET copolymers and additive packages enable enhanced degradation pathways certified under ECHA-recognized testing protocols. European hygiene nonwoven manufacturers are qualifying these grades for diaper and feminine hygiene applications ahead of anticipated microplastic restrictions.
- Crimped Fiber:Mechanical or chemical texturing imparts bulk and resilience for filling and insulation applications.
- Dyed Fiber:Solution-dyed or stock-dyed variants reduce downstream water consumption and color variation in carpet and textile applications.
Solid fiber anchors the volume base while biodegradable fiber gains share at the steepest rate on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports short cut polyester fiber to automotive OEMs in Germany and hygiene converters in the United States, while importing specialty high-tenacity grades from Japan for safety-critical applications.
China
Automotive lightweighting and hygiene nonwoven roll goods drive consumption across Jiangsu province chemical fiber clusters. The Ministry of Ecology and Environment enforces dual carbon goals through energy-efficiency audits that filter smaller melt-spinning operations. Yangtze River Delta manufacturing complexes near Shanghai consolidate capacity as shared thermal oxidizer infrastructure raises entry barriers.
United States
Carpet backing mills in Georgia and automotive tier-one suppliers in Michigan anchor domestic offtake. The EPA tightens effluent guidelines for antimony catalyst residues in synthetic fiber manufacturing, elevating compliance capital requirements. Southeast regional spinning operations face cost pressure from rPET flake supply volatility.
Germany
Automotive airbag fabric weavers and industrial gasket formulators specification-grade demand. REACH microplastic restrictions pressure certification through ECHA-recognized biodegradability testing protocols. Bavaria-based technical textile converters qualify fiber batches against multi-year OEM platform lifecycles.
India
Geotextile deployment for national highway expansion and carpet backing for export markets concentrate demand. The Bureau of Indian Standards enforces quality benchmarks for infrastructure-grade synthetic fibers. Gujarat chemical fiber corridors supply domestic textile mills while Maharashtra-based converters serve automotive seating applications.
Japan
High-tenacity filament for tire cord and airbag reinforcement commands premium positioning. METI industrial standards govern automotive safety-critical fiber specifications. Chubu region manufacturing complexes near Nagoya maintain technical leadership in precision melt-spinning for industrial yarn applications.
Short Cut Polyester Fiber Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated petrochemical conglomerates and specialty fiber engineers with captive recycling infrastructure. Three archetypes dominate: Southeast Asian bottle-to-fiber recyclers leveraging rPET flake supply chains, Japanese high-tenacity specialists serving automotive safety specifications, and South Asian PTA-MEG backward-integrated producers. Competitive moves center on thermal oxidizer upgrades for regulatory compliance and bicomponent capacity expansion for automotive insulation margins.
Among Asia-Pacific-based conglomerates, Indorama Ventures Public Company Limited exemplifies the integrated recycler archetype with Southeast Asian flake supply infrastructure. Toray Industries, Inc. and Teijin Limited occupy positions within the Japanese high-tenacity specialist tier, anchoring automotive filament qualification pipelines. Reliance Industries Limited represents South Asian backward-integrated supply, while Far Eastern New Century Corporation and Nan Ya Plastics Corporation sit within Taiwan-based technical fiber manufacturing.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Toray Industries, Inc. |
| Reliance Industries Limited |
| Alpek S.A.B. de C.V. |
| Sinopec Yizheng Chemical Fibre Company Limited |
| Hyosung Corporation |
| Nan Ya Plastics Corporation |
| Far Eastern New Century Corporation |
| Teijin Limited |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province's chemical fiber manufacturing cluster concentrates PTA and MEG feedstock supply within a 200-kilometer radius of Shanghai port infrastructure, concentrating margin capture among producers with captive flake sorting and shared thermal oxidizer assets while forcing non-integrated competitors toward price-taker positions in staple-grade spot markets.
Pricing Analysis
Conventional melt-spun staple fiber trades at commodity spot benchmarks against rPET-integrated grades that command certification premiums. Three-tier pricing structure across automotive-grade filament, hygiene-certified staple, and industrial commodity bulk separates Toray Industries' airbag specifications from Jiangsu cluster carpet backing supply. Cost compression in virgin polymer production is intensifying because China's MEE energy-efficiency audits filter smaller melt-spinning operations. Hygiene nonwoven converters in Europe show least price sensitivity as sustainability scorecards outweigh annual vendor reviews.
Supply Chain Analysis
rPET flake supply draws from Southeast Asian bottle collection infrastructure, purified terephthalic acid from Reliance Industries' Gujarat corridors, and high-tenacity filament from Toray's Chubu region complexes. Raw material dependencies center on post-consumer PET bale quality, antimony catalyst chemistry, and bicomponent polymer formulations. Single-source vulnerability concentrates in automotive airbag certification pipelines where 18-36 month OEM qualification timelines lock tier-one suppliers. Distribution runs through Shanghai port export terminals for Chinese staple, Nagoya technical textile hubs for Japanese filament, and Rotterdam chemical fiber terminals for European hygiene converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recycled PET feedstock integration and China's dual carbon enforcement are compressing conventional melt-spinning margins while rewarding vertically integrated recyclers, creating a high-growth disruption window for stakeholders with captive flake infrastructure.
For Market Incumbents: Insulate automotive filament qualification pipelines through machine vision sorting investments that compress batch release cycles from days to hours. Secure captive rPET flake supply via Southeast Asian bottle-to-fiber recycling infrastructure before collection infrastructure gaps widen feedstock price volatility. Thermal oxidizer upgrades at Yangtze River Delta complexes represent the critical compliance lever against MEE enforcement timelines. For New Entrants and Emerging Players: India's national highway expansion program for geotextile stabilization fabrics represents the most penetrable entry point among underqualified civil engineering specifications. European biodegradable fiber certification ahead of REACH microplastic restrictions offers white-space margin capture in diaper and feminine hygiene supply chains. Partner with automotive tier-one suppliers on bicomponent thermal-bonding trials for insulation applications requiring controlled melt behavior. For Investors and Strategic Acquirers: Capital is best deployed toward Southeast Asian bottle-to-fiber recyclers with established flake washing automation and automotive-grade purity certifications. Long-term viability across the analysis window favors producers with backward integration into PTA and MEG chemistry insulated from virgin polymer carbon audit exposure. Monitor EU CBAM implementation timelines as the inflection signal reshaping cost competitiveness of imported versus domestically recycled filament supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Supply | Captive bottle-to-fiber recycling infrastructure secures lower-cost feedstock against Southeast Asian collection volatility. |
| Thermal Oxidizer System Upgrades | China's MEE energy-efficiency audits filter non-compliant melt-spinning operations across Yangtze River Delta complexes. |
| Bicomponent Capacity Expansion | Sheath-core fiber configurations capture margin pools in automotive insulation applications requiring controlled melt behavior. |
| Biodegradability Certification Investment | ECHA-recognized testing protocols unlock premium positioning in European hygiene nonwoven supply chains ahead of microplastic restrictions. |
| Machine Vision Sorting Deployment | Automotive tier-one suppliers mandate 99.97% purity certifications compressing batch release cycles for airbag and tire cord applications. |
Research Methodology
Desk research of customs trade databases, chemical industry association filings, and SEC 10-K disclosures preceded structured interviews with plant managers at Jiangsu province melt-spinning complexes, procurement leads at European hygiene nonwoven converters, automotive tier-one supplier quality directors, and technical R&D heads at bicomponent fiber engineering divisions. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Assumptions held China's dual carbon enforcement trajectory and EU CBAM implementation fixed while varying rPET collection infrastructure development rates and automotive lightweighting specification adoption curves. Segmentation dimensions modeled include product type tier, end-use industry vertical, application specification intensity, and regional production hub cluster. CAGRs derived from historical volume elasticities applied to projected feedstock cost shifts and regulatory compliance capital requirements.
Practitioners should monitor MEE audit enforcement intensity, REACH microplastic restriction finalization, and Southeast Asian bottle collection infrastructure investment for early signals requiring forecast revision. Cross-checking against EIA petrochemical feedstock cost benchmarks and IHS Markit automotive production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Polypropylene Fiber Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
Extruded PLA Fiber Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
Melt Spun Fibers Market