
 High End Synthetic Suede Market | 2026-2036
High End Synthetic Suede Market Size, Share, and Industry Trends Forecast 2026-2036
High End Synthetic Suede Market Intelligence
Multi-source procurement for ultra-fine polyester microfiber is recalibrating how automotive OEMs and fashion houses secure premium synthetic suede volumes. Toray Industries leverages its polymer science heritage to sustain leadership in ultra-microfiber substrates. Asahi Kasei dominates Japan's technical textile ecosystem through captive filament production. Kuraray anchors European supply chains with specialized aliphatic polyurethane coatings for luxury upholstery applications.
High end synthetic suede denotes engineered non-woven or woven textiles composed of ultra-fine denier polyester, polyamide, or polyurethane microfibers with pile densities exceeding 100,000 fibers per square centimeter, manufactured through needle-punching, impregnation, and buffing processes to replicate natural suede's tactile and aesthetic properties for premium industrial and consumer applications. Microfiber variants command the deepest margin pools due to technical complexity and automotive certification requirements, while eco-suede formulations are displacing conventional solvent-based materials as REACH compliance tightens across European supply chains. Fashion accessories and automotive interiors represent the most structurally differentiated application segments, with footwear serving as the volume foundation where price competition intensifies.
REACH, ECHA, and the EU Green Deal collectively mandate phased reductions in dimethylformamide solvent use across synthetic leather manufacturing, reshaping process chemistry investments and supplier qualification timelines. Japan's METI enforces JIS standards for volatile organic compound emissions in automotive interior materials, creating dual compliance burdens for exporters serving both European and Japanese OEM programs. Stakeholders must monitor regulatory divergence between Asian production hubs and European end-markets to anticipate reformulation costs and qualification delays.
Market Dynamics
REACH solvent restrictions and the EU Green Deal are forcing polyester microfiber manufacturers toward water-based polyurethane impregnation systems, compressing qualification timelines for automotive OEM supplier programs.
Growth Catalysts
- Automotive Interior Premiumization:Luxury OEMs specify synthetic suede for dashboard wraps, headliners, and seat inserts to reduce weight while maintaining tactile quality. German Tier 1 suppliers anchor this demand corridor.
- REACH Phase-Out Mandates:Dimethylformamide solvent restrictions under ECHA regulations accelerate investment in aqueous coating lines. European manufacturers gain first-mover certification advantages for export markets.
- Ultra-Microfiber Technical Barriers:Sub-0.1 denier filament production requires specialized melt-blowing equipment. Captive polymer science capabilities at Japanese and Korean chemical conglomerates concentrate supply among qualified substrate producers.
Market Restraints
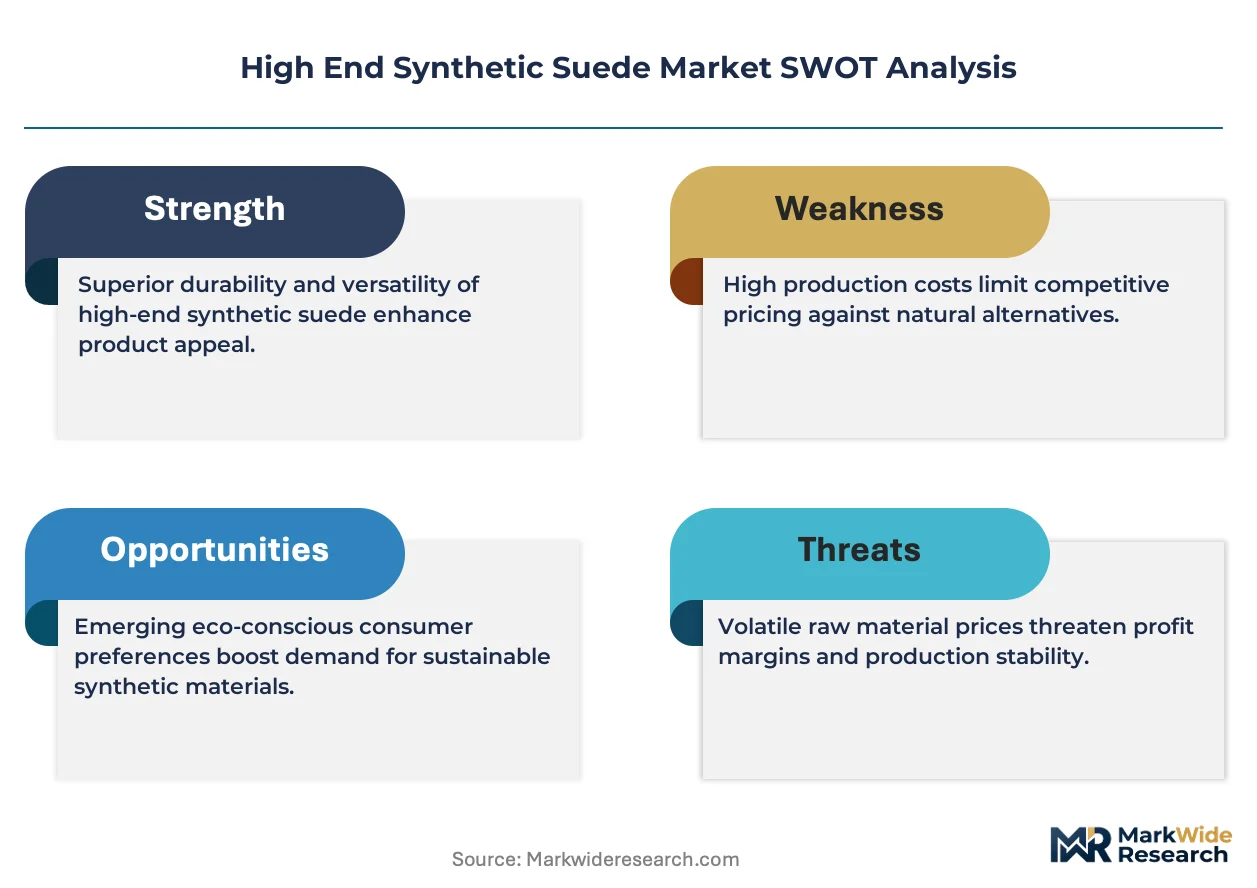
- Petrochemical Input Volatility:Purified terephthalic acid and ethylene glycol prices track crude oil benchmarks. Margin compression intensifies for non-integrated converters lacking backward polymer control.
- East Asian Supply Concentration:Over 70 percent of ultra-fine microfiber substrate capacity clusters in Zhejiang Province and Gyeongsang regions. Single-source dependency creates disruption exposure from port congestion or energy rationing.
- Natural Leather Substitution Resistance:Italian luxury fashion houses maintain material heritage commitments. Full-grain leather retains preference for iconic handbag lines despite synthetic suede technical parity.
Strategic Opportunities
- India Automotive Localization:Maruti Suzuki and Hyundai Motor India expand domestic sourcing mandates under PLI scheme incentives. Technical textile investments in Tamil Nadu and Gujarat address import substitution gaps.
- Marine and Aviation Upholstery:IMO fire-resistance standards and FAA burn-test certifications create premium application white space. Flame-retardant synthetic suede formulations command certification premiums over automotive grades.
- Bio-Based Polyurethane Feedstocks:Castor oil-derived isocyanates and plant-based polyols align with EU Green Deal circular economy targets. Early formulation adopters secure sustainability credential differentiation.
Industry Challenges
- Specialized Coating Engineer Scarcity:Water-based polyurethane formulation expertise resides with a narrow cohort of European and Japanese technical specialists. Talent migration lags behind plant capacity expansion.
- Automotive Qualification Timelines:OEM material approval cycles span 18 to 36 months for interior trim applications. Accelerated solvent-transition investments face delayed revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High End Synthetic Suede Market |
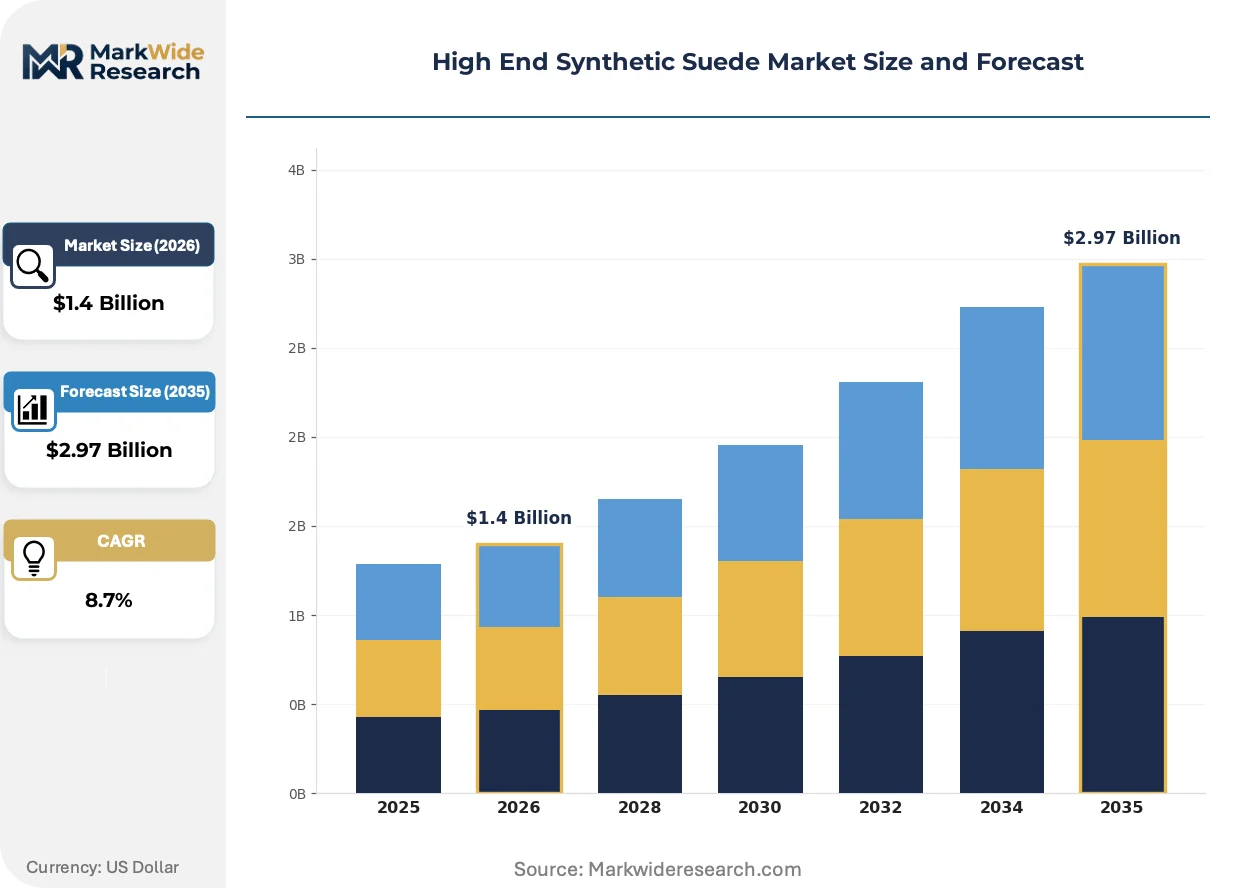
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiber, Ultra-suede, Eco-suede, Velvet Suede Application: Footwear, Upholstery, Fashion Accessories, Automotive Interiors End User: Fashion Brands, Furniture Manufacturers, Automotive OEMs, Retailers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Teijin Limited, Majilite Inc., Toray Industries, Inc., WINIW International Co., Limited, The Mitchell Group, Asahi Kasei Corporation, Seiren Co., Ltd., Zhejiang Meisheng New Material Co., Ltd., Kuraray Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High End Synthetic Suede Market Strategic Shifts & Innovations
Process automation and regulatory chemistry reform are converging to redefine synthetic suede manufacturing economics. Technical differentiation now hinges on precision engineering rather than commodity scale.
Closed-loop needle-punching lines with real-time pile density monitoring are automating quality consistency previously dependent on manual buffing inspection. Korean automotive textile suppliers deploy these systems to meet zero-defect PPAP thresholds. Labor content compression enables European producers to defend regional supply positions against lower-wage competitors.
ECHA restrictions on N-methyl-2-pyrrolidone under REACH SVHC candidate listing are forcing coating line retrofits before 2027 enforcement deadlines. German upholstery manufacturers accelerate capital deployment toward supercritical CO2 dyeing systems. Waterless processing eliminates effluent treatment burdens while reducing energy intensity per linear meter.
Automotive OEMs now mandate recycled content certificates for interior materials under CSRD supply chain disclosure rules. Procurement teams at Stuttgart and Munich headquarters require third-party mass-balance verification for polyester microfiber substrates. Italian fashion houses lag this standard, creating bifurcated specification landscapes between mobility and apparel end-uses.
High End Synthetic Suede Market Segmentation
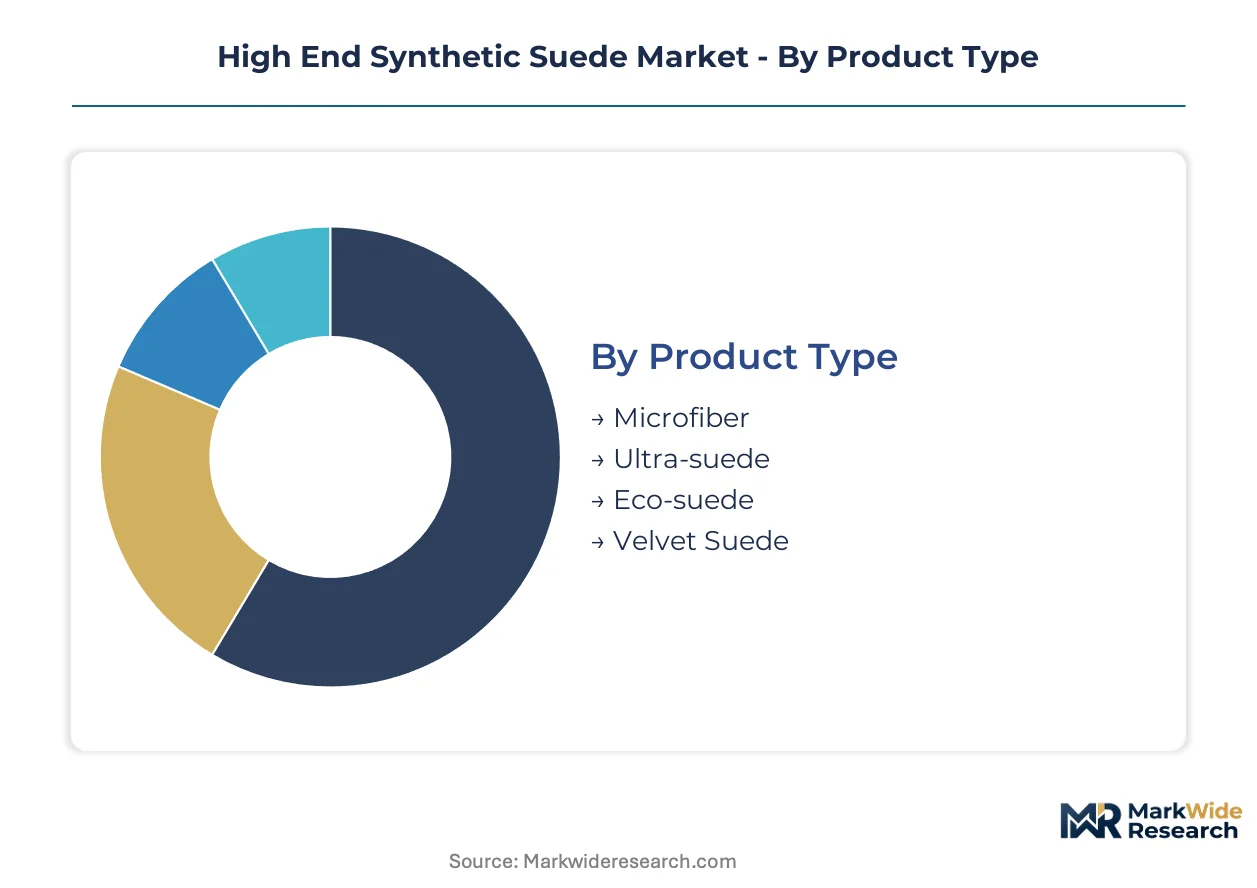
High end synthetic suede suppliers configure production lines around distinct technical specifications and buyer procurement rhythms. Each segmentation dimension reveals divergent margin structures and qualification barriers that reshape competitive positioning across automotive, fashion, and furniture verticals.
Product Type:
Buyers differentiate primarily by fiber denier precision and coating chemistry compliance rather than surface aesthetics alone.
- Microfiber:Engineered from ultra-fine polyester filaments below 0.1 denier with pile densities exceeding 100,000 fibers per square centimeter. German automotive suppliers anchor procurement volumes for dashboard and headliner applications where REACH solvent restrictions mandate aqueous polyurethane systems.
- Ultra-suede:Non-woven polyester microfiber substrate developed through needle-punching and impregnation processes. Japanese technical textile producers dominate substrate supply for luxury upholstery applications under METI JIS emission standards.
- Eco-suede:Water-based polyurethane coatings replace dimethylformamide solvents to meet EU Green Deal targets.
- Velvet Suede:Woven pile construction with brushed surface treatment for fashion accessory applications.
Volume sits with Microfiber; growth tilts toward Eco-suede.
Application:
End-use specifications diverge sharply between weight-sensitive automotive programs and tactile-focused fashion lines.
- Automotive Interiors:Luxury OEMs specify synthetic suede for seat inserts, door panels, and steering wheel wraps where gram-per-square-meter targets intersect with burn-test certifications. Stuttgart and Munich procurement headquarters mandate recycled content verification under CSRD disclosure rules.
- Fashion Accessories:Handbag linings, watch straps, and jewelry pouches demand color consistency across dye lots. Italian manufacturing clusters maintain heritage material preferences that slow synthetic substitution despite technical parity.
- Footwear:Upper materials and lining applications concentrate in volume-driven production.
- Upholstery:Residential and contract furniture applications prioritize abrasion resistance ratings.
Procurement scale clusters around Automotive Interiors; margin expansion favors Fashion Accessories.
End User:
Customer technical capabilities determine whether suppliers sell commodity substrates or qualified systems.
- Automotive OEMs:Material approval cycles spanning 18 to 36 months require PPAP documentation, VOC emission testing, and durability validation. Tier 1 suppliers in Germany's automotive corridor manage specification translation between OEM headquarters and converter operations.
- Fashion Brands:Seasonal collection timelines compress procurement windows to 8 to 12 weeks. Milan and Paris design houses prioritize surface hand-feel and color matching over standardized performance metrics.
- Furniture Manufacturers:Contract and residential segments split between flame-retardant specifications and cost-optimized production.
- Retailers:Private-label programs source through converter networks with limited technical specification control.
Revenue concentration follows Automotive OEMs; contract velocity favors Fashion Brands.
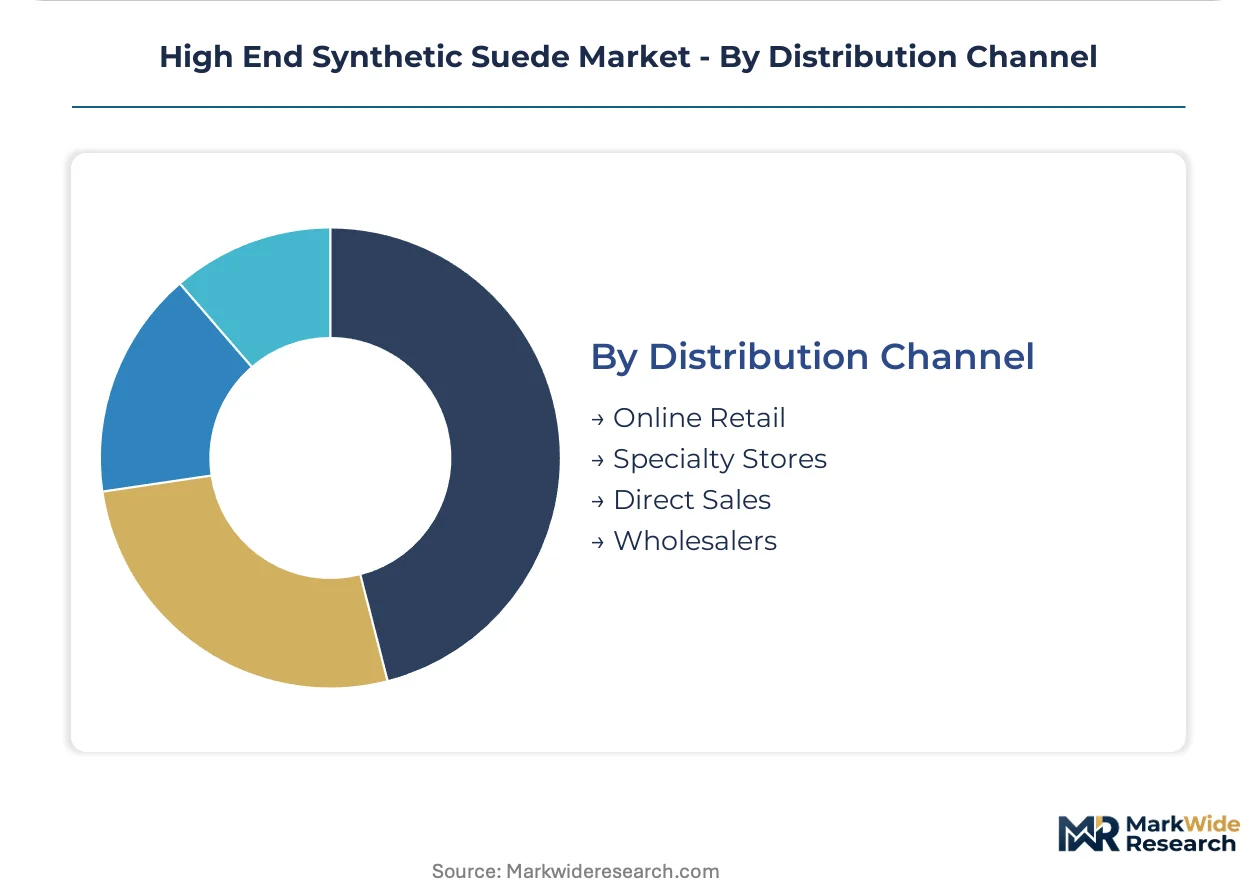
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements rather than price sensitivity alone.
- Direct Sales:Automotive OEMs and major furniture manufacturers negotiate frame contracts with substrate producers for qualified volume allocation. Toray Industries and Asahi Kasei maintain dedicated account teams for technical collaboration on formulation development.
- Specialty Stores:Small-batch fashion houses and independent furniture designers source through curated converter networks. Milan's Via Tortona district hosts showrooms where tactile evaluation precedes specification.
- Wholesalers:Volume distributors aggregate standard grades for footwear and mass-market upholstery converters.
- Online Retail:E-commerce platforms serve hobbyist and small-batch producers with limited technical qualification requirements.
Transaction value concentrates through Direct Sales; channel expansion tilts toward Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Tier 1 suppliers concentrate procurement volumes for premium cabin trims, while Italian fashion manufacturing clusters anchor European demand for luxury accessories. Japanese chemical conglomerates dominate ultra-microfiber substrate supply through captive polymer science capabilities. Chinese coastal provinces house the majority of global microfiber weaving capacity, creating supply-side dependency risks.
Germany
Stuttgart and Munich procurement headquarters at Mercedes-Benz and BMW drive specification adoption for dashboard wraps and seat inserts. REACH solvent restrictions under ECHA mandate aqueous polyurethane coating transitions by 2027. The Baden-Württemberg automotive supplier corridor hosts converter operations serving luxury OEM programs with zero-defect PPAP requirements.
Japan
METI enforces JIS standards for volatile organic compound emissions in automotive interior materials, creating compliance burdens for exporters. Tokyo and Osaka-based chemical conglomerates concentrate ultra-fine denier filament production through specialized melt-blowing equipment. Kansai region technical textile producers dominate substrate supply for luxury upholstery applications under domestic emission protocols.
China
Zhejiang Province clusters over 70 percent of global ultra-fine microfiber substrate capacity, concentrating supply-side risk from port congestion or energy rationing. The country's dual carbon goals pressure solvent-based manufacturing lines toward waterless processing retrofits. Shaoxing and Haining weaving centers supply volume grades for footwear and mass-market upholstery converters.
Italy
Milan design houses maintain heritage material preferences that slow synthetic substitution despite technical parity with natural suede. EU Green Deal circular economy targets pressure tannery-dependent supply chains toward bio-based alternatives. Tuscany and Veneto manufacturing clusters host showrooms where tactile evaluation precedes specification for handbag linings and accessory applications.
India
Maruti Suzuki and Hyundai Motor India expand domestic sourcing mandates under PLI scheme incentives for technical textile investments. BIS standards for automotive interior materials create qualification pathways for substrate producers. Tamil Nadu and Gujarat converter operations address import substitution gaps for seat fabric and headliner applications.
High End Synthetic Suede Market Key Industry Players
Capacity expansion dominates the current landscape as European manufacturers accelerate aqueous coating line investments ahead of 2027 ECHA enforcement deadlines. The vendor base stratifies between integrated chemical conglomerates with captive polymer production and specialized converters dependent on external substrate supply. Three archetypes define competitive positioning: Japanese and Korean conglomerates with backward polymer control, European coating specialists with REACH certification advantages, and Chinese volume producers with scale-driven cost positions. M&A activity concentrates on coating technology acquisitions, while strategic partnerships proliferate between substrate producers and automotive Tier 1 suppliers seeking qualified volume allocation.
Within the integrated chemical conglomerate tier, Toray Industries and Asahi Kasei exemplify archetypes combining captive filament production with technical textile expertise. Kuraray occupies a position among European-anchored specialists leveraging aliphatic polyurethane coating capabilities for luxury upholstery applications. Zhejiang Meisheng New Material represents the scale-driven Chinese producer archetype, while Teijin Limited sits within the diversified industrial group category with cross-sector material science applications. These five named entities collectively illustrate the geographic and structural segmentation defining supplier qualification hierarchies across automotive and fashion end-uses.
| Leading Market Players |
|---|
| Teijin Limited |
| Majilite Inc. |
| Toray Industries, Inc. |
| WINIW International Co., Limited |
| The Mitchell Group |
| Asahi Kasei Corporation |
| Seiren Co., Ltd. |
| Zhejiang Meisheng New Material Co., Ltd. |
| Kuraray Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Purified terephthalic acid and ethylene glycol spot prices cascade through polyester microfiber substrate costs, compressing margins for non-integrated converters while Japanese and Korean chemical conglomerates with captive polymer production defend pricing power across automotive qualification tiers.
Pricing Analysis
Volume concentrates in footwear-grade microfiber where price competition intensifies, while margins expand in automotive-certified ultra-microfiber and eco-suede formulations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant aqueous coating systems from legacy solvent-based production. Pricing pressure stems from petrochemical input volatility as purified terephthalic acid tracks crude oil benchmarks. Fashion accessories buyers exhibit lowest price sensitivity due to heritage brand premiums, while mass-market footwear converters face acute cost compression.
Supply Chain Analysis
Ultra-fine denier filament supply rests on specialized melt-blowing equipment concentrated in Japan, South Korea, and China's Zhejiang Province. Raw material dependencies span purified terephthalic acid, ethylene glycol, and aliphatic polyurethane coating resins. Single-source vulnerability pervades the Zhejiang production cluster where energy rationing or port congestion disrupt substrate flows. Distribution runs through direct sales channels for automotive OEM frame contracts and converter networks for fashion house specialty sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based polyurethane impregnation systems are displacing dimethylformamide solvent-based manufacturing, creating qualification windows for first-mover substrate producers and coating specialists.
For Market Incumbents: Cement aqueous coating certification advantages ahead of ECHA enforcement deadlines. Invest in supercritical CO2 dyeing lines to eliminate effluent treatment costs. Lock in long-term frame contracts with Stuttgart and Munich procurement headquarters before qualification timelines compress further.
For New Entrants and Emerging Players: REACH Phase-Out Mandates in Europe open a window for bio-based polyurethane formulators with castor oil-derived isocyanate capabilities. Target India's PLI scheme technical textile investments in Tamil Nadu and Gujarat. Pursue marine and aviation upholstery certifications where flame-retardant premiums exceed automotive grades.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European coating specialists with ECHA pre-certification and stranded aqueous line assets. Water-based formulation expertise scarcity concentrates value capture potential over a multi-year transition horizon. Monitor N-methyl-2-pyrrolidone SVHC candidate listing enforcement as inflection trigger for accelerated retrofit capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Supercritical CO2 dyeing retrofits eliminate effluent burdens under ECHA waterless processing mandates. |
| Backward Integration | Captive purified terephthalic acid production insulates margin compression from crude oil benchmark volatility. |
| Long-term Supply Agreement | Frame contracts with German Tier 1 suppliers secure volume allocation through 36-month OEM qualification cycles. |
| Joint Venture | Partnerships between Japanese substrate producers and Indian converters address PLI scheme localization requirements. |
| Capacity Expansion | Aqueous coating line additions in Baden-Württemberg defend regional supply positions against Asian imports. |
Research Approach
Document review covered customs and trade data, SEC filings from chemical conglomerates, and automotive supplier PPAP documentation, complemented by interviews with polymer science R&D directors, Tier 1 supplier procurement leads, and ECHA regulatory affairs specialists. Secondary validation drew from EU REACH substance registry updates, METI JIS standard publications, and Indian BIS automotive material certifications. Bottom-up volume modeling triangulated against top-down chemical industry capacity assessments.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were calibrated against automotive production forecasts and fashion accessory import flows. CAGRs were derived from regression analysis of historical pricing elasticity and substitution rate assumptions. Key inputs included solvent-transition capital expenditure schedules and OEM qualification pipeline visibility.
The model assumes a particular technology adoption path for water-based polyurethane systems; alternative pathways for bio-based polyol formulations would alter the outlook. Forecasts reflect assumptions about ECHA enforcement timing and automotive OEM recycled content mandate adoption. A small set of named triggers—N-methyl-2-pyrrolidone SVHC listing, India PLI scheme disbursement pacing, and Zhejiang energy rationing severity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
Polyester Filament Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Blended Fibers Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Polyimide Fiber Market
Synthetic Fibers
Regenerated Fibers Market