
 Indonesia Fungicide Market | 2026-2036
Indonesia Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Fungicide Market Insights
Indonesia's tightened maximum residue limits under SNI and Ministry of Agriculture decree is consolidating the supplier base toward registrants with full toxicology dossiers and local formulation capability. Syngenta Group leverages its integrated supply chain from active ingredient to farmer advisory services across Java and Sumatra. BASF SE anchors its position through proprietary strobilurin chemistry and extensive field trial networks with palm oil cooperatives. Bayer AG differentiates via biological-plus-chemical combination portfolios targeting soil-borne pathogens in estate crops.
Indonesia fungicides comprise synthetic or biological biocidal formulations designed to prevent, inhibit, or eradicate fungal pathogens in agricultural systems, typically applied at 0.1–2.0 kg active ingredient per hectare depending on crop canopy density and pathogen pressure. Their primary commercial purpose is to protect yield volume and quality in high-value perennial and annual cropping systems where fungal epidemics can destroy 30–70 percent of harvestable biomass. Triazoles and strobilurins command the largest share of the chemistry portfolio due to their systemic action and broad-spectrum control against rusts and blights in rice and vegetable systems. Wettable powders retain strong penetration among smallholder cooperatives with limited spray equipment infrastructure, while suspension concentrates are displacing older emulsifiable concentrate formats in estate agriculture due to improved operator safety profiles and reduced solvent loading.
Indonesia's national pesticide regulator under the Ministry of Agriculture, the Indonesian Food and Drug Monitoring Agency (BPOM) for residue surveillance, and SNI certification requirements collectively govern product registration, import licensing, and field-use protocols. These frameworks compel manufacturers to reformulate legacy chemistries and submit expanded ecotoxicology data, raising compliance costs while creating barriers for non-registered imports. Stakeholders must monitor pending revisions to the positive list of permitted actives and pre-position localized production assets before regulatory windows narrow for older fungicide chemistries.
Market Dynamics
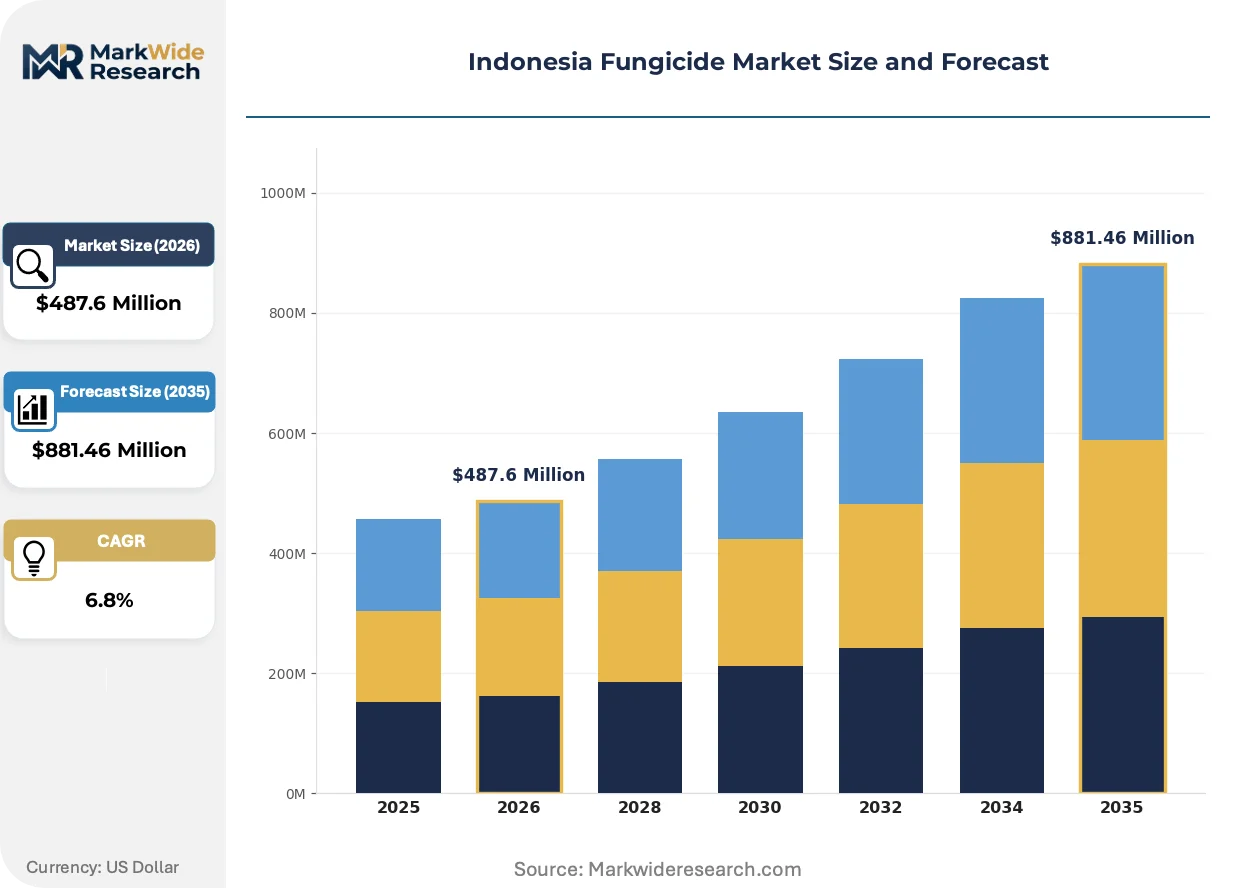
Indonesia's tightened SNI residue limits and Ministry of Agriculture decree are consolidating procurement toward registrants with full toxicology dossiers and local formulation assets, compressing margins for import-dependent distributors while rewarding integrated domestic producers.
Growth Catalysts
- Leaf rot epidemics in Sumatra palm estates:Ganoderma and basal stem rot outbreaks across Riau and North Sumatra plantations are forcing estate managers to double fungicide application frequencies during wet seasons.
- Biological-chemical combination portfolios:Bayer AG's integrated soil-borne pathogen solutions are gaining traction among Kalimantan cooperatives seeking reduced chemical loading per hectare.
- Downy mildew pressure in Java vegetable belts:Chili and onion growers in Central Java face intensified monsoon-driven pathogen cycles, expanding preventive spray programs.
Market Restraints
- Active ingredient import dependency:Formulators rely on Chinese and Indian technical grade supplies, exposing margins to shipping cost volatility and currency fluctuation.
- SNI certification timeline friction:Expanded ecotoxicology data requirements under Ministry of Agriculture protocols extend registration cycles by 18-24 months for legacy chemistries.
- Biological substitute penetration:Trichoderma-based biocontrol products from local fermentation facilities are capturing share in organic-certified vegetable segments.
Strategic Opportunities
- Sulawesi and Papua plantation expansion:New oil palm development zones in Central Sulawesi and Merauke lack established distribution infrastructure, creating first-mover positioning for registrants with localized blending capacity.
- Drone-based precision application:UAV spray services are reducing labor costs in uneven terrain estates, opening channel partnerships between agrochemical distributors and aerial service providers.
- Export-oriented residue compliance:EU-bound palm oil and spice producers require sub-MRL formulations, commanding premium pricing for SNI-registered, low-dose strobilurin and triazole products.
Industry Challenges
- Field advisory talent scarcity:Estate crop pathology expertise concentrates among senior agronomists near Medan and Jakarta, leaving outer island cooperatives underserved for disease diagnosis and spray timing optimization.
- Legacy wettable powder inventory reconfiguration:Smallholder cooperatives with limited spray equipment infrastructure face capital constraints upgrading from WP to suspension concentrate formats despite operator safety benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Fungicide Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triazoles, Chloronitriles, Benzimidazoles, Strobilurins Active Ingredient: Propiconazole, Azoxystrobin, Mancozeb, Chlorothalonil Formulation: Emulsifiable Concentrates, Wettable Powders, Granules, Suspension Concentrates Crops: Rice, Vegetables, Fruits, Oilseeds |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, FMC Corporation, UPL Limited, ADAMA Agricultural Solutions Ltd, Corteva Agriscience, Nufarm Ltd, PT Biotis Agrindo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Fungicide Market Trends and Innovations
Suspension concentrate formulations are displacing older chemistries across Indonesian estate agriculture, while regulatory data requirements and precision application technologies reshape competitive positioning among domestic formulators and multinational registrants.
Suspension concentrate (SC) formulations with reduced solvent loading and improved operator safety profiles are overtaking emulsifiable concentrate (EC) formats in Sumatra and Kalimantan palm oil estates. Large plantation operators with mechanized spray equipment are adopting SC products at accelerated rates during 2023-2024 procurement cycles. This format transition is compressing demand for aromatic solvent imports while elevating technical barriers for smaller formulators lacking high-shear milling capacity.
Indonesia's Ministry of Agriculture is expanding residue surveillance protocols under BPOM coordination, requiring registrants to submit crop-specific dissipation studies for new actives. The regulatory burden falls heaviest on generic importers lacking local field trial infrastructure. Domestic formulators with established Java-based trial networks are pre-positioning expanded toxicology dossiers ahead of anticipated positive list revisions.
Cooperative procurement consolidation is altering distribution economics across Java's vegetable belt. Medium-sized grower associations in Banten and East Java are bypassing traditional village-level agro-dealers, negotiating direct supply contracts with registrants for volume-based pricing. This channel disintermediation is most visible in chili and shallot production clusters where post-harvest value concentration justifies collective input purchasing.
Indonesia Fungicide Market Segmentation
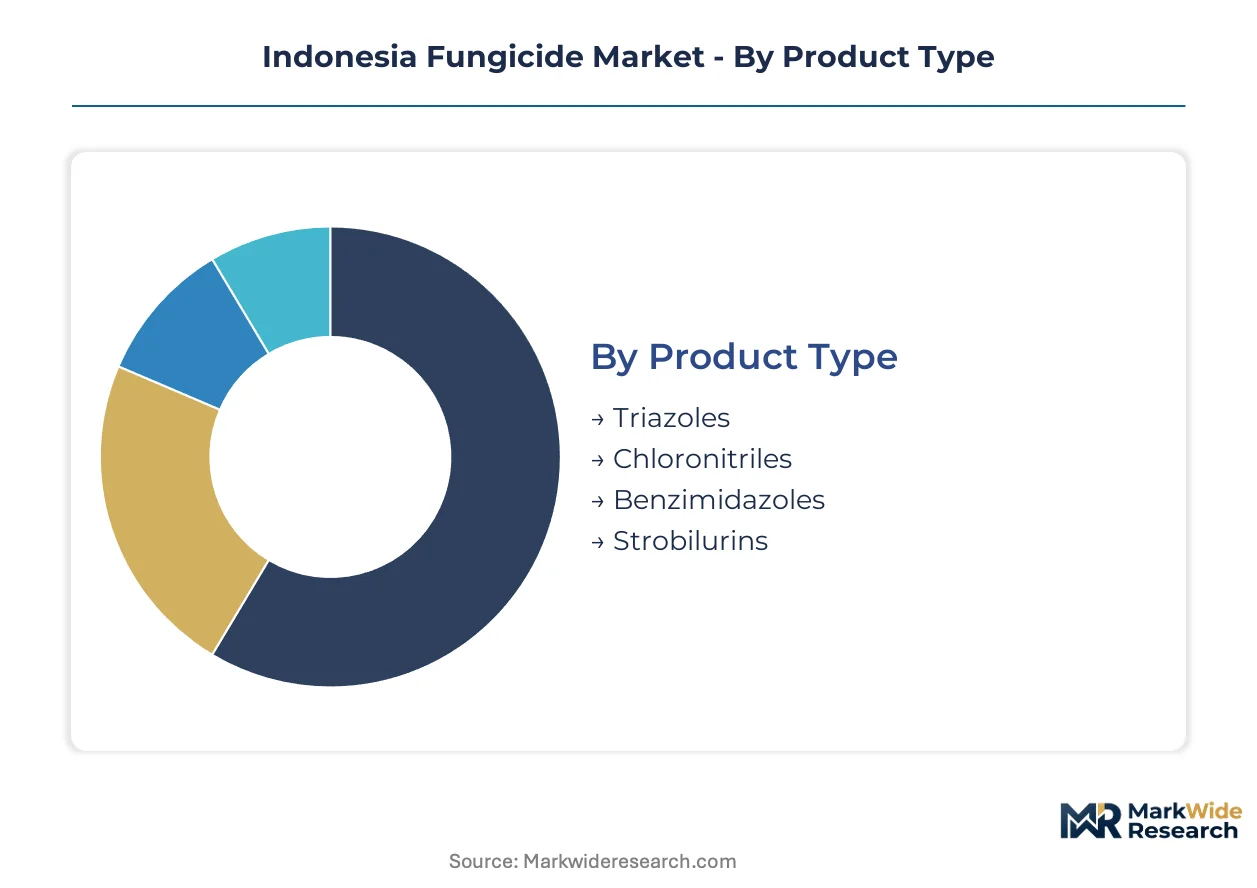
Indonesia's fungicide segmentation reflects divergent chemistries across estate agriculture versus smallholder systems. Product type and formulation choices map directly to equipment access, labor availability, and residue compliance requirements in palm oil versus vegetable production clusters.
Product Type:
Triazoles and strobilurins anchor estate procurement for systemic disease control, while chloronitriles and benzimidazoles serve protective spray programs in smallholder cooperatives with limited reapplication windows.
- Triazoles:Systemic demethylation inhibitors penetrate plant tissue to arrest ergosterol biosynthesis in fungal cell membranes. Demand concentrates in North Sumatra palm estates combating Ganoderma basal stem rot through trunk injection protocols. Estate managers favor triazoles for their curative action against established infections during wet season pressure cycles.
- Strobilurins:Quinone outside inhibitors disrupt mitochondrial respiration with broad-spectrum activity against rusts and blights. Java's chili and onion belts drive procurement for preventive downy mildew programs during monsoon peaks. The chemistry commands premium positioning among export-oriented growers facing EU MRL scrutiny.
- Chloronitriles:Multi-site contact protectants form surface barriers against spore germination in rice paddy systems.
- Benzimidazoles:Tubulin polymerization inhibitors retain niche use in banana and pineapple plantations for Sigatoka and fruit rot management.
Triazoles lead volumes today; strobilurins are gaining share fastest.
Active Ingredient:
Propiconazole and azoxystrobin dominate estate procurement for their systemic persistence, while mancozeb and chlorothalonil anchor protective programs in cost-sensitive smallholder segments.
- Propiconazole:Broad-spectrum triazole with pronounced curative properties against established infections. Kalimantan palm cooperatives deploy trunk injection formulations for Ganoderma control in mature estates. The active anchors Bayer AG and Syngenta portfolios across Sumatra and Kalimantan field trial networks.
- Azoxystrobin:First-generation strobilurin with translaminar movement and rainfastness advantages. Central Java vegetable growers prioritize the chemistry for chili anthracnose during extended wet periods. Premium pricing reflects its role in export residue compliance programs.
- Mancozeb:Dithiocarbamate protectant with multi-site action against early and late blights in potato and tomato systems.
- Chlorothalonil:Chloronitrile contact fungicide retaining strong penetration in rice blast management programs across Sulawesi.
Propiconazole anchors estate volumes; azoxystrobin shows steepest expansion trajectory in vegetable belts.
Formulation:
Suspension concentrates displace legacy formats in mechanized estates, while wettable powders persist in smallholder cooperatives with limited spray infrastructure investment capacity.
- Suspension Concentrates:Aqueous dispersions with reduced solvent loading and improved operator safety profiles. Large plantation operators in Riau and North Sumatra accelerated adoption during 2023-2024 procurement cycles. The format requires high-shear milling capacity that filters out smaller domestic formulators.
- Wettable Powders:Dry flowable powders reconstituted in water for backpack sprayer application. Smallholder cooperatives in Banten and East Java retain strong demand due to lower unit costs and minimal equipment requirements. Capital constraints delay format upgrades despite operator exposure concerns.
- Emulsifiable Concentrates:Solvent-based formulations facing displacement pressure from SNI safety protocols and aromatic import cost volatility.
- Granules:Soil-applied controlled-release formats capturing share in plantation seedling establishment protocols for Phytophthora suppression.
Wettable powders dominate unit volumes today; suspension concentrates are climbing the fastest in estate procurement.
Crops:
Oilseeds and vegetables command premium formulation procurement, while rice and fruits segment into cost-optimized protective programs and export-grade residue-compliant systems.
- Oilseeds:Palm oil estates drive the largest absolute fungicide consumption through Ganoderma and leaf rot management. Riau, North Sumatra, and Kalimantan plantation operators double application frequencies during wet season epidemics. Trunk injection and soil drench protocols favor systemic triazoles and strobilurins.
- Vegetables:Chili, onion, and shallot production in Central Java and East Java generates intensive preventive spray cycles. Downy mildew and anthracnose pressure during monsoon peaks expands program frequency among cooperative procurement groups.
- Rice:Blast and sheath rot management in Java and Sulawesi paddy systems favors cost-efficient contact protectants with multi-site action.
- Fruits:Banana, pineapple, and citrus plantations in Lampung and South Sumatra deploy specialized programs for Sigatoka and post-harvest rot suppression.
Oilseeds lead absolute volumes; vegetables show fastest share expansion through cooperative procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic talent clusters around Medan and Jakarta anchor technical advisory capacity, leaving outer island cooperatives underserved for disease diagnosis and spray timing optimization.
North Sumatra
Ganoderma basal stem rot outbreaks across Riau and North Sumatra palm estates drive intensive trunk injection protocols. The Ministry of Agriculture's SNI certification requirements filter out non-registered imports, consolidating procurement toward domestic formulators. Medan-based field trial networks anchor Bayer AG and Syngenta's technical service infrastructure for estate managers.
Riau
Leaf rot epidemics in mature plantations force operators to double fungicide application frequencies during wet seasons. BPOM residue surveillance protocols under Ministry of Agriculture coordination compel expanded toxicology dossiers from registrants. Pekanbaru plantation clusters accelerated adoption of suspension concentrate formats during 2023-2024 procurement cycles.
Central Java
Chili and onion growers face intensified downy mildew pressure during monsoon cycles, expanding preventive spray programs. Cooperative procurement consolidation in Banten and East Java bypasses traditional village-level agro-dealers for direct supply contracts. Semarang vegetable belt operations command premium pricing for SNI-registered, low-dose strobilurin products.
East Kalimantan
Biological-chemical combination portfolios gain traction among cooperatives seeking reduced chemical loading per hectare. The Ministry of Agriculture's tightened pesticide residue limits accelerate formulation upgrades toward lower-dose chemistries. Samarinda plantation development zones lack established distribution infrastructure, creating first-mover positioning opportunities.
Central Sulawesi
New oil palm development zones lack established distribution infrastructure, favoring registrants with localized blending capacity. SNI certification timeline friction extends registration cycles by 18-24 months for legacy chemistries. Palu corridor estates deploy drone-based precision application services to reduce labor costs in uneven terrain.
Indonesia Fungicide Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Indonesia's fungicide procurement channels. The supplier base consolidates toward registrants with full toxicology dossiers and local formulation capability, compressing margins for import-dependent distributors. Three archetypes dominate: integrated multinational registrants with Java-based trial networks, domestic formulators with high-shear milling capacity, and generic importers exposed to currency fluctuation. Competitive moves center on cooperative procurement consolidation and suspension concentrate format transitions.
Within the integrated multinational tier, Syngenta Group, BASF SE, and Bayer AG exemplify archetypes differentiated by chemistry specialization and advisory service depth. Syngenta leverages supply chain integration from active ingredient to farmer advisory services across Java and Sumatra. BASF anchors positioning through proprietary strobilurin chemistry and extensive field trial networks with palm oil cooperatives. Bayer differentiates via biological-plus-chemical combination portfolios targeting soil-borne pathogens in estate crops.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| FMC Corporation |
| UPL Limited |
| ADAMA Agricultural Solutions Ltd |
| Corteva Agriscience |
| Nufarm Ltd |
| PT Biotis Agrindo |
| Others |
Pricing and Supply Chain Analysis
Palm oil plantation operators in Riau and North Sumatra anchor procurement volumes, locking in contract-based long-term offtake structures with SNI-registered formulators. Their scale concentration feeds pricing power toward integrated domestic producers while compressing margins for import-dependent distributors exposed to currency fluctuation.
Pricing Analysis
Product-plus-advisory service bundling separates premium registrants from unbundled generic suppliers in estate procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks SNI certification status, formulation complexity, and field trial support depth. Cost compression in economy-tier wettable powders is intensifying because Chinese technical grade import costs swing with shipping volatility. Smallholder cooperatives in Banten and East Java exhibit highest price sensitivity; export-oriented vegetable clusters in Central Java show lowest.
Supply Chain Analysis
Direct-to-estate channels handle large plantation demand through Medan and Pekanbaru technical service hubs, while cooperative procurement consolidation in Java bypasses traditional village agro-dealers. Active ingredient supply draws from China and India for technical grade inputs, with formulation blending concentrated in Java and Sumatra. Single-source vulnerability runs through Chinese azoxystrobin and propiconazole technical supplies. Distribution runs through registrant-owned depots, third-party logistics partners, and emerging drone-based aerial service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on suspension concentrate format upgrades and SNI certification pre-positioning that commands premium positioning ahead of regulatory windows narrowing.
For Market Incumbents: Deploy high-shear milling capacity additions in Java to capture suspension concentrate format transition demand from Riau and North Sumatra estates. Consolidate field advisory talent around Medan and Jakarta to defend against biological substitute penetration from local Trichoderma fermentation facilities. Lock in cooperative procurement contracts in Central Java vegetable belts before channel disintermediation accelerates. For New Entrants and Emerging Players: Enter via Central Sulawesi and Papua plantation development zones lacking established distribution infrastructure, positioning localized blending capacity as first-mover advantage. Target drone-based precision application partnerships with aerial service providers in uneven terrain estates. White-space exists in sub-MRL formulation supply for EU-bound palm oil and spice producers. For Investors and Strategic Acquirers: Domestic formulators with SNI registration pipelines and Java-based trial networks are the most active acquirer targets in this space, as multinational registrants seek captive supply of local formulation assets. Acquisition archetypes center on mid-cap specialists with high-shear milling capability and established BPOM toxicology dossiers. Watch for Ministry of Agriculture positive list revisions as inflection signal accelerating consolidation toward compliant registrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Reduces exposure to Chinese technical grade import cost volatility for azoxystrobin supplies. |
| Suspension Concentrate Capacity Expansion | Captures estate procurement shift away from emulsifiable concentrate formats in Sumatra. |
| SNI Certification Pre-Positioning | Secures registration runway ahead of positive list revisions filtering legacy chemistries. |
| Drone Service Channel Partnership | Opens precision application revenue streams in Central Sulawesi uneven terrain estates. |
| Biological-Chemical Combination Portfolio | Addresses Kalimantan cooperative demand for reduced chemical loading per hectare. |
Research Methodology
Coverage spans Java, Sumatra, Kalimantan, Sulawesi, and Papua, with primary inputs from each region's production clusters. The analysis combines structured interviews with plantation agronomy directors, cooperative procurement managers, agrochemical distribution channel heads, and Ministry of Agriculture regulatory officers with secondary validation from BPOM residue surveillance protocols, Indonesian National Standard certification records, and customs import data for technical grade active ingredients. Bottom-up triangulation across estate spray program records and top-down reconciliation with Ministry of Agriculture pesticide consumption statistics anchored volume estimates.
Granularity extends to chemistry class, formulation format, crop system, and regional estate cluster across the analysis window. Segment-level CAGRs were derived from trend extrapolation of application frequency shifts, acreage expansion in frontier zones, and format transition curves in mechanized versus smallholder systems. Key inputs include Ganoderma infection incidence rates in mature palm estates, monsoon-driven downy mildew pressure cycles in Central Java, and SNI certification timeline friction for legacy chemistries.
Inputs from estate managers and cooperative leaders were available through the study window; gaps in real-time BPOM enforcement intensity data introduce uncertainty bands around regulatory compliance cost assumptions. Forecasts reflect base-case assumptions on positive list revision timing and suspension concentrate adoption curves. Periodic stress-testing of base assumptions is recommended against Ministry of Agriculture decree implementation pace and Chinese technical grade export policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Fogger Market
Crop Protection
Fumigation Service Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Tebuconazole Market
Crop Protection
Global Turf Protection Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Larvicides Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
United States Nematicides Market
Crop Protection
Asia Pacific Herbicide Market