
 Automotive 3D Imaging Market | 2026-2036
Automotive 3D Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 3D Imaging Market Analysis
The shift from outsourced sensor module procurement toward in-house 3D imaging system development is consolidating among tier-1 automotive suppliers. Robert Bosch GmbH leverages its MEMS fabrication depth to control LiDAR and depth-sensing component supply chains internally. Sony Group Corporation anchors image sensor production for automotive 3D vision systems across multiple OEM programs. Continental AG competes through integrated software-hardware stacks that span depth sensing to perception algorithms.
Automotive 3D imaging encompasses structured light projection, time-of-flight measurement, and stereoscopic triangulation techniques that generate dense spatial point clouds for object detection and surface metrology. Solid-state LiDAR arrays with no moving parts now achieve centimeter-range accuracy at highway speeds, enabling real-time occupancy grid mapping for autonomous navigation. Laser scanners command the largest installed base in quality control applications, while depth sensing technology grows fastest as OEMs embed 3D vision into production vehicle ADAS architectures. Tier-1 suppliers represent the most concentrated margin pool, given their position between component vendors and vehicle platform integration.
NHTSA mandates in the United States, EU type-approval frameworks under UNECE regulations, and Japan's MLIT safety standards collectively shape sensor performance thresholds and homologation pathways for 3D imaging systems. ISO 26262 functional safety requirements and ASPICE process standards further constrain supplier qualification and software development practices. Stakeholders must monitor regulatory divergence between federal and state-level autonomous vehicle testing rules, as fragmented compliance obligations will determine which 3D imaging architectures achieve scalable deployment across multiple jurisdictions.
Market Dynamics
Solid-state LiDAR miniaturization is compressing sensor form factors below 100 cubic centimeters while maintaining highway-speed detection ranges, forcing tier-1 suppliers to reconfigure their optical assembly lines and software stacks simultaneously.
Growth Catalysts
- UNECE type-approval frameworks:European regulatory mandates for automated emergency braking and pedestrian detection systems require certified 3D imaging hardware, creating guaranteed procurement volumes for qualified suppliers.
- Production metrology in electric vehicle battery manufacturing:Cell-to-pack assembly tolerances below 50 microns demand structured light and laser triangulation systems for weld inspection and dimensional validation.
- Silicon photonics foundry capacity expansion:Taiwan and South Korea semiconductor fabrication clusters are adding dedicated optical MEMS lines, reducing lead times for solid-state LiDAR chipsets.
Market Restraints
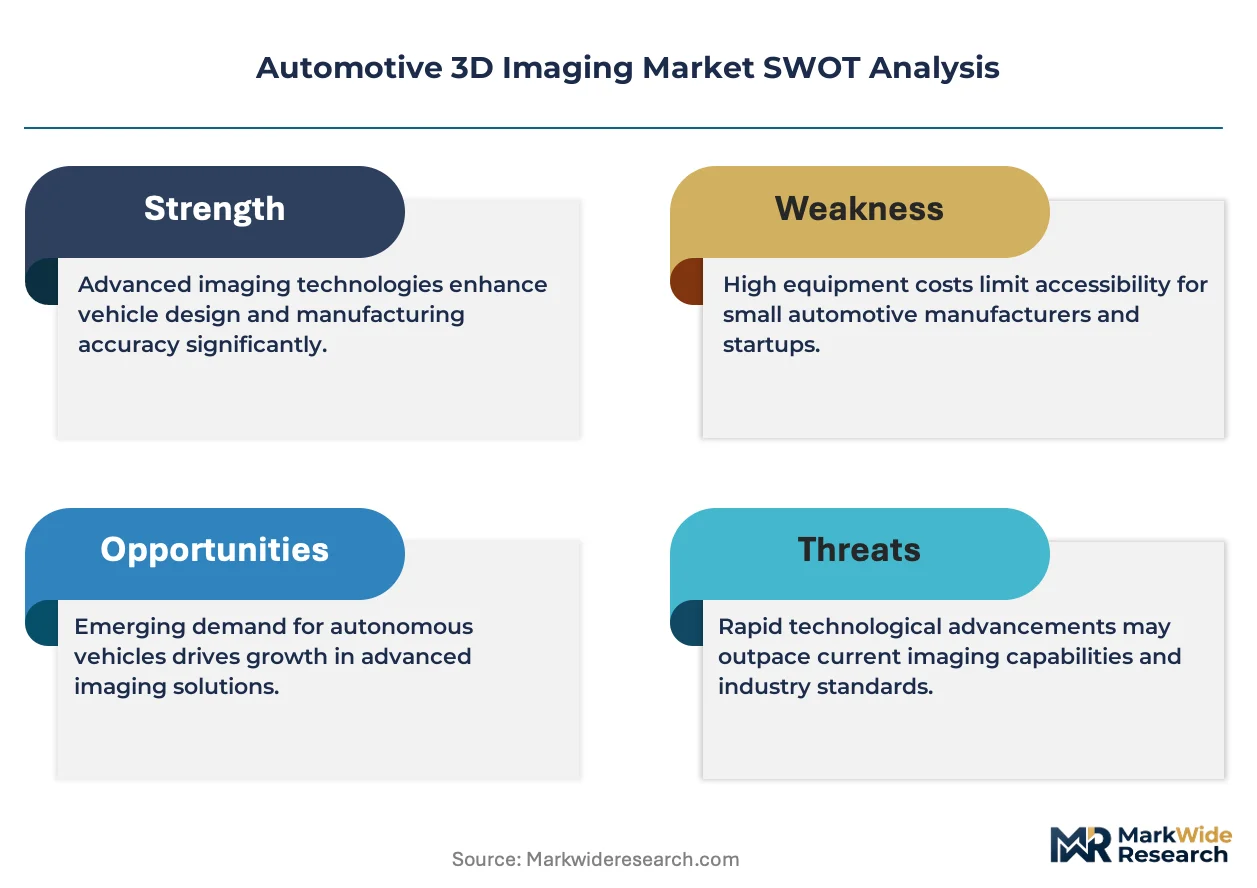
- Indium gallium arsenide detector costs:1550-nanometer LiDAR architectures require expensive InGaAs photodetectors that constrain bill-of-materials scaling below luxury vehicle price tiers.
- Single-source VCSEL dependency:Vertical-cavity surface-emitting laser arrays for time-of-flight modules concentrate among three foundry operators, creating supply vulnerability for multi-projector automotive designs.
- ISO 26262 ASIL-D certification timelines:Functional safety validation for perception software extends development cycles by 18-24 months, freezing architecture choices early in vehicle platform planning.
Strategic Opportunities
- India automotive manufacturing expansion:Domestic OEM capacity growth under the PLI scheme creates demand for affordable 3D vision systems in compact vehicle segments currently underserved by premium LiDAR suppliers.
- Construction and mining equipment retrofit:Off-highway vehicle operators are adding aftermarket 3D proximity sensing to aging fleets, opening a channel distinct from new-vehicle OEM supply.
- Fusion of thermal imaging and depth sensing:Combined long-wave infrared and LiDAR modules enable all-weather object classification, addressing performance degradation that limits pure optical systems.
Industry Challenges
- Perception algorithm validation:Edge-case scenario coverage for neural networks trained on 3D point clouds requires petabyte-scale labeled datasets that few suppliers can generate independently.
- Automotive Ethernet integration:Migrating sensor data from dedicated LVDS links to 10Gbps+ automotive Ethernet demands PHY layer redesigns that complicate legacy platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 3D Imaging Market |
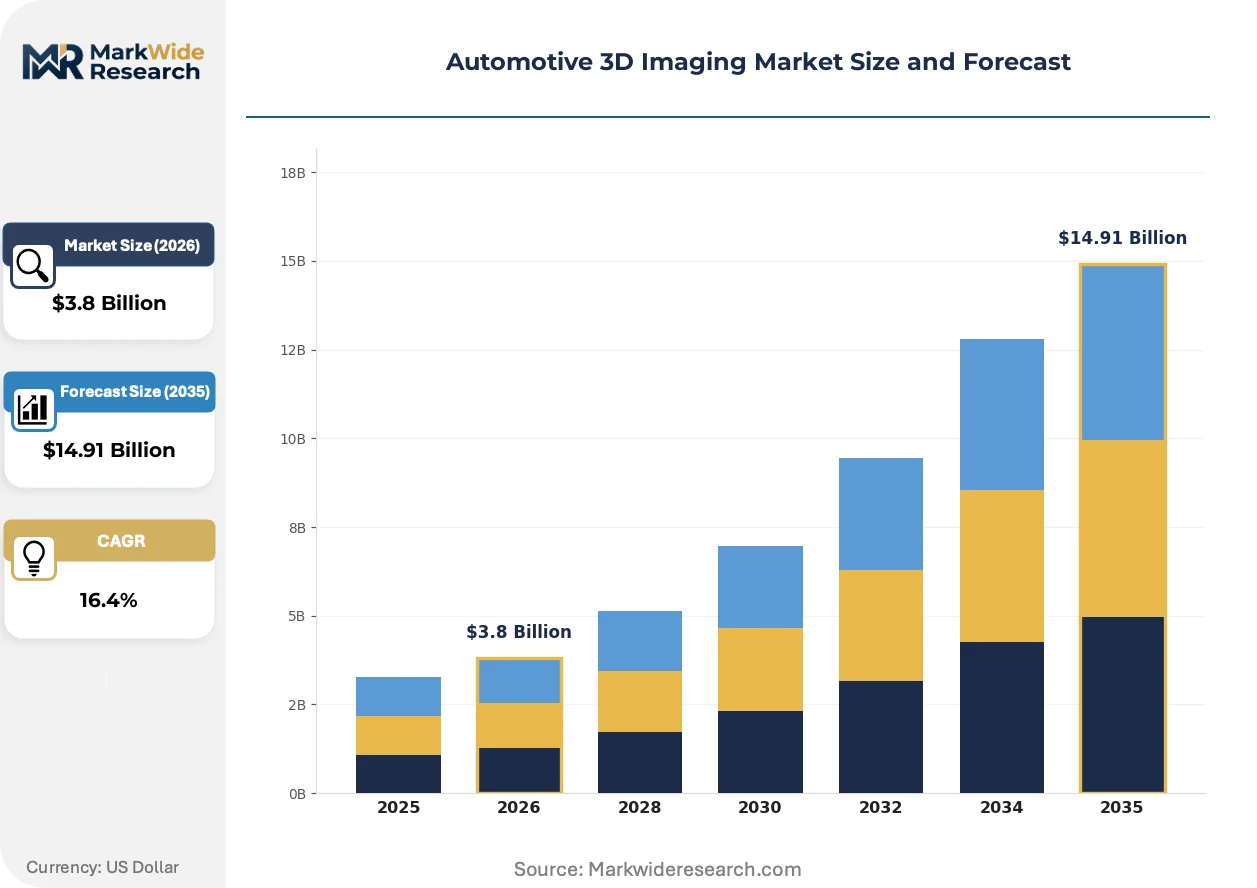
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
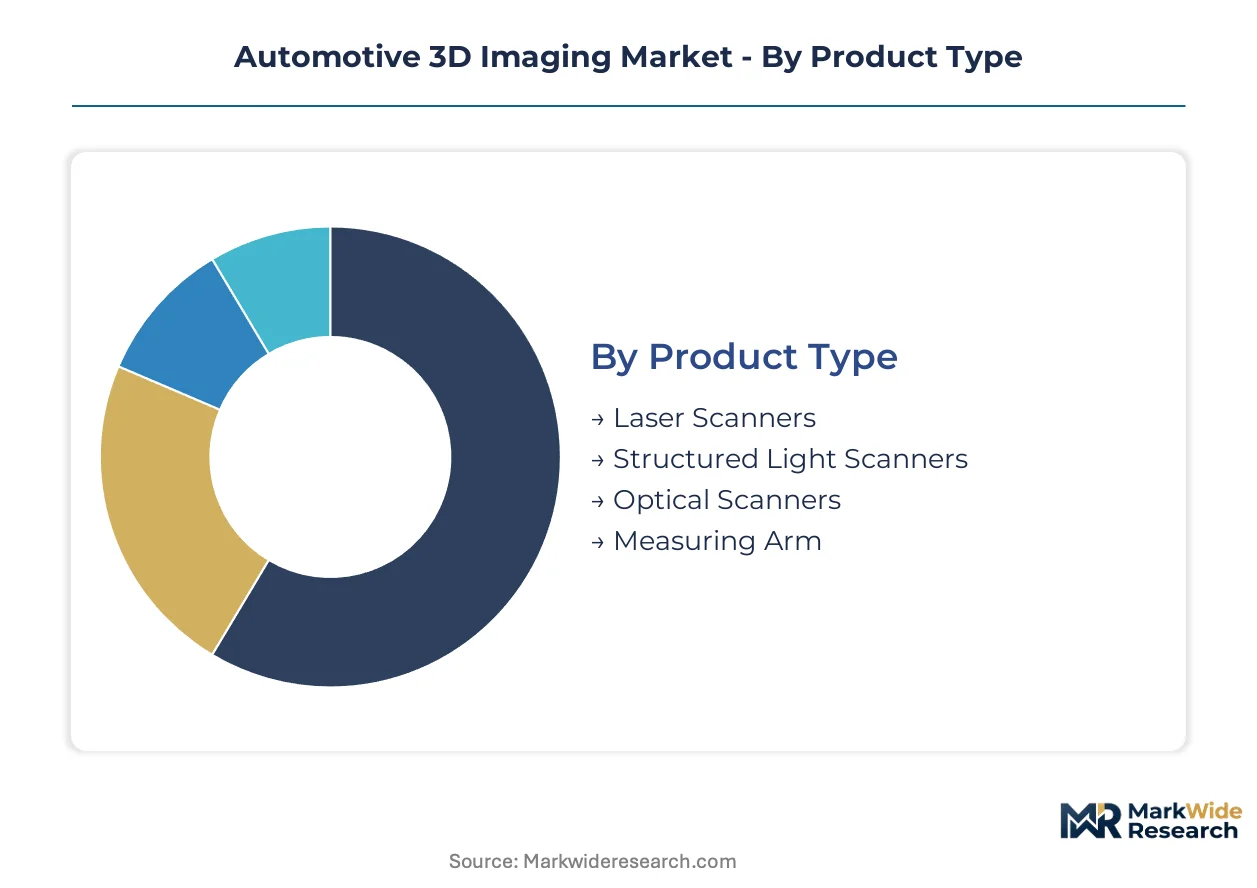
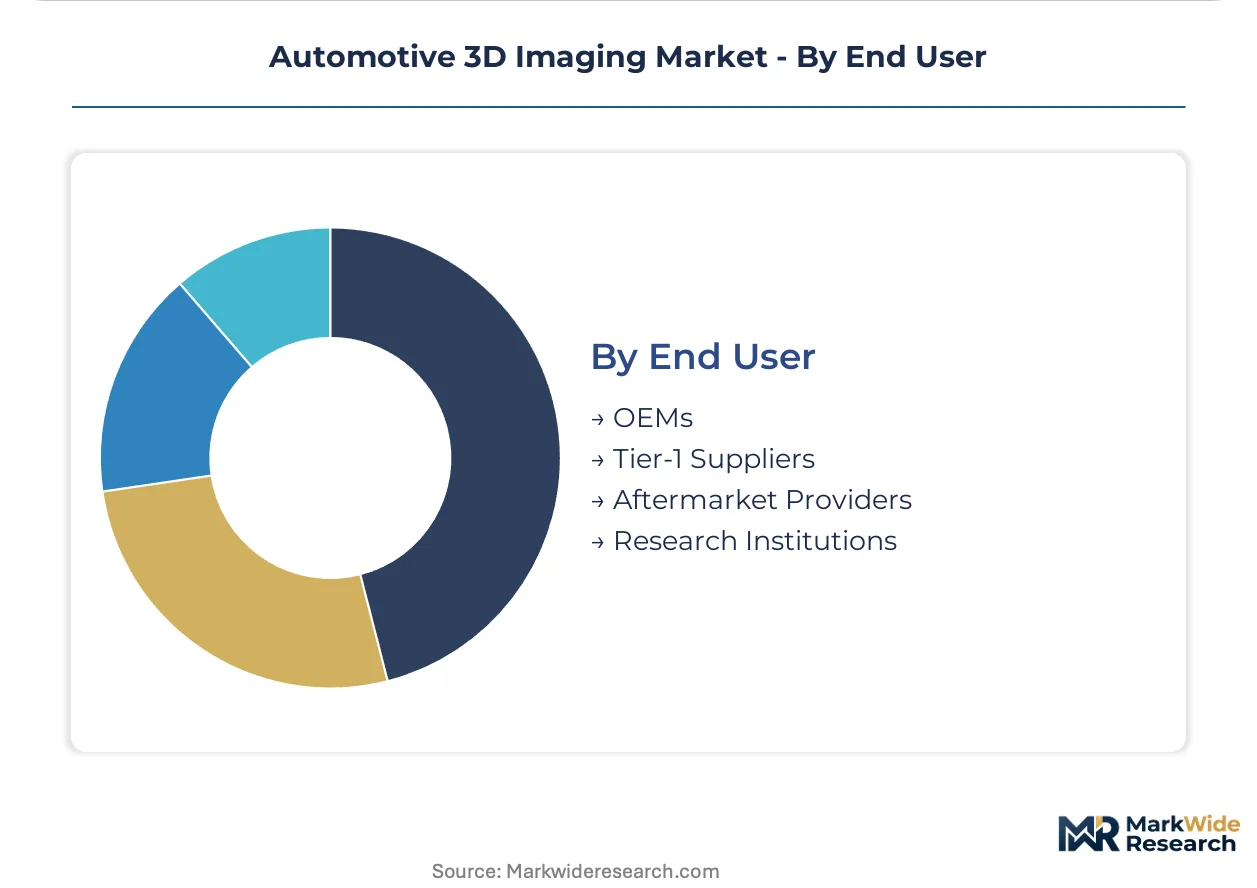
| Segmentation | Product Type: Laser Scanners, Structured Light Scanners, Optical Scanners, Measuring Arm Application: Prototyping, Quality Control, Reverse Engineering, Design Validation Technology: 3D Reconstruction, Computer Vision, Image Processing, Depth Sensing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions |
| Companies Covered | Robert Bosch GmbH, Texas Instruments, Continental AG, Sony Group Corporation, Valeo SE, STMicroelectronics, ZF Friedrichshafen AG, Autodesk Inc., Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 3D Imaging Market Emerging Trajectories
Photonic integration and software-defined perception are converging to collapse the traditional boundary between hardware capture and algorithmic interpretation, compressing supplier value chains and altering qualification requirements for automotive programs.
Optical phased array LiDAR is modularizing. This solid-state beam-steering technology replaces mechanical rotating assemblies with silicon-based waveguide arrays. Tier-1 suppliers in Germany and Japan are sampling integrated modules for 2027 vehicle platforms. The technology is modularizing sensor head designs, allowing OEMs to swap optical engines without redesigning mounting structures or calibration protocols.
NHTSA updated FMVSS 127 mandates automatic emergency braking with pedestrian detection for all light vehicles under 10,000 pounds by 2029. The rule prescribes minimum nighttime detection ranges that favor 1550-nanometer LiDAR over pure camera systems. US-based OEM procurement teams are now requiring dual-wavelength redundancy in their next-generation sensor suites, accelerating qualification of previously marginal infrared architectures.
Fleet operators are unbundling perception software from hardware procurement. Commercial vehicle and robotaxi deployers now license algorithm stacks separately from sensor modules, forcing LiDAR manufacturers to open API access or risk disintermediation. This pattern is most visible in California and Arizona autonomous testing corridors, where fleet-scale buyers negotiate direct contracts with perception software specialists.
Automotive 3D Imaging Market Segmentation
Automotive 3D imaging segments diverge sharply by technical maturity and procurement authority. OEMs and tier-1 suppliers allocate capital differently across hardware categories, while regulatory mandates reshape which applications absorb investment priority.
Product Type:
Technical specifications for range, accuracy, and environmental tolerance define procurement decisions across hardware categories.
- Laser Scanners:Time-of-flight and phase-shift architectures deliver sub-millimeter precision across distances exceeding 100 meters. German and Japanese automotive clusters deploy these systems for full-body dimensional validation in electric vehicle skateboard platforms.
- Structured Light Scanners:Projected fringe patterns generate dense point clouds for surface metrology without moving parts. Quality control workflows for battery pack assembly in United States manufacturing plants favor these units for cycle-time efficiency.
- Optical Scanners:Passive stereo vision systems triangulate surface geometry using ambient illumination. These units serve design studios where controlled lighting conditions enable lower-cost deployment.
- Measuring Arm:Articulated coordinate measurement machines with integrated optical probes enable tactile-optical hybrid inspection. Powertrain component manufacturers in Japan utilize these for gearbox housing verification.
Laser Scanners leads on scale; Structured Light Scanners leads on momentum.
Application:
Investment intensity varies by where in the vehicle lifecycle 3D imaging generates measurable cost avoidance.
- Quality Control:In-line dimensional verification catches deviation before value-adding processes compound error. United States battery cell manufacturers mandate 100% inspection coverage, driving scanner density per production line.
- Design Validation:Digital twin correlation between CAD models and physical prototypes compresses iteration cycles. German OEM design centers deploy structured light arrays for clay model surface capture.
- Prototyping:Rapid geometry capture accelerates form-factor iteration for interior component development. Tooling shops serving tier-1 suppliers in Japan integrate handheld scanners for first-article inspection.
- Reverse Engineering:Legacy part digitization supports aftermarket reproduction and competitive teardown analysis. Specialist service providers in the United States maintain archives of discontinued component geometries.
Quality Control commands capital deployment; Design Validation expands most quickly.
Technology:
Software stack differentiation increasingly determines hardware selection criteria as perception algorithms commoditize.
- Depth Sensing:Solid-state LiDAR and time-of-flight CMOS sensors generate real-time occupancy data for ADAS architectures. NHTSA mandates for automatic emergency braking accelerate integration into production vehicle sensor suites.
- Computer Vision:Neural network inference on edge processors classifies 3D point clouds into drivable surface and object categories. Tier-1 suppliers in Germany develop proprietary training pipelines to differentiate perception stacks.
- 3D Reconstruction:Multi-view stereo algorithms synthesize complete surface models from sparse sensor inputs. Research institutions in Japan advance volumetric fusion techniques for autonomous navigation mapping.
- Image Processing:Noise reduction and point cloud registration pipelines prepare raw sensor data for downstream algorithms. Silicon photonics foundries in Taiwan supply optical MEMS components that feed these processing chains.
Depth Sensing dominates procurement volume; Computer Vision gains share fastest.
End User:
Buying authority concentrates differently across the automotive supply hierarchy, with divergent technical specifications and commercial terms.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH integrate 3D imaging modules into complete ADAS and quality systems for OEM delivery. These entities control qualification pathways and volume pricing negotiations.
- OEMs:Vehicle manufacturers specify performance thresholds and homologation requirements that constrain supplier design choices. Direct procurement of metrology equipment for manufacturing engineering centers operates outside tier-1 channels.
- Aftermarket Providers:Collision repair networks and refurbishment specialists acquire portable scanning systems for damage assessment. California and Arizona robotaxi fleet operators source perception hardware independently of OEM supply agreements.
- Research Institutions:University laboratories and national research centers advance optical phased array and silicon photonics architectures. German and Japanese automotive research consortia prototype next-generation solid-state LiDAR concepts.
Tier-1 Suppliers anchors commercial volume; Aftermarket Providers shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor concentrates the highest density of 3D imaging deployment for electric vehicle quality control and autonomous system validation. Manufacturing investment flows toward jurisdictions with aligned regulatory mandates and established tier-1 supplier ecosystems.
United States
NHTSA's FMVSS 127 mandate for automatic emergency braking with pedestrian detection by 2029 drives OEM procurement of 1550-nanometer LiDAR systems. Michigan and California automotive clusters host validation facilities where tier-1 suppliers test solid-state sensor arrays against federal performance thresholds.
Germany
UNECE type-approval frameworks for automated emergency braking create guaranteed volumes for certified 3D imaging hardware. Stuttgart and Munich manufacturing belts integrate structured light scanners for battery pack assembly verification under EU regulatory timelines.
Japan
MLIT safety standards for vehicle autonomous systems shape sensor performance specifications for domestic OEM programs. Nagoya and Tokyo metropolitan areas concentrate research consortia prototyping optical phased array LiDAR for 2027 vehicle platforms.
China
MIIT guidelines for intelligent connected vehicles accelerate domestic production of solid-state LiDAR chipsets. Yangtze River Delta fabrication clusters expand silicon photonics capacity to reduce lead times for automotive optical MEMS components.
South Korea
Domestic OEM autonomous vehicle roadmaps drive demand for depth-sensing modules in compact vehicle segments. Seoul Capital Area semiconductor foundries add dedicated optical MEMS lines to supply regional tier-1 integration programs.
Automotive 3D Imaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state architectures and software-defined perception stacks. The supplier base concentrates among tier-1 integrators with captive MEMS fabrication or direct foundry partnerships. Three archetypes dominate: diversified industrial conglomerates with automotive divisions, pure-play sensor specialists with fabless models, and metrology equipment providers pivoting toward in-line production applications. Competitive dynamics center on vertical integration into optical component supply and strategic licensing of perception algorithm IP.
Within the diversified industrial tier, Robert Bosch GmbH and Continental AG exemplify integrated hardware-software stack providers. Sony Group Corporation anchors the image sensor supply position across multiple OEM programs. These three entities represent distinct competitive vectors: captive MEMS fabrication depth, tier-1 system integration authority, and component-scale supply relationships respectively.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Texas Instruments |
| Continental AG |
| Sony Group Corporation |
| Valeo SE |
| STMicroelectronics |
| ZF Friedrichshafen AG |
| Autodesk Inc. |
| Hexagon AB |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ISO 26262 ASIL-D qualified modules and uncertified commercial-grade alternatives manifests in both pricing power and supply chain sourcing strategies across automotive 3D imaging procurement. ASIL-D certified solid-state LiDAR commands substantial premiums due to 18-24 month validation cycles and limited qualified foundry capacity, while commercial-grade depth sensors compete on cost in aftermarket and research applications.
Pricing Analysis
Input-cost pass-through from indium gallium arsenide photodetectors and VCSEL arrays directly shapes module pricing across 1550-nanometer and 905-nanometer architectures respectively. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive-grade modules from industrial-grade units and consumer-grade alternatives. Cost compression in standard-tier time-of-flight modules is intensifying because silicon photonics foundry expansion in Taiwan and South Korea is adding optical MEMS capacity. Aftermarket providers and research institutions exhibit highest price sensitivity, while OEM platform engineering teams prioritize qualification timelines over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Nagoya operate hub-and-spoke patterns that consolidate optical component inventories before tier-1 assembly. Geographic supply concentration centers on Taiwan and South Korea for silicon photonics foundry capacity, Germany for precision optical assembly, and Japan for image sensor fabrication. Raw material dependencies include indium phosphide substrates, gallium arsenide wafers, and specialized optical coatings. Single-source VCSEL foundry vulnerability creates structural risk for multi-projector automotive designs. Distribution runs through tier-1 supplier direct-ship programs and OEM consignment inventory arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA's FMVSS 127 mandate for automatic emergency braking by 2029 compounds regulatory demand across multiple vehicle classes, creating guaranteed procurement volumes that reshape competitive positioning.
For Market Incumbents: Extend captive MEMS fabrication depth to secure optical component supply against fabless entrant cost pressure. Backward integration into silicon photonics foundry partnerships or in-house VCSEL array production reduces single-source dependency. Certification investment in ASPICE process maturity reinforces qualification authority for OEM platform programs. For New Entrants and Emerging Players: FMVSS 127 in the United States opens a window for 1550-nanometer LiDAR specialists to qualify dual-wavelength redundancy architectures before 2029 enforcement deadlines. Target India's PLI scheme automotive manufacturing expansion for affordable 3D vision systems in compact vehicle segments underserved by premium suppliers. Construction and mining equipment retrofit channels offer direct fleet sales without tier-1 qualification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined perception stacks disintermediate hardware-only LiDAR manufacturers in California and Arizona robotaxi procurement. Long-term viability favors tier-1 suppliers with integrated algorithm-hardware stacks or component-scale sensor specialists with captive foundry relationships. Acquisition target archetype: fabless solid-state LiDAR developers with open API architectures and pending automotive qualification. Signal to watch: fleet operator unbundling of perception software from hardware procurement in commercial vehicle segments.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Taiwan and South Korea optical MEMS capacity expansion reduces lead times for solid-state LiDAR chipsets. |
| ASIL-D Certification Investment | ISO 26262 functional safety validation extends development cycles but secures OEM platform integration authority. |
| Software-Defined Perception Stack Development | Neural network inference on edge processors differentiates tier-1 supplier offerings beyond hardware specifications. |
| India Manufacturing Localization | PLI scheme domestic OEM capacity growth creates demand for affordable 3D vision in compact vehicle segments. |
| Thermal-Depth Fusion Module Integration | Combined long-wave infrared and LiDAR architectures enable all-weather object classification for autonomous navigation. |
Methodological Framework
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each automotive manufacturing cluster combined with secondary validation. Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, silicon photonics foundry managers, and automotive research consortium technical leads provided structured interviews. Secondary sources include NHTSA FMVSS filings, UNECE type-approval databases, vehicle production registries, SEC automotive division disclosures, and MIIT intelligent connected vehicle guidelines. Bottom-up scanner deployment counts triangulate against top-down OEM sensor suite content estimates.
Rate-of-change decomposition separates volume growth from value-per-unit evolution across the projection horizon. Segmentation dimensions modeled include product type, application workflow, technology architecture, and end-user procurement authority, supplemented by vehicle class and regional regulatory cluster differentiation. CAGRs derive from segment-level trajectory analysis incorporating NHTSA mandate timelines, UNECE framework adoption curves, and foundry capacity expansion schedules. Industry-specific forecast inputs include solid-state LiDAR sampling schedules for 2027 vehicle platforms and battery manufacturing metrology equipment deployment rates.
Revisions become necessary when NHTSA delays FMVSS 127 enforcement, UNECE diverges from harmonized type-approval timelines, or silicon photonics foundry expansion stalls due to capital allocation shifts. Forecasts reflect documented assumptions regarding regulatory adherence and technology qualification pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision System Market
Imaging
Cooled IR Camera Market
Imaging
Mobile Camera Module Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
SDI Camera Market
Imaging
Handheld Retinal Scanners Market
Imaging
Global Digital Photography Market
Imaging
Video Processing Solutions Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
EUV Mask Inspection System Market
Imaging
Micro Computed Tomography Market
Imaging
Camcorder Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Compact Camera Module Market
Imaging
Video Microscopes Market