
 Null Detector Market | 2026-2036
Null Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Null Detector Market Insights
IEC 61000-4-3 electromagnetic immunity qualification is collapsing the supplier base for high-precision null detection systems. Keysight Technologies leverages its RF instrumentation heritage to dominate aerospace calibration workflows. Fluke Corporation anchors its position through channel density in industrial maintenance sectors. Agilent Technologies competes via R&D intensity in quantum-ready detector architectures.
A null detector measures minute voltage or current differentials between two signal paths with resolution often below one nanovolt, serving as the reference standard for precision bridge measurements and sensor validation. Digital detector architectures now lead product type segmentation due to their software-defined calibration routines and direct IEEE-488 interfacing, while quantum technology represents the fastest-expanding technology tier as cryogenic Josephson junction arrays enable metrological-grade accuracy. Optical technology segments maintain mature margin pools in telecommunications fiber testing, where stabilized laser interferometry commands premium positioning.
FCC Part 15 emissions limits in the United States and EU EMC Directive harmonization under CE marking constrain market access for uncertified instruments, while ISO 17025 laboratory accreditation mandates drive replacement cycles among research institutions. South Korea's MFDS and Germany's KBA both reference IEC standards in their respective electromagnetic compatibility enforcement frameworks for medical devices and automotive electronics. Stakeholders must monitor divergence between national metrology institute traceability requirements as quantum-based primary standards displace traditional thermal voltage references.
Market Dynamics
Quantum metrology is collapsing traditional thermal voltage reference hierarchies as national metrology institutes accelerate Josephson array deployments, forcing incumbent detector architectures toward cryogenic compatibility roadmaps.
Growth Catalysts
- IEC 61000-4-3 harmonization:Aerospace testing laboratories in Germany and the United States are expanding precision null detection procurement to meet electromagnetic immunity qualification mandates for avionics calibration workflows.
- South Korean semiconductor foundries:East Asian electronics manufacturing clusters are driving concentrated demand for nanovolt-resolution bridge systems in wafer-level sensor validation processes.
- EU EMC Directive enforcement:CE marking harmonization under tightening electromagnetic compatibility standards is compelling manufacturers to upgrade validation equipment across medical device and automotive electronics supply chains.
Market Restraints
- Cryogenic infrastructure costs:Quantum-ready Josephson junction arrays require specialized helium-3 cooling systems that multiply total cost of ownership for research institutions.
- East Asian supply concentration:Precision analog-to-digital converter substrates and cryogenic probe assemblies concentrate among Japanese component suppliers, creating geographic vulnerability.
- Thermal voltage reference obsolescence:Traditional Weston cell and electronic thermal standards face displacement without backward compatibility pathways, stranding installed base investments.
Strategic Opportunities
- Telecommunications fiber testing:Optical null detection segments command premium positioning in stabilized laser interferometry applications for submarine cable deployment verification.
- ISO 17025 laboratory accreditation:Mandatory replacement cycles among European and North American research institutions create predictable refresh demand for metrological-grade systems.
- Software-defined calibration routines:Digital detector architectures with direct IEEE-488 interfacing enable remote diagnostic services that unbundle hardware from recurring revenue streams.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in dilution refrigerator operation and superconducting circuit design concentrates among national metrology institutes and select university laboratories.
- Traceability reconfiguration timelines:Divergence between national metrology institute quantum-based primary standards and legacy thermal voltage references is forcing parallel calibration chain maintenance during transition periods.
- Legacy bridge integration complexity:Electromechanical Kelvin-Varley dividers and manual potentiometer systems in industrial maintenance sectors resist digital detector retrofit without workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Null Detector Market |
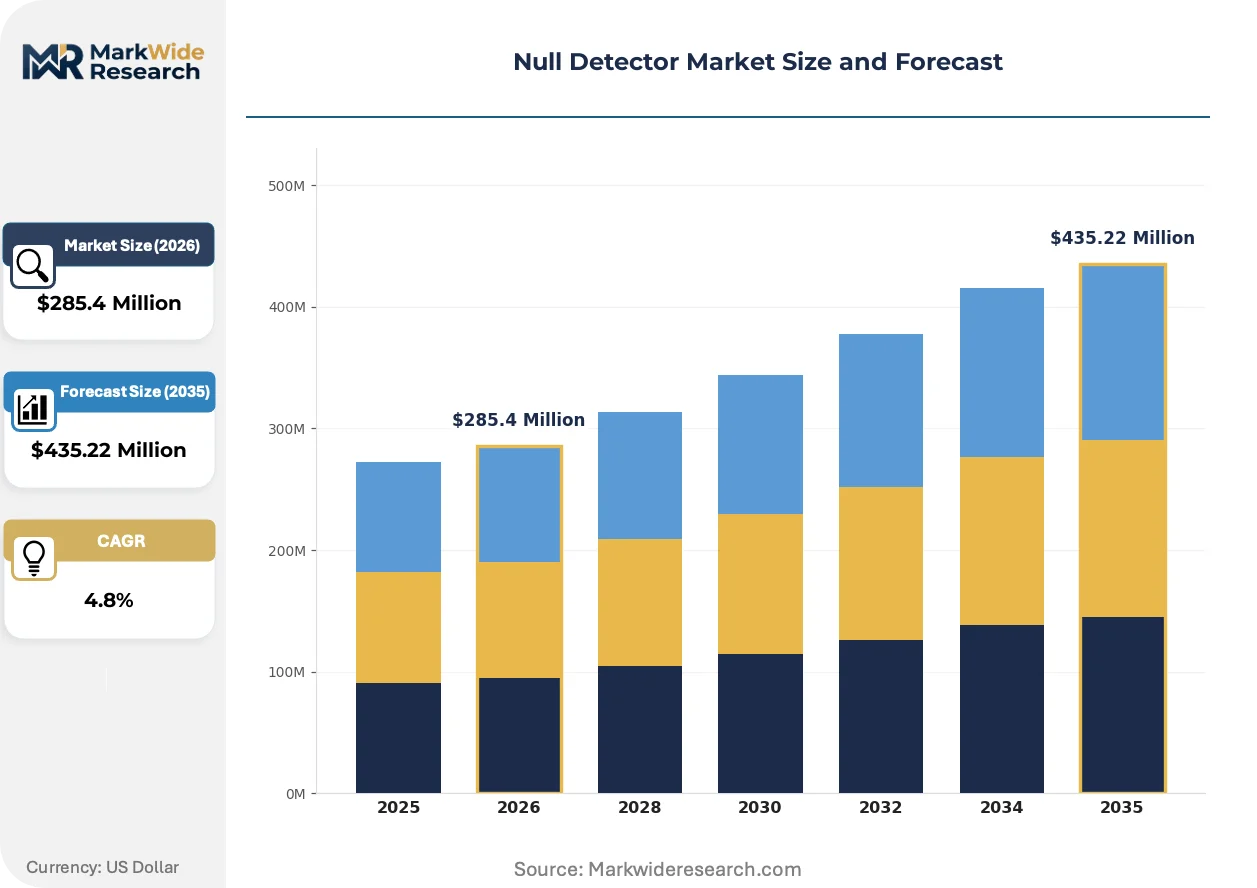
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Detectors, Digital Detectors, Smart Detectors, Miniaturized Detectors Application: Industrial Automation, Telecommunication, Aerospace, Consumer Electronics Technology: RF Technology, Optical Technology, Acoustic Technology, Quantum Technology End User: Manufacturers, Research Institutions, Telecom Companies, Electronics Firms |
| Companies Covered | Agilent Technologies, GMC-I Messtechnik GmbH, Fluke Corporation, TEGAM, Chroma ATE Inc., Keysight Technologies, National Instruments, Ambala Electronic Instruments, Tektronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Null Detector Market Trends and Innovations
Digital architectures are displacing analog electromechanical systems while quantum primary standards reconfigure traceability hierarchies, compressing development cycles for precision instrumentation vendors.
Cryogenic Josephson voltage standard arrays are miniaturizing from room-filling national laboratory installations toward rack-mountable commercial systems. Aerospace calibration providers in the United States and Germany are piloting these compact platforms for on-site avionics verification. The technology is miniaturizing metrological-grade accuracy into field-deployable form factors that bypass centralized laboratory bottlenecks.
EU EMC Directive harmonization under CE marking is tightening electromagnetic compatibility enforcement for medical devices and automotive electronics. Germany's KBA references IEC standards in type approval processes for vehicle electronic subsystems. Japanese precision instrument suppliers are accelerating dual-certification roadmaps to maintain access across European and North American qualification workflows.
Buyers are unbundling after-sales calibration services from hardware procurement through third-party ISO 17025 accredited laboratories. Industrial maintenance sectors in South Korea and Japan are driving this preference shift toward independent verification chains. Semiconductor foundries represent the most visible adopter segment, where fab-level metrology teams reject vendor-captive service contracts in favor of competitive calibration sourcing.
Null Detector Market Segmentation
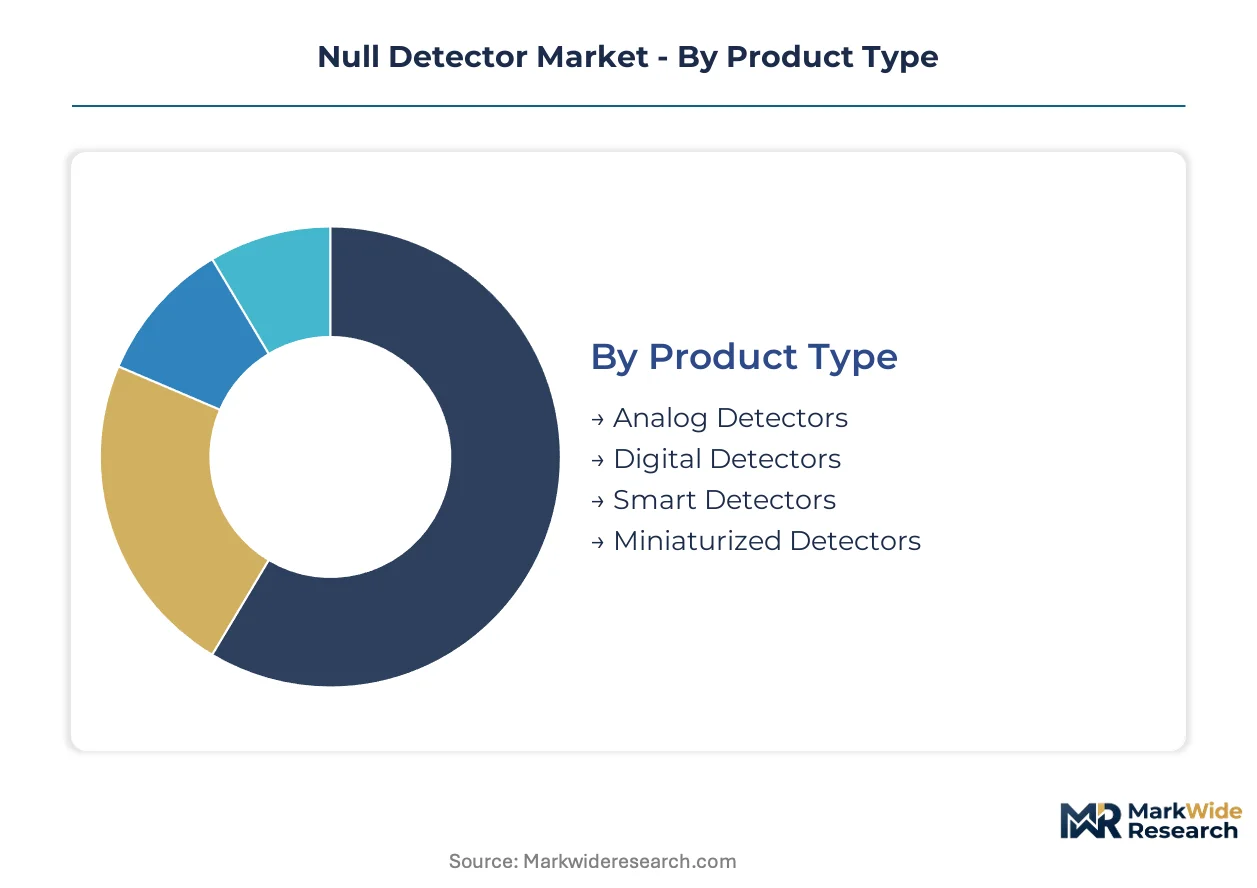
Precision instrumentation markets fragment along capability tiers that separate commodity validation from metrological-grade certification. Null detector procurement patterns diverge sharply between industrial maintenance workflows demanding rugged reliability and semiconductor fabrication requiring nanovolt-resolution bridge systems.
Product Type:
Margin pools concentrate in digital architectures that command premium positioning through software-defined calibration routines and IEEE-488 interfacing capabilities.
- Digital Detectors:Software-defined architectures enable remote diagnostic services and direct instrument bus interfacing. South Korean semiconductor foundries drive concentrated procurement for wafer-level sensor validation requiring programmable gain stages and automated null-seeking algorithms.
- Smart Detectors:Embedded microprocessor units integrate self-calibration routines with edge computing for real-time drift compensation. Aerospace testing laboratories in Germany prioritize these systems for avionics calibration workflows demanding reduced operator intervention.
- Analog Detectors:Electromechanical potentiometer systems retain installed base in legacy industrial maintenance sectors resistant to digital retrofit.
- Miniaturized Detectors:Chip-scale implementations target portable field applications with reduced thermal stability specifications.
Digital detectors hold installed capacity. Smart detectors are rotating up the share rankings.
Application:
Volume concentration follows electronics manufacturing cluster geography, with procurement intensity scaling to electromagnetic compatibility enforcement stringency.
- Industrial Automation:Process control systems deploy null detectors for sensor bridge validation in manufacturing line calibration. Japanese precision instrument suppliers anchor demand through channel density in factory automation retrofit programs.
- Aerospace:Avionics subsystem qualification under FAA and EASA electromagnetic immunity mandates requires precision null detection for antenna calibration and shielding effectiveness verification. German testing laboratories expand procurement to meet IEC 61000-4-3 harmonization deadlines.
- Telecommunication:Fiber optic submarine cable deployments utilize stabilized laser interferometry for insertion loss measurement.
- Consumer Electronics:High-volume production lines prioritize cost-optimized detection for routine quality assurance sampling.
Aerospace holds installed capacity. Telecommunication is rotating up the share rankings.
Technology:
Technology tier maturity curves separate established margin pools from emerging capability investments requiring cryogenic infrastructure.
- Quantum Technology:Cryogenic Josephson junction arrays enable metrological-grade accuracy through quantized voltage reference standards. National metrology institutes accelerate deployment, forcing commercial vendors toward cryogenic compatibility roadmaps despite helium-3 cooling cost multiplication.
- Optical Technology:Stabilized laser interferometry commands premium positioning in telecommunications fiber testing applications. Japanese suppliers maintain mature margin pools through proprietary stabilization algorithms and thermal compensation architectures.
- RF Technology:Broadband detection architectures serve electromagnetic compatibility pre-compliance screening across industrial sectors.
- Acoustic Technology:Ultrasonic null detection retains niche positioning in non-destructive testing workflows for structural integrity verification.
Optical technology holds installed capacity. Quantum technology is rotating up the share rankings.
End User:
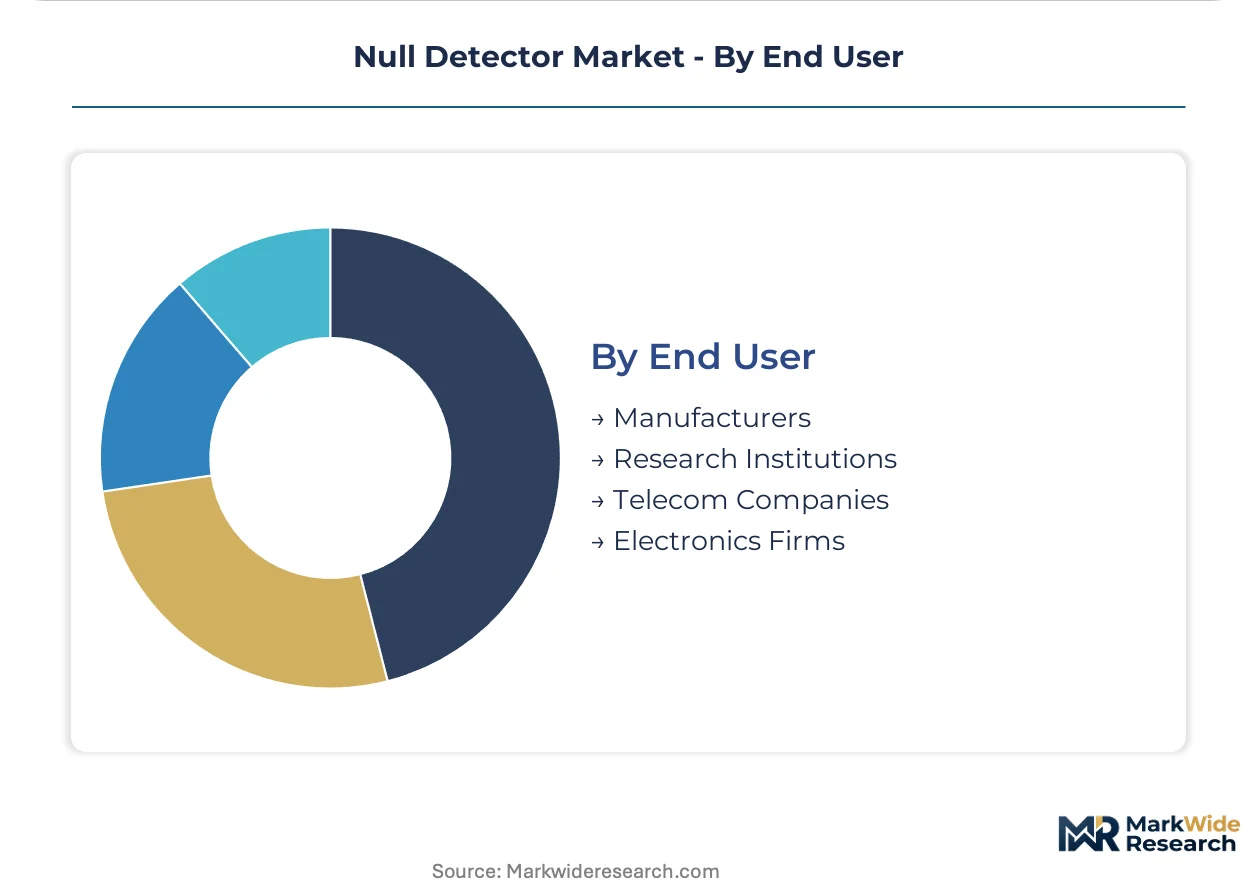
Customer type determines procurement authority structure, with centralized metrology teams diverging from distributed maintenance organizations in specification priorities.
- Research Institutions:ISO 17025 laboratory accreditation mandates drive predictable replacement cycles for metrological-grade systems. National metrology institutes in the United States and Germany prioritize quantum-ready detector architectures for primary standard traceability.
- Electronics Firms:Semiconductor foundries and precision instrument manufacturers demand nanovolt-resolution systems for wafer-level characterization. South Korean fab-level metrology teams reject vendor-captive service contracts in favor of competitive third-party calibration sourcing.
- Telecom Companies:Submarine cable operators and network infrastructure providers specify optical null detection for deployment verification.
- Manufacturers:Industrial maintenance sectors prioritize channel density and rapid spare parts availability over absolute precision specifications.
Research institutions hold installed capacity. Electronics firms are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's precision instrument export dominance, while South Korea's KTX high-speed rail network connects the Seoul Capital Area to Gumi's electronics corridor. These infrastructure assets anchor distinct procurement patterns across the null detector market.
United States
FAA electromagnetic immunity mandates for avionics certification drive procurement from aerospace testing laboratories in California and Texas. FCC Part 15 emissions enforcement compels manufacturers to upgrade validation equipment. Greater Boston's research corridor accelerates quantum-ready detector adoption for national metrology institute traceability.
Germany
KBA type approval processes for vehicle electronic subsystems require precision null detection in automotive testing facilities. EU EMC Directive harmonization under CE marking tightens electromagnetic compatibility standards. Bavaria's precision instrument cluster around Munich expands calibration service capacity for aerospace and medical device suppliers.
South Korea
MFDS electromagnetic compatibility enforcement for medical devices creates compliance-driven replacement cycles. Semiconductor foundries in the Seoul Capital Area demand nanovolt-resolution bridge systems for wafer-level sensor validation. Gumi's electronics manufacturing corridor concentrates procurement from fab-level metrology teams rejecting vendor-captive service contracts.
Japan
METI industrial standardization programs accelerate dual-certification roadmaps for European and North American market access. Chubu region's precision instrument suppliers maintain mature margin pools in optical null detection. Nagoya's manufacturing belt drives factory automation retrofit programs for industrial maintenance sectors.
China
MIIT electromagnetic compatibility standards under GB certification frameworks expand domestic testing laboratory capacity. Yangtze River Delta electronics manufacturing clusters absorb cost-optimized detection systems for consumer electronics quality assurance. Shanghai's metrology institutes pilot cryogenic Josephson array deployments for primary standard traceability.
Null Detector Market Competitive Landscape
Listed leaders compete with private specialists across instrumentation heritage and channel density dimensions. The vendor base concentrates among RF instrumentation conglomerates, precision measurement multinationals, and regional calibration service providers. Three archetypes dominate: aerospace calibration specialists leveraging electromagnetic immunity qualification mandates, industrial maintenance channel anchors, and quantum metrology pioneers. M&A activity targets cryogenic engineering capabilities, while strategic partnerships secure ISO 17025 accreditation footprints.
Among Germany-based precision measurement specialists, GMC-I Messtechnik GmbH exemplifies the industrial maintenance channel anchor archetype. Keysight Technologies and Fluke Corporation represent contrasting heritage models within the listed leader tier. Agilent Technologies occupies a position bridging quantum-ready research instrumentation with commercial calibration workflows. These three companies collectively illustrate the competitive tension between RF instrumentation conglomerates and precision measurement specialists.
| Leading Market Players |
|---|
| Agilent Technologies |
| GMC-I Messtechnik GmbH |
| Fluke Corporation |
| TEGAM |
| Chroma ATE Inc. |
| Keysight Technologies |
| National Instruments |
| Ambala Electronic Instruments |
| Tektronix |
| Others |
Pricing and Supply Chain Analysis
IEC 61000-4-3 electromagnetic immunity qualification gates both supplier certification and price tiering simultaneously, forcing uncertified vendors toward economy positioning while accredited laboratories capture premium positioning through traceability guarantees.
Pricing Analysis
Volume-discount tiering separates metrological-grade systems from industrial maintenance units. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 accreditation status and cryogenic compatibility. Cost compression in the economy tier is intensifying because semiconductor foundries reject vendor-captive service contracts. Electronics manufacturing clusters exhibit highest price sensitivity; national metrology institutes show least.
Supply Chain Analysis
Inbound logistics costs through the Port of Hamburg and Busan container terminals concentrate precision analog-to-digital converter substrates among Japanese component suppliers. Cryogenic probe assemblies draw from specialized helium-3 cooling system providers in Germany and the United States. Single-source vulnerability in Josephson junction array fabrication threatens commercial vendor roadmaps. Distribution runs through ISO 17025 accredited calibration laboratories and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in dilution refrigerator operation concentrates among national metrology institutes, creating acquisition premiums for cryogenic engineering capabilities that commercial vendors cannot replicate organically.
For Market Incumbents: Compound channel density in aerospace calibration workflows by securing FAA and EASA electromagnetic immunity qualification mandates before quantum-ready architectures displace thermal voltage references. Deepen backward integration into cryogenic probe assembly production to offset Japanese supplier concentration risk. For New Entrants and Emerging Players: Remote diagnostic services for digital detector architectures represent an under-served layer where incumbents bundle hardware with captive calibration contracts. Target South Korean semiconductor foundries with unbundled third-party verification offerings. Lead with software-defined calibration routines that enable subscription revenue models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across quantum-ready detector architectures as helium-3 cooling infrastructure multiplies total cost of ownership. Long-term viability favors vendors with national metrology institute partnerships for traceability certification. Acquisition targets should demonstrate cryogenic engineering talent pipelines. Monitor divergence timelines between quantum-based primary standards and legacy thermal voltage references as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Engineering Acquisition | Josephson junction array deployment requires dilution refrigerator expertise concentrated at NIST and PTB. |
| ISO 17025 Accreditation Expansion | European laboratory certification creates predictable replacement cycles among research institutions. |
| Software-Defined Calibration Launch | IEEE-488 interfacing enables remote diagnostics that unbundle hardware from recurring revenue. |
| Dual-Certification Roadmap | CE marking and FCC Part 15 compliance maintains access across German KBA and US FAA workflows. |
| Helium-3 Cooling Partnership | Specialized infrastructure providers anchor quantum-ready detector total cost of ownership. |
Research Methodology
A spread of perspectives from precision instrument procurement managers, metrology laboratory directors, semiconductor fab engineers, and aerospace calibration technicians converged on the working assumptions. Primary interviews combined with secondary validation from IEC standard documentation, FCC Part 15 enforcement records, and EU EMC Directive implementation reports. Customs data from German precision instrument exports and South Korean semiconductor equipment imports anchored trade flow analysis. Bottom-up procurement modeling triangulated against top-down market sizing.
Segmentation dimensions modeled include product architecture, application vertical, technology tier, and end-user procurement authority structure across the projection horizon. CAGRs derived from replacement cycle analysis of ISO 17025 accredited laboratories and quantum metrology deployment timelines at national metrology institutes. Aerospace electromagnetic immunity qualification mandates and semiconductor wafer-level sensor validation intensity shaped regional adoption patterns.
Forecasts assume regulatory continuity in FCC Part 15, EU EMC Directive, and IEC 61000-4-3 harmonization frameworks; material policy shifts would require re-modeling. Cryogenic infrastructure cost trajectories and Josephson array commercialization timelines present specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Walk Through Metal Detector Market